
 Real Time Location System Market | 2026-2036
Real Time Location System Market Size, Share, and Industry Trends Forecast 2026-2036
Real Time Location System Market Intelligence
System integrator and value-added reseller channels is reconfiguring how RTLS solutions reach end users, with specialized partners now bundling hardware, software, and installation services into turnkey offerings. Zebra Technologies Corporation dominates enterprise mobility and tracking ecosystems through its extensive partner network and integrated printer-reader portfolios. Siemens leverages its building automation and healthcare IT footprint to embed RTLS into smart infrastructure deployments. Impinj, Inc. specializes in RAIN RFID chip and reader technology, sustaining its position through semiconductor-level innovation and cloud connectivity platforms.
A real time location system comprises hardware tags, anchors, and software algorithms that calculate spatial coordinates through radio frequency signals, typically achieving sub-meter precision depending on the underlying protocol and environmental conditions. Ultra-Wideband technology leads precision-oriented applications in manufacturing and healthcare due to its centimeter-level accuracy and resistance to multipath interference, while Bluetooth Low Energy occupies the cost-sensitive asset tracking tier across retail and warehouse environments. RFID remains the volume workhorse for inventory management, though its growth rate lags behind newer protocols. Cloud-based connectivity architectures are expanding fastest as enterprises prioritize centralized fleet and personnel oversight across distributed facilities.
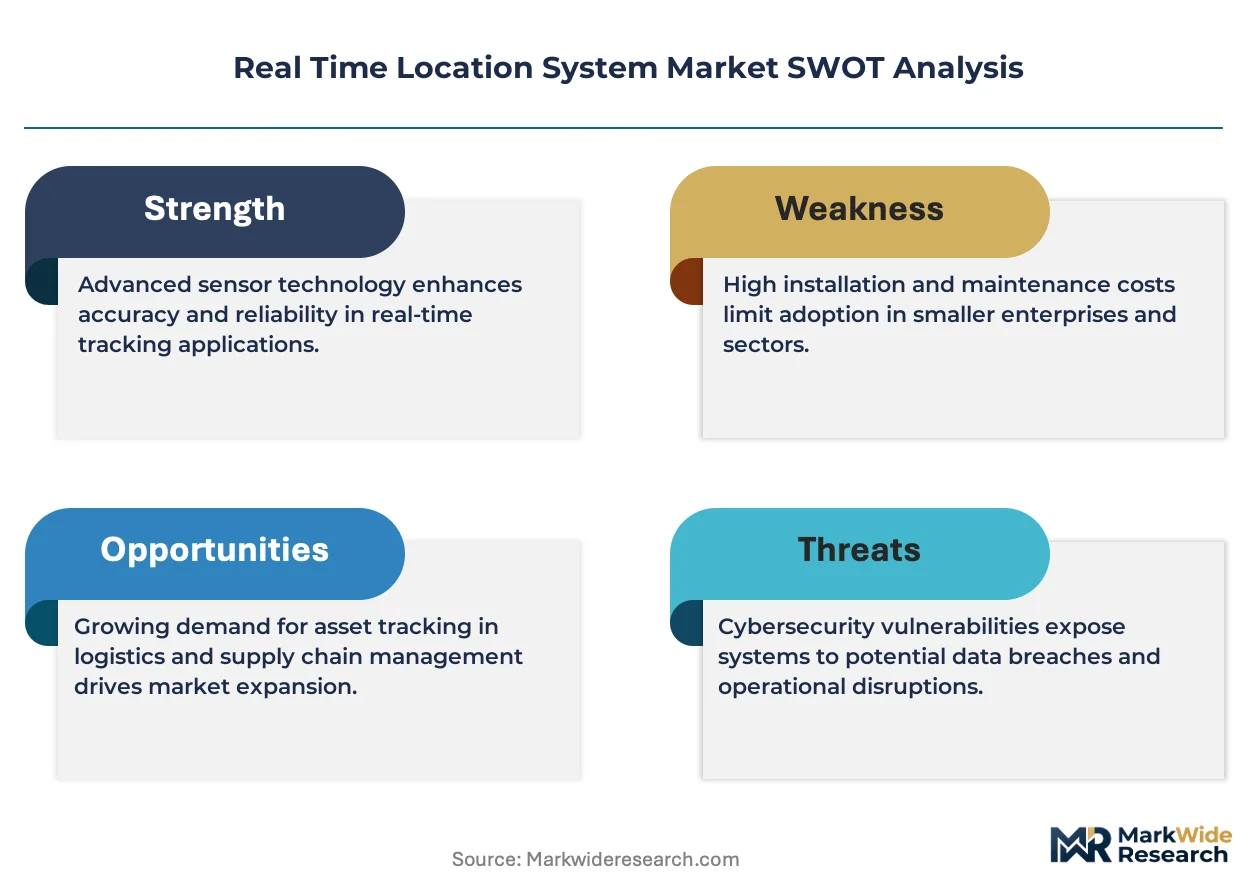
FDA unique device identification rules and the EU Medical Device Regulation are mandating item-level traceability in healthcare supply chains, directly expanding RTLS procurement budgets in hospitals and device manufacturers. FCC spectrum allocations for Ultra-Wideband in the United States, combined with CE marking requirements under the EU Radio Equipment Directive, shape which protocols vendors certify for regional deployment. Stakeholders must monitor evolving interoperability standards between proprietary and open-location frameworks to avoid stranded infrastructure investments as consolidation pressures intensify across the vendor landscape.
Market Dynamics
Ultra-Wideband chip shortages and FCC spectrum allocation delays are compressing deployment timelines for precision-oriented RTLS installations in US manufacturing and healthcare facilities.
Growth Catalysts
- FDA Unique Device Identification:Mandates for item-level traceability in medical device supply chains are expanding hospital procurement budgets for automated tracking infrastructure.
- German Industrial Logistics:Automotive component manufacturers are deploying centimeter-accurate positioning to synchronize just-in-sequence assembly lines with supplier deliveries.
- BLE AoA Technology:Angle-of-arrival algorithms are cutting hardware costs for mid-precision asset tracking, opening warehouse deployments previously reserved for passive RFID.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundries fabricate over 90% of UWB radio chips, creating single-point vulnerability for vendors dependent on sub-meter precision protocols.
- Multipath Interference:Metal-rich factory floors and hospital environments degrade Bluetooth signal reliability, forcing redundant anchor installations that inflate project costs.
- EU Radio Equipment Directive:CE marking timelines for new frequency bands add 8-14 months to product launch cycles, disadvantaging European vendors against faster-certifying competitors.
Strategic Opportunities
- Japanese Smart Hospital Construction:METI-funded infrastructure renewal programs are embedding RTLS into new-build medical facilities across Osaka and Tokyo metropolitan clusters.
- 5G Positioning Convergence:Integration of cellular network timing with local anchor arrays is enabling wide-area personnel tracking without dedicated infrastructure overlays.
- Outcome-Based Maintenance Contracts:Equipment manufacturers are bundling location analytics with service agreements, converting capital sales into recurring revenue streams.
Industry Challenges
- RF Engineering Talent Scarcity:Deployment of UWB and BLE mesh networks requires specialized expertise in propagation modeling that exceeds standard IT integration skill sets.
- Legacy WMS Integration:Warehouse management systems built for barcode scanning lack native APIs for real-time coordinate streams, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Time Location System Market |
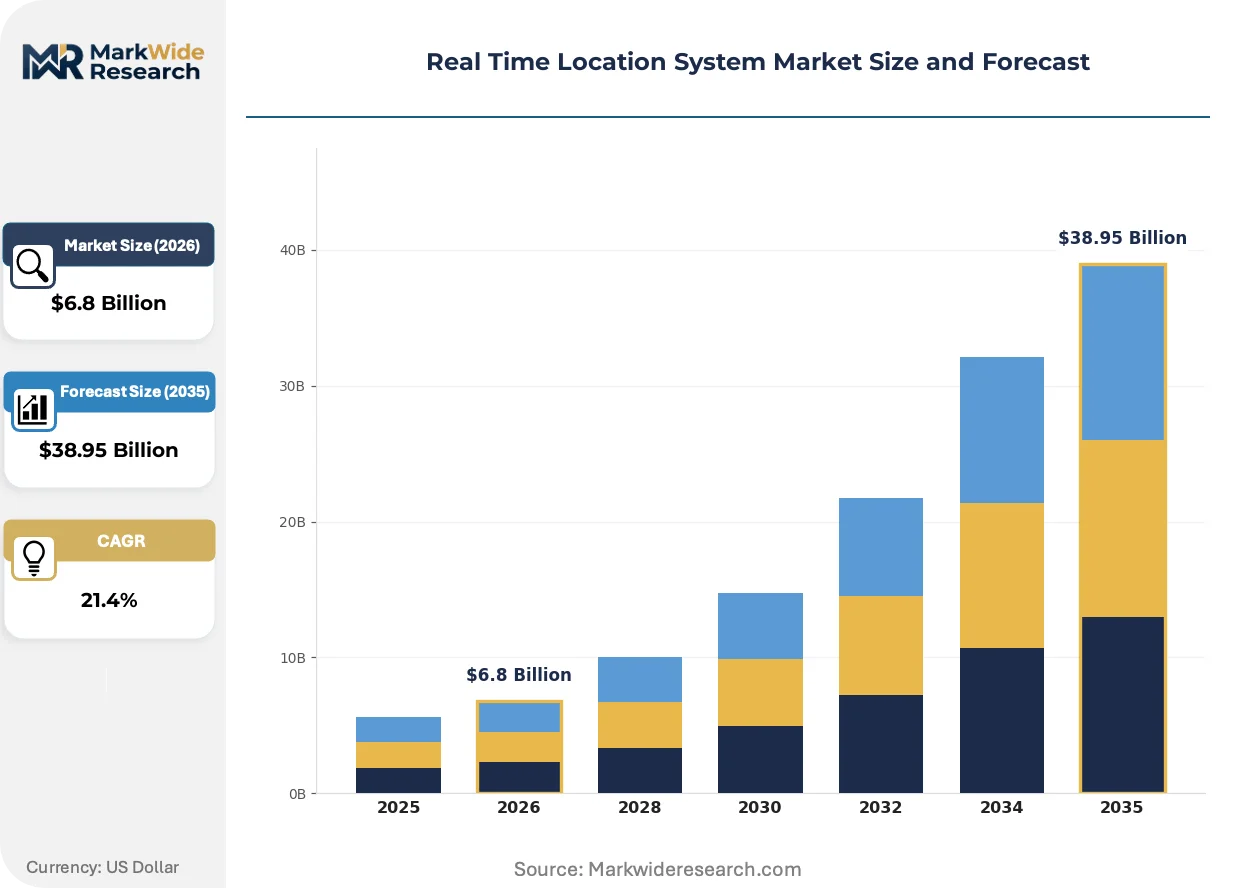
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Bluetooth, Ultra-Wideband, GPS End User: Healthcare Facilities, Retail Stores, Warehouses, Educational Institutions Application: Asset Tracking, Personnel Tracking, Inventory Management, Fleet Management Connectivity: Wireless, Wired, Hybrid, Cloud-Based |
| Companies Covered | Siemens, TeleTracking Technologies, Inc., Zebra Technologies Corporation, AiRISTA Flow, Inc., Ubisense Ltd., Securitas AB, CenTrak, Inc., Sonitor Technologies, Impinj, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Time Location System Market Strategic Shifts & Innovations
Protocol convergence and cloud-native architectures are dissolving the traditional boundary between indoor positioning and enterprise resource planning systems.
Ultra-Wideband is migrating from high-value manufacturing to mid-market warehouse operations as semiconductor volumes drive module costs below fifteen dollars. Third-party logistics providers in the US Midwest are piloting UWB for yard management, replacing GPS-denied trailer tracking with 30-centimeter accuracy. This migration from premium to mainstream segments is compressing margins for incumbent BLE specialists while opening new volume tiers for chip vendors.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated personnel monitoring systems. Healthcare RTLS deployments must now document decision logic for patient flow optimization tools, adding compliance overhead to software development cycles. German hospital networks are responding by segregating location data processing within EU-sovereign cloud regions.
System integrators are unbundling hardware procurement from software licensing, allowing end users to mix anchor vendors within single deployments. This purchasing flexibility is fragmenting vendor lock-in patterns that previously tied hospitals to single-source ecosystems. The shift is most pronounced in US acute care facilities where capital committees demand interoperability guarantees before approving infrastructure investments.
Real Time Location System Market Segmentation
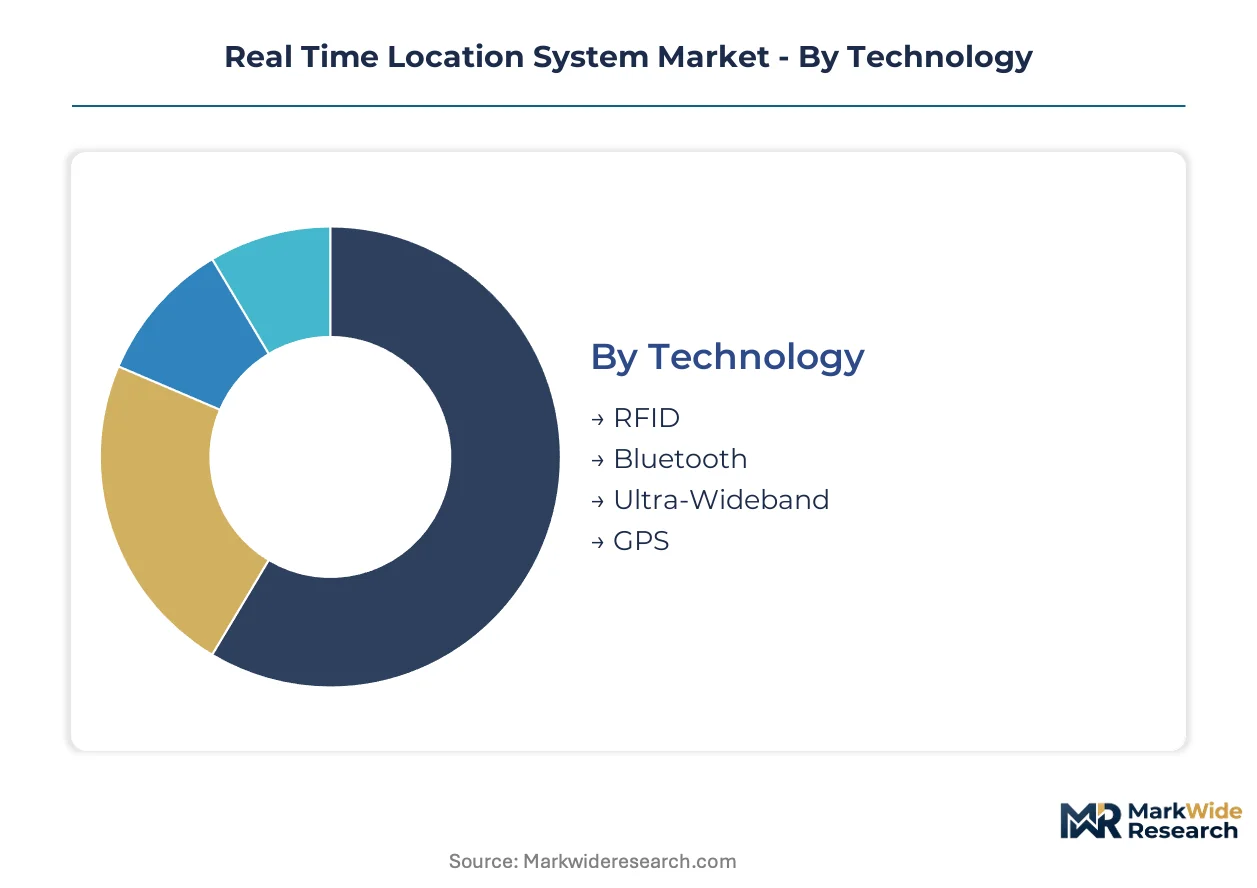
RTLS procurement cycles vary dramatically across deployment contexts. Healthcare infrastructure refresh programs run 7-10 years while warehouse technology upgrades turn over every 3-4 years. Understanding these rhythm differences shapes vendor sales forecasting and inventory planning.
Technology:
Replacement cycles stretch from 18 months for disposable RFID tags to 8 years for fixed UWB anchor infrastructure, creating fundamentally different revenue recognition patterns across protocol types.
- Ultra-Wideband:Centimeter-level precision through nanosecond pulse transmission enables collision-resistant positioning in metal-dense manufacturing floors. German automotive assembly plants specify UWB for supplier sequencing coordination, though Taiwan-based chip fabrication bottlenecks constrain deployment velocity.
- Bluetooth:Angle-of-arrival algorithms now deliver sub-meter accuracy at one-third the hardware cost of UWB alternatives. US third-party logistics providers in Indiana and Ohio are retrofitting warehouses with BLE mesh networks for pallet-level tracking.
- RFID:Passive backscatter technology dominates high-volume item-level identification in retail apparel and pharmaceutical packaging.
- GPS:Satellite-dependent positioning serves outdoor fleet and yard management where indoor precision protocols lack coverage.
RFID dominates installed base by tag volume. Ultra-Wideband is where expansion concentrates for precision-demanding applications.
End User:
Capital allocation authority and procurement sophistication create distinct selling motions across customer categories.
- Healthcare Facilities:FDA unique device identification mandates and Joint Commission accreditation requirements drive tracking infrastructure into US acute care networks. Hospital capital committees now demand interoperability guarantees before approving anchor deployments.
- Warehouses:E-commerce fulfillment velocity pressures are accelerating replacement of barcode scanning with real-time coordinate streams. Distribution centers near Chicago and Memphis are piloting hybrid UWB-BLE architectures for simultaneous pallet and forklift tracking.
- Retail Stores:Loss prevention and customer journey analytics applications concentrate in specialty apparel and electronics chains.
- Educational Institutions:Campus safety and equipment checkout systems drive adoption in large university research facilities.
Healthcare Facilities command the highest per-site deployment values. Warehouses represent the steepest expansion trajectory as e-commerce fulfillment requirements intensify.
Application:
Functional use cases determine hardware density, software licensing models, and integration complexity with downstream enterprise systems.
- Asset Tracking:Medical device location in hospital networks reduces equipment rental expenditures and improves utilization rates. RTLS-enabled asset registers in Cleveland Clinic and Mayo Clinic facilities demonstrate measurable capital efficiency gains.
- Personnel Tracking:Staff duress alerting and workflow optimization in emergency departments require sub-second latency and privacy-compliant data handling. The EU AI Act's risk classification framework now mandates algorithmic transparency for automated personnel monitoring systems.
- Inventory Management:Real-time stock location eliminates cycle counting labor in high-SKU distribution environments.
- Fleet Management:Yard truck and trailer positioning in GPS-denied environments enables dock door scheduling optimization.
Asset Tracking dominates current deployment value. Personnel Tracking is climbing the fastest as staff safety regulations tighten across jurisdictions.
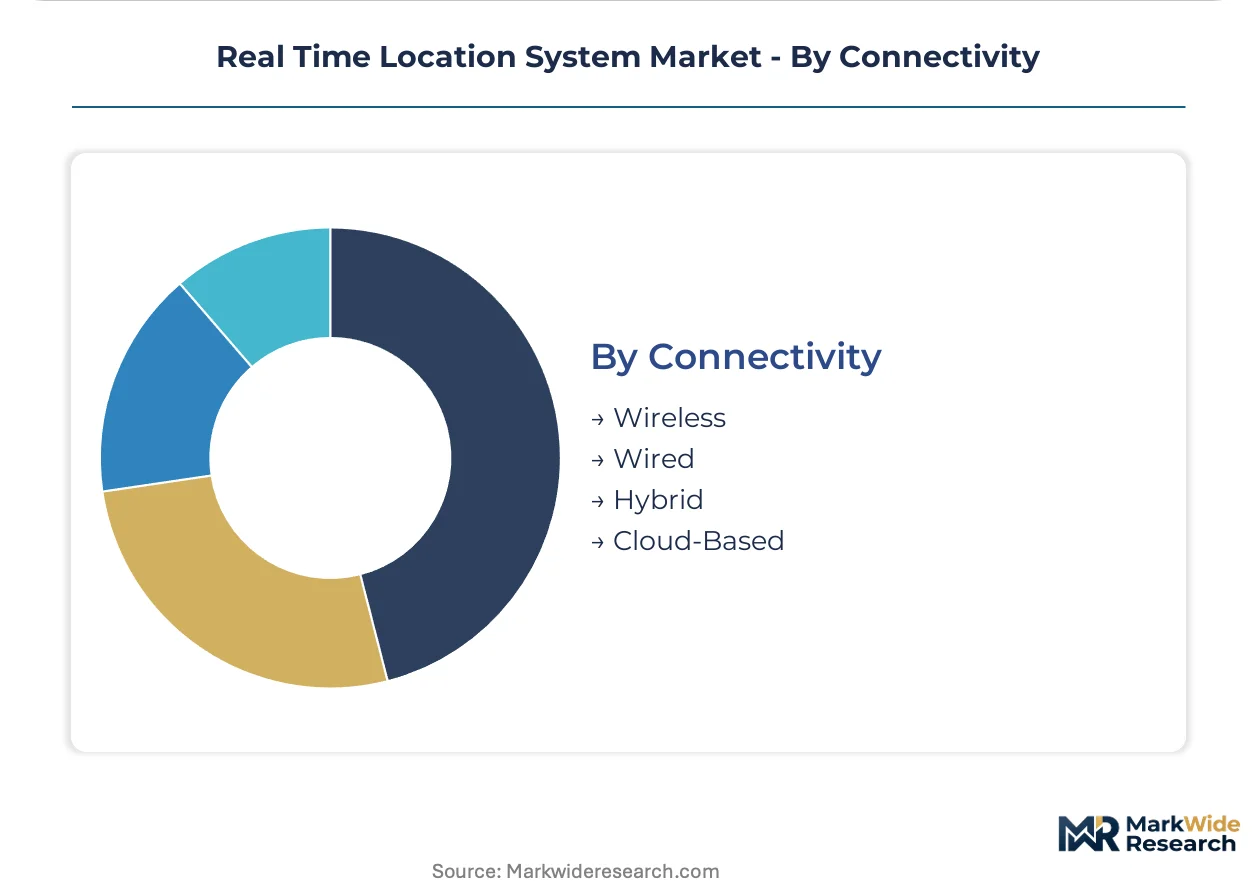
Connectivity:
Architecture choices determine scalability, cybersecurity exposure, and total cost of ownership across multi-site deployments.
- Cloud-Based:Centralized data aggregation and analytics platforms enable fleet-wide visibility without on-premise server infrastructure. German hospital networks are responding to EU AI Act requirements by segregating location data processing within EU-sovereign cloud regions.
- Hybrid:Edge computing for real-time positioning decisions combined with cloud synchronization for historical analytics balances latency and scalability. Manufacturing facilities in Japan's Osaka-Tokyo corridor favor this architecture for production line synchronization.
- Wireless:Self-healing mesh networks reduce cabling costs in retrofit deployments.
- Wired:Power-over-Ethernet anchor installations serve new construction with predictable infrastructure budgets.
Hybrid architectures dominate greenfield deployments. Cloud-Based connectivity is gaining share fastest as distributed facility oversight requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA unique device identification mandates and EU Medical Device Regulation traceability requirements are accelerating procurement cycles across hospital networks in multiple jurisdictions. Infrastructure renewal programs in Germany and Japan are embedding RTLS into new-build medical facilities. FCC spectrum allocations for Ultra-Wideband continue shaping protocol availability in North American deployments.
United States
Acute care networks in Cleveland and Rochester are expanding RTLS infrastructure for medical device tracking and patient flow optimization. FDA unique device identification rules mandate item-level traceability, directly inflating hospital capital budgets for automated tracking systems. Distribution centers near Chicago and Memphis pilot hybrid UWB-BLE architectures for simultaneous pallet and forklift coordination.
Germany
Automotive component manufacturers in Stuttgart and Wolfsburg deploy centimeter-accurate positioning to synchronize just-in-sequence assembly lines with supplier deliveries. EU Medical Device Regulation and EU AI Act algorithmic transparency requirements are adding compliance overhead to healthcare RTLS software development. Hospital networks in Berlin and Munich are segregating location data processing within EU-sovereign cloud regions.
Japan
METI-funded smart hospital construction programs are embedding RTLS into new-build medical facilities across Osaka and Tokyo metropolitan clusters. PMDA medical device traceability guidelines align with international UDI frameworks, expanding procurement budgets for tracking infrastructure. Manufacturing facilities in the Osaka-Tokyo corridor favor hybrid edge-cloud architectures for production line synchronization.
United Kingdom
NHS infrastructure modernization programs are driving RTLS adoption for equipment utilization and patient pathway optimization in London and Manchester teaching hospitals. MHRA alignment with EU MDR traceability standards sustains procurement momentum despite regulatory divergence. Third-party logistics providers in the Midlands are retrofitting warehouses with BLE mesh networks for pallet-level tracking.
China
NMPA medical device unique identification pilots are expanding traceability requirements for domestic manufacturers and importers. MIIT industrial internet initiatives promote localization of positioning chip supply chains to reduce dependence on Taiwan-based UWB fabrication. Smart factory deployments in Shenzhen and Shanghai are integrating RTLS into digital twin platforms for production monitoring.
Real Time Location System Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform providers while specialist component vendors occupy defensible niches in semiconductor and software layers. Enterprise mobility conglomerates and building automation multinationals anchor the top tier through extensive partner networks and bundled service offerings. Three archetypes dominate: full-stack platform vendors, semiconductor specialists, and system integrators with vertical expertise. Competitive moves center on unbundling hardware procurement from software licensing and forming outcome-based maintenance partnerships that convert capital sales into recurring revenue.
Among the named players in this market, Siemens represents the building automation-anchored archetype leveraging smart infrastructure footprints, while Zebra Technologies Corporation exemplifies the enterprise mobility platform model with integrated printer-reader portfolios. Impinj, Inc. occupies the semiconductor specialist position focused on RAIN RFID chip and reader technology.
| Leading Market Players |
|---|
| Siemens |
| TeleTracking Technologies, Inc. |
| Zebra Technologies Corporation |
| AiRISTA Flow, Inc. |
| Ubisense Ltd. |
| Securitas AB |
| CenTrak, Inc. |
| Sonitor Technologies |
| Impinj, Inc. |
| Others |
Cost & Logistics Intelligence
Taiwan-based foundry concentration for Ultra-Wideband radio chips creates simultaneous pricing tier compression and supply vulnerability that reshapes procurement strategies across precision-oriented RTLS deployments. This single-source dependency forces buyers into longer-term contracting while vendors absorb margin pressure from semiconductor bottlenecks.
Pricing Analysis
Certification level under FCC Part 15 and CE marking timelines creates the primary spread between premium UWB installations and cost-optimized BLE alternatives. Three-tier pricing structure across FDA-grade healthcare systems, industrial automation deployments, and retail asset tracking segments reflects compliance overhead differentials. Cost compression in mid-precision BLE tiers is intensifying because Angle-of-Arrival hardware commoditization erodes anchor margins. Warehouse operators exhibit highest price sensitivity, while German automotive manufacturers accept premium positioning for centimeter-accurate supplier sequencing.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic sourcing decisions for anchor hardware and tag assembly. Taiwan, South Korea, and Germany anchor semiconductor fabrication and precision engineering capabilities. UWB radio chips, BLE system-on-modules, and passive RFID inlays constitute critical component dependencies. Single-source vulnerability in Taiwan-based foundries threatens deployment timelines for sub-meter precision protocols. Distribution runs through system integrator channels that bundle hardware procurement with installation services and software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTLS market sits in early-cycle expansion as FDA unique device identification mandates and EU Medical Device Regulation traceability requirements penetrate hospital capital budgets for the first time.
For Market Incumbents: Insulate installed base relationships through outcome-based maintenance contracts that convert capital sales into recurring revenue streams. Deepen backward integration into cloud-native software layers to defend against unbundling trends that fragment vendor lock-in patterns. Counter emerging BLE specialists by embedding proprietary algorithms into hybrid edge-cloud architectures favored in Japanese manufacturing corridors. For New Entrants and Emerging Players: Build out vertical expertise in EU-sovereign cloud deployment to capture German hospital network procurement requiring GDPR-compliant data segregation. Target US third-party logistics providers in the Midwest with hybrid UWB-BLE architectures for simultaneous pallet and forklift tracking. Lead with interoperability guarantees that satisfy capital committee demands in acute care networks. For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors semiconductor specialists with RAIN RFID chip capabilities and cloud connectivity platforms. Long-term viability hinges on positioning upstream of system integrator channel capture. Signal to watch: FCC spectrum allocation velocity for Ultra-Wideband as indicator of precision-protocol deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Maintenance Contracts | Equipment manufacturers bundle location analytics with service agreements, converting capital sales into recurring revenue. |
| EU-Sovereign Cloud Deployment | German hospital networks segregate location data processing within EU regions to satisfy EU AI Act algorithmic transparency mandates. |
| Hybrid UWB-BLE Architecture Development | Distribution centers pilot simultaneous pallet and forklift tracking, replacing single-protocol infrastructure with flexible positioning stacks. |
| Semiconductor Volume Scaling | UWB module costs dropping below fifteen dollars enable migration from premium manufacturing to mid-market warehouse operations. |
| Interoperability Certification Investment | System integrators unbundle hardware procurement, allowing end users to mix anchor vendors and fragmenting vendor lock-in patterns. |
Research Approach
Operator-level perspectives from hospital biomedical engineers, warehouse operations directors, system integrator deployment leads, and automotive plant logistics managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, FCC equipment authorization databases, EU MDR technical documentation, and hospital procurement contract disclosures. Bottom-up protocol adoption modeling and top-down infrastructure spending analysis provided triangulation across technology and end-use dimensions.
Scenario-bracketing around semiconductor supply disruptions, regulatory certification delays, and hospital capital cycle timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include precision protocol type, end-use vertical, connectivity architecture, and geographic regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield penetration curves, with specific inputs from e-commerce fulfillment velocity pressures and automotive just-in-sequence assembly requirements.
Stress conditions across Taiwan foundry output volatility, FCC spectrum allocation timelines, and EU AI Act compliance overhead were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about protocol cost curves and hospital infrastructure refresh cadences. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Refrigeration Monitoring Market
Sensors
Mobile Laser Scanning Market
Sensors
Conveyor Monitoring Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Vibration Monitoring Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Transport Monitoring System Market
Sensors
Eye Tracking Market
Sensors
Asset Tags Market
Sensors
Europe Lidar Market
Sensors
Lidar in Mapping Market
Sensors
Voice Sounders Market
Sensors
Beacon Technology Market
Sensors
Asset Tracking Market
Sensors
Asia-Pacific Remote Sensing Technology Market