
 Asia-Pacific Irrigation Machinery Market | 2026-2036
Asia-Pacific Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Irrigation Machinery Market Outlook
Modular kit configurations that bundle drip lines, filtration units, and pressure regulators into scalable field packages is expanding procurement flexibility for smallholder cooperatives. Jain Irrigation Systems Ltd leverages its polymer compounding capabilities to sustain margin control across the drip tape value chain. Netafim Ltd anchors its position through precision emitter technology that dominates high-value horticulture segments in Australia and Japan. Lindsay Corporation competes in the mechanized pivot segment with manufacturing scale that extends across China's northern plains.
Asia-Pacific irrigation machinery encompasses mechanized systems designed to distribute water to crops through pressurized or gravity-fed networks, typically operating at flow rates between 0.5 and 30 liters per hour depending on emitter specifications and crop water requirements. These systems serve the primary commercial purpose of optimizing water application efficiency, reducing labor dependency, and improving yield consistency across diverse climatic zones from India's monsoon-dependent regions to Australia's arid interior. Drip irrigation leads product type value generation due to its penetration in water-stressed zones and compatibility with fertigation protocols, while smart irrigation technology represents the fastest-expanding segment as sensor-based soil moisture monitoring displaces timer-based scheduling in premium horticulture. Sprinkler systems occupy a mature position in broad-acre grain production where center-pivot and lateral-move configurations deliver economies of scale across flat topography.
India's BIS water-efficiency standards, Australia's Water Efficiency Labelling and Standards (WELS) scheme, and China's Ministry of Ecology and Environment (MEE) groundwater extraction controls collectively shape product certification requirements and market access conditions across the region. BIS compliance mandates filter performance thresholds and emitter uniformity coefficients that raise engineering barriers for unqualified suppliers. Australia's WELS ratings influence public procurement decisions for irrigation infrastructure tied to Murray-Darling Basin sustainability commitments. Stakeholders must monitor evolving groundwater licensing regimes and subsidy qualification criteria as governments recalibrate agricultural water policy.
Market Dynamics
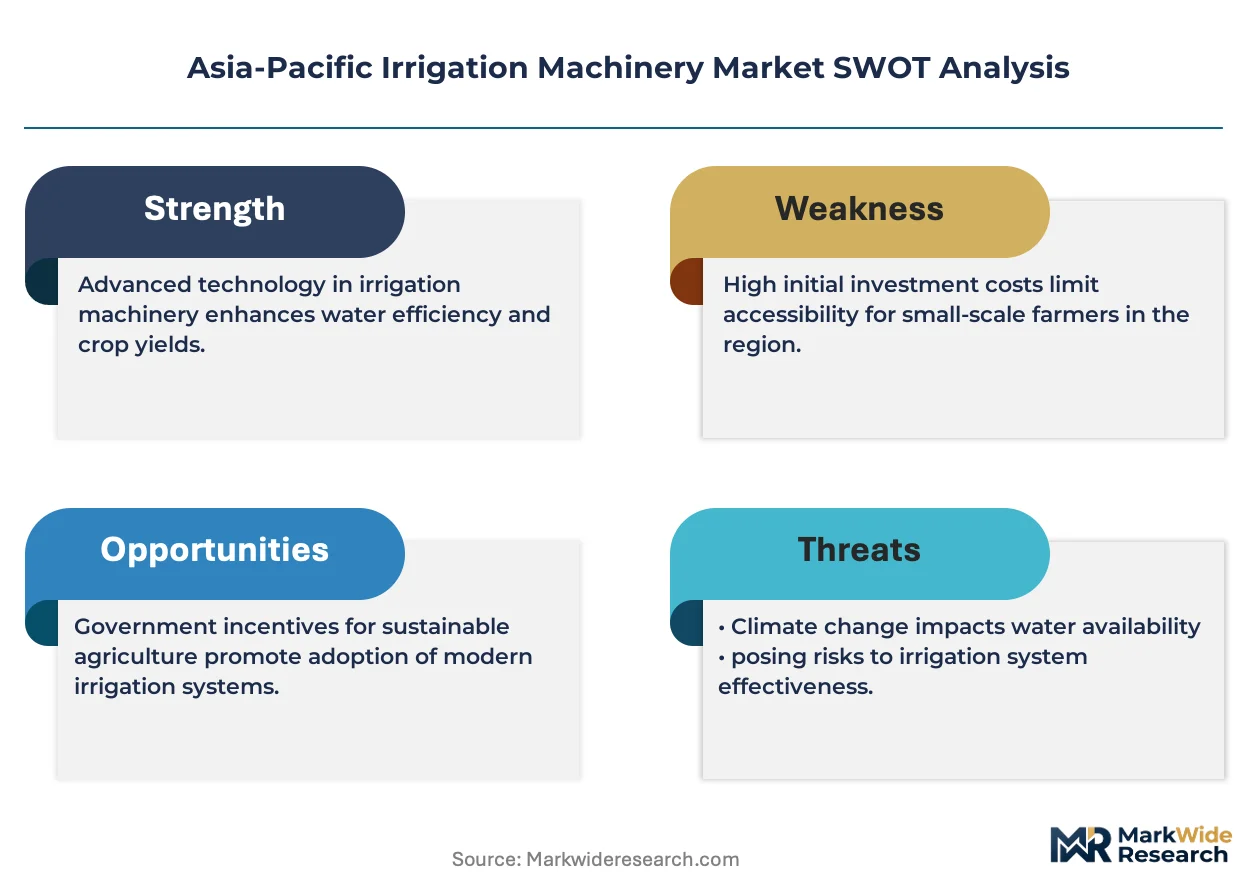
Groundwater depletion across India's Maharashtra and Gujarat is forcing rapid infrastructure replacement cycles, compressing payback-period expectations for precision irrigation hardware and accelerating farmer migration from flood to pressurized systems.
Growth Catalysts
- India's BIS water-efficiency certification:Tightened emitter uniformity coefficients and filter performance thresholds are disqualifying substandard equipment, creating pull for compliant drip and sprinkler infrastructure.
- Australian horticulture mechanization:Almond and table grape estates are scaling automated irrigation across the Murray-Darling Basin, driven by WELS-linked procurement mandates and basin sustainability commitments.
- Sensor-based soil moisture monitoring:Smart irrigation controllers are displacing timer-based scheduling in Japan's protected agriculture, enabling variable-rate water application tied to real-time crop demand.
Market Restraints
- Polymer resin cost volatility:Drip tape and lateral manufacturing depend on polyethylene and polypropylene feedstocks, exposing margin structures to petrochemical price swings.
- China's MEE groundwater extraction controls:Licensing restrictions in northern plains provinces are capping new irrigation expansion, constraining center-pivot and lateral-move system deployment.
- Technical limitation in uneven terrain:Mechanized pivot systems require flat topography, excluding substantial acreage in India's Deccan Plateau and Southeast Asia's upland cultivation zones.
Strategic Opportunities
- Underpenetrated smallholder cooperatives:Modular kit configurations bundling drip lines, filtration, and pressure regulators are unlocking procurement flexibility for India's fragmented landholding structure.
- Fertigation convergence:Integration of soluble fertilizer injection with drip infrastructure is expanding value capture in Vietnam's intensive vegetable production and Thailand's fruit orchards.
- Australia's WELS procurement linkage:Public infrastructure tenders tied to water-efficiency ratings are creating preferential market access for certified equipment suppliers.
Industry Challenges
- Certification timeline compression:India's BIS testing protocols for emitter durability and filtration efficiency are extending product approval cycles, delaying commercialization of upgraded designs.
- Integration complexity with legacy flood systems:Farmers transitioning from gravity-fed surface irrigation face reconfiguration of field topography, water sourcing, and labor allocation.
- Technical skill gaps in system diagnostics:Pressure regulation troubleshooting and clogging prevention require training beyond traditional agricultural extension services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Irrigation Machinery Market |
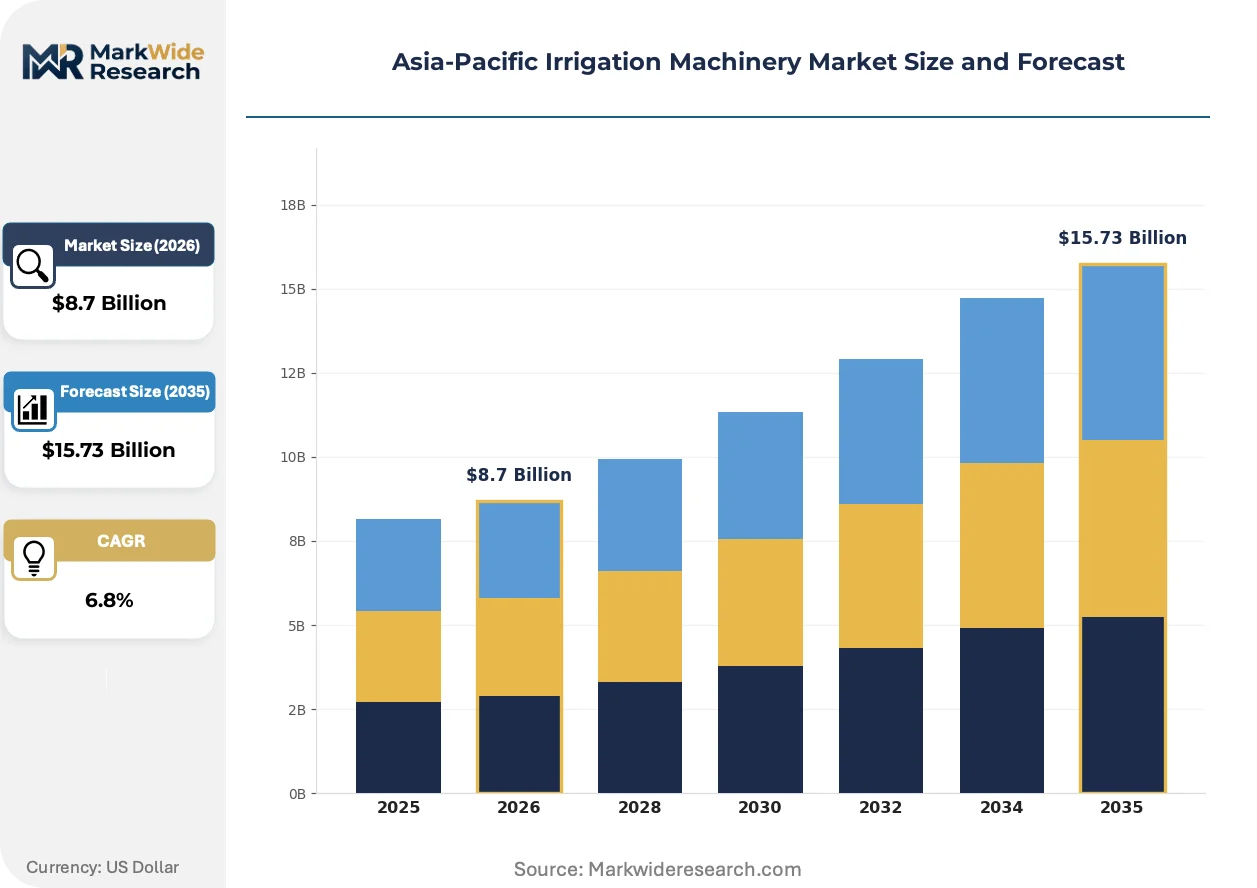
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Application: Agricultural, Industrial, Residential, Golf Courses Technology: Automation, Conventional, Smart Irrigation, Pressure Regulating End User: Farmers, Landscaping Companies, Government Agencies, Horticulturists |
| Companies Covered | Kothari Agritech Private Limited, Rain Bird Corporation, Jain Irrigation Systems Ltd, Rivulis Irrigation Ltd, Netafim Ltd, Harvel Agua India Private Limited, Valmont Industries, Lindsay Corporation, Mahindra & Mahindra, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Irrigation Machinery Market Strategic Shifts
Electrification of irrigation control systems is compressing the gap between precision agriculture hardware and digital farm management platforms, rewiring how water application decisions are made across the region's diverse climatic zones.
Solar-powered pumping and variable-frequency drive technology is electrifying field-level water pressure management. Australian broad-acre operators and Indian horticulturists are deploying photovoltaic arrays to replace diesel-powered pumping sets. This shift is compressing operating cost structures and enabling off-grid irrigation expansion into areas with unreliable grid connectivity.
China's MEE groundwater extraction licensing regime is tightening enforcement of extraction quotas across northern plains provinces. Industrial consequence includes mandatory metering and telemetry installation for agricultural bore wells. Large-scale grain operations in Hebei and Shandong are responding by retrofitting existing center-pivot systems with flow-monitoring hardware to maintain pumping permits.
Cooperative procurement consortia are aggregating smallholder demand into volume-scale equipment tenders. India's farmer producer organizations in Maharashtra and Gujarat are displacing individual retail purchases with collective bidding for drip infrastructure packages. This behavioral shift is most visible in water-stressed districts where subsidy qualification requires minimum acreage thresholds that single smallholders cannot meet independently.
Asia-Pacific Irrigation Machinery Market Segmentation
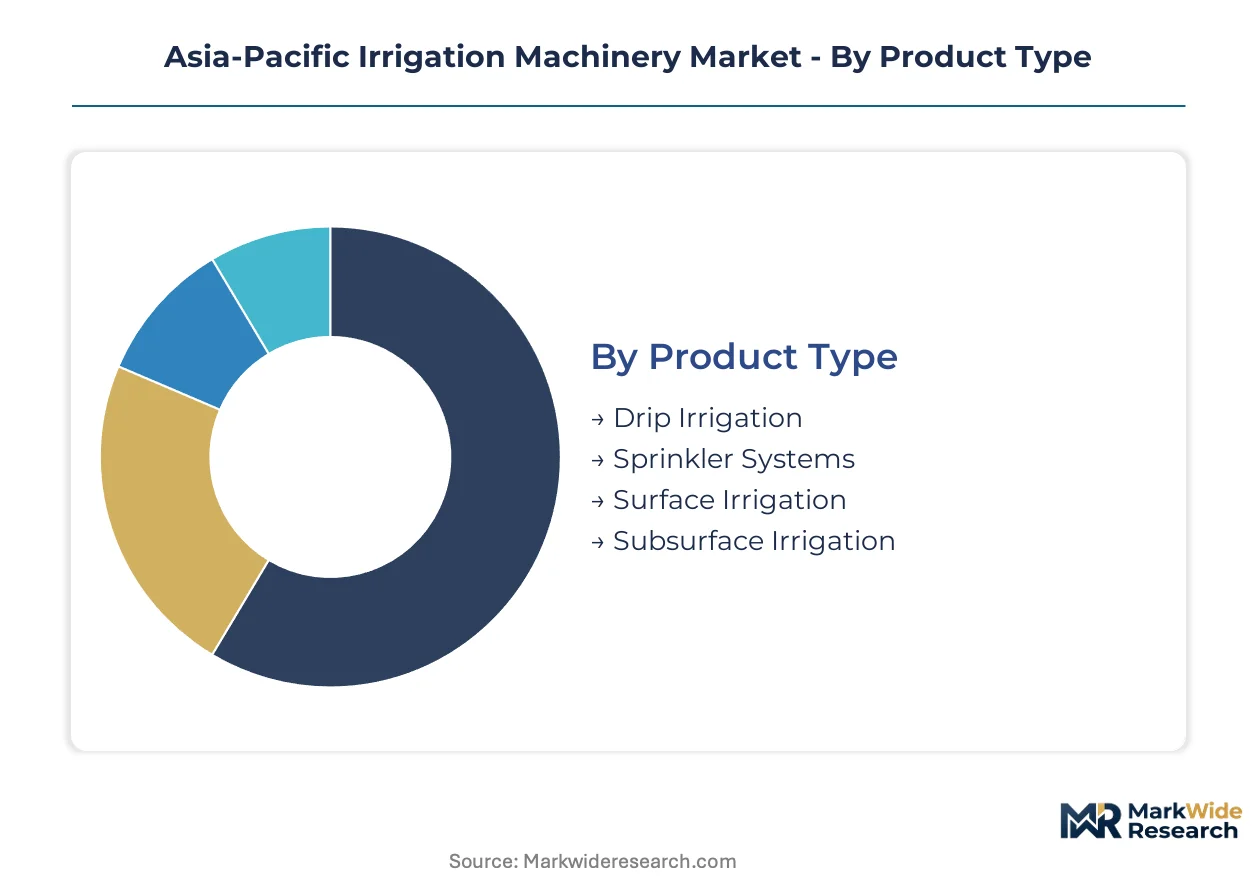
Water-stressed geographies across Asia-Pacific drive divergent equipment selection, with pressure-compensating emitters dominating premium horticulture while gravity-fed surface systems persist in subsidy-dependent smallholder contexts. Segment boundaries blur where fertigation convergence and smart controller retrofitting upgrade legacy infrastructure.
Product Type:
Emitter hydraulics and pressure management specifications differentiate equipment performance across the region's variable topography and water quality conditions.
- Drip Irrigation:Pressure-compensating emitters and labyrinth-flow path designs deliver precise water application at 0.5–4 liters per hour, with demand concentrating in India's Maharashtra and Gujarat where groundwater depletion mandates efficiency gains. BIS water-efficiency certification requirements are disqualifying non-compliant tape and tubing suppliers.
- Sprinkler Systems:Center-pivot and lateral-move configurations operate at 6–30 liters per hour across broad-acre grain production, with Australian Murray-Darling Basin operators scaling mechanized infrastructure under WELS-linked procurement mandates. Flat topography requirements exclude substantial Deccan Plateau acreage.
- Surface Irrigation:Gravity-fed flood and furrow systems persist where electricity access remains unreliable and capital constraints block pressurized system adoption.
- Subsurface Irrigation:Buried drip laterals at 20–40 centimeter depth reduce evaporative losses in Australia's arid interior and China's northern plains.
Mature deployment sits with Surface Irrigation. Newer deployment is concentrated in Drip Irrigation.
Application:
Water pricing structures and crop value density determine capital recovery timelines across end-use contexts.
- Agricultural:Field crops and intensive vegetable production absorb the majority of system volume, with India's farmer producer organizations aggregating smallholder demand into collective tenders for drip infrastructure packages.
- Industrial:Dust suppression and process cooling at mining and manufacturing facilities require high-volume, low-precision sprinkler coverage.
- Residential:Lawn and garden automation in Australia's urban periphery and Japan's suburban developments favors smartphone-integrated timer controllers.
- Golf Courses:Turf quality mandates drive investment in weather-based irrigation management systems across Japan, South Korea, and Australia's resort corridors.
Volume concentration rests with Agricultural. Margin expansion is steepest in Golf Courses.
Technology:
Control system architecture separates timer-based scheduling from sensor-driven variable-rate application.
- Automation:Programmable valve sequencing and remote monitoring reduce labor dependency across large-scale operations in China's northern plains and Australian broad-acre estates.
- Conventional:Manual valve operation and fixed-schedule timers dominate smallholder contexts where technical skill gaps and capital constraints block upgrade pathways.
- Smart Irrigation:Soil moisture sensors, evapotranspiration algorithms, and cloud-connected controllers enable real-time water application adjustments, expanding most quickly in Japan's protected agriculture and Australia's high-value horticulture.
- Pressure Regulating:Hydraulically or electrically actuated pressure sustaining and reducing valves maintain uniform emitter performance across elevation changes and fluctuating supply conditions.
Installed base tilts toward Conventional. Upgrade cycles are accelerating in Smart Irrigation.
End User:
Procurement scale and subsidy access qualifications fragment customer structure across the region.
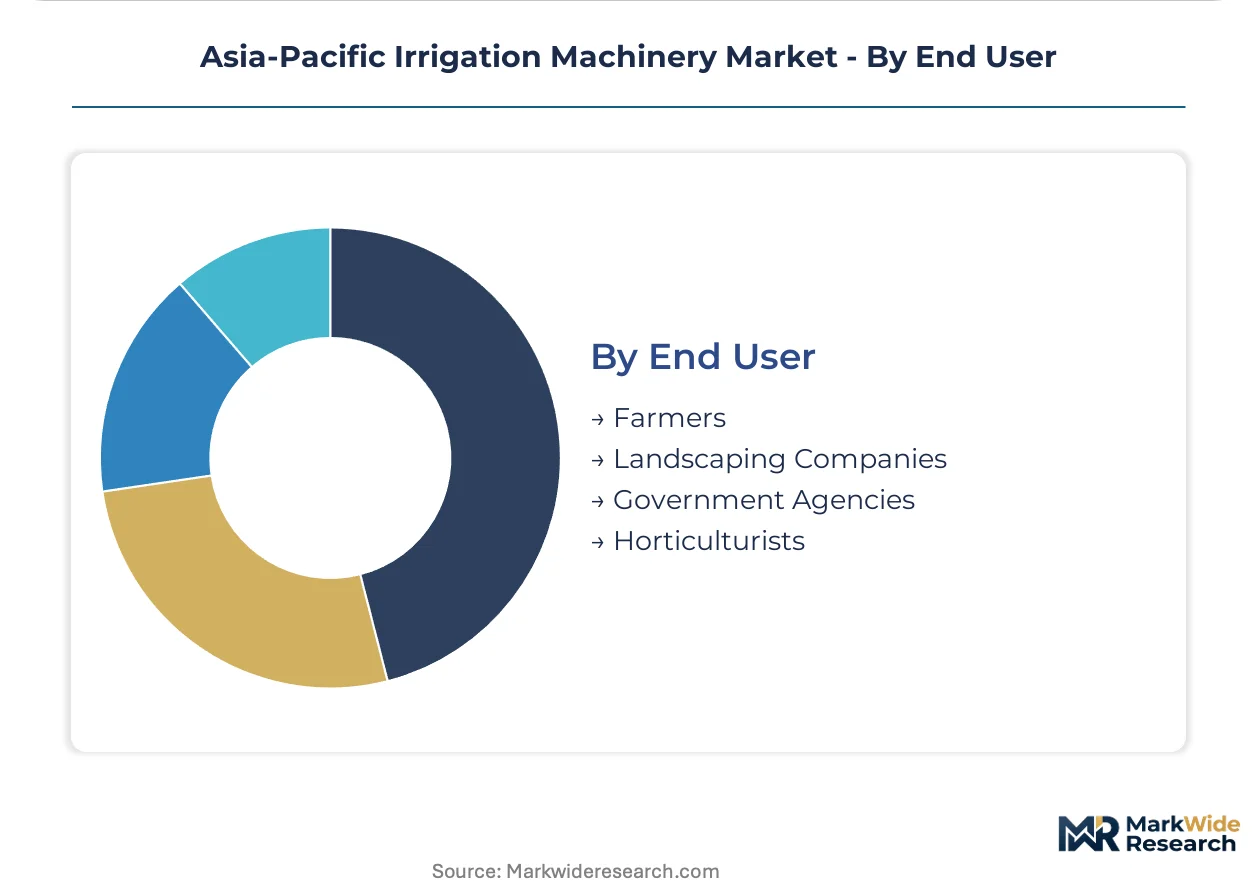
- Farmers:Individual smallholders and cooperative members in India's water-stressed districts drive drip system volume, with Maharashtra and Gujarat farmer producer organizations displacing retail purchases through collective bidding.
- Landscaping Companies:Commercial grounds maintenance contractors in Australian cities and Japanese urban centers specify modular controller systems for municipal and corporate clients.
- Government Agencies:Public irrigation infrastructure tenders tied to Australia's WELS ratings and India's subsidy schemes create preferential access for certified equipment suppliers.
- Horticulturists:Almond and table grape estate operators across Australia's Murray-Darling Basin deploy automated fertigation-integrated systems under basin sustainability commitments.
Procurement volume aggregates with Farmers. Specification sophistication concentrates with Horticulturists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pradhan Mantri Krishi Sinchayee Yojana subsidy corridors concentrate drip infrastructure deployment in designated agricultural export zones across Maharashtra and Gujarat.
India
Maharashtra's sugarcane belt and Gujarat's cotton districts drive pressurized system replacement cycles as aquifer levels decline. BIS water-efficiency certification mandates filter performance thresholds that disqualify non-compliant emitter suppliers. Farmer producer organizations in Nashik and Surat aggregate smallholder demand into collective procurement tenders exceeding individual acreage subsidy minimums.
China
Hebei and Shandong grain operations retrofit center-pivot systems with flow-monitoring hardware to maintain MEE groundwater extraction permits. Northern plains provinces face mandatory telemetry installation for agricultural bore wells under tightening licensing enforcement. Large-scale wheat and corn producers around Shijiazhuang deploy variable-frequency drive pumps to reduce energy intensity per hectare.
Australia
Murray-Darling Basin almond and table grape estates scale automated fertigation under WELS-linked procurement mandates. South Australian horticulturists deploy solar-powered pumping arrays to replace diesel sets across Riverland irrigation districts. Basin sustainability commitments require water-efficiency ratings for public infrastructure tenders, filtering equipment supplier qualification.
Japan
Chubu region protected agriculture operators integrate soil moisture sensors with cloud-connected controllers for variable-rate water application. METI efficiency standards accelerate displacement of timer-based scheduling in greenhouse vegetable production. Nagoya-area horticulturists specify pressure-compensating emitters for precision irrigation in high-value strawberry and tomato cultivation.
Vietnam
Mekong Delta intensive vegetable producers adopt soluble fertilizer injection systems bundled with drip infrastructure. Central government irrigation modernization programs channel equipment subsidies toward cooperatives in An Giang and Dong Thap provinces. Rice-to-vegetable transition zones around Can Tho deploy modular filtration packages for surface water quality management.
Asia-Pacific Irrigation Machinery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment categories, creating tiered competitive dynamics shaped by polymer compounding depth and emitter engineering capability. Market structure tilts toward consolidation in drip tape manufacturing where backward integration into resin compounding sustains margin control, while mechanized pivot assembly remains fragmented across regional fabricators. Three archetypes dominate: polymer-integrated drip system manufacturers, precision emitter technology specialists, and scale-driven mechanized irrigation fabricators. Capacity expansion in pressure-compensating emitter production and geographic licensing partnerships represent the dominant competitive moves.
Among polymer-integrated manufacturers, Jain Irrigation Systems Ltd exemplifies backward control over resin formulation and tape extrusion. Netafim Ltd occupies a position representing precision emitter engineering for high-value horticulture segments. Lindsay Corporation anchors the mechanized pivot archetype with manufacturing scale extending across China's northern plains. These three companies illustrate the capability segmentation separating compound-integrated drip suppliers from standalone equipment assemblers.
| Leading Market Players |
|---|
| Kothari Agritech Private Limited |
| Rain Bird Corporation |
| Jain Irrigation Systems Ltd |
| Rivulis Irrigation Ltd |
| Netafim Ltd |
| Harvel Agua India Private Limited |
| Valmont Industries |
| Lindsay Corporation |
| Mahindra & Mahindra |
| Others |
Value Chain & Pricing Dynamics
Polymer compounding specialists concentrated in Gujarat's petrochemical corridor command wage premiums that compress labor-cost differentials between premium emitter manufacturers and economy-tier assemblers. This workforce concentration tightens pricing-tier spreads as BIS certification mandates raise engineering barriers across all quality levels.
Pricing Analysis
Lead-time premiums separate urgent procurement from scheduled orders, with spot inventory commanding discounts against six-week delivery windows for custom emitter configurations. Pricing stratifies across BIS-certified premium tiers, standard compliance-grade equipment, and non-certified economy imports, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies as Indian farmer producer organizations aggregate demand into volume tenders. Smallholder cooperatives exhibit highest price sensitivity; Australian Murray-Darling Basin horticulturists show lowest sensitivity due to WELS-linked procurement mandates.
Supply Chain Analysis
Regional distribution centers in Mumbai, Singapore, and Sydney anchor hub-and-spoke patterns serving fragmented agricultural procurement across the Asia-Pacific. Manufacturing concentrates in India, China, and Israel, with polymer resin compounding and precision emitter molding as critical inputs. Supply chain risk centers on single-source vulnerability for pressure-compensating emitter technology held by specialized Israeli and Indian manufacturers. Distribution runs through agricultural equipment dealers, cooperative procurement consortia, and direct OEM contracts with large-scale estate operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure-compensating emitter production capacity constraints prop pricing power for qualified suppliers as BIS certification timelines extend approval cycles and compress available supply.
For Market Incumbents: Acquire precision molding capabilities in Maharashtra's industrial zones to secure captive supply of labyrinth-flow path components. Consolidate distribution control through exclusive dealer arrangements in Gujarat's cotton districts, countering emerging Chinese entrants with subsidized export financing. Expand backward integration into polymer compounding to defend margin structures against resin price volatility. For New Entrants and Emerging Players: Begin with modular kit configurations targeting India's farmer producer organizations in water-stressed districts where subsidy thresholds favor collective procurement. Penetrate Vietnam's Mekong Delta vegetable cooperatives through fertigation-integrated bundles, leveraging lower certification barriers than BIS-regulated Indian markets. Pursue licensing partnerships with established emitter technology specialists rather than greenfield R&D investment. For Investors and Strategic Acquirers: Re-rating potential sits with polymer-integrated drip manufacturers given BIS compliance barriers and consolidation pressure on standalone assemblers. Long-term viability favors compound-integrated specialists with captive resin formulation over equipment-only vendors exposed to feedstock volatility. Monitor BIS certification approval velocity as inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Jain Irrigation Systems Ltd sustains margin control through captive resin formulation across drip tape value chain. |
| Precision Emitter Technology Licensing | Netafim Ltd anchors high-value horticulture positioning through proprietary pressure-compensating designs in Australia and Japan. |
| Cooperative Procurement Consortium Formation | Farmer producer organizations in Maharashtra aggregate smallholder demand into volume-scale tenders exceeding individual subsidy minimums. |
| Solar-Powered Pumping Array Deployment | Australian broad-acre operators replace diesel sets with photovoltaic arrays, compressing operating cost structures across Riverland districts. |
| Flow-Monitoring Hardware Retrofit | Hebei grain producers install telemetry to maintain MEE groundwater extraction permits under tightening licensing enforcement. |
Study Parameters
Document review covered customs trade data, BIS certification registries, and MEE licensing disclosures, complemented by interviews with drip system plant managers, agricultural cooperative procurement leads, polymer compounding technical directors, and irrigation district engineers. Secondary validation drew from Australian Bureau of Agricultural and Resource Economics reports, India Central Ground Water Board aquifer assessments, and China Ministry of Water Resources irrigation statistics. Bottom-up equipment shipment tracking and top-down agricultural water policy analysis were triangulated against farmer investment survey panels.
Historical shipment patterns were cross-referenced against panel input from equipment distributors and subsidy program administrators across the analysis window. Segmentation modeling incorporated product type, application intensity, technology tier, and end-user procurement scale dimensions. CAGRs were derived from volume trajectory analysis calibrated to groundwater depletion rates and subsidy allocation trends. Industry-specific inputs included BIS certification timeline data and WELS rating migration patterns.
Underlying measurement precision varies by segment; drip irrigation equipment carries tighter precision than surface irrigation due to formal registration requirements, while smart controller adoption rates reflect higher uncertainty given rapid technology turnover. Forecasts reflect documented assumptions regarding subsidy continuity, regulatory enforcement intensity, and polymer feedstock price bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market