
 India Agricultural Irrigation Machinery Market | 2026-2036
India Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
India Agricultural Irrigation Machinery Market Foresight
The Pradhan Mantri Krishi Sinchayee Yojana is consolidating procurement standards across state tender processes. Jain Irrigation Systems Ltd. leverages its polymer extrusion capabilities to dominate micro-irrigation component supply. Mahindra EPC Irrigation Limited anchors its position through captive foundry operations for metal sprinkler heads. Netafim Ltd differentiates via precision emitter technology leadership in subsurface drip lines.
India agricultural irrigation machinery encompasses mechanical and electromechanical systems engineered to deliver controlled water application across agronomic landscapes, typically operating at pressures between 0.5 and 4.0 bar for drip systems and 2.0 to 6.0 bar for sprinkler networks. These systems integrate filtration units, distribution mains, lateral tubing, and emission devices to optimize crop water use efficiency and yield stability. Drip irrigation commands the dominant product category due to its suitability for water-stressed regions and horticultural intensification, while solar-powered systems within the technology dimension represent the fastest-expanding segment as rural electrification gaps persist. Smart irrigation platforms are capturing margin concentration through sensor-based automation, though conventional systems still sustain volume leadership among smallholder crop farmers with limited capital access.
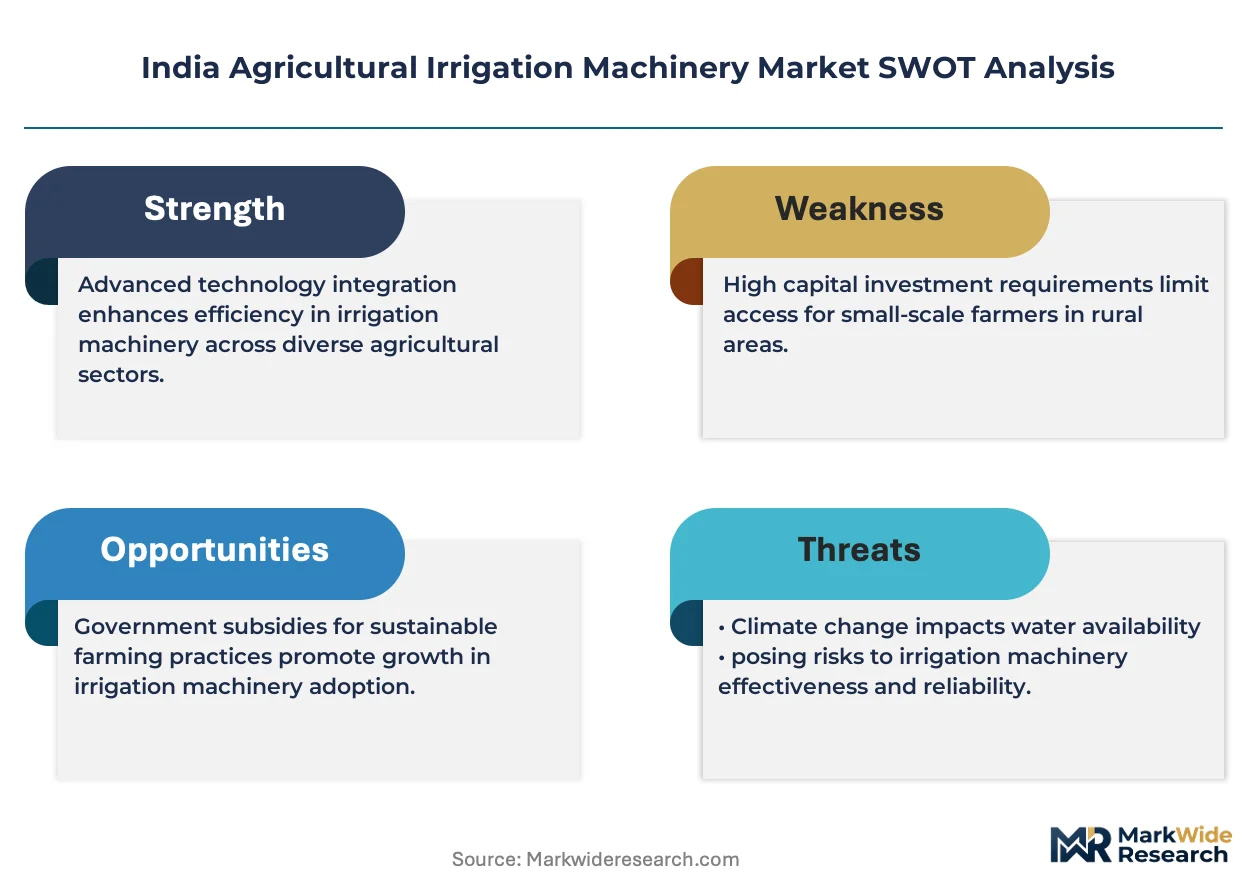
The Central Electricity Authority governs grid-interconnection standards for solar pumping systems, while BIS certification mandates material durability benchmarks for PVC and HDPE conduit products. The FSSAI's residue monitoring protocols indirectly shape irrigation water quality specifications for export-oriented commercial growers. Stakeholders must weigh the capital intensity of automation against the operational savings from PM-KUSUM subsidies as they configure product portfolios for the next investment cycle.
Market Dynamics
The PM-KUSUM scheme's subsidy architecture is restructuring capital flows across India's agricultural irrigation machinery sector, pulling solar-powered pump adoption from marginal presence toward mainstream procurement in water-stressed agrarian belts.
Growth Catalysts
- PM-KUSUM Component C:Central government subsidies covering up to 60 percent of standalone solar pump capital costs are unlocking adoption among smallholder farmers previously excluded from mechanized irrigation.
- Horticultural intensification:Punjab's vegetable belt and Maharashtra's grape-growing districts are driving drip system procurement as farmers shift from flood irrigation to precision water application for high-value crops.
- BIS polymer standards:Mandatory certification for HDPE and PVC conduit durability is consolidating supplier bases and elevating product quality baselines across state tender processes.
Market Restraints
- Petrochemical input volatility:Polymer resin prices fluctuate with crude oil movements, compressing margins for extrusion-dependent component manufacturers and creating pricing uncertainty for distributors.
- Regional supply concentration:Foundry capacity for metal sprinkler heads clusters in western Maharashtra, exposing procurement timelines to localized monsoon disruptions and logistics bottlenecks.
- Grid interconnection delays:CEA compliance timelines for solar pumping systems extend project commissioning by 4-8 months, freezing capital deployment and frustrating farmer adoption cycles.
Strategic Opportunities
- Northeastern underpenetration:Assam and Meghalaya's tea estates and horticulture belts remain underserved by micro-irrigation, presenting first-mover expansion terrain for drip system providers.
- Sensor-telemetry convergence:Integration of soil moisture probes with GSM-enabled valve controllers is creating precision automation tiers between basic drip and fully integrated smart platforms.
- FPO procurement aggregation:Farmer Producer Organizations are consolidating member demand into volume tenders, shifting transaction structures from individual retail to institutional B2B contracting.
Industry Challenges
- Skilled technician scarcity:Installation and maintenance of pressure-compensating emitters requires trained personnel absent in rural service networks, degrading system performance and warranty claim rates.
- Legacy flood irrigation persistence:Cultural resistance and sunk capital in conventional field layouts slow conversion rates even where subsidy economics favor drip adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agricultural Irrigation Machinery Market |
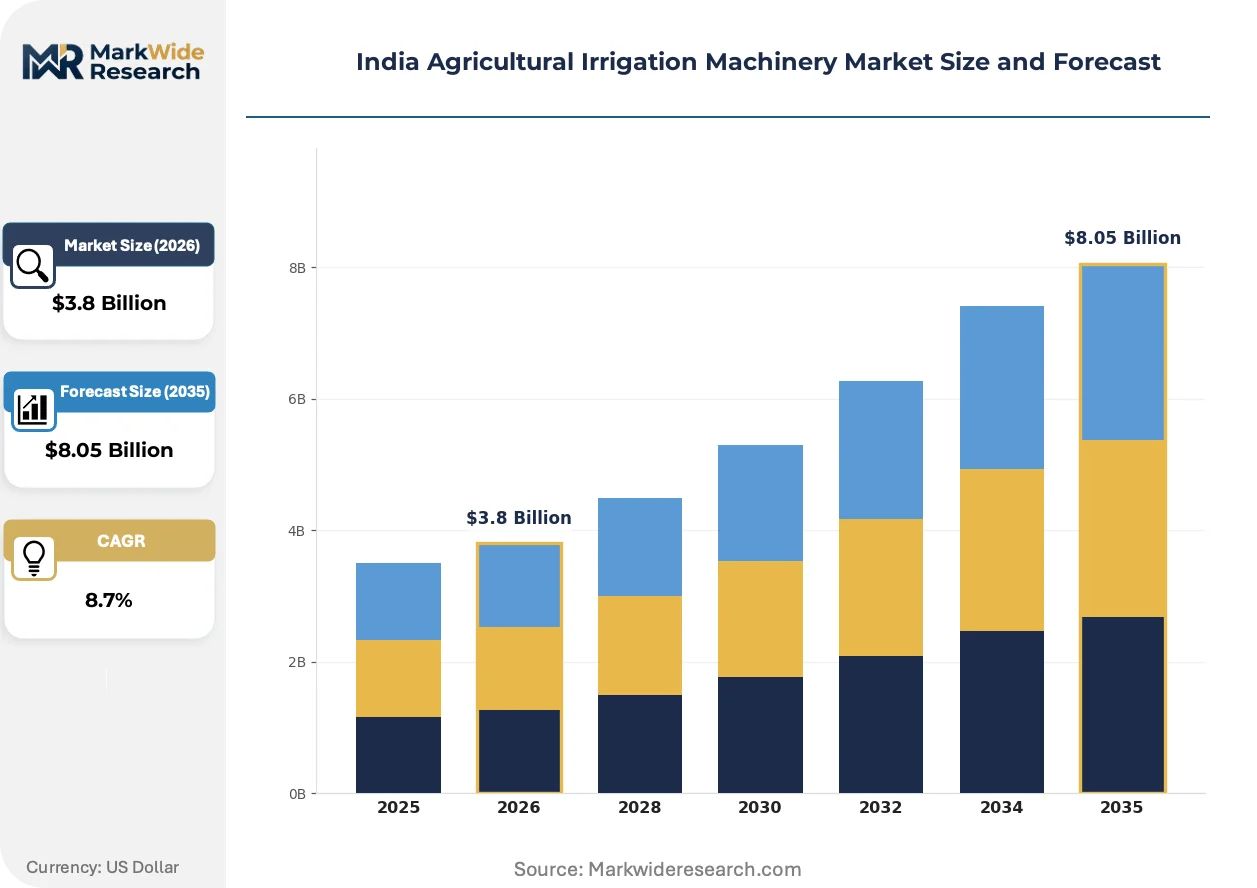
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Technology: Smart Irrigation, Automation, Solar-Powered Systems, Conventional Systems End User: Crop Farmers, Commercial Growers, Agricultural Cooperatives, Research Institutions Application: Field Irrigation, Greenhouse Irrigation, Landscape Irrigation, Urban Agriculture |
| Companies Covered | Jain Irrigation Systems Ltd., Netafim Ltd, Deere & Company, Mahindra EPC Irrigation Limited, Kothari Agritech Private Limited, Valmont Industries, Lindsay Corporation, Harvel Agua India Private Limited, Rivulis Irrigation India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agricultural Irrigation Machinery Market Shifts & Advancements
Solar-electrification of pumping infrastructure is fragmenting centralized grid dependency across India's agricultural heartland, while polymer chemistry advances and procurement digitization reshape competitive terrain.
Subsurface drip emitter technology is decentralizing water application control from surface-visible infrastructure to root-zone precision delivery. Grape and pomegranate growers in Karnataka and Andhra Pradesh are deploying these systems at accelerating rates. This shift is decentralizing maintenance responsibility from village-level mechanics to individual farm operators equipped with basic diagnostic tools.
The Pradhan Mantri Krishi Sinchayee Yojana's consolidated tender standards are harmonizing previously fragmented state procurement specifications. BIS certification mandates for UV-stabilized lateral tubing are filtering out non-compliant suppliers from government contract eligibility. Maharashtra and Gujarat irrigation departments are responding by pre-qualifying vendor pools against unified technical benchmarks.
Buying committees within sugarcane cooperatives are unbundling after-sales service from equipment procurement, awarding maintenance contracts to third-party agritech service providers separate from original manufacturers. This disintermediation is compressing brand loyalty cycles and elevating local service responsiveness as a competitive differentiator. The pattern is most visible in western Maharashtra's cooperative-dense belts where procurement volumes concentrate.
India Agricultural Irrigation Machinery Market Segmentation
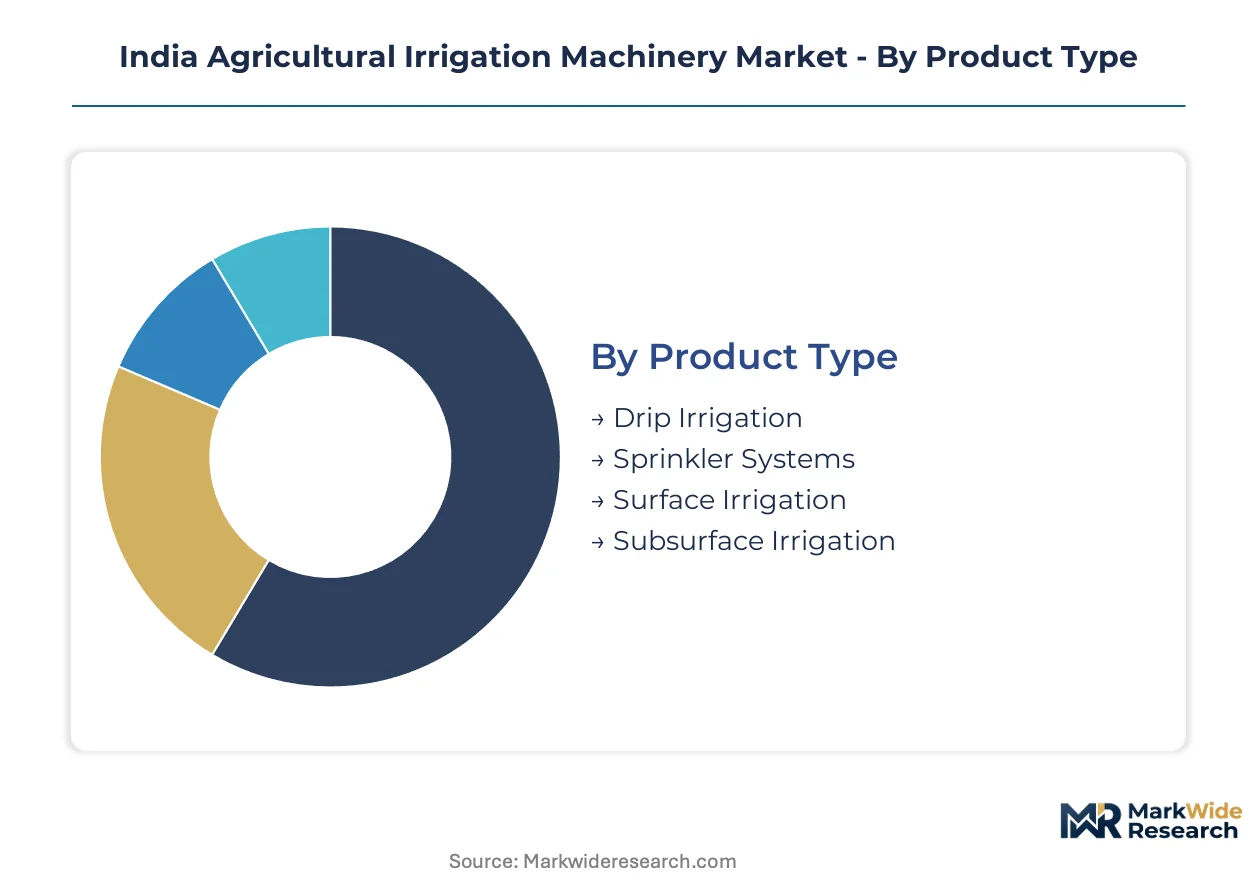
Segmentation of India's agricultural irrigation machinery reveals how certification requirements, subsidy eligibility, and crop-specific water delivery needs fragment procurement patterns across state tender processes and private retail channels. Understanding these divisions illuminates where BIS compliance burdens concentrate and which technology tiers capture PM-KUSUM capital flows.
Product Type:
BIS certification mandates for UV-stabilized polymers and pressure-rated conduit materials apply unevenly across product categories, with drip and sprinkler systems facing the most stringent material durability testing protocols.
- Drip Irrigation:Networks of lateral tubing, emitters, and filtration units deliver water directly to root zones at 0.5–4.0 bar operating pressure. Maharashtra's grape districts and Karnataka's pomegranate belts are driving procurement as horticultural intensification accelerates conversion from flood methods.
- Sprinkler Systems:Metal and polymer head assemblies distribute water through overhead spray patterns at 2.0–6.0 bar pressure. Western Maharashtra's sugarcane cooperatives maintain India's densest procurement concentration for these systems.
- Surface Irrigation:Gravity-fed channel and furrow systems dominate rice cultivation in Punjab and Haryana despite poor water use efficiency.
- Subsurface Irrigation:Buried emitter lines deliver water below the root zone, gaining traction among export-oriented vegetable growers seeking residue compliance with FSSAI protocols.
Drip irrigation sits at the top of the volume ranking, with subsurface systems climbing the fastest.
Technology:
Capital intensity and electrification requirements create sharp cost tiers across technology segments, determining which farmer categories can access PM-KUSUM subsidies versus self-financed automation upgrades.
- Smart Irrigation:Sensor-telemetry platforms integrating soil moisture probes with GSM-enabled valve controllers command premium pricing. Adoption concentrates among commercial grape and pomegranate operations in Karnataka seeking precision water stress management.
- Solar-Powered Systems:Standalone PV arrays driving submersible and surface pumps, eligible for 60 percent central subsidy under PM-KUSUM Component C. Rajasthan and Gujarat's groundwater-stressed districts are seeing the steepest expansion trajectory as grid connectivity gaps persist.
- Automation:Timer-based and remote-actuated control systems without full sensor integration occupy a mid-tier price position.
- Conventional Systems:Diesel and electric pumps with manual valve operation retain volume leadership among smallholders with limited capital access and no grid connection.
Conventional systems retain the largest installed base, though solar-powered alternatives are gaining share fastest.
End User:
Procurement scale and tender sophistication vary dramatically across end-user categories, with cooperatives and commercial growers driving standardization while smallholders remain fragmented.
- Agricultural Cooperatives:Maharashtra's sugarcane cooperatives unbundle equipment procurement from after-sales service, awarding maintenance contracts to third-party agritech providers. This disintermediation compresses manufacturer brand loyalty cycles.
- Commercial Growers:Export-oriented operations in Punjab's vegetable belt and Maharashtra's grape districts prioritize BIS-certified drip systems to meet FSSAI residue monitoring protocols.
- Crop Farmers:Smallholder cereal and oilseed producers in Madhya Pradesh and Uttar Pradesh dominate unit volumes but purchase lower-specification equipment through state subsidy schemes.
- Research Institutions:ICAR centers and state agricultural universities pilot precision irrigation technologies before commercial scaling.
Crop farmers represent the deepest volume pool, with cooperatives driving the fastest procurement value growth.
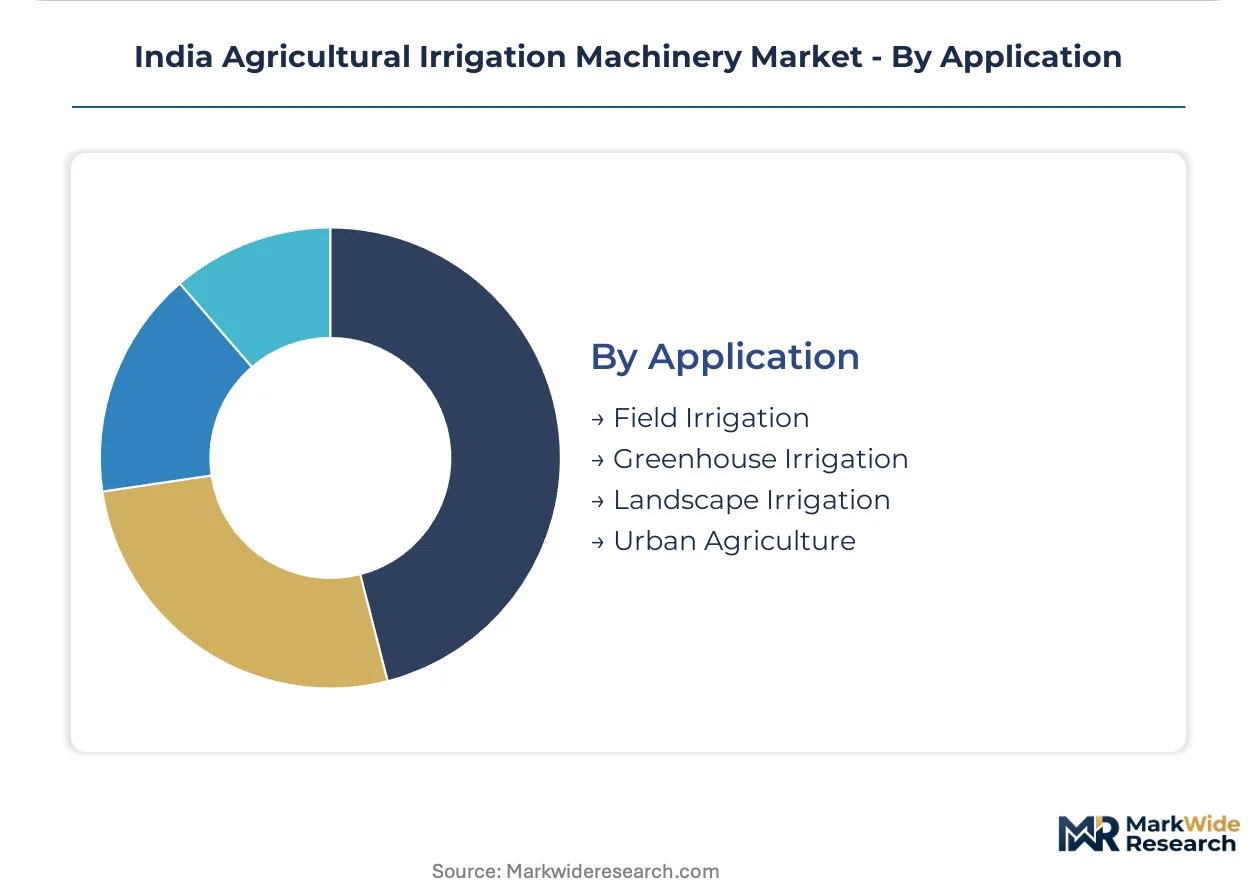
Application:
Water quality specifications and emitter clogging risks differentiate application segments, with greenhouse and urban agriculture demanding filtration intensities that field irrigation rarely requires.
- Greenhouse Irrigation:Closed-environment cultivation of flowers and vegetables in Nashik and Bengaluru peri-urban belts requires pressure-compensating emitters and acid-injection systems to manage fertigation.
- Field Irrigation:Open-field cereal, oilseed, and fiber crops across the Indo-Gangetic plain account for the largest water withdrawal volumes but lowest per-hectare equipment investment.
- Landscape Irrigation:Golf courses, highway medians, and institutional campuses in Delhi NCR and Mumbai metropolitan regions deploy high-pressure sprinkler networks.
- Urban Agriculture:Terrace and vertical farming installations in Bangalore and Hyderabad are piloting recirculating drip systems with nutrient recovery.
Field irrigation commands the greatest water volume, with greenhouse applications expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer extrusion technicians and foundry craftsmen concentrate in western India's industrial corridors, anchoring manufacturing capacity for precision irrigation components.
Maharashtra
Sugarcane cooperatives in western districts drive India's densest sprinkler system procurement, with unbundled maintenance contracts awarded to third-party agritech providers. The state irrigation department pre-qualifies vendor pools against PM-Krishi Sinchayee Yojana unified technical benchmarks. Pune-Nashik corridor hosts foundry clusters supplying metal sprinkler heads to cooperative buying committees.
Punjab
Horticulture belt vegetable growers are converting flood-irrigated fields to drip systems for potato, tomato, and capsicum cultivation. State agricultural universities pilot precision technologies before commercial scaling through ICAR extension networks. Ludhiana-Jalandhar axis concentrates polymer tubing distribution hubs serving the vegetable intensification zone.
Gujarat
Groundwater-stressed districts in Saurashtra and Kutch are seeing steepest solar pump expansion under PM-KUSUM Component C subsidies. BIS certification mandates for UV-stabilized HDPE conduit filter supplier eligibility in state tender processes. Anand-Vadodara industrial belt anchors captive foundry operations for metal component supply.
Karnataka
Commercial grape and pomegranate operations in Bijapur and Bagalkot districts deploy subsurface drip emitter technology for export-oriented production meeting FSSAI residue protocols. Sensor-telemetry platforms integrating soil moisture probes with GSM-enabled valve controllers concentrate among large commercial holdings. Bangalore peri-urban greenhouse clusters drive pressure-compensating emitter demand for closed-environment flower cultivation.
Rajasthan
Standalone solar pumping systems expand fastest among smallholders previously excluded from mechanized irrigation due to grid connectivity gaps. Central Electricity Authority compliance timelines extend project commissioning, freezing capital deployment in Jodhpur-Bikaner groundwater extraction zones. Jaisalmer-Barmer solar irradiance belts attract PV array manufacturers establishing regional service networks.
India Agricultural Irrigation Machinery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's agricultural irrigation machinery sector, creating a tiered structure where scale-driven manufacturers anchor volume segments and technology-focused firms capture premium niches. The vendor base clusters around three strategic archetypes: integrated polymer extrusion houses with captive compounding facilities, metalworking specialists commanding foundry-to-finish vertical control, and precision technology providers leveraging emitter engineering expertise. Consolidation pressures intensify as BIS certification mandates filter non-compliant suppliers from state tender eligibility, while cooperative procurement aggregation shifts transaction structures toward institutional B2B contracting.
Among integrated Indian manufacturers, Jain Irrigation Systems Ltd. and Mahindra EPC Irrigation Limited exemplify the diversified conglomerate archetype, each leveraging backward integration into polymer extrusion or captive foundry operations to anchor component supply positions. Netafim Ltd occupies a specialist tier representing precision emitter technology leadership, particularly in subsurface drip line applications where engineering differentiation commands premium positioning. These three anchors illustrate how competitive advantage in this sector derives from control over critical input materials, manufacturing process expertise, or precision technology IP rather than distribution scale alone.
| Leading Market Players |
|---|
| Jain Irrigation Systems Ltd. |
| Netafim Ltd |
| Deere & Company |
| Mahindra EPC Irrigation Limited |
| Kothari Agritech Private Limited |
| Valmont Industries |
| Lindsay Corporation |
| Harvel Agua India Private Limited |
| Rivulis Irrigation India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Polymer resin costs cascade through India's agricultural irrigation machinery sector from crude oil benchmarks to finished component tiers, with extrusion-dependent manufacturers absorbing margin compression while state tender processes lock in price ceilings for subsidized procurement.
Pricing Analysis
Bundled equipment-plus-service contracts dominate Maharashtra's sugarcane cooperatives, while unbundled procurement separates hardware from third-party maintenance awards. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade and after-sales service inclusion. Pricing pressure stems from petrochemical input volatility, with polymer resin fluctuations squeezing extrusion margins. Smallholder crop farmers in Madhya Pradesh and Uttar Pradesh exhibit highest price sensitivity, while commercial grape growers in Karnataka accept premium positioning for FSSAI-compliant subsurface systems.
Supply Chain Analysis
Dual-sourcing requirements in state tender processes mandate vendor pool pre-qualification against unified PM-Krishi Sinchayee Yojana benchmarks, forcing buyers to maintain multiple qualified suppliers. Manufacturing concentrates in India for polymer extrusion and metal foundry operations, with critical polymer resins drawing from Saudi Arabia, South Korea, and Singapore. Supply chain risk centers on single-source vulnerability for pressure-compensating emitter technology. Distribution runs through state irrigation department depots, cooperative buying committees, and private retail channels serving smallholder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's agricultural irrigation machinery market represents a late-cycle quality story, with BIS certification mandates and PM-KUSUM subsidy eligibility filtering non-compliant suppliers while demand shifts toward UV-stabilized, pressure-rated premium specifications.
For Market Incumbents: Deploy captive foundry capacity expansion to anchor metal component supply positions against polymer-focused competitors. Deepen backward integration into polymer compounding to buffer petrochemical volatility. Consolidate service networks in western Maharashtra's cooperative-dense belts before third-party agritech providers capture maintenance contracts. For New Entrants and Emerging Players: Launch via FPO procurement aggregation models targeting Assam and Meghalaya's underserved tea estates and horticulture belts. Prioritize sensor-telemetry convergence for mid-tier automation between basic drip and fully integrated smart platforms. Partner with state agricultural universities for ICAR-validated pilot programs before commercial scaling. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification burdens and subsidy eligibility requirements outpace smaller competitors' compliance capacity. Five-to-ten-year viability favors integrated manufacturers with captive polymer extrusion or foundry operations over pure distribution plays. Watch CEA grid-interconnection timeline compression as inflection signal for solar pump adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin processing buffers margin compression from crude-linked petrochemical volatility. |
| CEA Pre-Certification Partnership | Early regulatory engagement compresses solar pump commissioning timelines by 4-8 months. |
| FPO Procurement Channel Development | Institutional B2B contracting aggregates fragmented smallholder demand into volume tenders. |
| Sensor-Telemetry Platform Launch | GSM-enabled valve controllers capture precision automation tier between basic and smart systems. |
| Northeastern Expansion Deployment | First-mover positioning in Assam tea estates accesses underpenetrated micro-irrigation terrain. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with irrigation equipment manufacturers, state irrigation department procurement officers, cooperative buying committee members, and agritech service providers with secondary validation from BIS certification databases, CEA grid-interconnection filings, PM-KUSUM subsidy disbursement records, and ICAR extension network reports. Bottom-up equipment shipment tracking and top-down subsidy allocation analysis provided triangulation anchors.
Segment-weighting approaches applied product type, technology tier, end-user category, and application intensity dimensions across the projection horizon. CAGRs derived from fitted growth curves against subsidy scheme trajectories and horticultural intensification patterns. Forecast inputs incorporated groundwater stress indices for solar pump penetration modeling and FSSAI protocol adoption curves for subsurface drip demand.
Several conditions sit outside the modeled scope, including monsoon variability impacts on procurement timing, state-level subsidy co-funding changes, and unforeseen polymer resin supply disruptions. Forecasts reflect documented assumptions about PM-KUSUM continuity and BIS enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Tractor Rental Market