
 Asia-Pacific Plant Growth Regulators Market | 2026-2036
Asia-Pacific Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plant Growth Regulators Market Outlook
Modular formulation packaging is broadening buyer choice across the Asia-Pacific Plant Growth Regulators Market, enabling smallholder cooperatives and commercial farms to purchase application-ready units rather than bulk concentrates. Syngenta Group leverages its integrated seed-to-harvest portfolio to bundle growth regulators with proprietary crop protection packages. Tata Chemicals Ltd. anchors its position through deep distribution networks across India's agrarian states. Sumitomo Chemical Co. Ltd. differentiates via specialized cytokinin formulations tailored for premium horticultural export segments.
Plant growth regulators comprise synthetic or naturally derived organic compounds that modulate physiological processes in plants, including cell elongation, fruit set, and senescence, typically applied at concentrations measured in parts per million to achieve targeted agronomic outcomes. Their primary commercial purpose centers on optimizing yield quality, synchronizing harvest windows, and reducing post-harvest losses across intensive cropping systems. Auxin-based formulations occupy the dominant share of product type demand due to established efficacy in root initiation and fruit development protocols. Liquid formulations are expanding fastest among formulation categories, driven by compatibility with precision spraying equipment and fertigation infrastructure now penetrating Southeast Asian markets.
Regulatory frameworks across the Asia-Pacific region include China's MEE environmental compliance standards, India's FSSAI residue limits for export-bound produce, and Australia's APVMA registration requirements for agricultural chemical imports. These bodies collectively shape product registration timelines, residue tolerance thresholds, and market access conditions for both domestic manufacturers and multinational suppliers. Stakeholders must monitor evolving biopesticide equivalency pathways and carbon-footprint disclosure mandates that will determine which formulation technologies secure preferential positioning in procurement frameworks across the region.
Market Dynamics
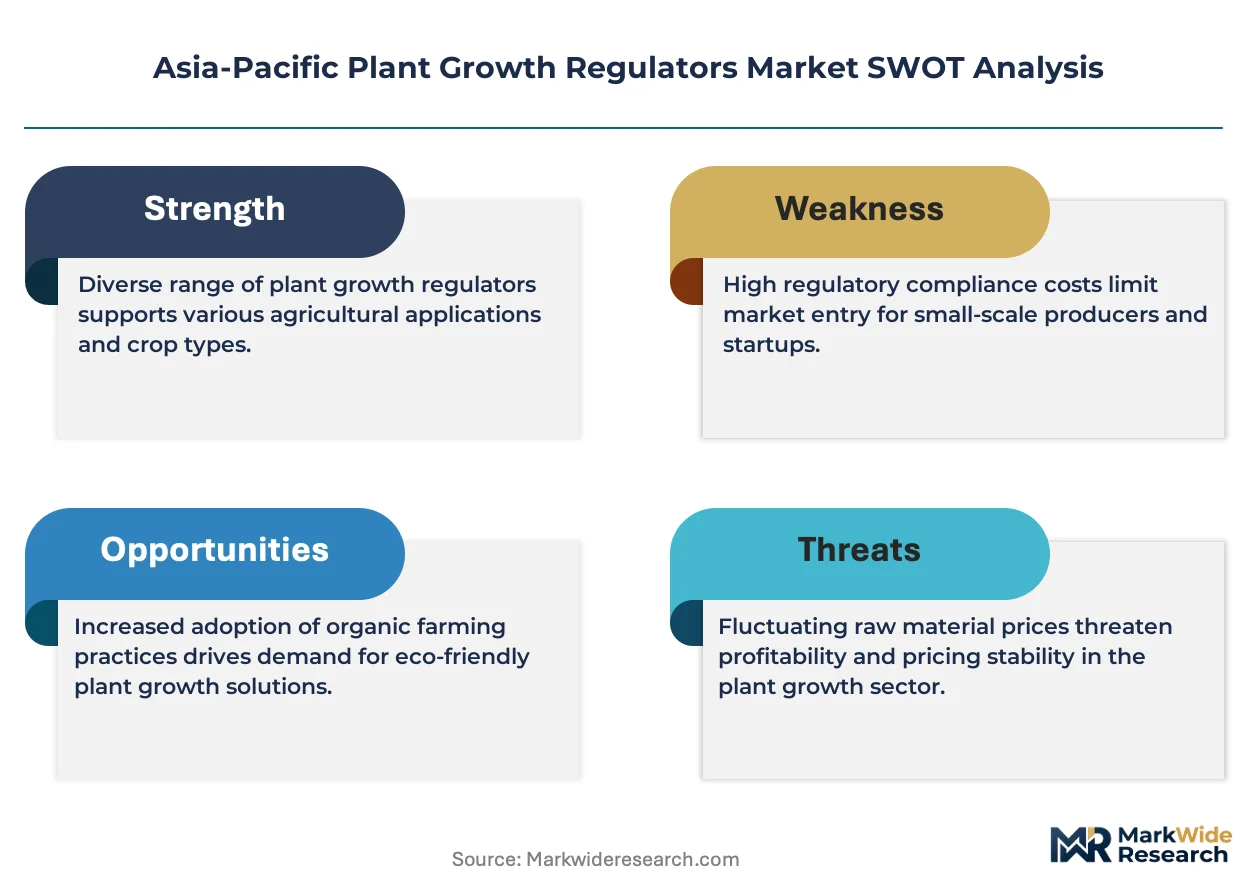
China's dual carbon goals and MEE environmental compliance standards are compressing registration timelines for synthetic formulations while accelerating bio-based alternative development across the Asia-Pacific Plant Growth Regulators Market.
Growth Catalysts
- Precision agriculture infrastructure:Southeast Asian commercial farms are integrating fertigation-compatible liquid formulations with automated spraying systems to synchronize harvest windows across contract farming arrangements.
- India's FSSAI residue limits:Export-oriented fruit and vegetable producers in Maharashtra and Karnataka are intensifying input quality requirements to meet European supermarket chain specifications.
- MEE environmental standards:China's tightening effluent and carbon-footprint disclosure mandates are pulling domestic manufacturers toward low-residue and bio-based formulation portfolios.
Market Restraints
- Active ingredient cost volatility:Petrochemical-derived synthetic auxin precursors face price pressure from naphtha supply fluctuations and energy input inflation.
- Registration concentration risk:China's NMPA and Australia's APVMA maintain divergent data requirements that extend multi-country product launch timelines by 18-36 months.
- Technical efficacy gaps:Bio-based cytokinin alternatives currently demonstrate shorter field persistence and more variable performance across soil pH gradients.
Strategic Opportunities
- Vietnam's Mekong Delta expansion:Specialty mango and dragon fruit cultivation zones remain underpenetrated by precision-applied regulator programs relative to Thai and Chinese benchmarks.
- Modular packaging formats:Application-ready unit dosing is opening cooperative procurement channels previously blocked by minimum order thresholds for bulk concentrates.
- Japan's METI bioeconomy roadmap:National subsidies for carbon-neutral agricultural inputs are creating preferential procurement pathways for fermentation-derived formulations.
Industry Challenges
- Field application expertise scarcity:Optimal parts-per-million calibration and phenological timing protocols require agronomists with combined horticultural and precision equipment training that remains concentrated in research institutions.
- Legacy inventory integration:Commercial farms with substantial synthetic auxin stocks face stranded asset risk as residue tolerance thresholds tighten under FSSAI and APVMA revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plant Growth Regulators Market |
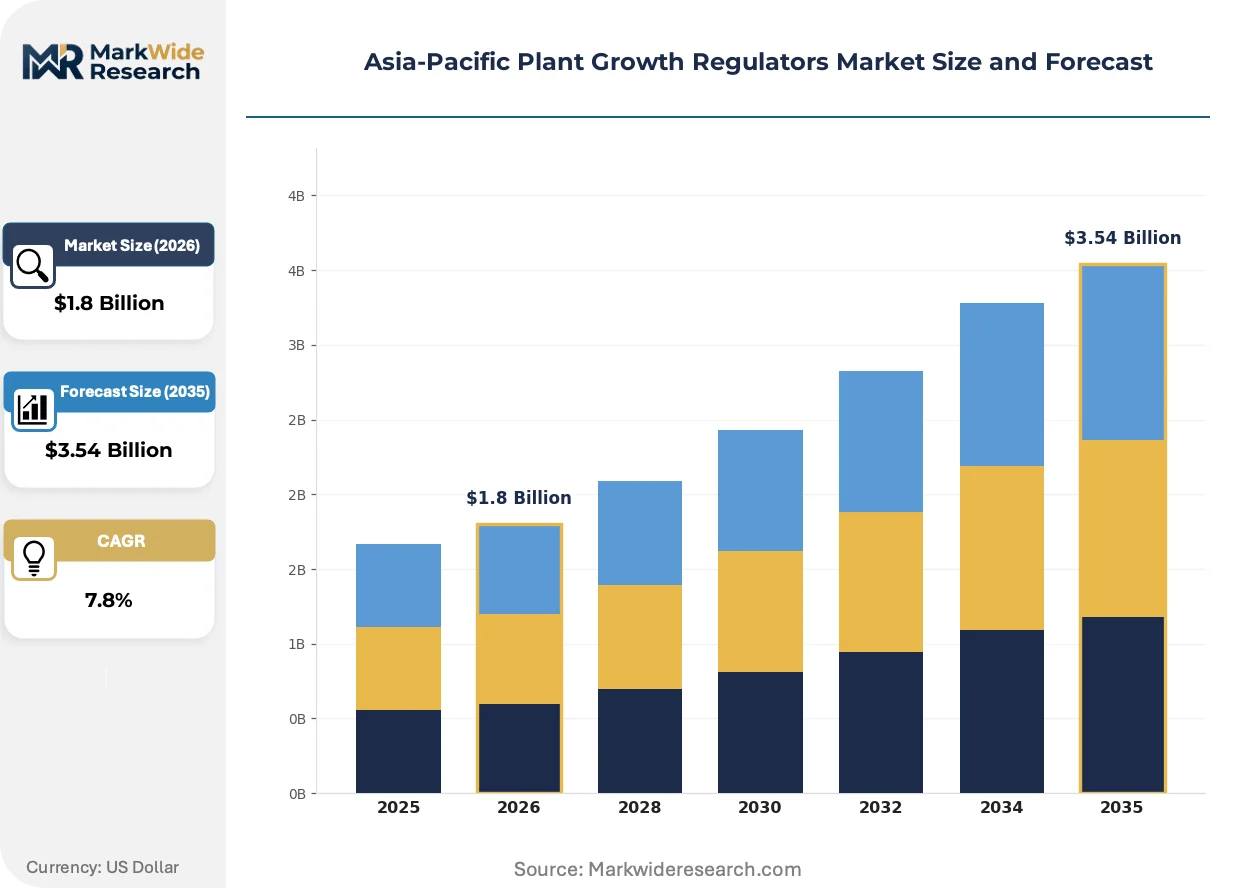
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Others Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Online, Retail, Distributors, Wholesalers |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Nufarm Limited, Sumitomo Chemical Co. Ltd., Tata Chemicals Ltd., Sichuan Guoguang Agrochemical Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plant Growth Regulators Market Strategic Shifts
Formulation chemistry, regulatory disclosure requirements, and procurement channel structures are simultaneously shifting across the Asia-Pacific Plant Growth Regulators Market, compressing traditional product lifecycles and redistributing margin capture toward application-technology bundlers.
Microencapsulated delivery systems with controlled-release kinetics are rewriting efficacy expectations for foliar-applied cytokinins in premium horticultural export segments. Japanese greenhouse operators and Australian table grape producers are piloting these formulations at commercial scale. The technology is compressing application frequency requirements from weekly to monthly intervals while reducing labor cost exposure.
MEE's carbon-footprint disclosure mandates for agricultural chemical manufacturing are forcing reformulation investments across Chinese domestic suppliers. Facilities must now quantify Scope 1 and 2 emissions per kilogram of active ingredient and submit verified data for registration renewals. Synthetic auxin producers with captive fermentation capacity for bio-based feedstocks are securing expedited approval pathways.
Smallholder cooperatives in India's Maharashtra and Gujarat are consolidating procurement through digital input aggregators that unbundle traditional distributor markups. These platforms offer direct manufacturer pricing on application-ready units with embedded agronomic advisory services. The shift is most visible in pomegranate and grape cultivation belts where export contract farming penetration exceeds sixty percent.
Asia-Pacific Plant Growth Regulators Market Segmentation
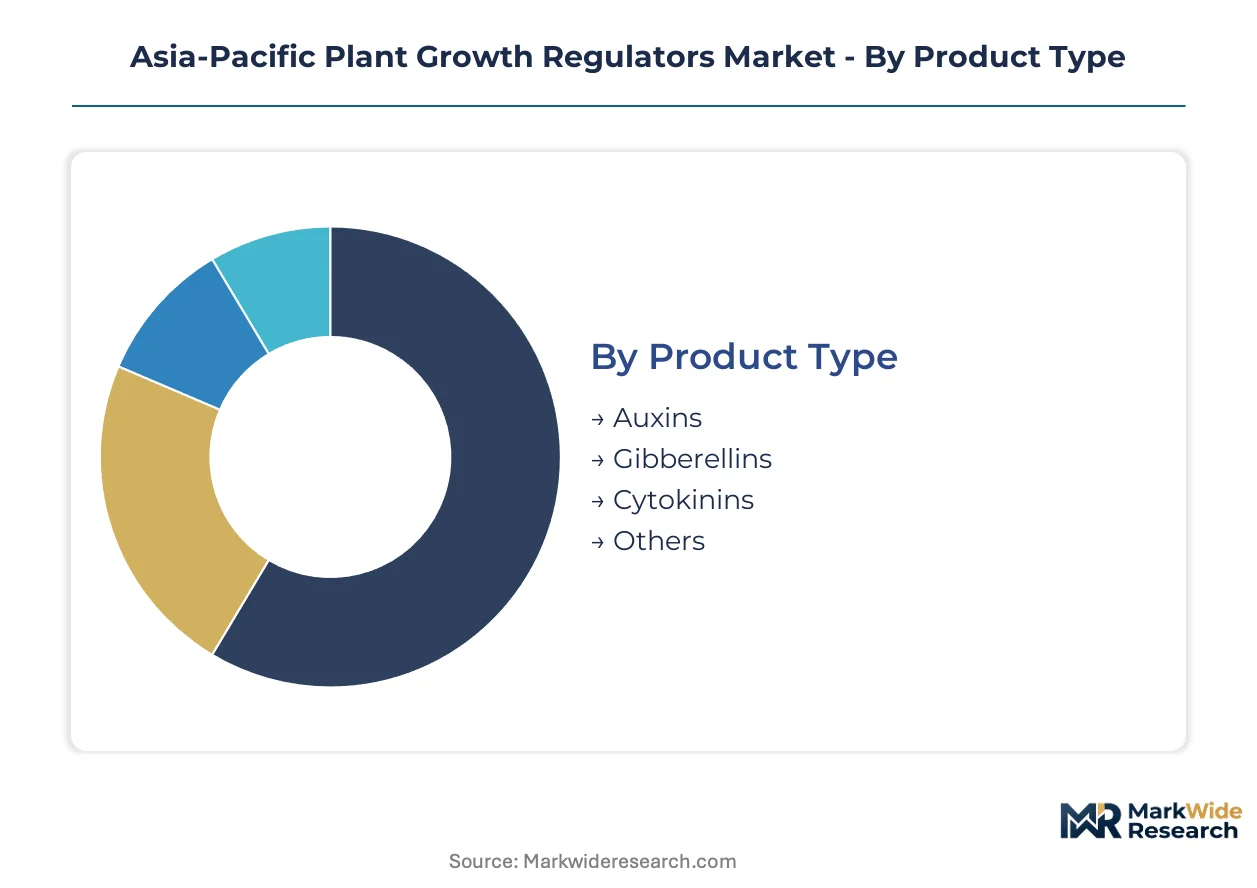
Segmentation across the Asia-Pacific Plant Growth Regulators Market reveals divergent growth vectors between commodity-scale agricultural applications and precision-managed horticultural systems. Formulation chemistry and distribution channel structures are compressing traditional product lifecycles as regulatory disclosure requirements intensify across Chinese and Indian jurisdictions.
Product Type:
Auxin-based formulations command volume leadership through established root initiation protocols, while cytokinin alternatives capture premium positioning in export-oriented fruit development programs.
- Auxins:Synthetic indole-3-butyric acid and naphthaleneacetic acid formulations dominate commercial root cutting and fruit setting applications across India's Maharashtra grape belts and China's Shandong apple regions. MEE carbon-footprint disclosure mandates are forcing domestic manufacturers toward fermentation-derived bio-based feedstocks with captive production capacity.
- Gibberellins:GA3 and GA4+7 formulations synchronize flowering and break seed dormancy in citrus and table grape cultivation across Australia's Sunraysia and Vietnam's Mekong Delta. Demand concentrates where export contract farming requires precise harvest window coordination for European supermarket chain specifications.
- Cytokinins:Specialized 6-benzylaminopurine formulations for premium horticultural export segments.
- Others:Abscisic acid and ethylene inhibitors for stress tolerance and post-harvest management protocols.
Today's leader: Auxins. Tomorrow's challenger: Cytokinins.
Application:
Commercial significance tilts toward high-value horticultural segments where parts-per-million calibration precision justifies input cost premiums against commodity crop economics.
- Agricultural Crops:Rice, wheat, and maize applications across India's Indo-Gangetic Plain and China's Northeast Plain rely on cost-optimized auxin formulations for lodging resistance and yield stabilization. FSSAI residue limit compliance for export-bound basmati rice intensifies input quality screening.
- Horticultural Crops:Precision-applied regulator programs in mango, dragon fruit, and table grape cultivation command formulation premiums across Thailand's Chiang Mai, Vietnam's Lam Dong, and Australia's Riverina. Microencapsulated delivery systems with controlled-release kinetics are compressing application frequency from weekly to monthly intervals.
- Turf:Golf course and sports field maintenance across Japan's Kanto Plain and South Korea's metropolitan regions.
- Ornamentals:Greenhouse chrysanthemum and orchid production for export floriculture.
Horticultural crop applications are expanding most quickly; agricultural crop volumes anchor manufacturer throughput.
Formulation:
Liquid formats are displacing legacy granular systems as fertigation infrastructure penetrates Southeast Asian commercial farming operations.
- Liquid:Water-soluble concentrates compatible with automated spraying and drip irrigation systems dominate new procurement across Vietnam's commercial mango operations and Indonesia's protected vegetable greenhouses. Sumitomo Chemical's cytokinin portfolios and Syngenta's bundled crop protection packages favor this format for precision equipment integration.
- Granular:Slow-release formulations persist in smallholder rice cultivation where equipment access remains limited.
- Powder:Wettable powder formulations for manual mixing in cooperative procurement channels.
- Emulsifiable Concentrate:Oil-based systems for foliar penetration in waxy-leaf horticultural species.
Liquid formulations are gaining share fastest; granular systems retain penetration in equipment-constrained segments.
Distribution Channel:
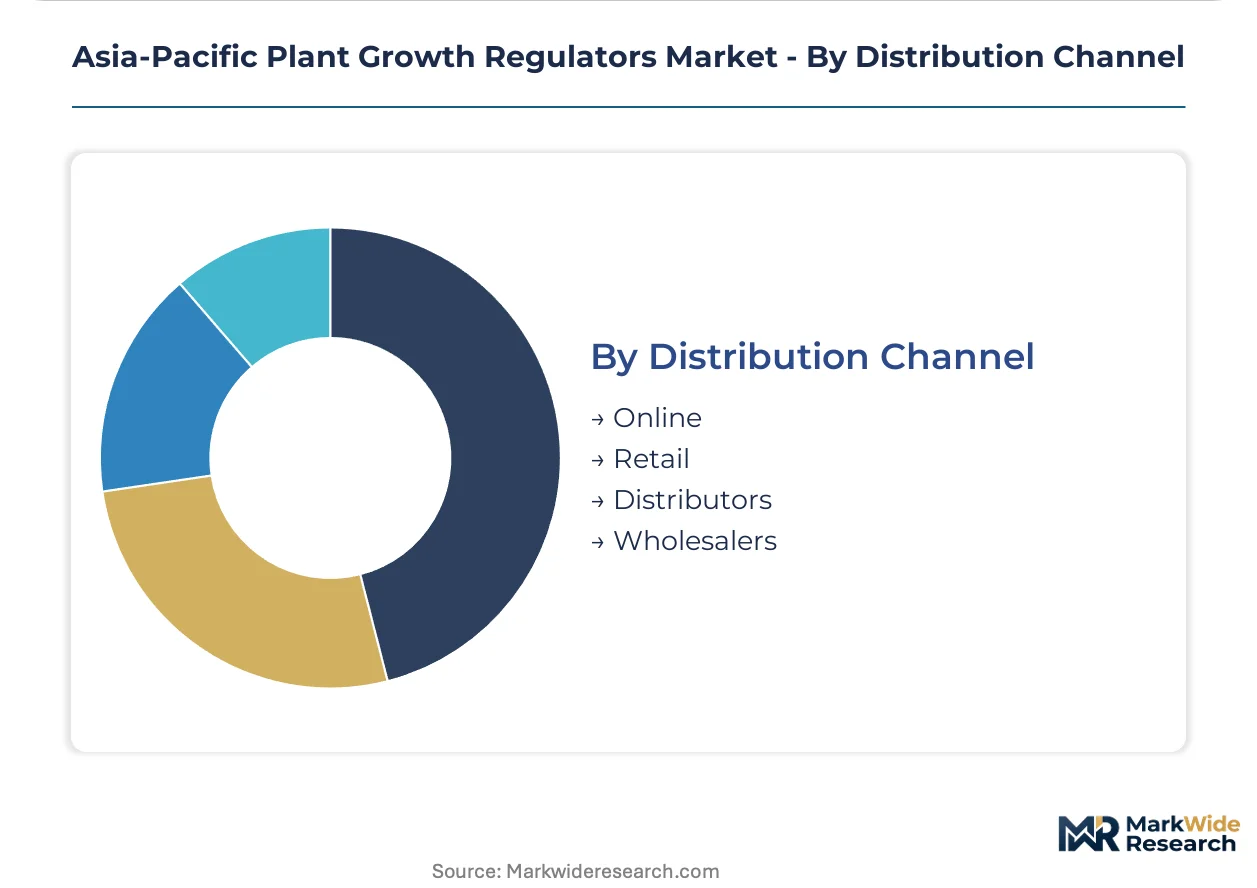
Channel structures are bifurcating between digitized direct procurement for export-oriented commercial farms and traditional distributor networks serving smallholder cooperatives.
- Distributors:Tata Chemicals anchors market presence through deep distribution networks across India's agrarian states, with agronomist-staffed depots in Gujarat and Karnataka providing phenological timing advisory. Minimum order thresholds for bulk concentrates have historically blocked cooperative access.
- Online:Digital input aggregators in Maharashtra and Gujarat are unbundling traditional markups through direct manufacturer pricing on application-ready units with embedded advisory services.
- Retail:Branded counter sales through agricultural supply cooperatives.
- Wholesalers:Volume procurement intermediaries for plantation-scale operations.
Distributor networks defend current volume leadership; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial plant growth regulator applications first achieved scale in Japan's protected cultivation systems during the 1970s, then diffused through Taiwan's export horticulture sector before penetrating mainland China's intensifying fruit belts. Today's Asia-Pacific landscape reflects this lineage through tiered adoption patterns across maturing precision agriculture markets.
China
Shandong Province's apple cultivation belts and Yunnan's flower export zones drive formulation demand for harvest synchronization. MEE carbon-footprint disclosure mandates now require Scope 1 and 2 emissions quantification per kilogram of active ingredient for registration renewals. Domestic manufacturers with captive fermentation capacity in Jiangsu and Zhejiang are securing expedited approval pathways for bio-based auxin alternatives.
India
Maharashtra's grape belts and Karnataka's pomegranate cultivation zones concentrate demand for residue-compliant inputs under FSSAI export specifications. Contract farming arrangements with European supermarket chains intensify parts-per-million calibration requirements. Gujarat's agrarian cooperatives are consolidating procurement through digital input aggregators that unbundle traditional distributor markups on application-ready units.
Japan
Chubu region's greenhouse vegetable operators and Kanto Plain's turf management sectors prioritize precision application technologies. METI's bioeconomy roadmap channels national subsidies toward carbon-neutral agricultural inputs, creating preferential procurement pathways for fermentation-derived cytokinin formulations. Microencapsulated delivery systems with controlled-release kinetics are compressing application frequency from weekly to monthly intervals.
Australia
Sunraysia's table grape cultivation and Riverina's citrus belts require APVMA-registered formulations for export-oriented harvest window coordination. The regulator's divergent data requirements relative to China's NMPA extend multi-country product launch timelines. Premium horticultural segments are piloting controlled-release cytokinin formulations at commercial scale to reduce labor cost exposure.
Vietnam
Lam Dong Province's specialty mango operations and Mekong Delta dragon fruit cultivation zones remain underpenetrated by precision-applied regulator programs relative to Thai benchmarks. Commercial farms are integrating fertigation-compatible liquid formulations with automated spraying infrastructure to synchronize harvest windows across emerging contract farming arrangements.
Asia-Pacific Plant Growth Regulators Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and advisory bundling capabilities. The vendor base clusters around three strategic archetypes: integrated agrochemical conglomerates with seed-to-harvest portfolios, domestic specialists with deep distribution networks in agrarian states, and fermentation-derived bio-based formulators serving carbon-neutral procurement channels. Dominant competitive moves include portfolio diversification into microencapsulated delivery systems and backward integration into captive bio-based feedstock production.
Among Asia-Pacific-based suppliers, Sumitomo Chemical Co. Ltd. and Tata Chemicals Ltd. exemplify contrasting positioning strategies. Sumitomo Chemical occupies a position within the specialized cytokinin tier serving premium horticultural export segments. Tata Chemicals anchors presence through distribution infrastructure across India's agrarian states. Syngenta Group represents the integrated conglomerate archetype with bundled crop protection packaging capabilities.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm Limited |
| Sumitomo Chemical Co. Ltd. |
| Tata Chemicals Ltd. |
| Sichuan Guoguang Agrochemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Formulation-grade bifurcation between residue-compliant premium tiers and commodity auxin grades manifests in divergent procurement pathways across the Asia-Pacific Plant Growth Regulators Market. Premium cytokinin formulations command price premiums through FSSAI-certified channels serving European export contracts, while standard-grade synthetic auxins flow through bulk distributor networks to smallholder rice belts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with differentiation driven by MEE carbon-footprint certification status and microencapsulation technology integration. Cost compression in synthetic auxin feedstocks intensifies as naphtha-derived precursors face energy input inflation, while bio-based alternatives with captive fermentation capacity capture margin expansion. Export-oriented horticultural operations in Maharashtra and Karnataka demonstrate lowest price sensitivity due to contract farming premiums, whereas Indo-Gangetic Plain cereal growers anchor economy-tier demand.
Supply Chain Analysis
Regional distribution centers in Shanghai, Mumbai, and Singapore anchor hub-and-spoke patterns for liquid formulation logistics across Southeast Asian commercial farm networks. Active ingredient production concentrates in Jiangsu and Zhejiang provinces for fermentation-derived cytokinins, Gujarat for synthetic auxin compounding, and Osaka for precision encapsulation technologies. Raw material dependencies span naphtha streams from South Korean refineries, fermentation substrates from Thai sugarcane processing, and specialty polymer coatings from Japanese chemical suppliers. Single-source vulnerability in microencapsulation polymer feedstocks presents structural risk. Distribution runs through agronomist-staffed depots for premium tiers and digital input aggregators for cooperative procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Plant Growth Regulators Market functions as a stable compounder, with precision agriculture infrastructure penetration across Southeast Asian commercial farms driving steady formulation demand expansion.
For Market Incumbents: Deploy backward integration into captive bio-based feedstock production to secure MEE expedited approval pathways and insulate margin structures from naphtha volatility. Synthetic auxin producers with stranded legacy inventory face tightening FSSAI residue thresholds; accelerate portfolio transition through microencapsulation R&D partnerships with Japanese greenhouse operators. Channel control through agronomist-staffed depots defends premium positioning against digital aggregator disintermediation. For New Entrants and Emerging Players: METI's bioeconomy roadmap in Japan opens a window for fermentation-derived cytokinin specialists to capture national subsidy procurement pathways. Vietnam's Mekong Delta specialty mango and dragon fruit cultivation zones present underpenetrated white-space for fertigation-compatible liquid formulation programs. Digital input aggregator partnerships in Gujarat and Maharashtra offer direct go-to-market access previously blocked by distributor minimum order thresholds. For Investors and Strategic Acquirers: Consolidation pressure builds where distributor networks lack digital advisory capabilities and face margin compression from platform-based procurement. Acquisition target archetypes include mid-cap formulators with captive fermentation capacity and regional registration portfolios spanning China NMPA and Australia APVMA. Watch for inflection signals in MEE carbon-footprint disclosure enforcement timelines that will determine which formulation technologies secure preferential positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures MEE expedited approval pathways and reduces naphtha cost exposure for domestic Chinese manufacturers. |
| Microencapsulation Technology Licensing | Compresses application frequency from weekly to monthly intervals for Japanese greenhouse vegetable operators. |
| Digital Input Aggregator Partnership | Unbundles traditional distributor markups for Maharashtra grape belt cooperatives through direct manufacturer pricing. |
| Dual Registration Portfolio Expansion | Accelerates multi-country product launches across China NMPA and Australia APVMA convergence timelines. |
| Carbon-Neutral Formulation Certification | Captures METI subsidy procurement pathways for fermentation-derived cytokinin alternatives in Japanese markets. |
Study Parameters
Multiple input streams — technical interviews with formulation chemists and regulatory affairs directors, distributor network mapping across India's agrarian states, and customs data reconciliation for active ingredient trade flows — were reconciled against secondary validation from MEE disclosure filings, FSSAI residue limit notifications, and APVMA registration databases. Bottom-up triangulation across product-type demand curves and top-down cross-checks against regional agricultural output statistics anchored volume estimates.
Historical shipment patterns were cross-referenced against panel input from procurement managers at export-oriented horticultural operations and precision equipment integrators in Vietnam's Mekong Delta. Segmentation dimensions modeled include product type, application crop category, formulation chemistry, and distribution channel structure across the analysis window. CAGRs were derived from fitted growth curves incorporating fertigation infrastructure penetration rates and contract farming expansion trajectories in premium fruit belts.
Revisions become necessary when MEE carbon-footprint enforcement timelines accelerate, FSSAI residue thresholds tighten beyond current notification schedules, or naphtha feedstock disruptions alter synthetic auxin cost structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Global Soil Wetting Agents Market