
 Asia Pacific Irrigation Valves Market | 2026-2036
Asia Pacific Irrigation Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Irrigation Valves Market Insights
Australia's Murray-Darling Basin water buyback reforms is decoupling irrigation efficiency from simple acreage expansion, forcing growers toward precision water control. Hunter Industries leverages its R&D intensity to dominate smart controller integration with valve systems across Australian viticulture. Netafim anchors drip-line valve demand through its specialized position in subsurface irrigation networks for Indian sugarcane belts. Toro Company competes on manufacturing scale, sustaining broad distribution across Southeast Asian plantation agriculture.
Irrigation valves regulate, direct, and control water flow within pressurized agricultural distribution networks, typically rated for operating pressures between 0.1 and 1.6 MPa with corrosion-resistant seals suited to chemically treated water and saline conditions. Their primary purpose is to enable zone-based water application, prevent backflow contamination, and automate scheduling in modern precision agriculture systems. Ball valve configurations lead product type demand due to their quarter-turn reliability in high-cycle automation environments, while butterfly valve adoption is accelerating in large-diameter canal distribution projects where cost-per-flow-capacity dominates procurement decisions. Stainless steel material grades command premium positioning in saline groundwater zones across coastal India and Southeast Asia, whereas plastic variants occupy volume-driven segments in China's mechanized field crop sectors.
India's BIS mandates material durability testing for plastic irrigation components, while Australia's Water Act enforcement through the Murray-Darling Basin Authority shapes volumetric control requirements. China's GB standards for agricultural machinery hydraulic interfaces influence valve connector specifications, and METI's water-saving equipment certification in Japan creates a technical barrier for non-compliant imports. Stakeholders must monitor how cumulative regulatory divergence across these frameworks affects cross-border product platform strategies and certification cost structures.
Market Dynamics
Australia's Murray-Darling Basin water buyback reforms are decoupling irrigation efficiency from simple acreage expansion, forcing growers toward precision water control systems that demand higher-specification valve infrastructure.
Growth Catalysts
- Water trading schemes:Australia's Murray-Darling Basin Authority volumetric controls incentivize infrastructure upgrades among cotton and rice growers seeking tradable water efficiency credits.
- BIS certification mandates:India's Bureau of Indian Standards material durability testing for plastic irrigation components is accelerating replacement cycles across Maharashtra and Gujarat farming cooperatives.
- Subsurface drip networks:Sugarcane belts in Uttar Pradesh and Karnataka are adopting buried drip-line systems requiring specialized pressure-compensating valve configurations.
Market Restraints
- Stainless steel input volatility:Coastal saline groundwater zones across India and Southeast Asia require corrosion-resistant grades, exposing valve manufacturers to nickel price swings.
- Regional supply concentration:Precision controller integration capabilities cluster among Australian and Israeli technology providers, limiting sourcing options for Southeast Asian plantation operators.
- Butterfly valve technical limitations:Large-diameter canal distribution projects face seal degradation under high-cycle automation, constraining reliability in China's mechanized field crop sectors.
Strategic Opportunities
- Vietnam Mekong Delta underpenetration:Rice intensification zones lack automated zone-control infrastructure, creating first-mover advantage for pressure-rated valve distributors.
- Japan METI water-saving certification:Technical barriers for non-compliant imports protect premium positioning for certified precision agriculture equipment in high-value horticulture.
- IoT-sensor convergence:Soil moisture telemetry integration with hydraulic actuators enables predictive valve scheduling in Australian viticulture and orchard operations.
Industry Challenges
- Hydraulic integration complexity:China's GB standards for agricultural machinery interfaces create retrofit friction for legacy pressurized distribution networks.
- Multi-jurisdiction certification timelines:Valve manufacturers face divergent testing protocols across Australia's Water Act, India's BIS mandates, and Japan's METI requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Irrigation Valves Market |
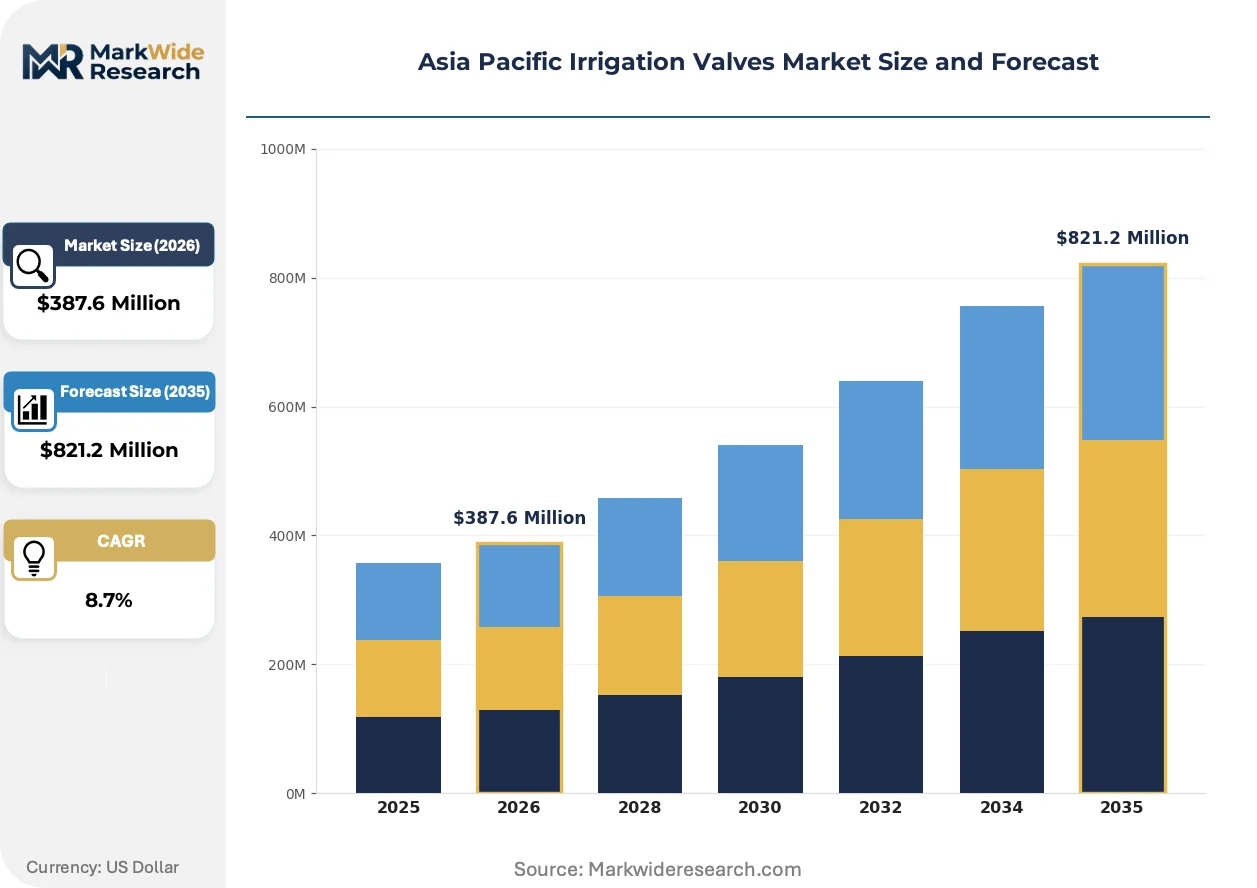
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Ball Valve, Check Valve, Butterfly Valve Installation Method: Above Ground, Underground, Portable, Permanent End User: Agriculture, Commercial, Residential, Landscaping Material: Plastic, Brass, Stainless Steel, Cast Iron |
| Companies Covered | Hunter Industries, Netafim, Toro Company, Bermad CS Ltd, Nelson Irrigation, KSB Co. Ltd., Rivulis Irrigation, Cla-Val Asia Pacific, TeeJet Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Irrigation Valves Market Trends and Innovations
Smart controller integration is unifying hydraulic actuation with real-time telemetry, collapsing the historical separation between mechanical valve hardware and automated scheduling platforms across Asia Pacific precision agriculture.
Electromechanical valve actuators with embedded flow sensors are unifying pressure regulation and consumption monitoring into single hardware units. Australian viticulture cooperatives are deploying these systems at scale to satisfy Murray-Darling Basin volumetric reporting requirements. This convergence is unifying what were separate capital expenditure decisions for hardware and telemetry infrastructure.
India's BIS certification framework for plastic irrigation components is tightening material standards through mandatory UV degradation and impact resistance testing. Manufacturers serving Maharashtra's drip-irrigation districts must now document polymer grade traceability. Maharashtra's sugarcane processing cooperatives are responding by consolidating procurement around certified suppliers with established testing laboratory relationships.
Service unbundling is separating valve hardware sales from installation and calibration support across Southeast Asian plantation agriculture. Large palm oil and rubber estate operators now contract precision agriculture specialists for zone mapping and pressure optimization rather than relying on equipment distributors. This shift is most visible in Indonesia and Malaysia where estate consolidation has concentrated buying power among technical procurement teams.
Asia Pacific Irrigation Valves Market Segmentation
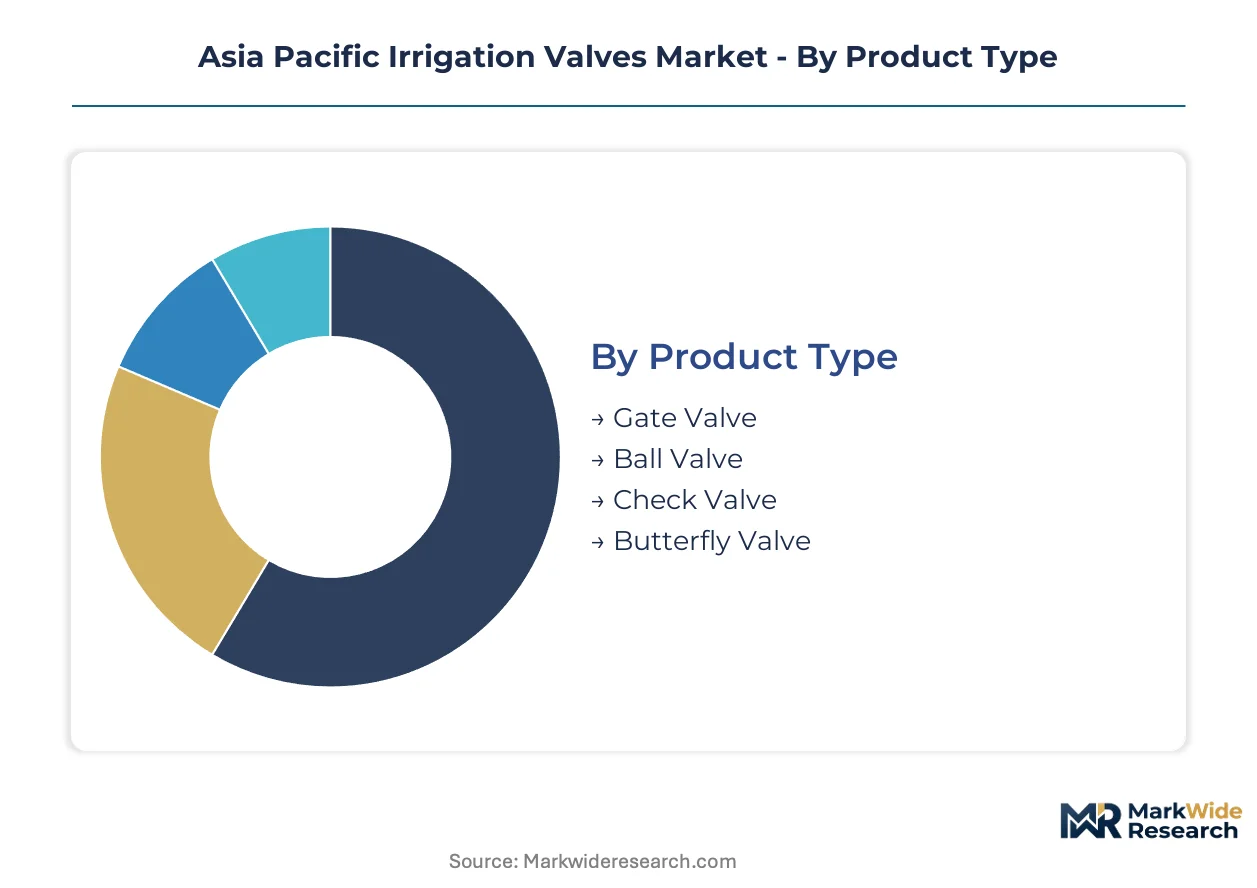
Irrigation valve procurement across Asia Pacific follows distinct technical and economic logics that reshape replacement cycles. Segment-specific durability requirements and automation readiness determine which configurations capture upgrade budgets in Australia's water-trading zones versus India's BIS-regulated districts.
Product Type:
Replacement cycles accelerate where precision agriculture mandates demand higher automation reliability.
- Ball Valve:Quarter-turn actuation delivers consistent sealing across high-cycle automation environments. Australia's Murray-Darling Basin cotton growers specify these for zone-control retrofits that qualify for volumetric efficiency credits under Water Act enforcement.
- Butterfly Valve:Cost-per-flow-capacity economics dominate large-diameter canal distribution projects. China's mechanized field crop sectors in Heilongjiang and Xinjiang deploy these for mainline branching, though seal degradation under frequent cycling constrains reliability in fully automated networks.
- Gate Valve:Linear stem movement suits isolation duties in low-cycle applications. India's BIS-certified plastic pipeline networks in Maharashtra's sugarcane belts retain these for sectional shutoff rather than modulation.
- Check Valve:Passive backflow prevention protects chemically treated distribution lines. Coastal saline groundwater zones across Tamil Nadu and Karnataka specify corrosion-resistant configurations for subsurface drip inlet protection.
Ball valve configurations sit at the top of the volume ranking, with butterfly valve demand climbing the fastest in canal modernization programs.
Installation Method:
Capital intensity and labor availability shape method selection across plantation versus cooperative farming structures.
- Above Ground:Exposed mounting enables rapid access for maintenance and seasonal reconfiguration. Australian viticulture cooperatives in Riverina and Barossa Valley favor these for smart controller retrofits that require frequent sensor calibration.
- Underground:Buried placement protects against mechanical damage and UV degradation in high-radiation climates. India's BIS-mandated UV resistance testing for plastic components has normalized this approach across Gujarat's groundnut irrigation districts.
- Portable:Mobile configurations serve rotational cropping systems and rental equipment markets. Southeast Asian rice intensification zones in Vietnam's Mekong Delta deploy these where land tenure fragmentation prevents permanent infrastructure investment.
- Permanent:Fixed installations amortize capital across multi-decay crop cycles. Indonesian and Malaysian palm oil estates specify these for central-pivot and linear-move systems with 15-year depreciation horizons.
Above ground installations retain the largest installed base, though underground methods are expanding most quickly under India's tightening material standards.
End User:
Water pricing mechanisms and crop value density create divergent specification thresholds across user categories.
- Agriculture:Pressurized distribution networks for broadacre and horticultural production constitute the core demand pool. Australia's water trading schemes directly incentivize infrastructure upgrades among cotton and rice growers seeking efficiency credits.
- Commercial:Golf courses, sports turf, and municipal parks require aesthetic performance alongside hydraulic function. Japan's METI water-saving certification creates technical barriers that protect premium positioning for precision equipment in this segment.
- Residential:Individual property automation drives demand for compact electromechanical actuators. China's urban landscaping expansion in tier-two cities concentrates volume for WiFi-enabled zone controllers.
- Landscaping:Contract maintenance operations prioritize rapid diagnostics and modular replacement. Service unbundling across Indonesian estate agriculture has separated hardware procurement from calibration support in this channel.
Agriculture dominates absolute volume, with commercial applications showing the steepest specification escalation under certification requirements.
Material:
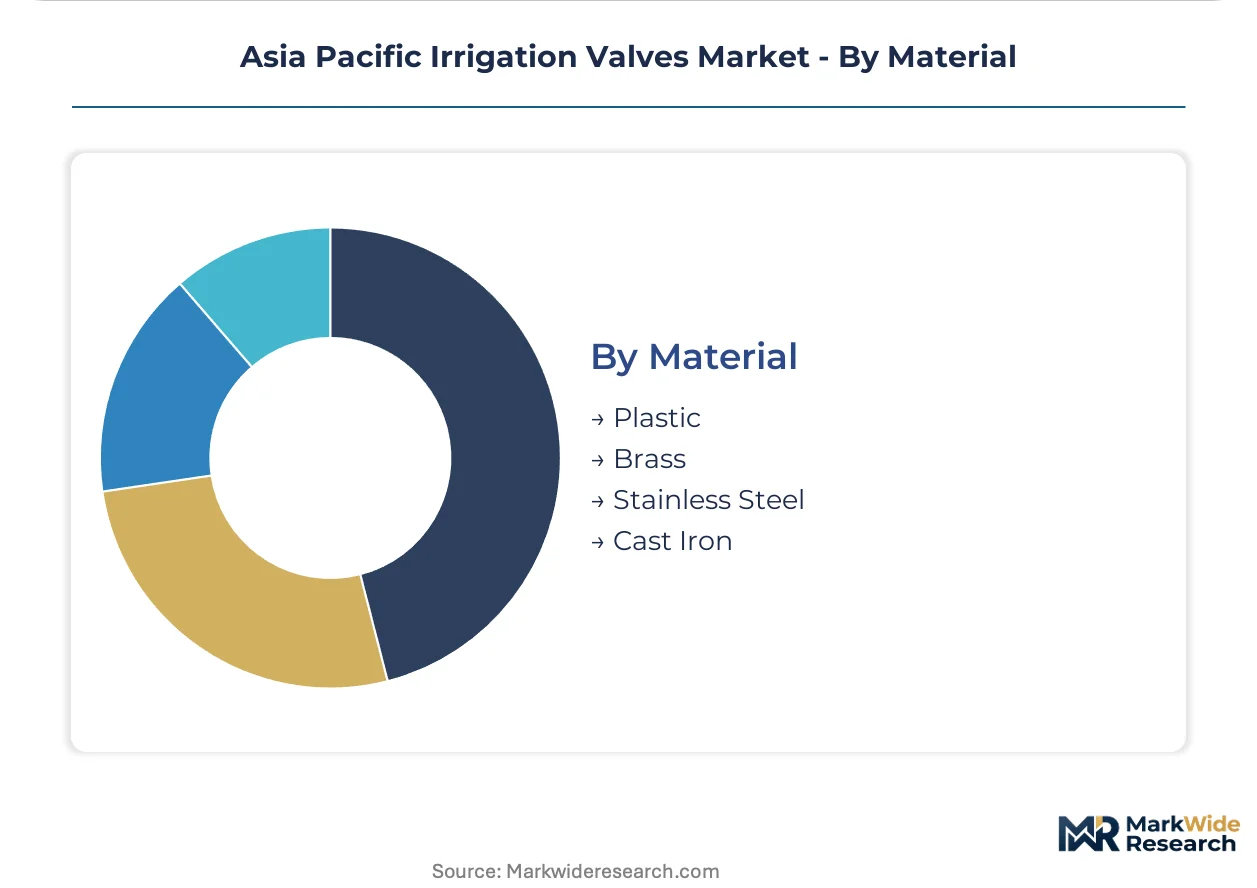
Corrosion resistance and cost trajectories determine material substitution patterns across saline and freshwater zones.
- Stainless Steel:Austenitic grades withstand saline groundwater and chemically treated water in coastal India and Southeast Asia. Nickel price volatility exposes manufacturers to margin compression when procurement cycles misalign with commodity spikes.
- Plastic:Polymer variants occupy volume-driven segments in China's mechanized field crop sectors. India's BIS mandates for UV degradation and impact resistance testing have consolidated procurement around certified suppliers with laboratory relationships.
- Brass:Copper-zinc alloys balance machinability with moderate corrosion resistance. Residential and light commercial applications in Japan's high-value horticulture zones specify these for mid-tier automation systems.
- Cast Iron:Ductile grades serve large-diameter static applications where weight and brittleness are acceptable tradeoffs. China's GB standards for agricultural machinery hydraulic interfaces influence flange specifications in this category.
Plastic materials lead by unit volume, with stainless steel gaining share fastest in coastal corrosion environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale irrigation infrastructure first scaled in Australia's Murray-Darling Basin during the post-war era, establishing the region's early dominance in pressurized distribution technology. This historical foundation now shapes divergent modernization trajectories across Asia Pacific's agricultural economies.
Australia
Cotton and rice growers in the Murray-Darling Basin drive replacement demand through water trading schemes that reward volumetric efficiency. The Murray-Darling Basin Authority enforces strict volumetric controls under the Water Act. Riverina and Barossa Valley viticulture cooperatives deploy smart controller retrofits for zone-based precision irrigation.
India
Maharashtra and Gujarat farming cooperatives accelerate valve replacement cycles amid tightening material standards. BIS mandates UV degradation and impact resistance testing for all plastic irrigation components. Uttar Pradesh and Karnataka sugarcane belts adopt buried drip-line systems requiring pressure-compensating configurations.
China
Mechanized field crop sectors in Heilongjiang and Xinjiang deploy large-diameter butterfly valves for mainline branching in canal distribution projects. GB standards for agricultural machinery hydraulic interfaces influence valve connector specifications. The Yangtze River Delta and Pearl River Delta concentrate demand for WiFi-enabled residential zone controllers.
Japan
High-value horticulture and commercial turf applications sustain premium equipment demand. METI water-saving equipment certification creates technical barriers protecting domestic precision agriculture suppliers. Kanto and Kansai regions concentrate METI-certified smart irrigation deployments for golf courses and municipal parks.
Vietnam
Rice intensification zones in the Mekong Delta lack automated zone-control infrastructure, creating first-mover opportunities for pressure-rated valve distributors. Portable configurations serve fragmented land tenure patterns that prevent permanent infrastructure investment. Delta farming cooperatives represent underpenetrated demand for electromechanical actuation systems.
Asia Pacific Irrigation Valves Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation integration capability, with R&D intensity determining tier placement in Australia's water-trading zones. The vendor base clusters around three strategic archetypes: Israeli drip-irrigation specialists with embedded valve expertise, Australian-smart-controller integrators, and Japanese precision-equipment certifiers. Dominant competitive moves include backward integration into sensor manufacturing and geographic licensing partnerships to bypass METI certification barriers.
Among Israeli-founded irrigation specialists, Netafim and Rivulis Irrigation exemplify the drip-line valve archetype through their embedded positions in subsurface distribution networks. Hunter Industries and Toro Company anchor the smart-controller integration tier, with the former representing R&D-intensive automation convergence and the latter exemplifying manufacturing-scale distribution across Southeast Asian plantation agriculture. These three names collectively span the premium-to-volume spectrum in Asia Pacific valve procurement.
| Leading Market Players |
|---|
| Hunter Industries |
| Netafim |
| Toro Company |
| Bermad CS Ltd |
| Nelson Irrigation |
| KSB Co. Ltd. |
| Rivulis Irrigation |
| Cla-Val Asia Pacific |
| TeeJet Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between METI-certified precision systems and BIS-compliant commodity hardware manifests in parallel supply chain configurations across Asia Pacific irrigation valve procurement. Premium-tier manufacturers anchor production in Japan and Australia where R&D intensity justifies value-based pricing, while volume suppliers cluster in China's industrial corridors to serve cost-sensitive mechanized field crop sectors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Asia Pacific irrigation valve procurement, with differentiation driven by automation integration depth and corrosion-resistant material grades. Stainless steel configurations for coastal saline zones in Tamil Nadu and Karnataka command substantial premiums over plastic variants serving China's Heilongjiang mechanized sectors. Price erosion runs through standard-tier butterfly valve segments where Chinese manufacturers compete on manufacturing scale. Smallholder cooperatives in Vietnam's Mekong Delta exhibit highest price sensitivity, while Australian water-trading zone operators demonstrate lowest sensitivity due to efficiency credit monetization.
Supply Chain Analysis
Single-source vulnerability sits with precision controller manufacturing concentrated among Australian and Israeli technology providers. Valve hardware production draws from China, India, and Japan, with electromechanical actuators and embedded flow sensors sourcing primarily from Japanese and South Korean component specialists. Raw material exposure centers on nickel price volatility affecting austenitic stainless steel grades for coastal corrosion environments. Distribution runs through agricultural equipment distributors in Australia, farming cooperative procurement consortia in India, and plantation estate technical teams across Indonesia and Malaysia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific irrigation valve procurement functions as a geographic-arbitrage play where Australian water-trading scheme incentives and India's BIS certification mandates create divergent cost structures and margin profiles across otherwise similar hardware categories.
For Market Incumbents: Acquire embedded sensor manufacturing capabilities to collapse the hardware-telemetry integration gap that Hunter Industries currently exploits in Australian viticulture. Consolidate laboratory relationships for BIS UV degradation certification to defend Maharashtra and Gujarat cooperative procurement volumes against emerging polymer specialists. Backward integration into corrosion-resistant alloy sourcing mitigates nickel price volatility exposure in coastal Indian and Southeast Asian markets. For New Entrants and Emerging Players: Fragmented land tenure in Vietnam's Mekong Delta rice intensification zones represents the most penetrable white-space target for portable electromechanical valve configurations. First-mover positioning in pressure-rated automated zone control addresses infrastructure gaps that permanent installation economics cannot serve. Partnership with Vietnamese agricultural extension services provides regulatory credibility and cooperative access without direct distribution investment. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification timelines fragment procurement scale across Australia's Water Act, India's BIS mandates, and Japan's METI requirements. Target acquisition archetypes include Israeli drip-irrigation specialists with embedded valve expertise and established testing laboratory relationships. Signal to watch is BIS enforcement intensity in Maharashtra sugarcane belts as indicator of certification-driven procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin from telemetry-hardware convergence demanded by Murray-Darling Basin volumetric reporting. |
| BIS Certification Laboratory Partnership | Secures procurement access to Maharashtra and Gujarat farming cooperatives under tightening material standards. |
| Geographic Licensing for METI Compliance | Bypasses technical import barriers protecting Japan's high-value horticulture and commercial turf segments. |
| Service Unbundling Capability Buildout | Addresses Indonesian and Malaysian plantation estate demand for separate zone mapping and calibration contracts. |
| Corrosion-Resistant Alloy Sourcing Control | Hedges nickel price volatility exposure in coastal India and Southeast Asia saline groundwater zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with irrigation equipment distributors, agricultural cooperative procurement managers, plantation estate technical directors, and precision agriculture system integrators with secondary validation against customs trade data, BIS certification registries, Murray-Darling Basin Authority water trading records, and METI equipment certification databases. Bottom-up installation estimates across product type, material, and installation method segments triangulated against top-down agricultural land use and irrigation infrastructure investment flows.
Segment-weighting approaches distributed value and volume across ball, butterfly, gate, and check valve configurations by automation readiness and durability requirements, with material-grade substitution patterns modeled for saline versus freshwater zones. CAGRs derived from replacement cycle acceleration under regulatory mandates and water pricing mechanism evolution across the projection horizon. Forecast inputs incorporated BIS enforcement trajectory in Indian plastic irrigation components and Murray-Darling Basin water buyback program intensity.
Underlying measurement precision varies by segment; Australia's water-trading zone demand carries tighter precision than Vietnam's Mekong Delta penetration estimates where land tenure fragmentation obscures installed base accounting. Forecasts reflect assumptions regarding regulatory enforcement continuity and commodity price corridor stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Tractor Rental Market