
 Europe Gluten-Free Breakfast Cereals Market | 2026-2036
Europe Gluten-Free Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gluten-Free Breakfast Cereals Market Foresight
Buckwheat and quinoa flour is consolidating as the preferred grain base for premium gluten-free flakes, displacing rice-dominant formulations that carry higher glycemic indexes. General Mills leverages its supply chain scale to secure certified gluten-free oat volumes from Scandinavian growers. Dr. Schär specializes in cross-contamination protocols that exceed baseline EU requirements. Nature's Path Foods anchors its positioning through organic-certified ingredient sourcing across its European portfolio.
Europe gluten-free breakfast cereals comprise processed grain formulations containing fewer than 20 parts per million of gluten, manufactured through segregated production lines with validated cleaning procedures to prevent cross-contact with wheat, barley, or rye. These products serve celiac patients, gluten-intolerant consumers, and health-seeking households seeking convenient morning nutrition without dietary triggers. Flakes and muesli categories capture the deepest margin pools due to higher price elasticity among established free-from buyers, while granola segments attract emerging consumers through indulgence-positioned flavor profiles. Rice and oat ingredient sources dominate current volume, though quinoa is gaining traction as a protein-differentiated input.
EFSA sets the scientific benchmark for gluten threshold definitions that national regulators transpose into enforceable product standards, while the EU Green Deal's Farm to Fork strategy pressures manufacturers to document sustainable sourcing across their ingredient supply chains. CE marking and national food safety authority inspections govern market access, with ECHA's emerging attention to pesticide residues in imported quinoa adding compliance complexity. Stakeholders must monitor how the EU's forthcoming packaging waste regulations reshape single-serve sachet economics relative to bulk formats.
Market Dynamics
EU Green Deal compliance requirements are forcing manufacturers to restructure sourcing documentation across their oat and quinoa supply chains. This regulatory pressure compounds with EFSA's tightening gluten threshold enforcement to create simultaneous sustainability and purity verification burdens.
Growth Catalysts
- Regulation (EU) No 1169/2011:Updated labeling mandates expand certified gluten-free shelf space in French and German retail channels, accelerating consumer trial among undiagnosed gluten-sensitive households.
- Buckwheat flour substitution:Lower glycemic index profiles attract diabetic and weight-management segments previously excluded from rice-dominant formulations.
- Urban health clusters:Concentrated celiac diagnosis rates in Paris, Berlin, and Milan metropolitan zones sustain premium pricing tolerance for validated cross-contamination protocols.
Market Restraints
- Certified oat supply concentration:Scandinavian growers control the majority of EU-sourced gluten-free oat volume, creating single-region dependency for flake and muesli production.
- Quinoa import pesticide scrutiny:ECHA's emerging residue monitoring adds testing layers and border delay risks for Andean-sourced protein-differentiated inputs.
- Rice base glycemic load:Nutritional positioning limitations constrain rice-dominant brands from accessing diabetic and keto-adjacent consumer segments.
Strategic Opportunities
- Spain and Italy underpenetration:Southern European markets exhibit lower free-from retail density relative to per-capita celiac prevalence, presenting whitespace for specialty distribution partnerships.
- CSRD-aligned sustainability reporting:Early Farm to Fork documentation adopters can differentiate through verified supply chain transparency ahead of mandatory disclosure timelines.
- Direct-to-subscription channels:Recurring delivery models bypass slotting fee barriers in consolidated retail and capture higher lifetime value from diagnosed celiac households.
Industry Challenges
- Segregated production line capex:Dedicated facility investments for validated cleaning protocols strain mid-tier manufacturers with sub-scale volume.
- Cross-contamination detection talent:Specialized analytical chemistry and supply chain audit expertise commands premium compensation in tight European labor markets.
- Multi-certification timeline compression:Simultaneous organic, gluten-free, and carbon footprint verifications extend product development cycles beyond conventional cereal innovation benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gluten-Free Breakfast Cereals Market |
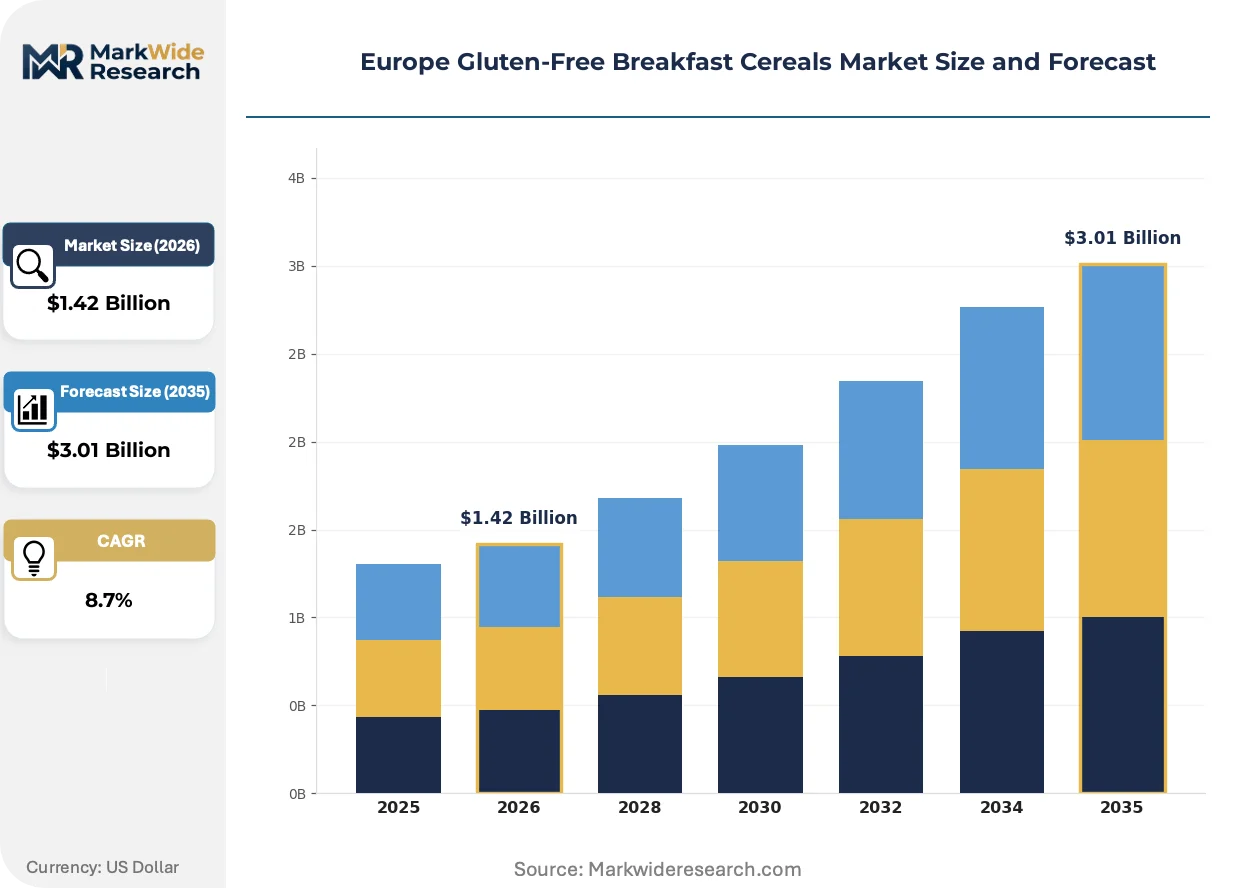
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola, Puffed Rice, Flakes, Muesli Ingredient Source: Rice, Oats, Quinoa, Corn Packaging Type: Bags, Boxes, Bulk Containers, Sachets Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Stores |
| Companies Covered | General Mills, Kellogg Company, Nestlé, Dr. Schär, The Hain Celestial Group, Kraft Heinz Company, Nature's Path Foods, Hero Group, Barilla, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gluten-Free Breakfast Cereals Market Shifts & Advancements
Processing technologies and verification protocols are rewriting competitive boundaries between commodity and premium tiers. Manufacturers now compete on traceability depth rather than formulation novelty alone.
Sprouted grain activation is rewriting nutrient bioavailability claims in premium positioning. German and Austrian health-food retailers are adopting these SKUs at twice the rate of conventional gluten-free lines. The technology is compressing margin pools for untreated grain formulations by establishing new baseline expectations among free-from loyalists.
EU Green Deal's Farm to Fork strategy is mandating ingredient origin documentation down to farm-level geolocation. This industrial consequence favors vertically integrated processors with captive sourcing relationships over contract-dependent competitors. Organic-certified suppliers in France and Benelux are responding fastest due to pre-existing audit infrastructure.
Subscription pantry consolidation is displacing intermittent grocery trial among diagnosed celiac households. Dedicated free-from e-commerce platforms in Germany and the UK are capturing pantry-automation spend that mainstream grocers cannot replicate. This behavioral shift concentrates most visibly among dual-income urban families with limited shopping time flexibility.
Europe Gluten-Free Breakfast Cereals Market Segmentation
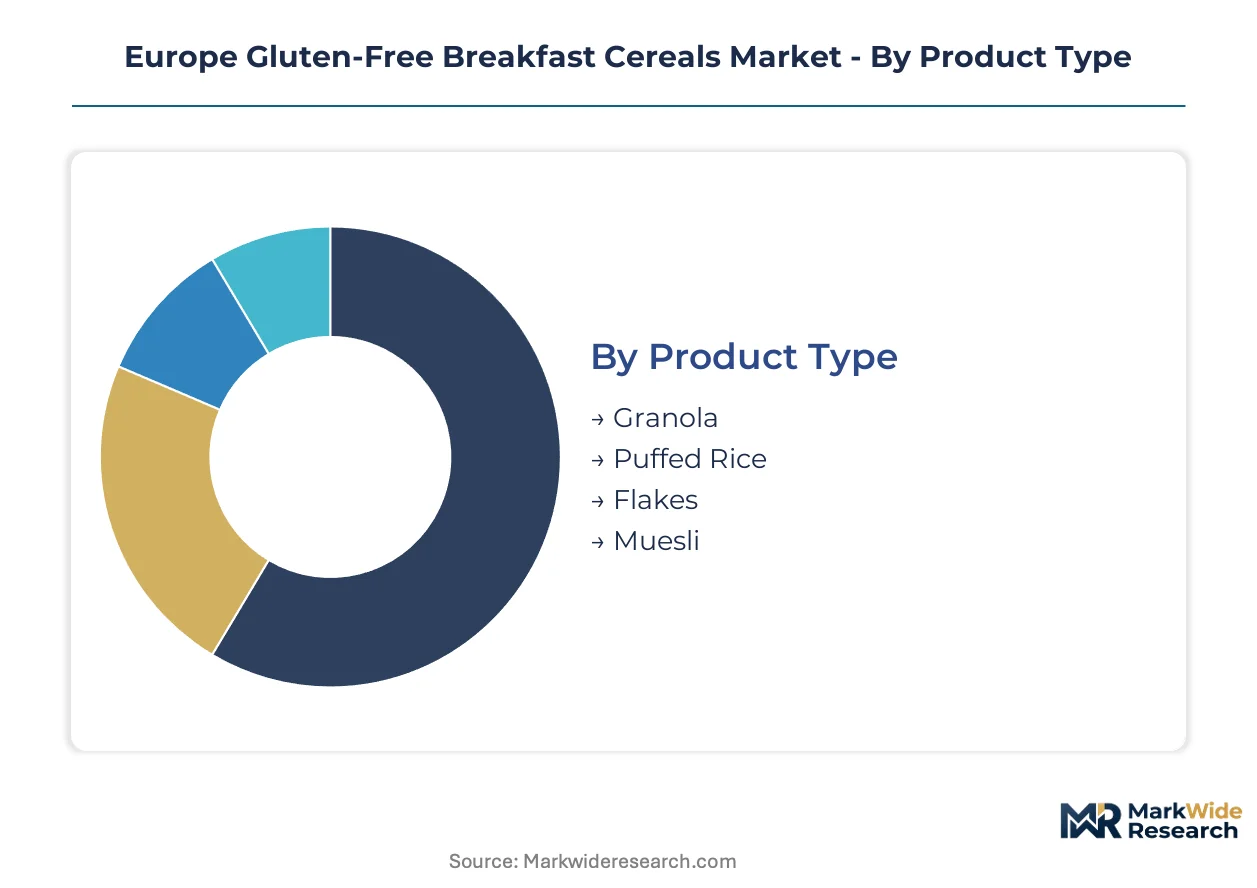
Segmentation in Europe's gluten-free breakfast cereals market reveals how capital deployment, regulatory compliance burdens, and distribution economics concentrate margin capture. Manufacturers must align production investments with the specific purity and packaging requirements of each segment cluster.
Product Type:
Capital intensity varies sharply across formats, with flake and muesli production requiring dedicated extrusion and drying lines that carry seven-figure equipment commitments.
- Flakes:Rolled and toasted grain formulations processed through validated extrusion systems. German and French retailers allocate premium shelf space to certified oat flakes, driven by EFSA labeling clarity that accelerates consumer trial among undiagnosed gluten-sensitive households.
- Muesli:Unbaked blends of flakes, seeds, and dried fruit requiring segregated mixing infrastructure. Paris and Berlin metropolitan clusters sustain pricing tolerance for validated cross-contamination protocols in this category.
- Granola:Baked clusters with binding agents; lower equipment barriers than flakes but higher ingredient complexity.
- Puffed Rice:Extrusion-puffed grains; commodity positioning with thinner margins and limited differentiation scope.
Most installed capacity flows through Flakes. Expansion is steepest in Muesli.
Ingredient Source:
Supply chain documentation requirements under the EU Green Deal's Farm to Fork strategy reshape competitive economics by input type.
- Oats:Scandinavian growers dominate EU-sourced gluten-free certified volume, creating single-region dependency. EFSA threshold enforcement and REACH-aligned pesticide documentation impose dual verification layers that favor processors with captive sourcing relationships.
- Quinoa:Andean-imported protein-differentiated input facing ECHA residue monitoring that adds border delay risks. Spanish and Italian markets show underpenetration relative to per-capita celiac prevalence, presenting whitespace for quinoa-based positioning.
- Rice:Commodity base with established supply chains but glycemic load constraints limiting diabetic segment access.
- Corn:Lower-cost alternative with weaker free-from premium positioning in Western European retail.
Procurement concentration centers on Oats. Quinoa is climbing the fastest as protein differentiation gains traction.
Packaging Type:
Format selection directly determines compliance exposure to forthcoming EU packaging waste regulations and per-unit economics.
- Boxes:Paperboard primary packaging with plastic liners; dominant in supermarket channels. Benelux and French organic-certified suppliers leverage pre-existing audit infrastructure to meet CSRD-aligned sustainability reporting demands for this format.
- Bags:Flexible film packaging; lower material cost but weaker shelf differentiation in health food retail.
- Sachets:Single-serve portions facing regulatory pressure under EU packaging waste rules; subscription pantry consolidation in Germany and the UK favors this format for recurring delivery models.
- Bulk Containers:Foodservice and zero-waste retail channels; limited branded margin capture.
Volume leadership sits with Boxes. Sachets are gaining share fastest through direct-to-subscription channels.
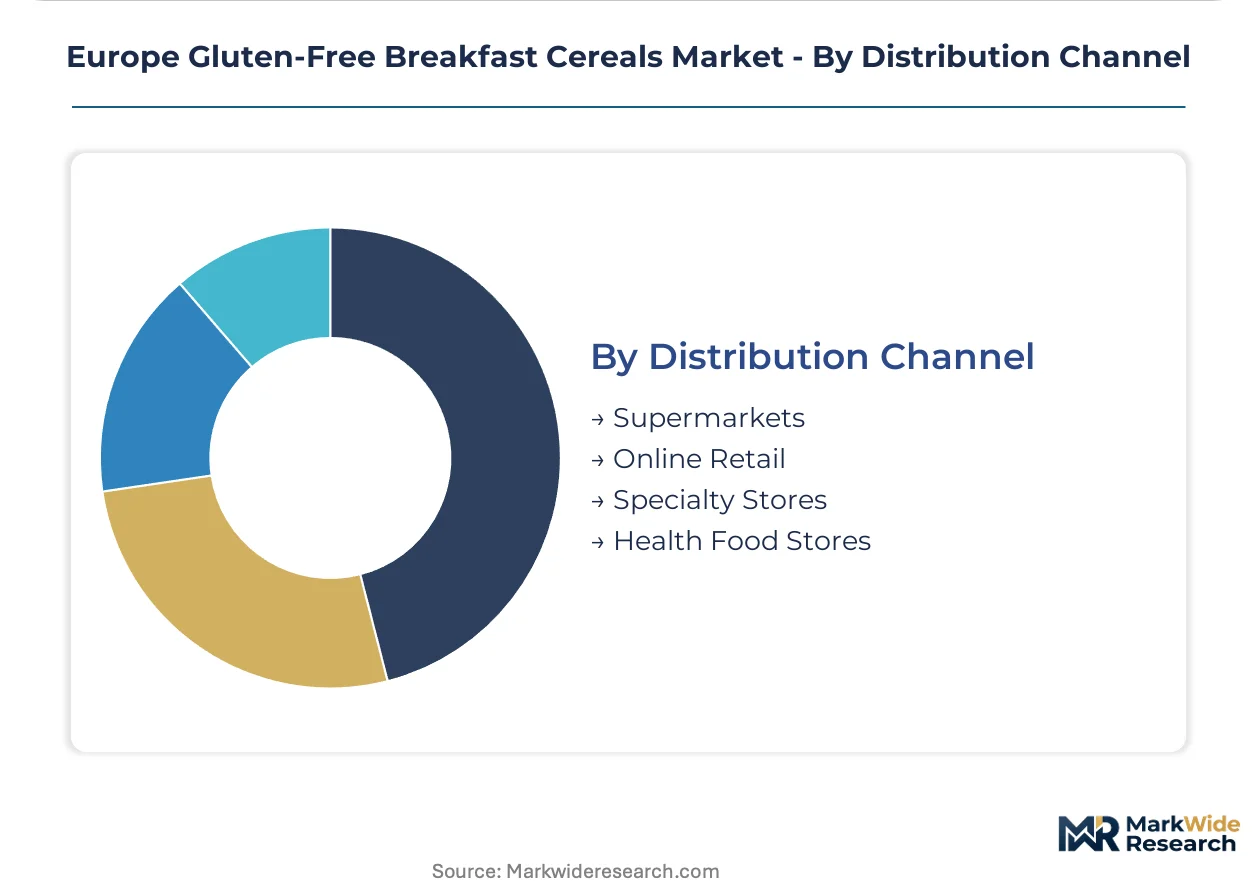
Distribution Channel:
Channel economics determine whether manufacturers absorb slotting fees or capture higher lifetime value through alternative pathways.
- Supermarkets:Consolidated retail with high barrier-to-entry through listing fees; French and German chains expanding certified gluten-free shelf space under Regulation (EU) No 1169/2011 labeling mandates.
- Online Retail:Dedicated free-from e-commerce platforms in Germany and the UK capture pantry-automation spend that mainstream grocers cannot replicate, particularly among dual-income urban families.
- Specialty Stores:Curated assortment with trained staff; Austrian and German health-food retailers adopting sprouted grain SKUs at accelerated rates.
- Health Food Stores:Independent channels with localized customer relationships; weaker scale but stronger margin retention for niche positioning.
Revenue concentration runs through Supermarkets. Online Retail shows the steepest expansion trajectory as subscription models consolidate diagnosed celiac household purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian gluten-free oat cultivation anchors the regional supply base, with Swedish and Finnish growers supplying certified grain to Western European processors. EFSA threshold enforcement and REACH-aligned pesticide documentation create dual compliance layers that favor established sourcing relationships. Paris, Berlin, and Milan metropolitan clusters sustain premium pricing tolerance for validated cross-contamination protocols.
Germany
Urban health clusters in Berlin and Munich drive demand for buckwheat and quinoa-based formulations among diagnosed celiac households. Regulation (EU) No 1169/2011 labeling mandates expand certified gluten-free shelf space across Rewe, Edeka, and Aldi Süd chains. Bavaria-based specialty maltsters and extrusion processors supply validated oat flakes to domestic and export markets.
France
Paris metropolitan concentration sustains pricing tolerance for premium muesli and sprouted grain SKUs among dual-income professional households. ANSM and DGCCRF enforcement of EFSA gluten thresholds tightens purity verification for oat-based imports. Île-de-France organic-certified suppliers leverage pre-existing audit infrastructure to meet CSRD-aligned sustainability reporting demands.
United Kingdom
Subscription pantry consolidation concentrates among London and Manchester urban families seeking recurring free-from cereal delivery. FSA transposition of EU labeling standards maintains threshold alignment post-Brexit. Dedicated free-from e-commerce platforms capture pantry-automation spend that mainstream grocers struggle to replicate.
Italy
Underpenetrated free-from retail density relative to per-capita celiac prevalence creates whitespace for quinoa-based positioning in Rome and Milan. Farm to Fork strategy pressures manufacturers to document sustainable sourcing for Andean-imported protein inputs. Emilia-Romagna and Lombardy health-food retailers accelerate adoption of sprouted grain activation technologies.
Spain
Lower certified gluten-free shelf allocation in Madrid and Barcelona contrasts with rising celiac diagnosis rates among pediatric populations. ECHA emerging residue monitoring adds border delay risks for quinoa shipments through Valencia and Barcelona ports. Andalusian organic grain cooperatives develop captive oat supply relationships with Portuguese and French processors.
Europe Gluten-Free Breakfast Cereals Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers secure dedicated extrusion and segregated mixing infrastructure. The vendor base stratifies across three tiers: multinational CPG conglomerates with supply chain scale, European specialty free-from specialists with validated cross-contamination protocols, and emerging organic-certified challengers with Farm to Fork documentation advantages. M&A activity concentrates on Scandinavian oat sourcing relationships and Spanish distribution networks. Portfolio diversification into sprouted grain and protein-differentiated quinoa lines represents the second dominant competitive vector.
Among North American CPG conglomerates, General Mills and Kellogg Company exemplify scale-driven archetypes leveraging supply chain breadth for certified oat volume security. European specialists Dr. Schär and Nature's Path Foods occupy positions defined by cross-contamination protocol depth and organic-certified ingredient sourcing respectively. These five entities represent the competitive spectrum from mass-market penetration to premium free-from positioning.
| Leading Market Players |
|---|
| General Mills |
| Kellogg Company |
| Nestlé |
| Dr. Schär |
| The Hain Celestial Group |
| Kraft Heinz Company |
| Nature's Path Foods |
| Hero Group |
| Barilla |
| Others |
Supply & Pricing Matrix
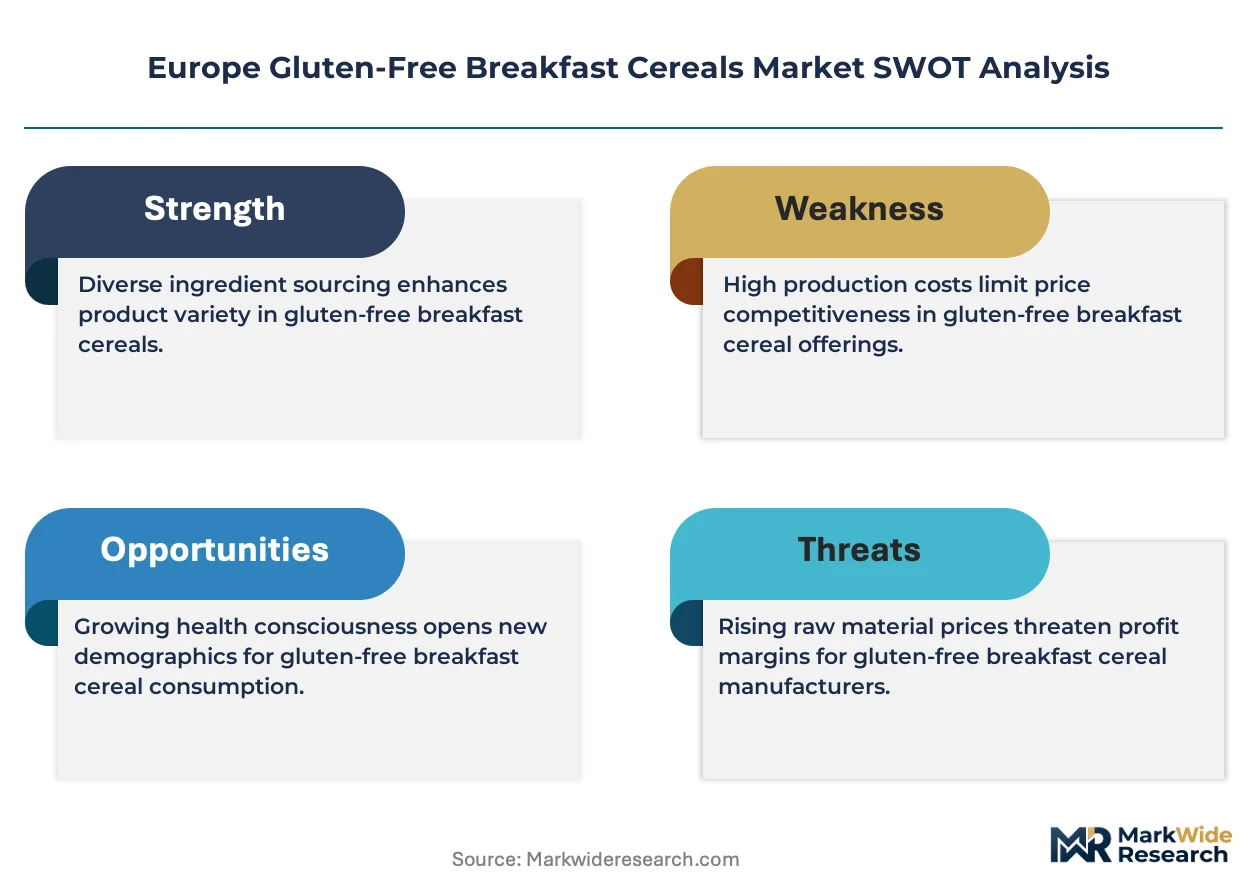
Diagnosed celiac households in Paris, Berlin, and Milan sustain premium pricing tolerance for validated cross-contamination protocols, anchoring a three-tier pricing structure across premium, standard, and economy levels. Scandinavian oat supply concentration and EU Green Deal documentation burdens compress margins for mid-tier processors lacking captive sourcing relationships.
Pricing Analysis
Certified gluten-free oat premiums pass through directly from Scandinavian growers to finished flake and muesli price points. Price differentiation rests on EFSA validation tier and organic certification status, with sprouted grain activation commanding the widest spreads. Cost compression in rice-dominant formulations is intensifying because diabetic and keto-adjacent segments reject high-glycemic bases. Undiagnosed gluten-sensitive trialists exhibit highest price sensitivity; diagnosed celiac households show lowest elasticity due to pantry-automation subscription lock-in.
Supply Chain Analysis
Baltic Sea freight corridors and overland trucking from Sweden and Finland concentrate logistics cost exposure for Western European processors. Raw material flows draw from Scandinavian oats, Andean quinoa, and Asian rice. Single-region dependency for certified gluten-free oat volume creates structural vulnerability to harvest variability and climate events. Distribution runs through consolidated supermarket chains in France and Germany, with direct-to-subscription channels capturing growing share among urban dual-income families.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sprouted grain activation and protein-differentiated quinoa lines are displacing untreated rice formulations among free-from loyalists. Premium specifications now dominate purchasing criteria as pantry-automation subscriptions reduce price sensitivity among core celiac segments.
For Market Incumbents: Extend validated cross-contamination protocol investments into Spanish and Italian distribution partnerships before specialty entrants capture whitespace. Secure captive oat supply relationships with Scandinavian growers to defend against General Mills' supply chain scale advantages. Prioritize CSRD-aligned Farm to Fork documentation ahead of mandatory disclosure timelines. For New Entrants and Emerging Players: Regulation (EU) No 1169/2011 in France and Germany opens a window for certified gluten-free shelf space expansion among undiagnosed gluten-sensitive households. Target Madrid and Barcelona retail channels where free-from density lags per-capita celiac prevalence. Pursue direct-to-subscription go-to-market models that bypass Rewe and Edeka slotting fee barriers. For Investors and Strategic Acquirers: European specialty free-from CPG conglomerates are the most active acquirer in this space, prioritizing Scandinavian oat sourcing relationships and Spanish distribution networks. Mid-term viability hinges on portfolio diversification into sprouted grain and quinoa protein lines. Watch ECHA pesticide residue enforcement intensity for Andean quinoa as inflection signal for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Oat Supply Securement | Scandinavian grower relationships insulate processors from EFSA purity verification bottlenecks. |
| Sprouted Grain SKU Launch | German and Austrian health-food retailers adopt activation technologies at accelerated rates. |
| Direct-to-Subscription Channel Buildout | Recurring delivery models capture higher lifetime value from diagnosed celiac households in London and Manchester. |
| Farm to Fork Documentation Investment | Early CSRD-aligned sustainability reporting adopters differentiate ahead of mandatory disclosure timelines. |
| Southern European Distribution Partnership | Spain and Italy underpenetration presents whitespace for quinoa-based positioning relative to celiac prevalence. |
Research Methodology
Coverage spans Western Europe, Scandinavia, and Southern Europe, with primary inputs from each region combined with secondary validation. Interviews with category buyers at Rewe and Edeka, supply planners at oat processors, regulatory affairs leads at free-from specialists, and procurement managers at Andean quinoa importers were triangulated against EFSA threshold documentation, EU customs trade data, Nielsen retail audit figures, and SEC filings from North American CPG parents. Bottom-up volume modeling and top-down value reconciliation were cross-checked for consistency.
Rate-of-change decomposition across the analysis window segments volume and value by product type, ingredient source, packaging format, and distribution channel. CAGRs were derived from installed capacity trajectories, retail shelf space expansion rates, and diagnosed celiac household formation patterns. Modeled inputs include EFSA enforcement intensity indices, EU Green Deal compliance cost curves, and subscription pantry consolidation velocity among urban professional families.
Revisions become necessary when ECHA escalates quinoa pesticide monitoring, when EU packaging waste regulations reshape single-serve economics, or when Scandinavian harvest failures disrupt certified oat flows. Forecasts reflect documented assumptions about regulatory enforcement pacing and consumer pantry-automation adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Sea Moss Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Zhacai Market
Specialty Foods
Miso Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Moringa Products Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Free-From Food Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Global Truffle Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
US Jam Jelly and Preserves Market