
 United Kingdom Gluten Free Foods and Beverages Market | 2026-2036
United Kingdom Gluten Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Gluten Free Foods and Beverages Market Analytics
Supermarket shelf space allocation is narrowing as discounters and premium grocers redraw category boundaries for free-from products. Warburtons Ltd. sustains its position through dedicated gluten-free bakery facilities in the English Midlands. Dr. Schär AG leverages continental European manufacturing scale to supply British retailers with extended shelf-life lines. Glebe Farm Foods Ltd. anchors its competitive stance through domestic oat milling and controlled supply chains.
Gluten free foods and beverages comprise products formulated with alternative grains, starches, and hydrocolloids to achieve sub-20 ppm gluten content under Codex Alimentarius standards, serving celiac patients, gluten-intolerant consumers, and lifestyle buyers seeking digestive wellness. Bakery items occupy the deepest margin pools due to ingredient complexity and premium positioning, while online sales channels represent the fastest-growing application dimension as direct-to-consumer subscriptions reshape replenishment patterns. Household end users dominate volume, though cafés and restaurants are expanding gluten-free menu integration to capture dietary-specific dining occasions.
The Food Standards Agency governs gluten-free claims through quantified threshold enforcement, while Trading Standards coordinates local authority compliance testing across UK jurisdictions. BSI PAS 220 and BRCGS certification schemes shape manufacturer access to major retail listings through audited allergen control protocols. Stakeholders must monitor evolving front-of-pack labeling mandates and the potential alignment of domestic standards with post-EU regulatory frameworks.
Market Dynamics
Supermarket shelf space reallocation is compressing margins for mid-tier gluten-free brands while discounters and premium grocers redraw category boundaries across England and Scotland. The Food Standards Agency's strict gluten threshold labeling enforcement creates compliance cost tiers that favor scaled manufacturers with dedicated allergen-control facilities.
Growth Catalysts
- Coeliac UK diagnostic campaigns:Rising celiac disease identification rates in the National Health Service are expanding the clinical patient base requiring certified gluten-free products.
- BSI PAS 220 certification expansion:Major retail chains now mandate audited allergen control protocols for supplier onboarding, filtering out smaller non-compliant producers.
- London health-conscious consumption clusters:Premium positioning uptake concentrates in the South East where disposable income supports higher price points for digestive wellness products.
Market Restraints
- Alternative grain input volatility:Domestic oat and buckwheat supply fluctuations create margin pressure for bakery segment producers dependent on UK-sourced raw materials.
- Continental European manufacturing dominance:Dr. Schär AG and similar scaled producers control extended shelf-life production capacity, limiting British manufacturer expansion.
- Substitution threat from low-FODMAP:Irritable bowel syndrome consumers increasingly pivot to broader dietary protocols that reduce dedicated gluten-free product reliance.
Strategic Opportunities
- Scottish Highlands underpenetrated retail:Dedicated free-from aisle expansion remains incomplete in northern Scotland beyond Aberdeen and Inverness urban centers.
- Direct-to-consumer subscription channels:Replenishment pattern reshaping through online platforms bypasses traditional supermarket margin structures entirely.
- Café and restaurant menu integration:Dietary-specific dining occasion capture presents volume growth outside household retail channels.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise in hydrocolloid and alternative starch blending commands premium wages in the English Midlands production cluster.
- BRCGS certification timeline compression:Six-to-twelve-month audit cycles delay new product launches and retail listing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Gluten Free Foods and Beverages Market |
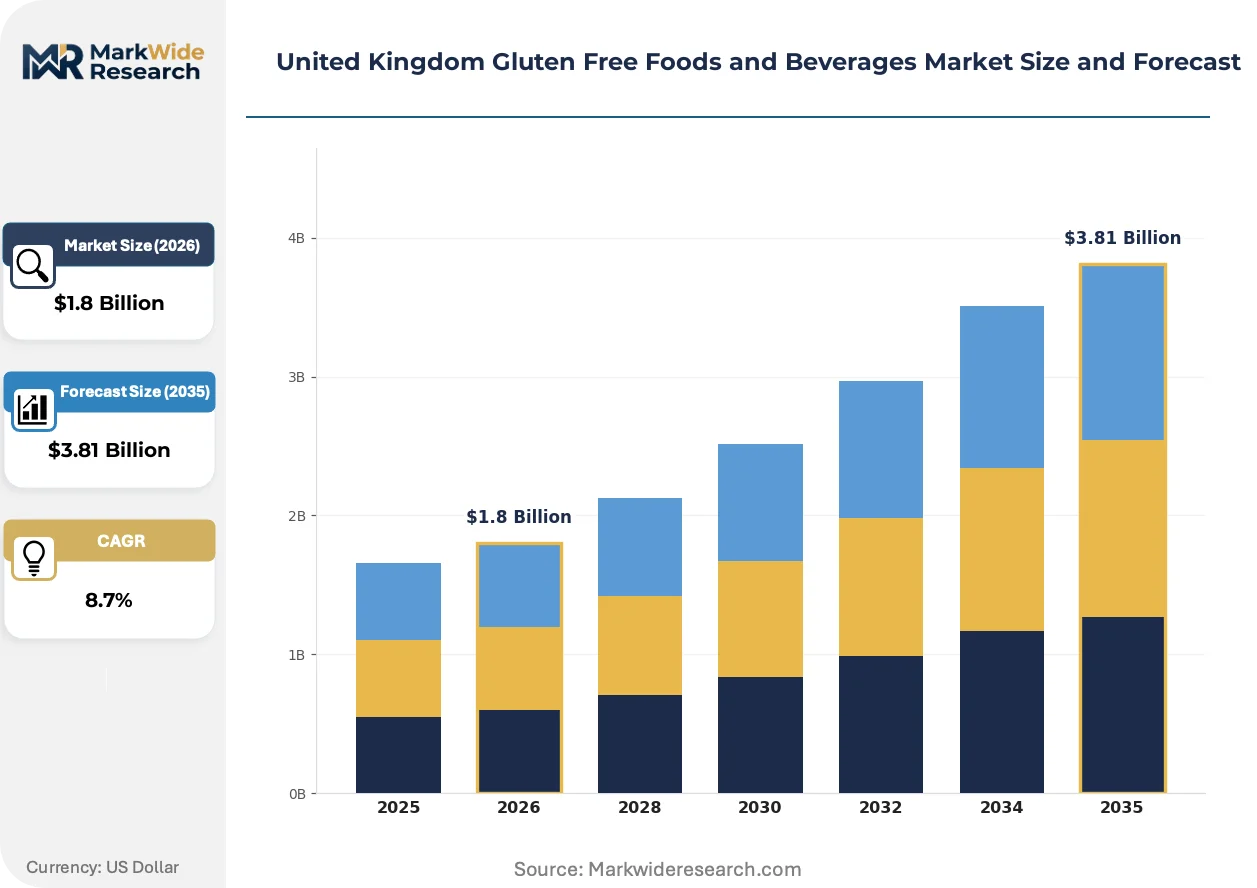
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Bakery Items Application: Household, Food Service, Retail, Online Sales End User: Individuals, Restaurants, Hotels, Cafés Packaging Type: Bags, Boxes, Containers, Tins |
| Companies Covered | Genius Foods Ltd., Warburtons Ltd., Dr. Schär AG, Nairns Oatcakes Ltd., Co-operative Group Ltd., Creative Nature Ltd., Glebe Farm Foods Ltd., Finsbury Food Group Plc, Prima Foods Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Gluten Free Foods and Beverages Market Evolving Landscape
Enzymatic gluten degradation technologies are disrupting traditional formulation approaches while regulatory labeling mandates tighten and consumer purchasing patterns fragment across channel types. These forces collectively reshape competitive positioning in the British gluten-free sector.
Protease enzyme treatments that break down gluten proteins in conventional wheat flour are rendering obsolete the historical reliance on rice, corn, and tapioca starch bases. Early-stage bakery manufacturers in Manchester and Bristol pilot facilities are adopting these processes to improve texture profiles. The technology is rendering obsolete the capacity constraints of dedicated gluten-free production lines by enabling shared equipment utilization with conventional products.
The Food Standards Agency's front-of-pack labeling mandate consultation is forcing reformulation investments across mid-tier manufacturers. Quantified threshold enforcement now requires sub-20 ppm verification through accredited laboratory testing for all gluten-free claims. Bakery items face the highest compliance burden due to cross-contamination risks in shared production environments.
Subscription-based replenishment models are capturing pantry-stocking occasions previously dominated by supermarket weekly shops. Direct-to-consumer platforms bypass retail margin stacking and build proprietary consumer data assets. This shift concentrates in London and the South East where delivery logistics density supports viable unit economics.
United Kingdom Gluten Free Foods and Beverages Market Segmentation
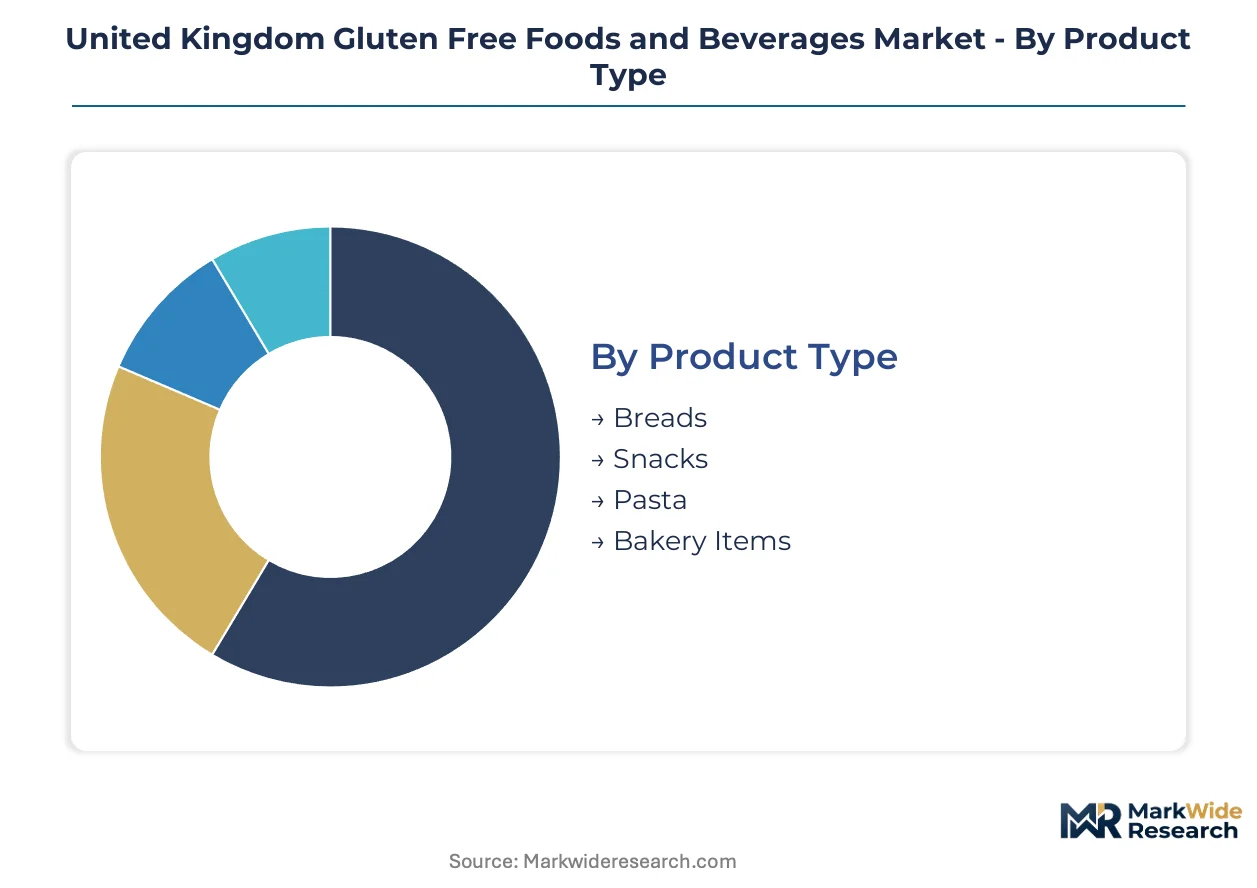
Segmentation in the United Kingdom gluten-free sector reveals how purchasing velocity, consumption context, and channel economics fragment demand. Manufacturers must align formulation investments with the distinct technical and logistical requirements of each slice.
Product Type:
Inventory velocity varies sharply across this category, with ambient-stable lines turning monthly while frozen bakery formats cycle quarterly.
- Breads:Formulated with rice flour, tapioca starch, and hydrocolloid binders to achieve sub-20 ppm gluten thresholds under Food Standards Agency protocols. Daily consumption habits in London and the South East sustain volume, though price compression from supermarket own-label ranges constrains branded margin expansion.
- Bakery Items:Cakes, muffins, and pastries command the deepest margin pools due to ingredient complexity and premium positioning. Manchester and Bristol production clusters serve this segment through dedicated allergen-control facilities that satisfy BRCGS certification mandates for retail listing access.
- Snacks:Crackers, biscuits, and cereal bars leverage extended shelf-life formulations from continental European suppliers. Discounter channel growth in England drives volume concentration at economy price points.
- Pasta:Corn and rice flour extrusions dominate, with Scottish retail penetration lagging behind English supermarket distribution density. Supply chains source alternative grains from domestic oat millers where available.
Breads anchors the volume base while Bakery Items gains share at the steepest rate.
Application:
Channel cost structures diverge significantly, with direct-to-consumer platforms capturing margin otherwise absorbed by retail listing fees and promotional spend.
- Household:Weekly replenishment patterns dominate volume, concentrated in London health-conscious consumption clusters where disposable income supports premium digestive wellness positioning. Warburtons Ltd. and Dr. Schär AG compete intensely for pantry-stocking occasions through supermarket dedicated free-from aisles.
- Online Sales:Subscription-based models reshape replenishment economics by bypassing traditional retail margin stacking entirely. Delivery logistics density in the South East supports viable unit economics that northern England and Scotland cannot yet match.
- Retail:Supermarket shelf space reallocation compresses margins for mid-tier brands as discounters and premium grocers redraw category boundaries across England and Scotland.
- Food Service:Institutional procurement operates on quarterly contract cycles with stringent allergen documentation requirements that favor scaled manufacturers with audited BSI PAS 220 protocols.
Household consumption anchors the volume base while Online Sales expands most quickly through platform-based replenishment capture.
End User:
Customer technical sophistication spans from medically diagnosed celiac patients requiring certified products to lifestyle buyers seeking occasional digestive wellness.
- Individuals:Medically diagnosed celiac disease patients and gluten-intolerant consumers drive certified product demand through strict adherence to Food Standards Agency labeling thresholds. Coeliac UK diagnostic campaigns expand this clinical base through National Health Service identification programs.
- Cafés:Independent coffee shops and bakery chains in London integrate gluten-free options to capture dietary-specific dining occasions. Menu integration requires supplier flexibility on minimum order quantities and delivery frequency.
- Restaurants:Full-service dining establishments face cross-contamination liability risks that drive preference for pre-certified ingredient suppliers with documented allergen control protocols.
- Hotels:Hospitality procurement consolidates through group purchasing organizations that prioritize extended shelf-life lines and consolidated delivery schedules over product innovation.
Individuals anchor the volume base while Cafés gains share at the steepest rate through dietary-specific occasion capture.
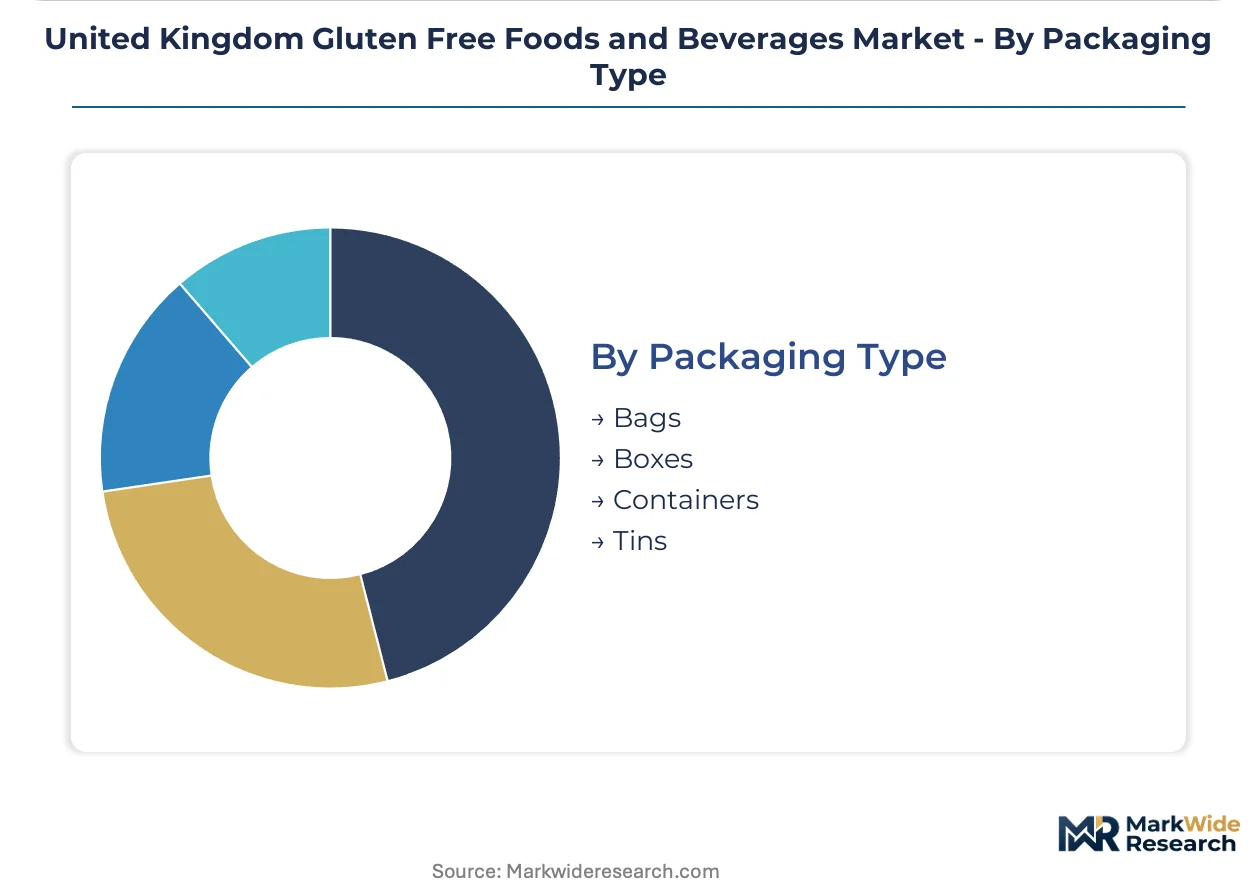
Packaging Type:
Material selection trade-offs between shelf-life extension, sustainability credentials, and supply chain handling durability shape procurement decisions.
- Bags:Flexible film laminates dominate ambient snack and bread formats, offering cost efficiency and lightweight logistics. Recycling infrastructure limitations in England create regulatory pressure for material transition.
- Boxes:Corrugated secondary packaging protects fragile bakery items through distribution networks. Premium positioning in the South East favors board with sustainability certifications.
- Containers:Rigid plastics serve wet and refrigerated formats where moisture barrier properties are essential. Scottish retail penetration remains incomplete for chilled gluten-free lines.
- Tins:Metal packaging preserves extended shelf-life for export-oriented production and emergency pantry stocking, though material cost volatility constrains adoption.
Bags anchor the volume base while Boxes gains share at the steepest rate through premium positioning and e-commerce shipping protection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in London and the South East while Scottish retail penetration lags significantly behind English distribution density. The Food Standards Agency's uniform gluten threshold labeling applies across all UK jurisdictions, yet regional consumption clusters fragment demand patterns. Sub-regional manufacturing capabilities and retail infrastructure create distinct competitive terrains across the British market.
London and South East
Health-conscious consumption clusters and elevated disposable income sustain premium positioning for digestive wellness products. The Food Standards Agency enforces strict sub-20 ppm gluten threshold verification through accredited laboratory testing. Dedicated free-from aisles in premium grocers concentrate in Greater London and commuter belt supermarkets.
Midlands
Dedicated gluten-free bakery facilities anchor production capacity for national retail distribution networks. BSI PAS 220 certification schemes filter supplier access to major retail listings through audited allergen control protocols. Birmingham and Nottingham production clusters serve as manufacturing hubs for ambient-stable bread and snack formats.
North England
Supermarket shelf space reallocation compresses margins for mid-tier brands as discounters redraw category boundaries. Trading Standards coordinates local authority compliance testing across Greater Manchester and Yorkshire jurisdictions. Manchester pilot facilities adopt enzymatic gluten degradation technologies to improve texture profiles.
Scotland
Scottish Highlands retail penetration remains incomplete beyond Aberdeen and Inverness urban centers. The Food Standards Agency's gluten-free claims governance applies uniformly, yet distribution logistics density limits chilled line availability. Domestic oat milling at Scottish facilities supports controlled supply chain strategies for bakery segment producers.
Wales
Health service diagnostic campaign effects from Coeliac UK expand the clinical patient base requiring certified products in Cardiff and Swansea corridors. Trading Standards Wales enforces the same quantified threshold requirements as English jurisdictions. Bristol production clusters across the border supply Welsh retail channels with extended shelf-life formulations.
United Kingdom Gluten Free Foods and Beverages Market Competitive Landscape
Integrated bakery conglomerates and continental European specialists split the market between domestic manufacturing scale and import-dependent shelf-life extension. The vendor base concentrates around three strategic archetypes: scaled manufacturers with dedicated allergen-control facilities, oat-milling domestic specialists, and continental suppliers leveraging extended shelf-life production capacity. Competitive moves center on BRCGS certification timeline management and direct-to-consumer channel bypass strategies.
Within the scaled manufacturing tier, Warburtons Ltd. and Dr. Schär AG occupy positions representing divergent geographic sourcing strategies, while Glebe Farm Foods Ltd. exemplifies the domestic oat-milling specialist archetype. Warburtons Ltd. anchors its stance through English Midlands production infrastructure. Dr. Schär AG represents continental European manufacturing scale applied to British retail supply. Glebe Farm Foods Ltd. sits within the controlled supply chain segment through captive oat milling operations.
| Leading Market Players |
|---|
| Genius Foods Ltd. |
| Warburtons Ltd. |
| Dr. Schär AG |
| Nairns Oatcakes Ltd. |
| Co-operative Group Ltd. |
| Creative Nature Ltd. |
| Glebe Farm Foods Ltd. |
| Finsbury Food Group Plc |
| Prima Foods Ltd. |
| Others |
Value Network & Pricing Analysis
English Channel freight corridors from continental European manufacturing hubs into British distribution centers impose cost dynamics that concentrate supply power among scaled importers while fragmenting domestic producers into price-taker positions across premium and economy tiers.
Pricing Analysis
The customization-premium spread between certified gluten-free bakery items and standard free-from staples separates Warburtons Ltd. and Dr. Schär AG pricing from discounter own-label ranges. Certification grade under Food Standards Agency protocols and geographic delivery cost from Midlands versus continental facilities drive this price differentiation. Cost compression in the mid-tier intensifies as supermarket shelf space reallocation favors scaled suppliers. Household consumers in London and the South East exhibit lowest price sensitivity, while Scottish and northern English buyers gravitate toward economy positioning.
Supply Chain Analysis
Tariff exposure between continental European Union suppliers and post-Brexit British import regimes dominates supply chain risk assessment for extended shelf-life formulations. Manufacturing concentrates in Germany, Italy, and Austria for Dr. Schär AG and similar specialists, while domestic production clusters in the English Midlands serve ambient bread and snack formats. Raw material dependencies center on rice flour, tapioca starch, and hydrocolloid binders sourced through Rotterdam and Hamburg ports. Distribution runs through supermarket dedicated free-from aisles and direct-to-consumer subscription platforms in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom gluten-free sector exhibits cyclical recovery characteristics as Coeliac UK diagnostic campaigns through the National Health Service expand the clinical patient base requiring certified products, rebuilding demand momentum after pandemic-era supply disruptions.
For Market Incumbents: Entrench market position through BRCGS certification timeline compression and dedicated allergen-control facility investment in the English Midlands. Substitution threat from low-FODMAP dietary protocols demands formulation diversification beyond gluten-free positioning. Backward integration into domestic oat milling secures margin control against alternative grain input volatility. For New Entrants and Emerging Players: Scottish Highlands retail corridors beyond Aberdeen and Inverness represent the most penetrable entry point for dedicated free-from aisle expansion. Direct-to-consumer subscription channels in northern England bypass supermarket margin stacking entirely. Partner with Manchester and Bristol pilot facilities adopting enzymatic gluten degradation technologies for shared production infrastructure access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized gluten-free production lines and dormant BRCGS certifications. Long-term viability hinges on regulatory alignment between domestic Food Standards Agency protocols and evolving post-EU frameworks. Monitor front-of-pack labeling mandate consultations as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| BRCGS Certification Investment | Audited allergen control protocols unlock major retail listing access across England and Scotland. |
| Direct-to-Consumer Platform Launch | Subscription models bypass supermarket margin stacking and build proprietary London consumer data assets. |
| Domestic Oat Milling Integration | Captive supply chains at Glebe Farm Foods Ltd. demonstrate margin defense against continental import dependency. |
| Enzymatic Technology Adoption | Protease treatments enable shared equipment utilization, collapsing dedicated gluten-free production line constraints. |
| Scottish Distribution Expansion | Aberdeen and Inverness urban centers anchor northern retail penetration before Highlands corridor development. |
Research Methodology
Operator-level perspectives from bakery production managers, supermarket category buyers, Food Standards Agency compliance officers, and Coeliac UK patient advocacy leads anchored the qualitative base for this study. Primary interview data combined with secondary validation from Food Standards Agency labeling consultations, Trading Standards enforcement reports, BRCGS certification databases, and Nielsen retail audit data. Bottom-up volume triangulation against top-down value estimates calibrated segment-level outputs.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling product type segmentation alongside application channel economics and end-user technical sophistication dimensions. CAGRs derived from patient identification rate trajectories, shelf space allocation trends, and channel shift velocity parameters. Enzymatic technology adoption curves and subscription platform penetration rates informed bakery and online sales segment trajectories respectively.
Practitioners should monitor Food Standards Agency front-of-pack labeling mandate outcomes and Coeliac UK diagnostic campaign intensity for early signals of forecast revision. Alternative grain commodity price volatility and continental European manufacturing capacity expansion present material assumption risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
North America Free from Food Market