
 Gluten Free Tortillas Market | 2026-2036
Gluten Free Tortillas Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Tortillas Market Intelligence
Advanced flour blending technology, which combines multiple non-wheat sources like cassava and chickpea, is narrowing the sensory gap between gluten-free and traditional wheat tortillas. Siete Family Foods leverages grain-free formulations to target paleo and health-focused consumers. Mission Foods sustains its market position through extensive distribution networks. Gruma SAB de CV competes on a global scale by utilizing its corn milling expertise.
Gluten-free tortillas are flatbreads made from flours devoid of wheat, barley, or rye proteins, such as corn masa, rice, or cassava. These products are specifically formulated to maintain pliability and a shelf life of at least 30 days without using gluten. Their primary commercial purpose is to serve as a safe bread alternative for individuals with celiac disease or gluten sensitivity. Corn-based tortillas maintain a dominant share by product type, while cassava and almond flour options are expanding rapidly.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate strict gluten-free labeling standards. These rules, defining products with less than 20 parts per million of gluten, govern market access and build consumer trust. Compliance with certifications like those from the Gluten-Free Certification Organization (GFCO) is also a key differentiator. Manufacturers must ultimately decide whether to prioritize allergen-free positioning or compete on taste and texture parity with conventional products.
Market Dynamics
The convergence of consumer demand for functional, health-oriented foods and advances in food science is the central force shaping the market. This dynamic pushes manufacturers to innovate beyond simple gluten avoidance, focusing on improved nutritional profiles and achieving sensory parity with traditional wheat tortillas.
Growth Catalysts
- Strict Labeling Mandates:Regulations from the U.S. FDA and European EFSA create a protected category for certified products, building consumer trust and justifying premium pricing for verified gluten-free items.
- Foodservice Sector Expansion:Quick-service restaurants and institutional cafeterias are incorporating gluten-free tortillas to cater to dietary needs and offer versatile, allergen-aware menu items like wraps and bowls.
- Alternative Flour Innovation:Advances in processing non-traditional flours like cassava, chickpea, and almond are improving the taste, texture, and nutritional value of tortillas, broadening their appeal beyond medical necessity.
Market Restraints
- Higher Input Costs:The price volatility and supply chain complexity of specialty flours such as almond and cassava result in a higher production cost compared to conventional wheat tortillas.
- Shelf-Life and Pliability:Formulating tortillas that maintain flexibility and resist cracking over a 30-day shelf life without gluten's binding properties remains a significant technical and R&D hurdle.
- Substitution from Adjacent Categories:Health-conscious consumers seeking low-carbohydrate options often turn to substitutes like lettuce wraps or rice bowls, bypassing the tortilla category entirely.
Strategic Opportunities
- Market Entry in Latin America:Countries like Brazil and Mexico, with a strong corn tortilla tradition, present an opportunity for introducing value-added, certified gluten-free options targeting urban, health-aware consumer segments.
- Functional Food Fortification:An opportunity exists to enrich tortillas with proteins, fibers, and vitamins, positioning them not just as gluten-free but as nutritionally enhanced functional foods.
- Expansion into Meal Kit Services:Partnering with subscription-based meal kit companies provides a direct channel to home cooks seeking convenient, health-conscious, and allergen-safe meal components.
Industry Challenges
- Certification Complexity:Achieving and maintaining certifications like those from the Gluten-Free Certification Organization (GFCO) requires stringent, costly production protocols and dedicated, allergen-free facilities.
- Cross-Contamination Risk Management:Ensuring a gluten-free supply chain from farm to finished product demands rigorous supplier vetting and segregated processing lines to prevent accidental contamination, a constant operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Tortillas Market |
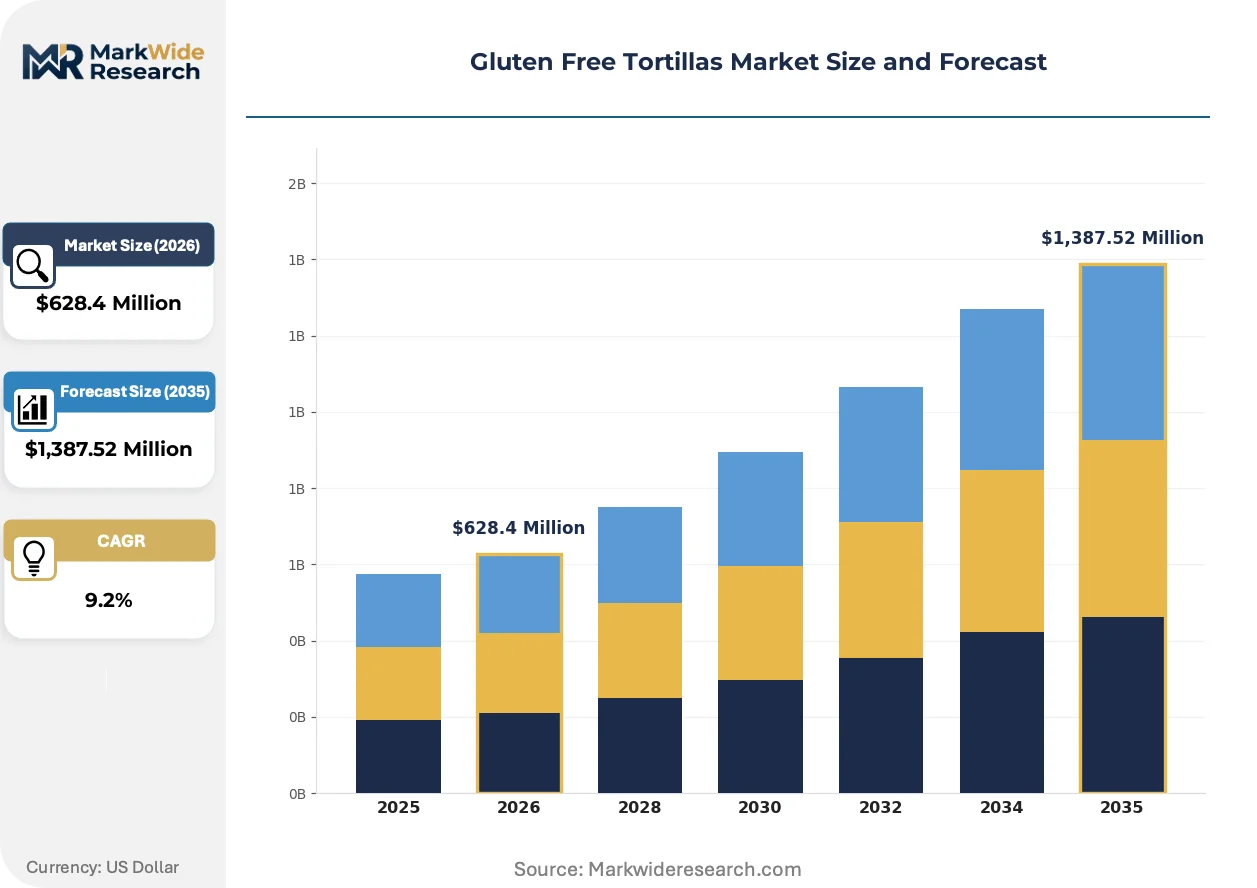
| Market Size in 2026 | $628.4 Million |
| Market Size in 2035 | $1,387.52 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Rice, Cassava, Almond Flour, Chickpea, Quinoa Form: Soft, Hard, Flat, Rolled, Mini, Flavored Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores, Health Food Stores, Foodservice Customer Type: Health-conscious Consumers, Celiac Patients, Vegan Consumers, Fitness Enthusiasts, Parents, Dieticians |
| Companies Covered | Mission Foods, La Tortilla Factory, Siete Family Foods, General Mills, Gruma SAB de CV, Azteca Foods, Ole Mexican Foods, Udi's Gluten Free, Canyon Bakehouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Tortillas Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from products for medical necessity to mainstream lifestyle choices. This shift is propelled by ingredient science that closes the sensory gap with traditional wheat products, recasting gluten-free as a premium attribute for a wider audience.
Advanced flour blending combines multiple non-wheat sources like cassava, almond, and chickpea using precise hydration and binding agents. Health-focused consumer segments and foodservice chains are rapidly adopting these next-generation tortillas for their superior texture and nutritional benefits. This technology is rendering obsolete the perception that gluten-free products are inherently inferior in taste and pliability to their conventional counterparts.
New front-of-pack nutritional labeling schemes, such as the Nutri-Score system in several European Union countries, are becoming more prevalent. These regulations compel manufacturers to improve the overall health profile of their products, beyond just being gluten-free, to achieve favorable ratings. Products high in sodium or low in fiber are most affected, prompting reformulation efforts in the cassava and corn-based tortilla segments.
Consumers are increasingly purchasing gluten-free products through specialized health food stores and direct-to-consumer online platforms rather than exclusively at large supermarkets. This channel shift disrupts the traditional distribution model dominated by major retailers and gives smaller, niche brands direct access to their target audience. This trend is most visible in metropolitan areas of the United States and Germany, where consumer density supports a diverse ecosystem of specialty food retailers.
Gluten Free Tortillas Market Segmentation
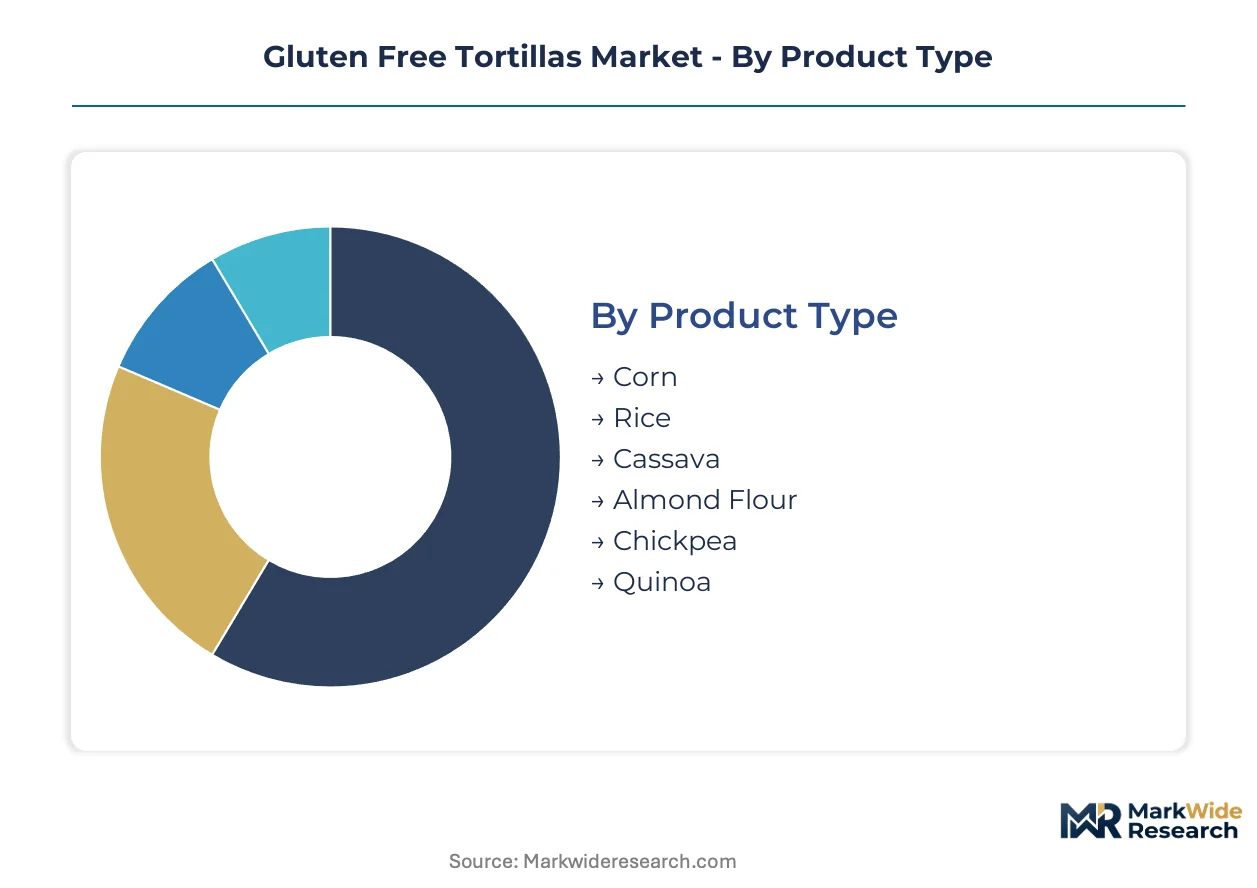
The Gluten Free Tortillas Market exhibits diverse segmentation, reflecting evolving consumer preferences and technological advancements. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively. This granular view highlights areas of established demand and emerging growth opportunities.
Product Type:
The product type segment spans mature staple ingredients and rapidly emerging alternative flours.
- Corn:These tortillas are traditionally made from masa harina, offering a distinct flavor and texture profile. Corn-based varieties maintain a dominant share, particularly in the United States and Mexico, driven by cultural heritage and established consumer acceptance.
- Cassava:Derived from the cassava root, these tortillas provide a neutral flavor and excellent pliability, making them highly versatile. Demand for cassava tortillas is expanding quickly in health-conscious markets like Germany, driven by paleo and grain-free diet trends.
- Rice:Rice flour tortillas offer a mild taste and soft texture, appealing to consumers seeking a neutral base for various fillings.
- Almond Flour:Almond flour tortillas cater to low-carbohydrate and keto diets, offering a higher protein and fiber content.
- Chickpea:Chickpea flour tortillas are gaining traction for their nutritional profile, including protein and fiber, attracting health-focused consumers.
- Quinoa:Quinoa-based options provide a complete protein source, appealing to consumers prioritizing nutritional density in their diet.
Corn retains volume leadership; cassava holds the steepest expansion curve.
Form:
Product form dictates consumer usage and convenience, influencing purchasing decisions across various applications.
- Soft:Soft tortillas are designed for flexibility and pliability, making them ideal for wraps, tacos, and burritos. This form dominates household consumption and foodservice applications due to its versatility.
- Flavored:These tortillas incorporate herbs, spices, or vegetable purees to enhance taste and offer culinary variety. Flavored options are gaining traction among consumers seeking novel taste experiences and premium products in urban markets.
- Hard:Hard tortillas, often fried or baked, provide a crispy texture suitable for tostadas or as a base for loaded dishes.
- Flat:Flat tortillas serve as a foundational element for various meals, including pizzas, quesadillas, and open-faced sandwiches.
- Rolled:Rolled tortillas are pre-formed for convenience, often used in snack applications or ready-to-eat meal kits.
- Mini:Mini tortillas cater to snack-sized portions and children's meals, offering versatility for appetizers and small bites.
Consumer preference guides the development of diverse forms, with soft and flavored options leading innovation.
Distribution Channel:
The distribution channel highlights how gluten-free tortillas reach end-consumers, reflecting market accessibility and consumer shopping habits.
- Supermarkets:Supermarkets represent the primary distribution channel, offering broad product visibility and convenience for mainstream consumers. Major retailers in the United States and European Union countries stock a wide range of gluten-free tortilla brands.
- Online Retailers:E-commerce platforms provide direct access to niche brands and specialized gluten-free products, catering to consumers seeking specific dietary options. This channel is expanding rapidly, particularly in metropolitan areas of Germany.
- Specialty Stores:These stores focus on organic, natural, and dietary-specific products, serving consumers with specific health requirements.
- Convenience Stores:Convenience stores offer limited selections, primarily targeting impulse purchases and immediate consumption needs.
- Health Food Stores:Health food stores cater to a dedicated segment of health-conscious buyers seeking premium and certified gluten-free products.
- Foodservice:The foodservice segment includes restaurants, cafes, and institutional settings, integrating gluten-free tortillas into diverse menu offerings.
Broad market penetration relies on channels like supermarkets, while direct-to-consumer models through online retailers gain traction.
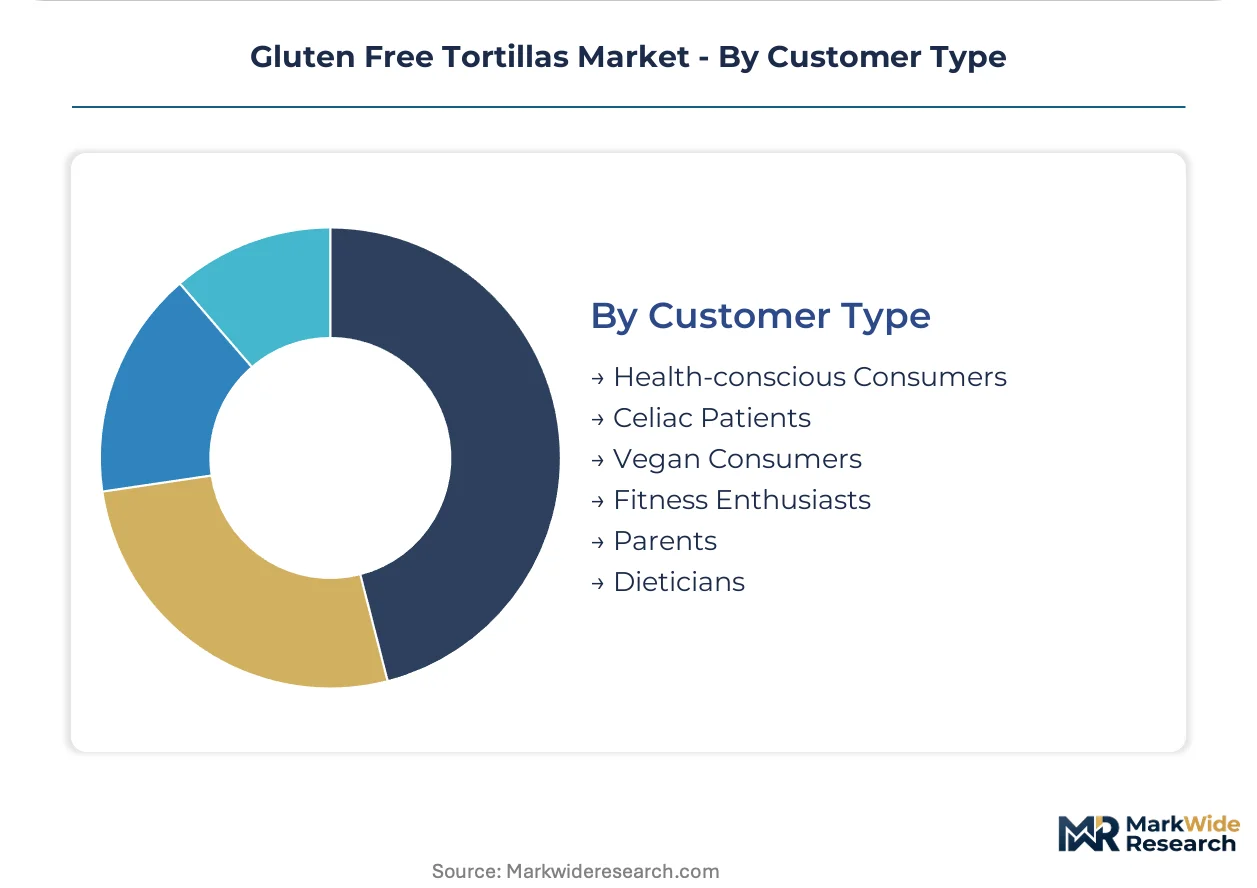
Customer Type:
This segmentation reveals the diverse motivations behind purchasing gluten-free tortillas, from medical necessity to lifestyle choices.
- Celiac Patients:Individuals diagnosed with celiac disease require strict adherence to gluten-free diets to manage their health. This group represents the foundational demand for certified gluten-free products, prioritizing safety and compliance with FDA and EFSA standards.
- Health-conscious Consumers:This broad group actively seeks products perceived as healthier, often including gluten-free options as part of a balanced diet. Demand from these consumers drives innovation in nutritional profiles and clean label ingredients in countries like the United States.
- Vegan Consumers:Vegan consumers choose gluten-free tortillas made without animal products, aligning with their plant-based dietary principles.
- Fitness Enthusiasts:These consumers often seek gluten-free options for their perceived health benefits, aiding in digestion or specific fitness goals.
- Parents:Parents purchase gluten-free tortillas for children with sensitivities or as part of family dietary preferences.
- Dieticians:Dieticians recommend gluten-free tortillas as a safe and versatile option for patients with specific dietary requirements or allergies.
The market caters to specific dietary needs, with Celiac Patients representing the core demographic and Health-conscious Consumers expanding the addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers and individuals with specific dietary needs drive demand for gluten-free tortillas across diverse global markets. The market's expansion reflects a broader shift towards functional foods and allergen-aware options. Manufacturers adapt product formulations and distribution strategies to cater to these evolving consumer preferences.
United States
Demand for gluten-free tortillas stems from a large base of health-conscious consumers and celiac patients. The U.S. Food and Drug Administration (FDA) mandates strict labeling standards for gluten-free products, building consumer trust. Major metropolitan areas like Los Angeles and New York City exhibit high adoption rates, supporting diverse product offerings.
Germany
Germany experiences significant demand for cassava-based gluten-free tortillas, driven by paleo and grain-free diet trends. The European Food Safety Authority (EFSA) sets stringent gluten-free standards, ensuring product safety and market access. Berlin and Munich are key urban centers where online retailers and specialty stores thrive, serving niche consumer segments.
Mexico
Mexico's market for gluten-free tortillas is influenced by its strong traditional corn tortilla consumption and a growing interest in healthier alternatives. Local food safety regulations ensure product quality, though specific gluten-free mandates are emerging. Mexico City and Guadalajara represent urban hubs where value-added, certified gluten-free options are gaining traction.
Brazil
Brazil presents a strategic opportunity for gluten-free tortilla manufacturers, particularly among urban, health-aware consumer segments. ANVISA, Brazil's health surveillance agency, oversees food product regulations, including allergen labeling. São Paulo and Rio de Janeiro are primary markets for introducing nutritionally enhanced and certified gluten-free products.
Italy
Italian consumers increasingly seek gluten-free alternatives, driven by a rising awareness of celiac disease and general wellness trends. The European Food Safety Authority (EFSA) guidelines are strictly enforced, requiring clear labeling for gluten-free items. Milan and Rome are key distribution points for specialty stores and health food retailers offering diverse gluten-free tortilla options.
Gluten Free Tortillas Market Key Industry Players
Channel-controlling players compete with product-specialist players across the gluten-free tortilla market. The market exhibits a tiered structure, with large food conglomerates alongside agile niche brands. Strategic archetypes include diversified food manufacturers, grain-free innovators, and traditional tortilla producers adapting their portfolios. Companies focus on strategic partnerships and portfolio diversification to maintain market relevance.
Within the diversified food manufacturer archetype, Mission Foods, a major global player, sustains its market position through extensive distribution networks. Gruma SAB de CV, a Mexico-based food company, anchors the traditional tortilla segment by leveraging its corn milling expertise and global scale. Siete Family Foods, a US-based brand, exemplifies grain-free innovation, targeting paleo and health-focused consumers with its specialized formulations. These companies collectively illustrate the varied approaches to market penetration and consumer engagement within the gluten-free tortilla sector.
| Leading Market Players |
|---|
| Mission Foods |
| La Tortilla Factory |
| Siete Family Foods |
| General Mills |
| Gruma SAB de CV |
| Azteca Foods |
| Ole Mexican Foods |
| Udi's Gluten Free |
| Canyon Bakehouse |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialty flour milling capacity drives both supplier negotiation power and premium pricing for alternative gluten-free tortilla ingredients. This utilization dynamic directly impacts manufacturer margins and product availability across key markets.
Pricing Analysis
Cost-plus contract patterns with corn masa indexation govern pricing for traditional gluten-free tortillas, especially in Latin American markets. Price differentiation stems from alternative flour types like almond or chickpea and stringent GFCO certification levels. Pricing softness reflects competition from adjacent low-carb substitutes. Health-conscious lifestyle consumers exhibit higher price sensitivity than celiac patients prioritizing safety.
Supply Chain Analysis
Extended payment terms for specialty flour suppliers characterize the gluten-free tortilla supply chain, impacting manufacturer working capital. Geographic supply concentration for key inputs centers on Mexico for corn masa and Brazil for cassava flour. Raw material dependencies include corn, cassava, and almond flours. Commodity price volatility for these agricultural inputs presents a significant structural risk. Distribution runs through a hybrid model, combining broad supermarket reach with direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free tortilla market is at a platform-economics inflection, driven by the expanding integration of products into subscription-based meal kit ecosystems. This shift demands new approaches to consumer engagement and product delivery.
For Market Incumbents: Harden existing distribution networks by securing long-term contracts with major supermarket chains and foodservice distributors. Invest in advanced R&D to improve product pliability and shelf-life, countering the threat from alternative low-carb wraps. Diversify flour sourcing to mitigate commodity price volatility for specialty ingredients. Leverage brand equity through targeted allergen-free certification investments.
For New Entrants and Emerging Players: Establish a beachhead in the functional food segment by fortifying tortillas with protein and fiber for health-aware consumers. Target urban health food stores and direct-to-consumer online channels in Germany and the United States. Penetrate the burgeoning meal kit market through strategic partnerships. Offer unique flavor profiles to differentiate from established brands.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among niche brands specializing in certified allergen-free formulations with strong online direct-to-consumer sales. Long-term viability over a ten-year window favors companies with proprietary flour blending technologies. Acquisition targets should include innovators in cassava and chickpea flour applications. Watch for regulatory harmonization across international markets as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Flour Blending R&D | Enhances product sensory attributes, closing the gap with traditional wheat tortillas for broader consumer appeal. |
| Functional Fortification Integration | Positions products as nutritionally superior, appealing to health-conscious consumers beyond gluten avoidance. |
| Direct-to-Consumer Channel Expansion | Provides niche brands with direct access to target audiences, bypassing traditional retail gatekeepers. |
| Foodservice Partnership Development | Expands market reach into quick-service restaurants and institutional settings for versatile menu options. |
| Certification Standard Compliance | Builds consumer trust and ensures market access by meeting strict FDA and EFSA gluten-free mandates. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings and quantitative models. Interviews included food scientists, product development leads, retail category managers, and foodservice procurement specialists. Secondary sources comprised FDA and EFSA regulatory documents, trade association reports, company annual filings, and academic food science journals. This approach enabled robust bottom-up and top-down triangulation.
The calibration approach involved segmenting the market across product type, form, distribution channel, customer type, and regional consumption patterns over the projection horizon. Compound annual growth rates were derived from historical data extrapolation and expert consensus. Key inputs included alternative flour price trends and celiac disease prevalence rates across major geographies.
Sensitivities concentrate around ingredient supply disruptions and evolving dietary trend shifts. Forecasts reflect documented assumptions regarding market dynamics and technological advancements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market