
 Allergen Free Food Market | 2026-2036
Allergen Free Food Market Size, Share, and Industry Trends Forecast 2026-2036
Allergen Free Food Market Analysis
EU FIC Regulation 1169/2011 is restructuring how food manufacturers validate ingredient chains and factory segregation protocols. Nestlé leverages its global procurement network to secure dedicated allergen-free production lines across multiple facilities. Dr. Schär specializes in certified gluten-free bakery products, anchoring its reputation through controlled supply chains and medical community endorsement. General Mills competes by extending mainstream brand recognition into allergen-free variants, occupying shelf space that specialty players cannot match.
Allergen free food denotes products formulated without specific proteins capable of triggering immune responses, typically manufactured under HACCP-aligned protocols with validated cleaning procedures between production runs and analytical testing below detection thresholds. The gluten-free product type dominates retail volume due to celiac disease prevalence and consumer-perceived wellness benefits, though nut-free formulations command premium positioning in school and childcare channels. Online retail distribution channels are expanding fastest among end user segments, as individuals and parents of allergic children prioritize direct-to-home replenishment with transparent ingredient documentation over supermarket browsing.
The FDA enforces Food Allergen Labeling and Consumer Protection Act requirements in the United States, while EFSA provides scientific opinions that inform EU-wide allergen thresholds and precautionary labeling standards. Health Canada and the PMRA coordinate domestic allergen management with import inspection protocols, creating compliance complexity for cross-border suppliers. Stakeholders must monitor evolving threshold science and emerging legume allergen classifications to anticipate reformulation mandates before regulatory deadlines crystallize.
Market Dynamics
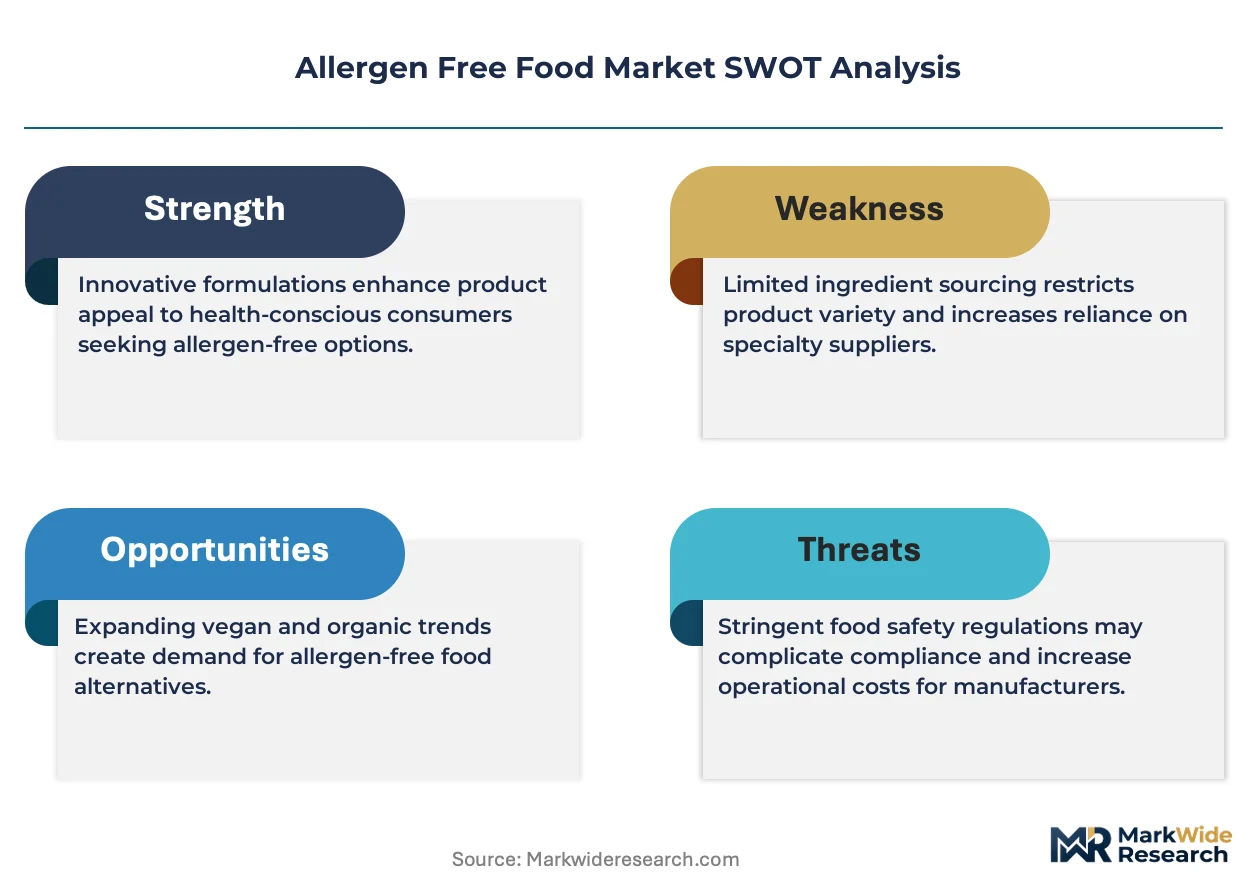
EU FIC Regulation 1169/2011 is compressing reformulation timelines across packaged food portfolios, forcing manufacturers to rebuild supply chains around validated allergen segregation protocols rather than precautionary labeling alone.
Growth Catalysts
- Pediatric allergy protocols:Schools across the United States and Canada are mandating nut-free meal environments, creating institutional procurement volumes that specialty manufacturers cannot serve through retail channels alone.
- REACH-aligned chemical disclosure:European manufacturers are extending ingredient transparency requirements into allergen testing methodologies, accelerating adoption of ELISA and PCR detection systems at facility entry points.
- E-commerce replenishment:Parents of children with multiple allergies are subscribing to direct-to-home delivery with batch-tested documentation, bypassing supermarket shelf uncertainty.
Market Restraints
- Dedicated facility scarcity:Gluten-free production requires physical separation from wheat-processing lines, limiting contract manufacturing options to a concentrated base of third-party bakeries in Germany and Italy.
- Input cost volatility:Rice and tapioca starch prices fluctuate with climate patterns in Thailand and Vietnam, compressing margins on reformulated pasta and snack products.
- Threshold science uncertainty:EFSA has not finalized quantitative action levels for tree nut residues, forcing manufacturers to maintain detection capabilities below current analytical confidence intervals.
Strategic Opportunities
- Legume protein expansion:Chickpea and lentil flour formulations are penetrating the free-from bakery segment in France and Spain, where Mediterranean dietary patterns reduce consumer resistance to unfamiliar textures.
- Foodservice channel integration:Hospital and airline catering contracts are specifying allergen-free meal guarantees, creating volume commitments that justify dedicated production line investments.
- Dual carbon alignment:EU Green Deal procurement criteria are favoring domestic allergen-free ingredient sourcing over imported alternatives, rewarding localized supply chain reconstruction.
Industry Challenges
- Cross-contamination validation:HACCP-aligned cleaning protocols require documented swab testing between production runs, extending changeover times and reducing effective capacity at multi-allergen facilities.
- Ingredient provenance verification:Suppliers of natural flavors and colorants rarely maintain allergen-specific segregation, forcing downstream manufacturers to audit tier-two and tier-three vendors directly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergen Free Food Market |
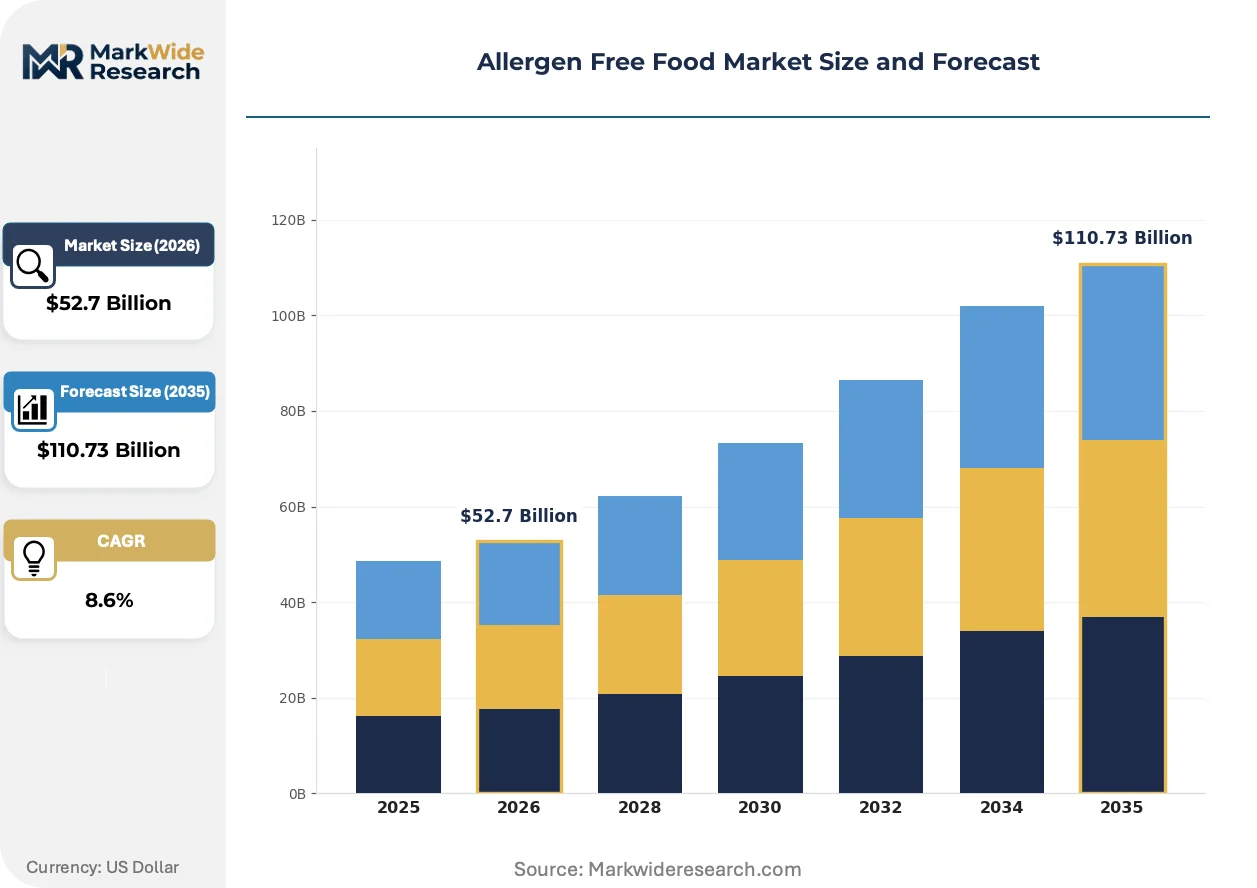
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Egg-Free End User: Individuals, Schools, Restaurants, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Service Type: Consultation, Delivery, Subscription Services, Custom Orders |
| Companies Covered | Nestlé, Danone, General Mills, Kraft Heinz, Enjoy Life Foods, Dr. Schär, The Hain Celestial Group, Conagra Brands, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergen Free Food Market Emerging Trajectories
Mass spectrometry detection methods are displacing immunoassay testing at ingredient intake points, enabling simultaneous screening for multiple allergen classes rather than sequential protein-specific assays.
Enzymatic protein hydrolysis is converging with precision fermentation to produce hypoallergenic dairy analogues. Infant formula manufacturers in the Netherlands are adopting these processes to serve diagnosed cow's milk protein allergy cases. This convergence is compressing the performance gap between clinical nutrition products and mainstream retail alternatives, blurring channel boundaries.
EFSA's pending opinion on precautionary labeling thresholds is forcing reformulation investments ahead of formal mandate publication. Manufacturers are removing "may contain" statements from packaging to avoid consumer deselection, accepting higher compliance costs for competitive positioning. The snack and confectionery categories are most affected, with Swiss and Belgian producers accelerating cleaning validation programs.
Subscription-based replenishment is displacing conventional supermarket purchasing among households with multiple allergic members. Parents are prioritizing batch-traceable inventory with digital certificates over in-store price comparison. This pattern is most visible in suburban United States markets where direct delivery density supports weekly replenishment cycles without freight surcharges.
Allergen Free Food Market Segmentation
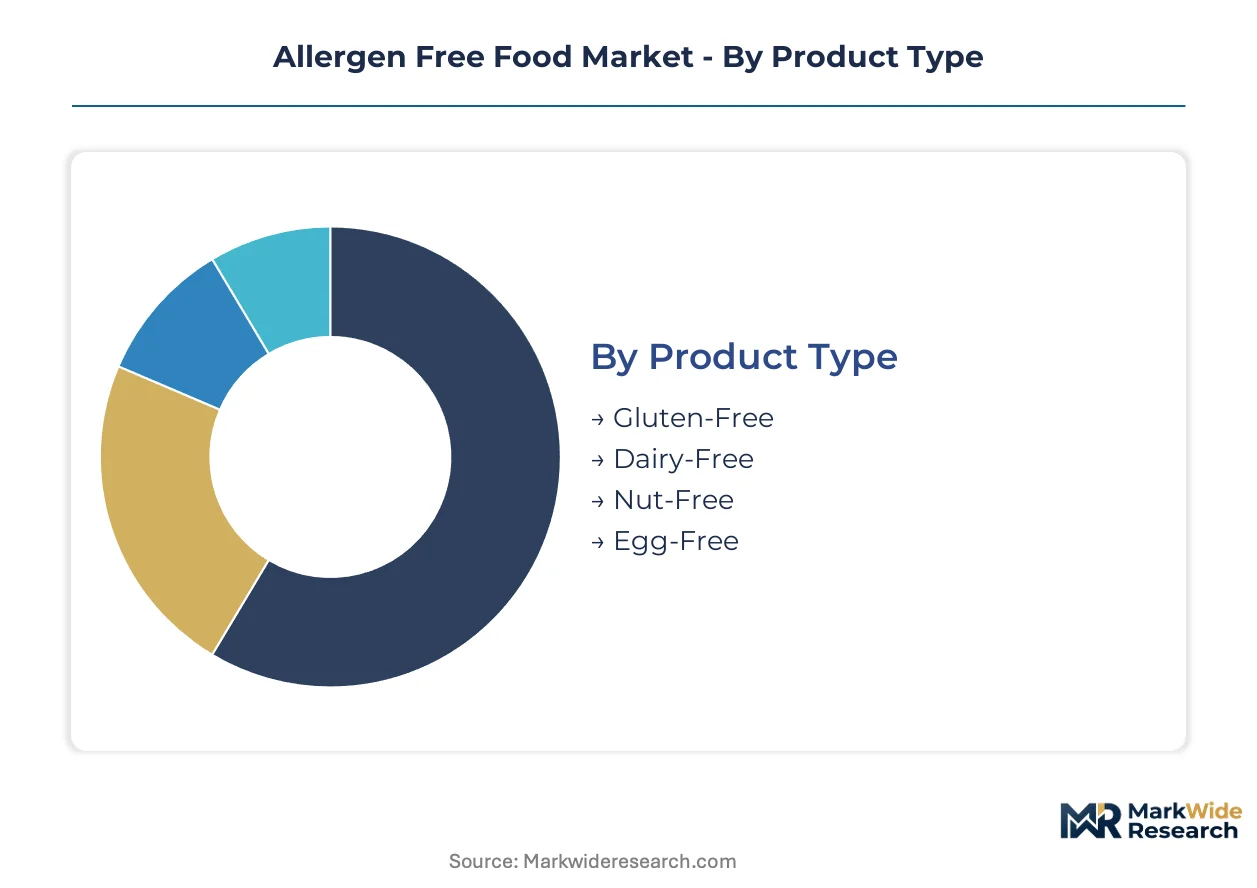
Allergen-free food segmentation reflects divergent technical requirements across production protocols and procurement relationships. Manufacturers must align facility certifications with channel-specific documentation demands while managing ingredient traceability across multiple distribution pathways.
Product Type:
Formulation chemistry and protein substitution complexity define competitive positioning within each product category.
- Gluten-Free:Wheat protein replacement relies on rice, tapioca, and sorghum flour blends with xanthan gum binding agents. Celiac disease prevalence in the United States and Germany sustains retail volume leadership, though Italian pasta manufacturers face input cost pressure from Southeast Asian starch supply volatility.
- Dairy-Free:Precision fermentation and enzymatic hydrolysis produce hypoallergenic analogues with improved mouthfeel versus early-generation soy formulations. Dutch infant formula specialists are accelerating adoption of these processes to serve diagnosed cow's milk protein allergy cases through clinical and retail channels simultaneously.
- Nut-Free:School procurement mandates in the United States and Canada institutionalize demand for validated peanut and tree nut absence.
- Egg-Free:Aquafaba and modified starch systems replicate emulsification and leavening functions in bakery applications.
Gluten-Free leads on scale; Dairy-Free leads on momentum.
End User:
Purchasing authority and compliance documentation requirements vary sharply across institutional versus individual buyers.
- Individuals:Direct consumers prioritize batch-traceable inventory with digital certificates over supermarket shelf uncertainty, particularly parents managing multiple allergies. Subscription replenishment patterns concentrate in suburban United States markets where delivery density supports weekly cycles without freight surcharges.
- Schools:North American and European educational institutions mandate nut-free meal environments, creating procurement volumes that specialty manufacturers cannot serve through retail channels alone. HACCP-aligned documentation requirements exceed standard foodservice specifications.
- Restaurants:Kitchen cross-contamination protocols and staff training investments limit allergen-free menu expansion.
- Food Manufacturers:Ingredient sourcing demands validated supplier audits extending to tier-two and tier-three vendors for natural flavors and colorants.
Schools concentrate procurement volume; Individuals expand most quickly through direct-to-home channels.
Distribution Channel:
Channel selection determines documentation transparency and replenishment predictability for allergic consumers.
- Online Retail:Direct-to-home delivery with transparent ingredient documentation and batch-tested certificates displaces conventional supermarket browsing among households with multiple allergic members. Parents prioritize subscription models that eliminate shelf uncertainty.
- Supermarkets:Mainstream retail shelf space competition favors established brands with reformulated variants over specialty entrants lacking scale for slotting fees.
- Specialty Stores:Health food retailers provide educated staff guidance and curated allergen-free assortments.
- Direct Sales:Hospital and airline catering contracts specify allergen-free meal guarantees with volume commitments justifying dedicated production line investments.
Online Retail climbs the fastest; Supermarkets retain volume dominance through brand extension strategies.
Service Type:
Value-added services differentiate suppliers beyond formulation capabilities.
- Consultation:Dietitian-guided product selection and meal planning support pediatric allergy management.
- Delivery:Temperature-controlled logistics with contamination prevention protocols serve institutional foodservice contracts.
- Subscription Services:Automated replenishment with batch-traceable inventory reduces stockout risk for households managing multiple allergies.
- Custom Orders:Small-batch production accommodates rare allergen combinations outside standard product lines.
Subscription Services gain share fastest; Delivery anchors institutional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Allergen-free food production clusters around specialized workforce pools in food science, regulatory compliance, and precision manufacturing. Talent density in these regions determines facility siting decisions and supply chain reliability.
United States
Pediatric allergy diagnoses and parental purchasing power drive institutional procurement across suburban school districts. The FDA enforces Food Allergen Labeling and Consumer Protection Act requirements that compress reformulation timelines for domestic manufacturers. Minneapolis-St. Paul anchors General Mills' reformulation operations, where dedicated production lines serve both retail and foodservice channels.
Germany
Gluten-free bakery demand from diagnosed celiac patients sustains specialized milling and extrusion capacity. EFSA scientific opinions inform EU-wide allergen thresholds that German manufacturers anticipate through early compliance investments. Lübeck hosts Dr. Schär's European production hub, where controlled supply chains validate ingredient provenance for export markets.
Italy
Traditional pasta manufacturers face input cost pressure from Southeast Asian starch supply volatility. EU FIC Regulation 1169/2011 mandates clear allergen labeling that compels reformulation of heritage product lines. Parma and Modena concentrate gluten-free pasta innovation, leveraging existing dry-goods infrastructure for allergen-segregated production.
Netherlands
Precision fermentation expertise serves hypoallergenic infant formula demand through clinical and retail channels simultaneously. REACH-aligned chemical disclosure requirements accelerate ELISA and PCR detection adoption at facility entry points. Wageningen University's food science cluster feeds talent directly into Dutch manufacturers advancing enzymatic protein hydrolysis.
Canada
School nut-free mandates in Ontario and British Columbia institutionalize procurement volumes exceeding retail channel capacity. Health Canada and PMRA coordinate domestic allergen management with import inspection protocols that complicate cross-border supplier relationships. Toronto's food manufacturing corridor hosts contract bakeries serving US institutional buyers with HACCP-aligned documentation.
Allergen Free Food Market Vendor Landscape
The competitive structure tilts toward diversified multinationals with reformulated mainstream brands rather than pure-play specialists. Tiered positioning separates scale-driven portfolio extensions from certified specialty producers with medical endorsements. Three archetypes dominate: global CPG conglomerates leveraging procurement networks, European-certified specialists controlling supply chains, and subscription-native direct-to-consumer brands. Capacity expansion and strategic portfolio diversification constitute the dominant competitive moves, with manufacturers removing precautionary labeling to avoid consumer deselection.
Among diversified multinationals, Nestlé and General Mills occupy positions where global procurement networks secure dedicated allergen-free production lines across multiple facilities. Dr. Schär exemplifies the certified specialist archetype, anchoring reputation through controlled supply chains and medical community endorsement rather than mainstream brand recognition. These three players collectively represent the spectrum from scale-driven shelf-space competition to precision-segment medical positioning.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| General Mills |
| Kraft Heinz |
| Enjoy Life Foods |
| Dr. Schär |
| The Hain Celestial Group |
| Conagra Brands |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Precision fermentation specialists clustered around Wageningen and Leiden create labor-cost differentials that widen pricing spreads between clinical-grade hypoallergenic formulations and commodity gluten-free alternatives. This workforce concentration allows Dutch manufacturers to command premiums for enzymatic hydrolysis capabilities while Italian pasta producers absorb Southeast Asian starch volatility through thinner margins.
Pricing Analysis
Bundled subscription services with batch-traceable digital certificates carry 15-25% premiums over unbundled supermarket purchases. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade infant formula from retail gluten-free pasta from private-label nut-free snacks. Cost compression in the standard tier is intensifying because Thai and Vietnamese rice starch prices fluctuate with monsoon patterns. School procurement officers show lowest price sensitivity due to liability protocols, while individual consumers on subscription platforms negotiate hardest on freight surcharges.
Supply Chain Analysis
Single-source vulnerability sits with Thai and Vietnamese rice starch suppliers, where climate disruption in the Mekong Delta propagates through European pasta manufacturing. Germany, Italy, and the Netherlands anchor validated allergen-segregated production, drawing from Southeast Asian starch, North American pea protein, and domestic precision fermentation inputs. Tariff exposure on imported legume flours threatens margin stability for French chickpea-based bakery entrants. Distribution runs through direct-to-home subscription platforms fastest, though supermarket retail retains volume dominance through slotting-fee barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allergen-free food market functions as a stable compounder, with pediatric allergy diagnosis rates providing non-cyclical demand insulation against economic downturns.
For Market Incumbents: Anticipate EFSA threshold finalization by accelerating cleaning validation investments ahead of formal mandate publication. Nestlé and General Mills should secure dedicated production line capacity in Minneapolis-St. Paul and Lübeck before German contract bakeries reach full utilization. Certification investment in mass spectrometry detection at intake points will differentiate compliant portfolios from precautionary-label competitors when regulatory deadlines crystallize. For New Entrants and Emerging Players: Mass spectrometry multi-allergen screening platforms offer technology-first wedge into institutional foodservice contracts where HACCP documentation exceeds retail requirements. Hospital and airline catering channels present the most penetrable white space, with volume commitments justifying capital equipment investments that retail slotting fees would foreclose. Direct sales teams with biomedical engineering backgrounds outperform traditional foodservice brokers in securing these contracts. For Investors and Strategic Acquirers: Foodservice distributors with institutional catering relationships are the most active acquirer in this space, seeking backward integration into validated production capacity. The long-term viability window favors certified specialists with medical community endorsements over brand-extended CPG portfolios. Watch for EFSA quantitative action level publication as the inflection signal that triggers precautionary-label removal investments and consolidates compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Cleaning Validation Program Acceleration | Swiss and Belgian confectionery producers are removing "may contain" statements ahead of EFSA deadlines to avoid consumer deselection. |
| Direct-to-Consumer Subscription Launch | Parents of children with multiple allergies prioritize batch-traceable inventory with digital certificates over supermarket shelf uncertainty. |
| Precision Fermentation Capacity Expansion | Dutch infant formula specialists serve diagnosed cow's milk protein allergy cases through clinical and retail channels simultaneously. |
| Institutional Foodservice Contract Capture | Hospital and airline catering guarantees create volume commitments that justify dedicated allergen-segregated production line investments. |
| Mass Spectrometry Detection Adoption | Simultaneous multi-allergen screening at ingredient intake points displaces sequential protein-specific immunoassay testing. |
Methodological Framework
Coverage spans the United States, Germany, Italy, the Netherlands, and Canada, with primary inputs from each market. The research combines structured interviews with food science R&D directors, regulatory affairs leads at manufacturers, school district procurement officers, and allergen testing laboratory managers with secondary validation from FDA FALCPA guidance documents, EFSA scientific opinions, EU FIC Regulation 1169/2011 filings, and Health Canada allergen management protocols. Bottom-up segmentation modeling triangulates against top-down macroeconomic anchors.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, end user, distribution channel, and service type dimensions alongside regional regulatory cluster variations. CAGRs derive from segmented growth trajectory blending rather than single-point extrapolation. Forecast inputs include pediatric allergy diagnosis incidence patterns, school procurement mandate expansion timelines, and precision fermentation yield improvement curves.
The model holds under stable regulatory timelines and continued EFSA threshold science progression; deviation in climate-induced starch supply disruption or accelerated EU Green Deal procurement criteria would shift volume projections. Forecasts reflect documented assumptions about allergen detection technology adoption rates and institutional channel penetration speed. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Gluten-Free Pasta Market