
 Argentina Gluten-Free Food and Beverage Market | 2026-2036
Argentina Gluten-Free Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Gluten-Free Food and Beverage Market Outlook
Market Context
Brazilian ingredient milling capacity is narrowing the supply gap for Argentine gluten-free manufacturers seeking regional raw material security. Granero Gluten Free dominates Buenos Aires shelf space through dedicated bakery operations. Dr. Schar leverages European formulation expertise to anchor premium positioning in Argentine supermarkets. Molinos Rio de la Plata extends its legacy grain infrastructure into certified gluten-free milling lines.
Technical Definition and Segments
Argentina gluten-free food and beverage encompasses edible products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or quinoa derivatives to achieve structural integrity below 20 ppm gluten threshold. These products serve diagnosed celiac patients, gluten-sensitive consumers, and households pursuing wheat-free dietary patterns. Bread and pasta categories occupy the deepest retail penetration due to their centrality in Argentine daily consumption habits. Snacks represent the fastest-growing product type as convenience-oriented formats attract younger demographics. Online retail channels capture expanding margin pools by bypassing traditional distributor markups in secondary cities.
Regulatory Environment
ANMAT enforces gluten-free labeling protocols that mandate facility certification and periodic allergen testing for domestic producers and importers alike. The country's national food code aligns with CODEX Alimentarius standards while adding traceability requirements that elevate compliance costs for smaller entrants. Celiac associations actively monitor enforcement, creating reputational risk for brands with labeling discrepancies. Stakeholders must weigh ANMAT audit frequency against the capital requirements for dedicated production lines.
Market Dynamics
ANMAT's facility certification mandate is restructuring Argentine gluten-free production economics, forcing dedicated milling investments that separate compliant operators from shared-line competitors.
Growth Catalysts
- Celiac association advocacy:Argentine celiac patient organizations press supermarkets for dedicated shelf space and cross-contamination protocols. Retailers respond by expanding certified product assortments.
- Quinoa derivative substitution:Andean grain processors supply structural alternatives to imported rice flour. Local sourcing reduces input cost volatility for domestic bakers.
- Buenos Aires metropolitan demand density:Concentrated diagnosed populations in the capital corridor sustain volume throughput for specialized distribution networks.
Market Restraints
- Input cost volatility:Tapioca starch prices fluctuate with Brazilian cassava harvest cycles. Argentine formulators lack alternative thickening agents at comparable functionality.
- Supply concentration risk:Certified oat imports depend on single-source Canadian suppliers. Cross-contamination testing at port of entry creates inventory delays.
- Regulatory friction:ANMAT's traceability requirements demand batch-level documentation systems. Small bakeries face disproportionate compliance overhead relative to revenue scale.
Strategic Opportunities
- Cordoba and Rosario underpenetration:Secondary cities lack dedicated gluten-free retail sections. Direct-to-store distribution bypasses Buenos Aires-centric wholesale markups.
- Online channel innovation:E-commerce platforms enable subscription-based pantry replenishment. Home delivery resolves mobility constraints for diagnosed rural households.
- ANMAT export equivalency recognition:Certification alignment with Mercosur standards opens Brazilian and Uruguayan retail access for compliant Argentine producers.
Industry Challenges
- Technical talent scarcity:Food chemists with gluten-free formulation expertise command premium compensation. Training programs at Buenos Aires universities remain underdeveloped.
- Capex intensity for dedicated lines:Segregated milling equipment requires facility reconfiguration. Bank lending for allergen-controlled infrastructure carries risk-adjusted rate premiums.
- Certification timeline compression:ANMAT audit backlogs extend product launch schedules. Brands miss seasonal demand windows waiting for facility approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Gluten-Free Food and Beverage Market |
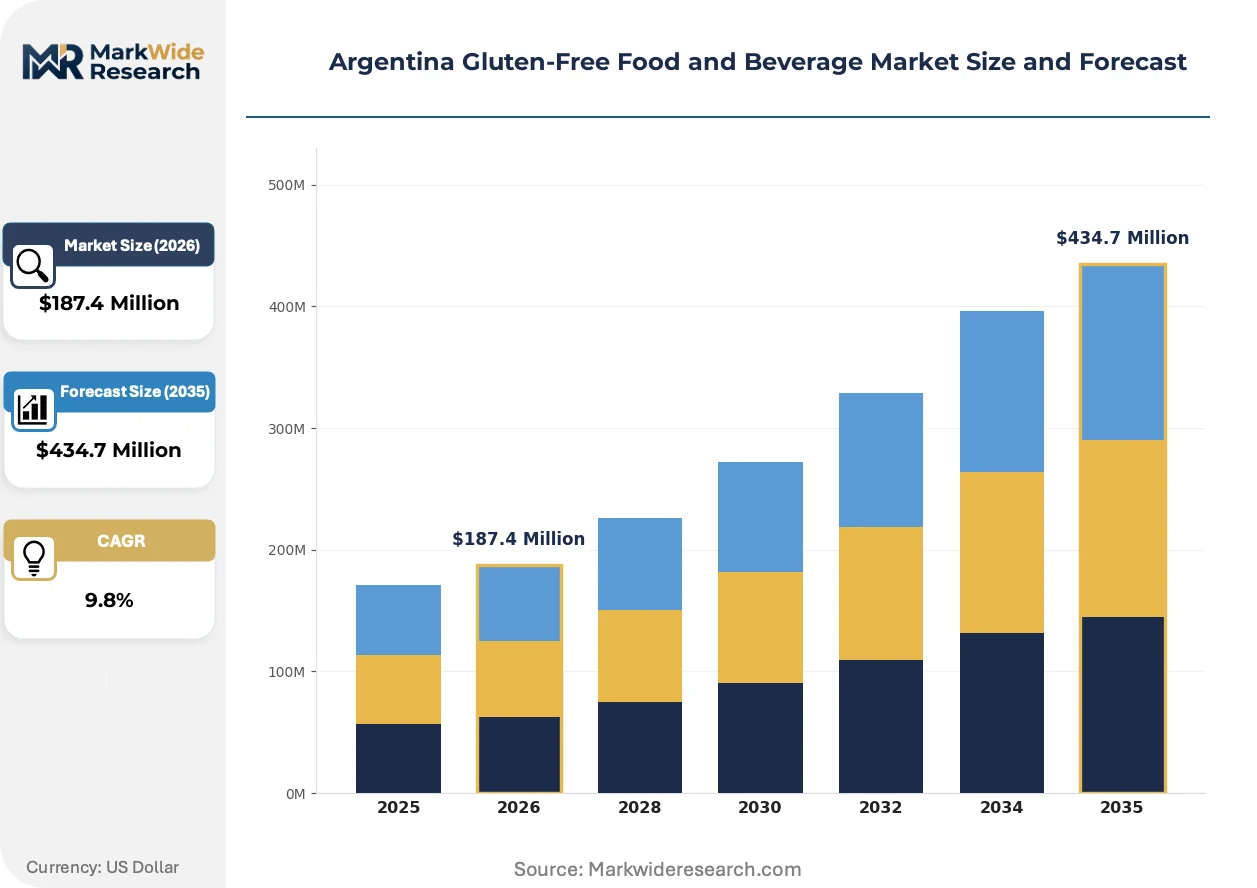
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pasta, Snacks, Beverages Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores End User: Individuals, Families, Restaurants, Cafes Packaging Type: Bags, Boxes, Tins, Bottles |
| Companies Covered | Granero Gluten Free, Bob's Red Mill, Molinos Rio de la Plata, General Mills Inc., Dr. Schar, Cerealko, Quinoa Corporation, Boulder Brands, CeliGourmet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Gluten-Free Food and Beverage Market Strategic Shifts
Formulation science and regulatory precision are converging to redefine competitive advantage in Argentine gluten-free manufacturing, with technology adoption separating scalable operators from artisanal competitors.
Enzymatic gluten degradation is hybridizing traditional wheat-based processing with certified-safe outputs. Large-scale pasta manufacturers deploy transglutaminase and protease treatments to neutralize gluten fragments in conventional dough. This approach compresses capital requirements versus dedicated gluten-free facilities while expanding product portfolios.
ANMAT's updated food code alignment with CODEX Alimentarius standards tightens facility segregation protocols. Domestic producers must demonstrate physical separation of gluten-containing and gluten-free production zones. Bread and pasta categories face the steepest compliance adjustments due to shared equipment legacy in Argentine milling infrastructure.
Subscription-based pantry replenishment is displacing conventional supermarket purchasing among diagnosed celiac households. Digital-native consumers in Buenos Aires prioritize convenience and contamination guarantees over price comparison. Direct-to-consumer channels capture margin pools previously absorbed by distributor networks in secondary provinces.
Argentina Gluten-Free Food and Beverage Market Segmentation
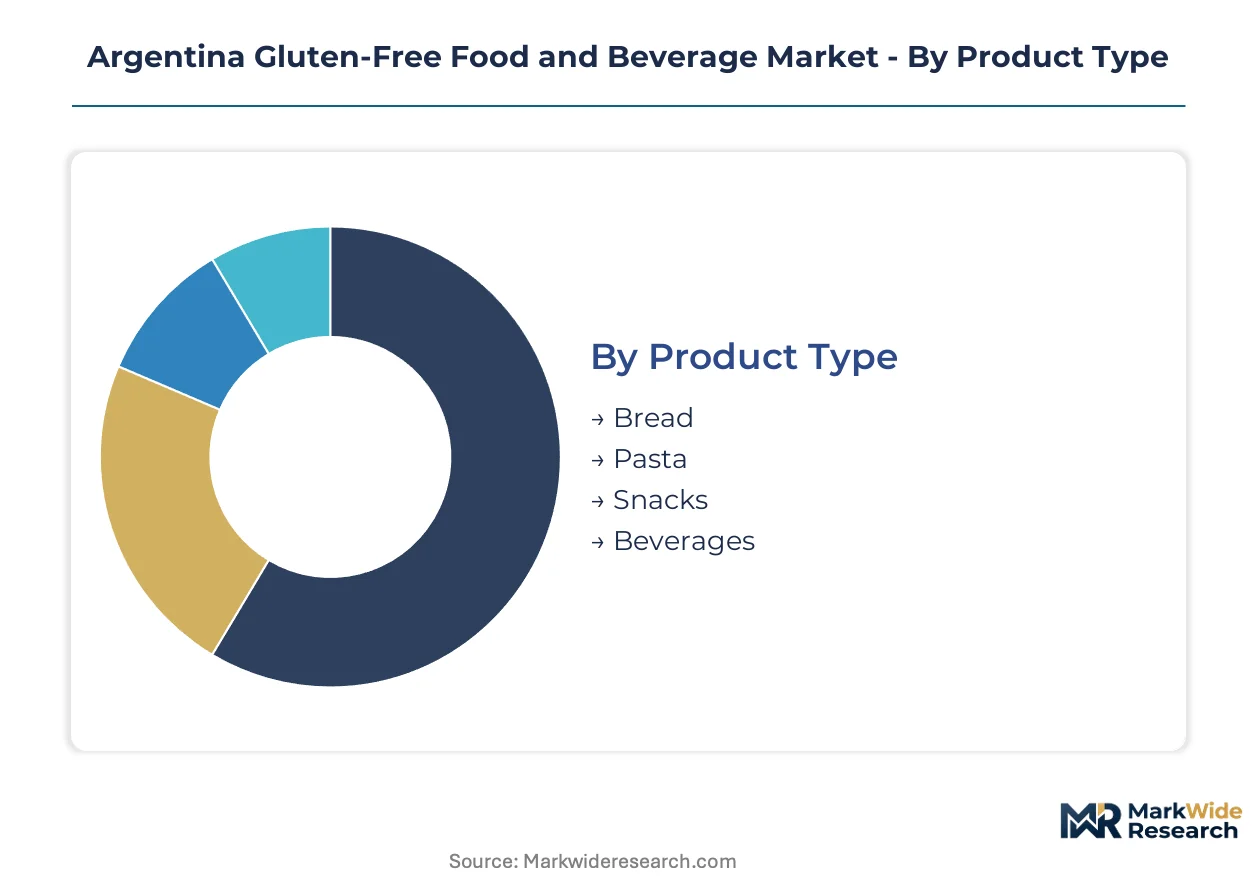
Segmentation in the Argentine gluten-free market reveals distinct demand patterns across product formats and purchase occasions. ANMAT certification requirements and distribution economics create divergent growth trajectories across channels and end-user categories.
Product Type:
Argentine consumption habits center on wheat-dependent staples, creating differentiated adoption curves across reformulated categories.
- Bread:Rice flour and tapioca starch formulations replicate traditional Argentine sandwich rolls and facturas. Buenos Aires metropolitan households with diagnosed celiac members sustain dedicated bakery counter space in major supermarket chains.
- Pasta:Corn and quinoa-based extrusions target family meal preparation occasions. Molinos Rio de la Plata's certified milling lines supply regional distributors with dried formats that command shelf-stable inventory turns.
- Snacks:Convenience-oriented formats attract younger demographics seeking portable options.
- Beverages:Quinoa-based malt drinks and oat-free alternatives serve breakfast and hydration occasions.
Established volume favors bread; emerging adoption favors snacks.
Distribution Channel:
Channel economics in Argentina reflect geographic concentration of diagnosed populations and regulatory compliance burdens.
- Supermarkets:Granero Gluten Free and Dr. Schar anchor dedicated shelf sections in Buenos Aires hypermarkets. ANMAT traceability requirements favor centralized procurement systems with batch-level documentation.
- Online Retail:Subscription-based pantry replenishment captures margin pools previously absorbed by provincial distributors. Home delivery resolves mobility constraints for rural celiac households outside capital corridor access.
- Health Stores:Neighborhood pharmacies and dietetic shops serve diagnosed patients seeking pharmacist guidance.
- Specialty Stores:Dedicated gluten-free bakeries in Palermo and Recoleta districts offer contamination-controlled environments.
Supermarkets dominate transaction volume; online retail climbs the fastest.
End User:
User categories reflect household structure and foodservice operational requirements.
- Individuals:Single-person diagnosed households prioritize portion-controlled formats and subscription convenience.
- Families:Multi-member households with one celiac patient drive bulk purchasing and cross-contamination protocol adherence at home.
- Restaurants:Buenos Aires dining establishments seek ANMAT-certified suppliers for dedicated menu sections. Liability exposure from cross-contamination incidents pressures procurement toward verified sources.
- Cafes:Coffee shop chains in Cordoba and Rosario test gluten-free pastry offerings for metropolitan expansion.
Families anchor revenue stability; restaurants offer steepest expansion trajectory.
Packaging Type:
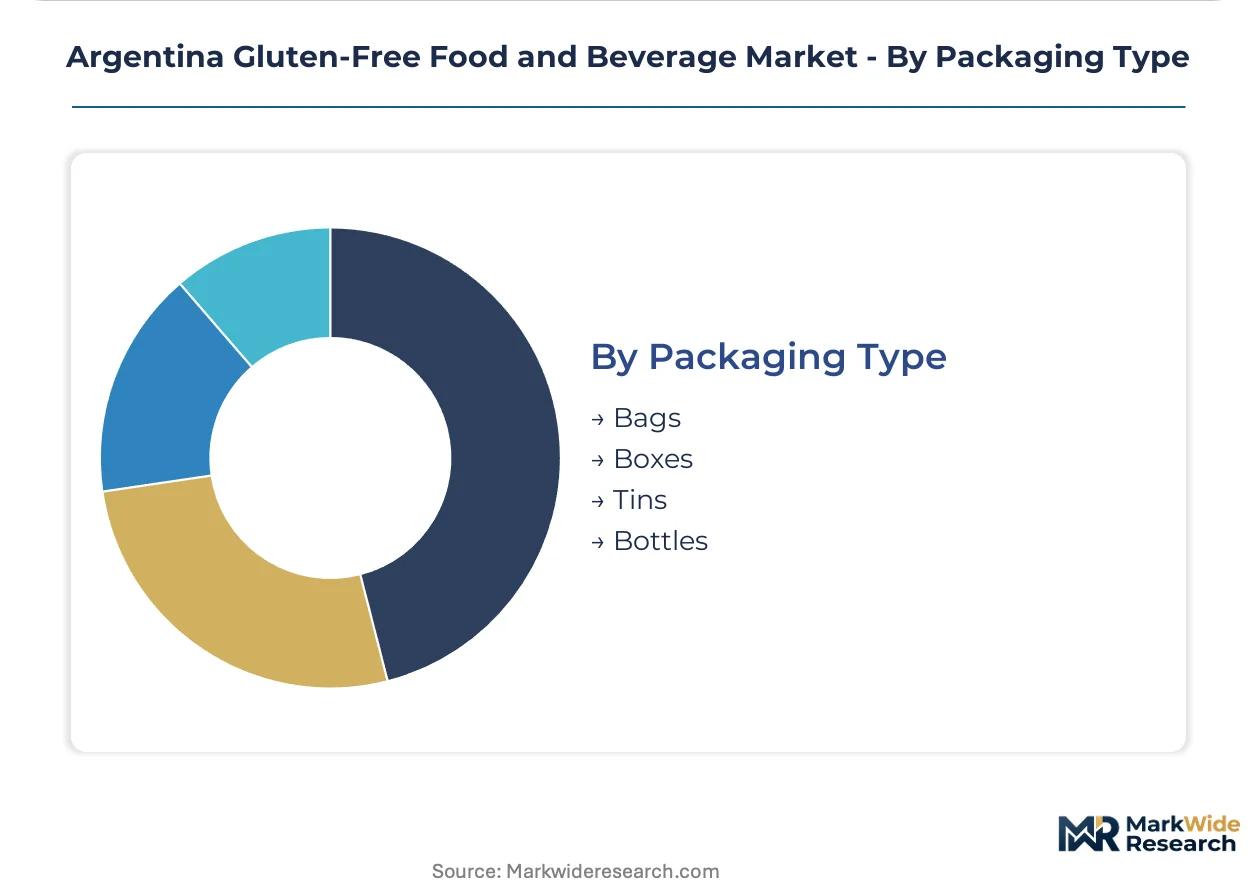
Packaging selection balances shelf-life extension with ANMAT labeling mandates and retail display requirements.
- Bags:Flexible packaging dominates bread and snack categories for cost-efficient distribution.
- Boxes:Rigid cartons protect pasta shapes through supply chain handling.
- Tins:Metal containers serve premium biscuit and cracker positioning.
- Bottles:Beverage formats require light-blocking materials for quinoa-based drinks.
Bags capture highest shipment volumes; bottles face emerging demand from beverage innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified milling capacity clusters in Buenos Aires and surrounding provinces, creating geographic asymmetry between compliant supply and dispersed demand across Argentina's interior. ANMAT's facility audit protocols reinforce this concentration by elevating capital barriers for peripheral entrants. Secondary cities remain dependent on capital corridor distribution networks.
Buenos Aires Metropolitan Area
Diagnosed celiac household density drives the deepest retail penetration of dedicated gluten-free sections. ANMAT's updated traceability mandates favor centralized procurement systems with batch-level documentation capabilities. Palermo and Recoleta districts host specialty bakeries offering contamination-controlled environments for premium-positioned consumers.
Cordoba
Underpenetrated retail infrastructure creates whitespace for direct-to-store distribution models bypassing Buenos Aires wholesale markups. Provincial health authorities coordinate with celiac associations to expand certified product availability. Coffee shop chains in the city center test gluten-free pastry offerings ahead of format expansion.
Rosario
Port logistics and grain trading heritage position the city for quinoa derivative processing integration into gluten-free supply chains. Local distributors face inventory delays from ANMAT cross-contamination testing requirements at entry points. Neighborhood pharmacies serve diagnosed patients seeking pharmacist guidance on certified options.
Mendoza
Wine tourism corridors attract gluten-free dining establishments seeking ANMAT-certified suppliers for dedicated menu sections. Provincial regulators align enforcement with national food code standards while adding regional traceability documentation. Andean grain processors in surrounding valleys supply structural alternatives to imported rice flour.
Argentina Gluten-Free Food and Beverage Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient milling and certification services. The Argentine gluten-free market structures around three tiers: dedicated gluten-free operators with segregated facilities, legacy grain processors extending into certified lines, and international importers leveraging formulation expertise. Strategic moves concentrate on facility certification attainment, dedicated production line investment, and regional distribution network expansion into secondary cities.
Among domestic dedicated operators, Granero Gluten Free exemplifies the capital corridor concentration archetype through Buenos Aires bakery operations. Molinos Rio de la Plata represents legacy grain infrastructure extension into certified gluten-free milling. Dr. Schar anchors the international formulation expertise tier, occupying premium positioning in Argentine supermarket channels through European-derived product standards.
| Leading Market Players |
|---|
| Granero Gluten Free |
| Bob's Red Mill |
| Molinos Rio de la Plata |
| General Mills Inc. |
| Dr. Schar |
| Cerealko |
| Quinoa Corporation |
| Boulder Brands |
| CeliGourmet |
| Others |
Value Chain & Pricing Dynamics
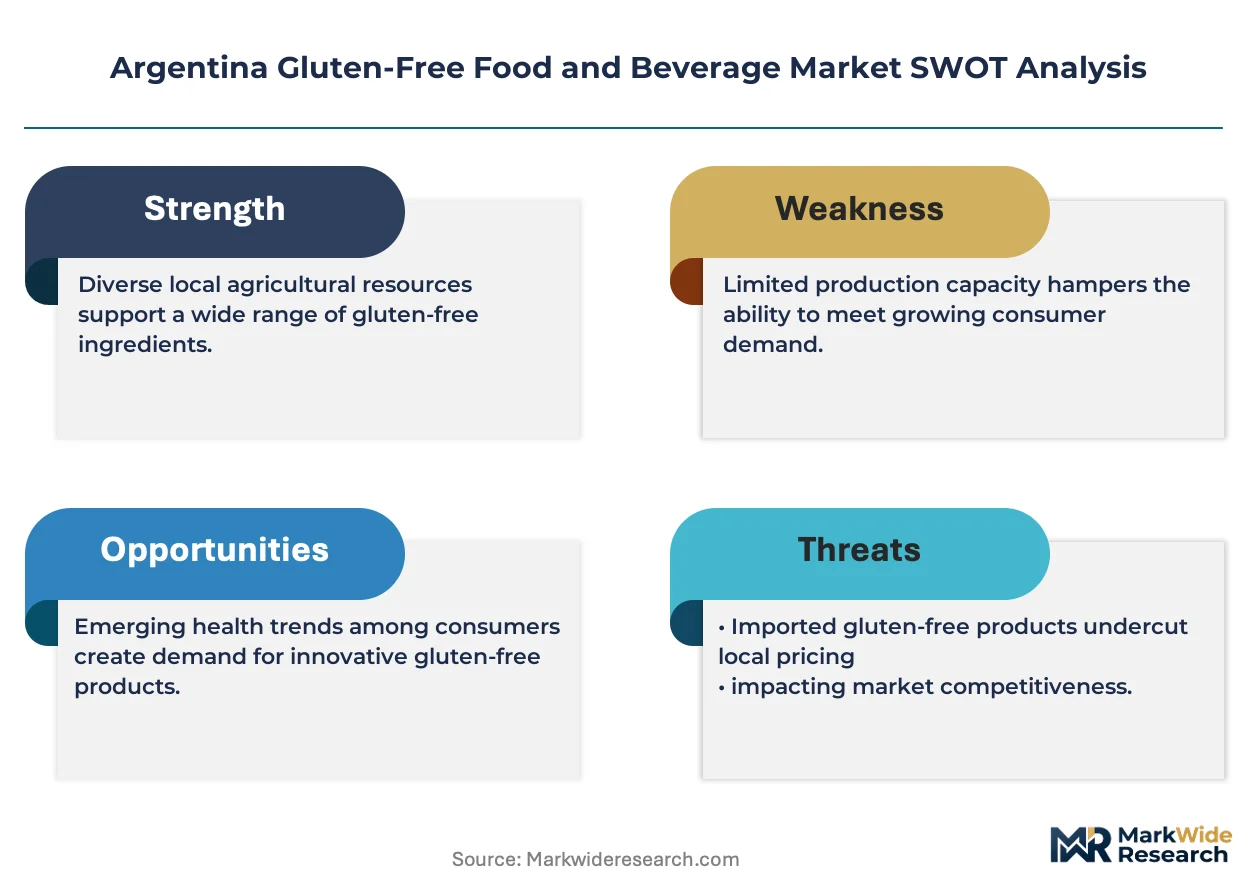
Single-source Canadian oat dependency creates inventory chokepoints at Argentine ports that compress margins for certified producers while forcing three-tier pricing stratification across premium import-reliant, standard domestic-quinoa, and economy shared-facility tiers. ANMAT cross-contamination testing delays at entry points directly determine working capital requirements and downstream price spreads.
Pricing Analysis
ANMAT facility certification dictates the pricing tier structure across Argentine gluten-free manufacturing. Premium tiers command spreads based on dedicated line segregation and traceability documentation depth, while standard tiers compete on quinoa derivative substitution against rice flour formulations. Cost compression in the economy tier intensifies as shared-line operators face audit frequency penalties. Family households with diagnosed celiac members show lowest price sensitivity due to contamination risk aversion; single-person households in secondary cities exhibit highest elasticity.
Supply Chain Analysis
Granero Gluten Free and Molinos Rio de la Plata hold concentrated certified milling capacity in Buenos Aires province, with limited secondary sourcing from Cordoba grain processors. Raw material flows draw from Brazilian tapioca starch suppliers, Andean quinoa processors, and Canadian oat importers. Single-source vulnerability in certified oat supply creates batch-level inventory risk. Distribution runs through Buenos Aires-centric wholesale networks with direct-to-store bypass emerging in Cordoba and Rosario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supermarket buyer consolidation in Buenos Aires metropolitan corridors concentrates procurement leverage among three retail banners, shifting supplier power toward volume-guaranteed compliant producers.
For Market Incumbents: Entrench facility certification moats through ANMAT audit pre-emption and dedicated line capacity additions in Buenos Aires province. Secure backward integration into Andean quinoa milling to reduce Brazilian tapioca starch price volatility exposure. Channel control through direct-to-store distribution in Cordoba and Rosario defends against emerging local formulators.
For New Entrants and Emerging Players: Mid-market family households in Rosario and Mendoza represent the most penetrable entry point given underdeveloped dedicated retail sections and pharmacy-dependent purchasing. Subscription-based pantry replenishment for rural diagnosed households offers go-to-market differentiation against Buenos Aires-centric incumbents.
For Investors and Strategic Acquirers: ANMAT's alignment with Mercosur export equivalency standards reshapes the acquisition landscape toward certified operators with cross-border production scalability. Target archetypes include dedicated gluten-free facilities with segregated infrastructure and traceability documentation systems. Monitor Brazilian retail chain entry into Argentine gluten-free procurement as inflection signal for regional volume consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Facility Certification Investment | Segregated production lines unlock premium tier access and supermarket shelf placement. |
| Andean Quinoa Milling Integration | Captive supply of structural alternatives reduces Brazilian tapioca starch cost volatility. |
| Direct-to-Consumer Subscription Launch | Bypasses Buenos Aires wholesale markups while serving rural celiac household mobility constraints. |
| Mercosur Export Equivalency Attainment | ANMAT certification alignment opens Brazilian and Uruguayan retail channel access. |
| Enzymatic Gluten Degradation Adoption | Transglutaminase treatments compress capital requirements versus dedicated facility construction. |
Study Parameters
Initial hypotheses were tested against primary input from ANMAT regulatory affairs officers, celiac association procurement leads, supermarket category buyers, and dedicated gluten-free facility managers and refined through secondary validation against ANMAT food code filings, CODEX Alimentarius standards documentation, Argentine customs import records, and celiac patient registry data. Bottom-up volume estimates from facility-level production capacity triangulated against top-down consumption surveys across Buenos Aires, Cordoba, Rosario, and Mendoza metropolitan areas.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation across product type, distribution channel, end user category, and packaging format. CAGRs derived from diagnosed celiac population growth trajectories, ANMAT certification expansion timelines, and quinoa derivative processing capacity buildouts. Industry-specific inputs included ANMAT audit backlog durations and Brazilian cassava harvest cycle volatility indices.
Practitioners should monitor ANMAT traceability mandate enforcement intensity and Canadian oat supplier concentration ratios for early signals of margin compression or supply disruption. Forecasts reflect assumptions on celiac diagnosis rates, certification facility investment flows, and Mercosur regulatory harmonization progress. Quarterly review of ANMAT audit queue lengths and port cross-contamination testing delays is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Gluten Free Products Market