
 Global Breakfast Cereals Market | 2026-2036
Global Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breakfast Cereals Market Analysis
Ingredient sourcing and fortification partnerships is reconfiguring margin distribution across the value chain. General Mills leverages its North American manufacturing scale to control oat supply contracts. Nestlé anchors its competitive position through deep R&D investment in micronutrient fortification. Post Holdings differentiates via specialized grain processing capabilities that reduce production variability.
Breakfast cereals comprise processed grain formulations—typically wheat, oats, corn, or rice—that undergo flaking, puffing, or extrusion to achieve shelf-stable, ready-to-eat texture, with caloric density ranging from 350 to 400 kcal per 100 grams and fiber content engineered between 3% and 12% depending on target segment. Granola and muesli categories command premium shelf positioning due to higher nut and dried fruit inclusion rates that justify elevated price points. Online retail distribution is accelerating fastest among channels as subscription models and direct-to-consumer health branding reduce supermarket dependency. Cornflakes remain the most mature product type with thin margin pools concentrated in volume-driven emerging market penetration.
The FDA enforces nutritional labeling and health claim substantiation that shapes product formulation decisions for US-bound cereals, while EFSA and the EU Green Deal impose sustainability disclosure and palm oil sourcing restrictions affecting European market access. Kellogg Company and Associated British Foods navigate these frameworks through reformulated recipes and certified supply chains. Stakeholders must monitor evolving fortification standards and carbon footprint reporting requirements as regulatory stringency intensifies across multiple jurisdictions.
Market Dynamics
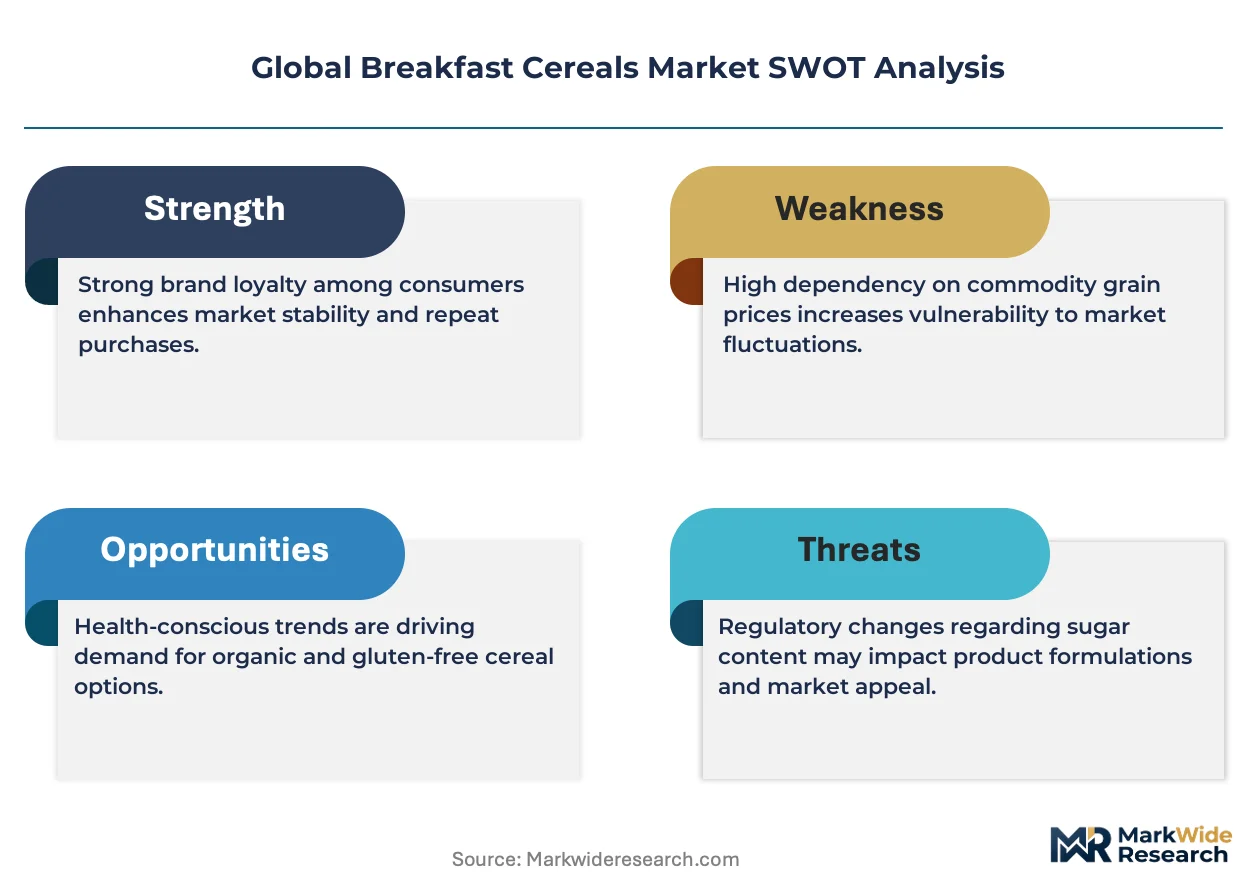
Clean-label regulations and EU Green Deal sustainability mandates are forcing wholesale reformulation of grain sourcing and fortification protocols across the breakfast cereals value chain.
Growth Catalysts
- FDA Nutritional Labeling:The FDA's updated serving-size disclosure rules compel manufacturers to reformulate recipes, accelerating fiber fortification and sugar reduction investments across US-bound production lines.
- Oat Supply Concentration:North American oat contract consolidation gives scaled processors preferential access to beta-glucan-rich grain stocks essential for heart-health positioning.
- Extrusion Technology:Advanced twin-screw extrusion systems enable precise texture control and reduced thermal degradation of heat-sensitive micronutrients during high-volume production runs.
Market Restraints
- Wheat Price Volatility:Black Sea supply disruptions and drought cycles in Australian growing regions create input cost instability for wheat-based flake and puff formulations.
- Palm Oil Sourcing Restrictions:EFSA and EU Green Deal deforestation-free supply chain mandates block market access for cereals using non-certified palm oil derivatives in binding and coating applications.
- Substitution by Yogurt and Protein Bars:Refrigerated Greek yogurt and shelf-stable protein bar categories capture convenience-seeking breakfast occasions with higher protein density and portable formats.
Strategic Opportunities
- Subscription Direct-to-Consumer:Health-branded cereal startups bypass supermarket slotting fees through recurring delivery models targeting urban professionals in Germany and Japan.
- EU Carbon Footprint Reporting:CSRD-aligned sustainability disclosure creates first-mover advantage for processors with verified Scope 3 grain sourcing data and regenerative agriculture partnerships.
- Precision Fermentation:Convergence of enzymatic processing and AI-driven formulation design enables novel protein-fiber matrices that replicate traditional textures without conventional grain bases.
Industry Challenges
- Clean-Label Reformulation Timeline:Removing artificial preservatives while maintaining shelf stability demands extended R&D cycles and sensory panel validation that compresses product launch windows.
- Legacy Equipment Retrofit Costs:Transitioning from high-sugar coating drums to aqueous binding systems requires capital-intensive line modifications incompatible with depreciated asset schedules at mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breakfast Cereals Market |
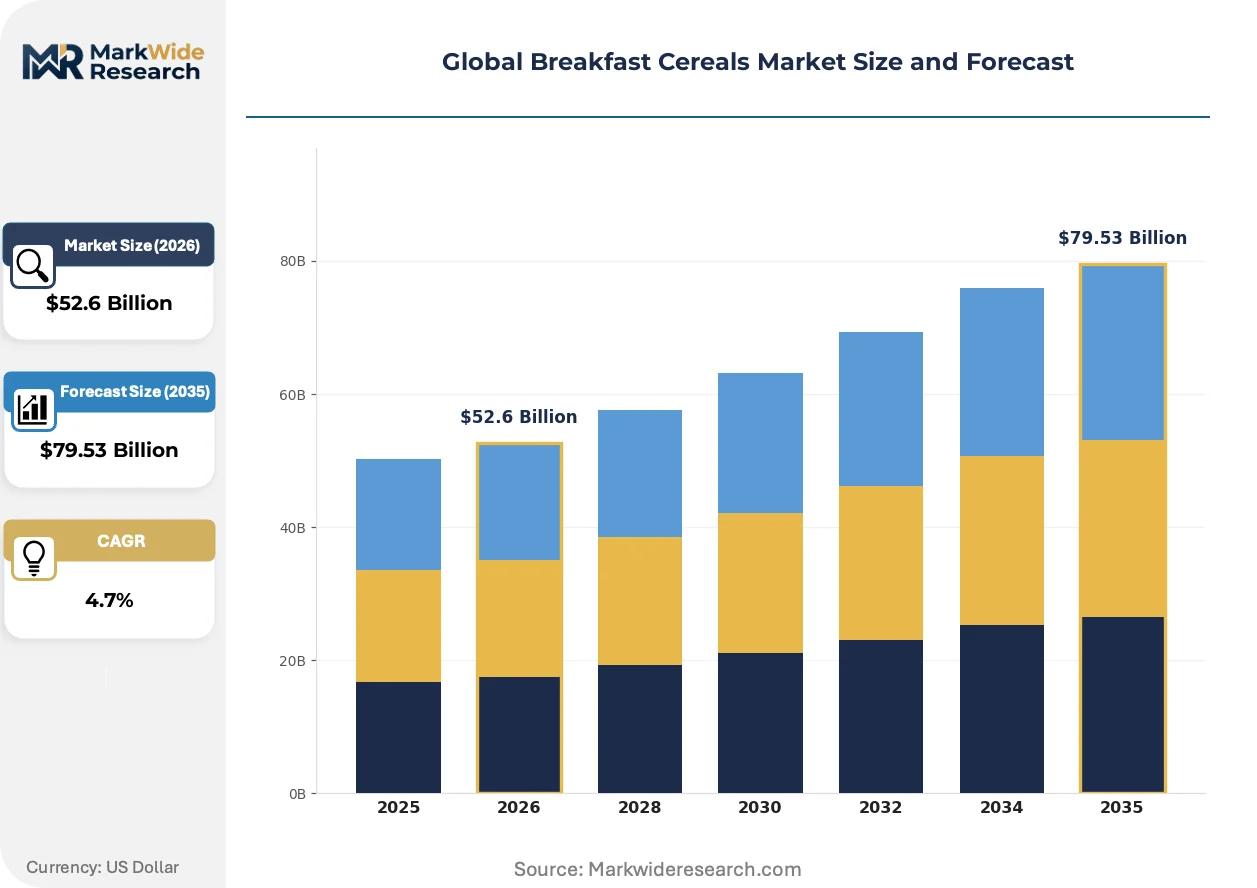
| Market Size in 2026 | $52.6 Billion |
| Market Size in 2035 | $79.53 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola, Oats, Cornflakes, Muesli Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Hypermarkets Customer Type: Families, Health-Conscious Consumers, Busy Professionals, Children Packaging Type: Bags, Boxes, Pouches, Tubs |
| Companies Covered | PepsiCo, B&G Foods, General Mills, Migros, Calbee, Nestlé, Post Holdings, Associated British Foods, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breakfast Cereals Market Emerging Trajectories
Breakfast cereals are undergoing fundamental transformation as processing technology, regulatory disclosure requirements, and channel economics simultaneously reshape competitive boundaries.
Cold-extrusion processing at sub-40°C temperatures is collapsing the traditional trade-off between production throughput and micronutrient retention. Functional cereal specialists in Japan and Germany deploy these systems to preserve heat-labile vitamins B and C through the forming stage. The technology compresses R&D-to-shelf timelines for fortified positioning claims.
EFSA's evolving health claim substantiation framework now demands randomized controlled trial evidence for cardiovascular benefit assertions on oat beta-glucan cereals. European manufacturers face reformulation costs or label removal for existing heart-health SKUs. German and Dutch processors lead adaptation through clinical partnership investments.
Pantry-loading behavior among remote workers has fragmented bulk purchasing patterns that previously concentrated demand in family-sized boxes. Single-serve and portion-controlled formats displace traditional large-format SKUs in direct-to-consumer channels. This rotation is most pronounced in US metropolitan markets with high dual-income household density.
Global Breakfast Cereals Market Segmentation
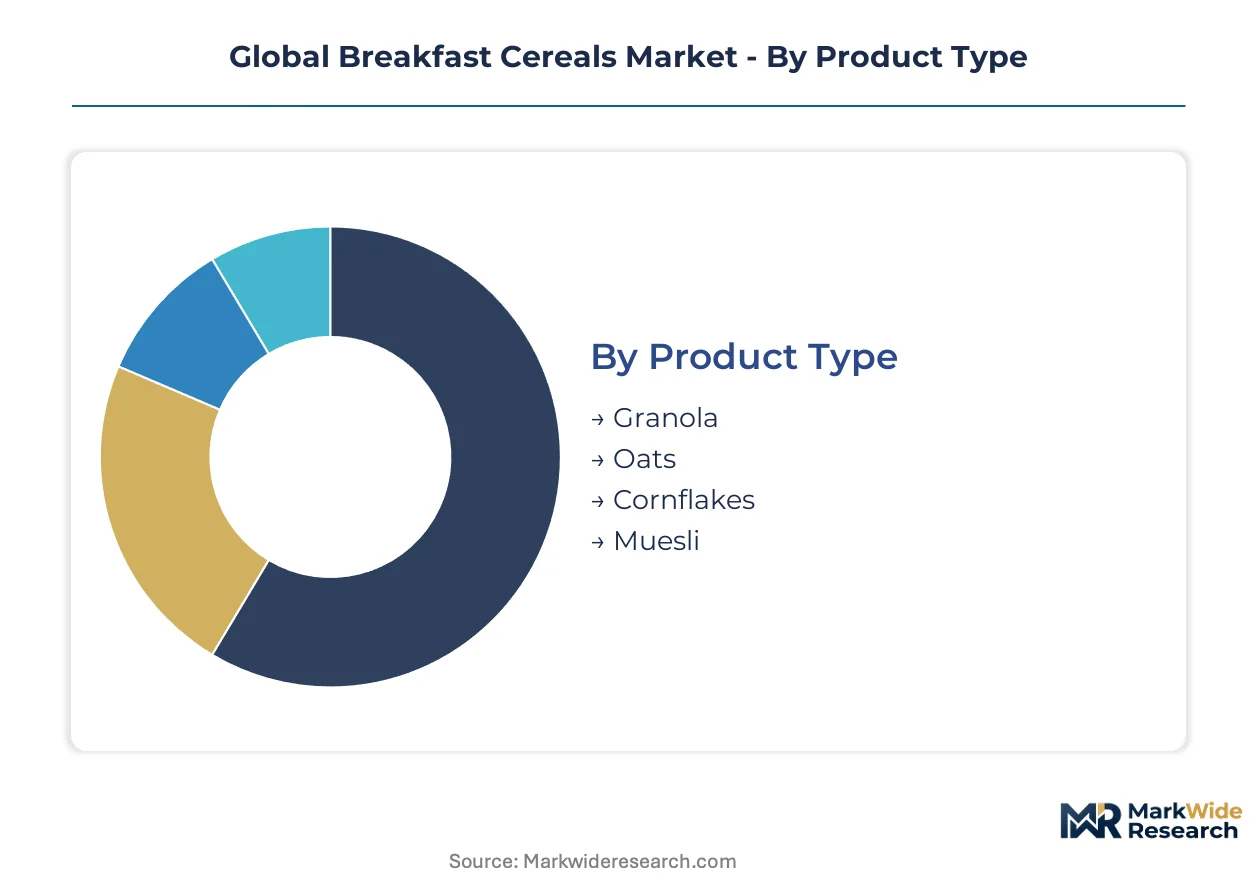
Breakfast cereals segment across four distinct dimensions that determine formulation priorities, channel economics, and margin architecture. Product type dictates ingredient sourcing and fortification intensity. Distribution channel selection shapes packaging formats and pricing flexibility. Customer type drives health-positioning investments. Packaging type influences shelf-life engineering and logistics costs.
Product Type:
The use-case spectrum spans indulgent morning rituals to functional nutrition delivery, with each format demanding distinct processing investments and raw material specifications.
- Granola:Baked clusters of rolled oats, nuts, seeds, and sweeteners deliver 400-450 kcal per 100 grams with elevated protein and fat content from nut inclusions. German and Japanese urban professionals drive premium positioning through direct-to-consumer subscription channels that emphasize artisanal sourcing and low-glycemic formulations.
- Oats:Rolled, steel-cut, or instant oat formats provide beta-glucan soluble fiber at 3-5 grams per serving, anchoring heart-health regulatory claims under FDA and EFSA frameworks. North American contract consolidation gives scaled processors preferential access to high-beta-glucan grain stocks essential for cholesterol-reduction positioning.
- Cornflakes:Flaked maize formulations undergo high-temperature toasting to achieve brittle texture and extended shelf stability without preservatives. Volume-driven penetration in emerging markets concentrates manufacturing in cost-optimized extrusion facilities with thin margin pools.
- Muesli:Unbaked blends of rolled grains, dried fruits, and nuts preserve raw nutrient profiles but require moisture-controlled packaging to prevent rancidity. Swiss and German heritage brands command shelf positioning through clean-label simplicity and heritage authenticity narratives.
The dominant share belongs to Cornflakes, while Granola is closing the gap fastest.
Distribution Channel:
Channel selection determines slotting fee exposure, inventory velocity requirements, and consumer data capture capabilities that reshape marketing investment allocation.
- Supermarkets:Traditional grocery anchors generate high-volume throughput but demand trade promotion spending and category management compliance that compresses net margins. US and German chains enforce planogram standards that limit SKU proliferation for mid-tier brands.
- Online Retail:E-commerce platforms and direct-to-consumer subscriptions bypass slotting fees while enabling precision targeting of health-conscious segments through algorithmic recommendation engines. Urban professionals in Japan and Germany drive fastest channel expansion through recurring delivery models.
- Convenience Stores:Small-format urban outlets prioritize single-serve and impulse-oriented packaging with rapid inventory turns and limited shelf space for premium positioning. Grab-and-go breakfast occasions favor portable cup formats over family-sized boxes.
- Hypermarkets:Big-box retail combines grocery and general merchandise traffic to support bulk purchasing and promotional stacking that drives volume concentration for value-tier SKUs. Warehouse club formats in the United States enforce strict packaging standardization that limits format innovation.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly.
Customer Type:
Demographic and psychographic segmentation determines fortification intensity, sugar content thresholds, and packaging format preferences that cascade through R&D priorities.
- Families:Multi-person households prioritize value-oriented bulk packaging with broad palatability and child-friendly formulations that balance taste acceptance with parental nutritional concerns. US and German family units drive demand for mid-tier fortified flakes with vitamin D and iron enrichment.
- Health-Conscious Consumers:Fitness-oriented buyers demand high-fiber, low-sugar, and protein-fortified options with transparent ingredient sourcing and third-party certifications. Japanese functional food specialists and German organic processors capture this segment through clinical substantiation of cardiovascular benefits.
- Busy Professionals:Time-constrained urban workers favor single-serve portability, minimal preparation, and subscription replenishment that eliminates pantry planning friction. Metropolitan clusters in Tokyo, Berlin, and New York concentrate demand for grab-and-go cup formats and office delivery programs.
- Children:Pediatric-oriented formulations face strict sugar content scrutiny under FDA and EFSA evolving standards while competing with school breakfast programs and portable yogurt alternatives. Character licensing and gamified packaging drive trial but face regulatory pressure on nutritional profiles.
Families command the largest addressable base, yet Health-Conscious Consumers are gaining share fastest.
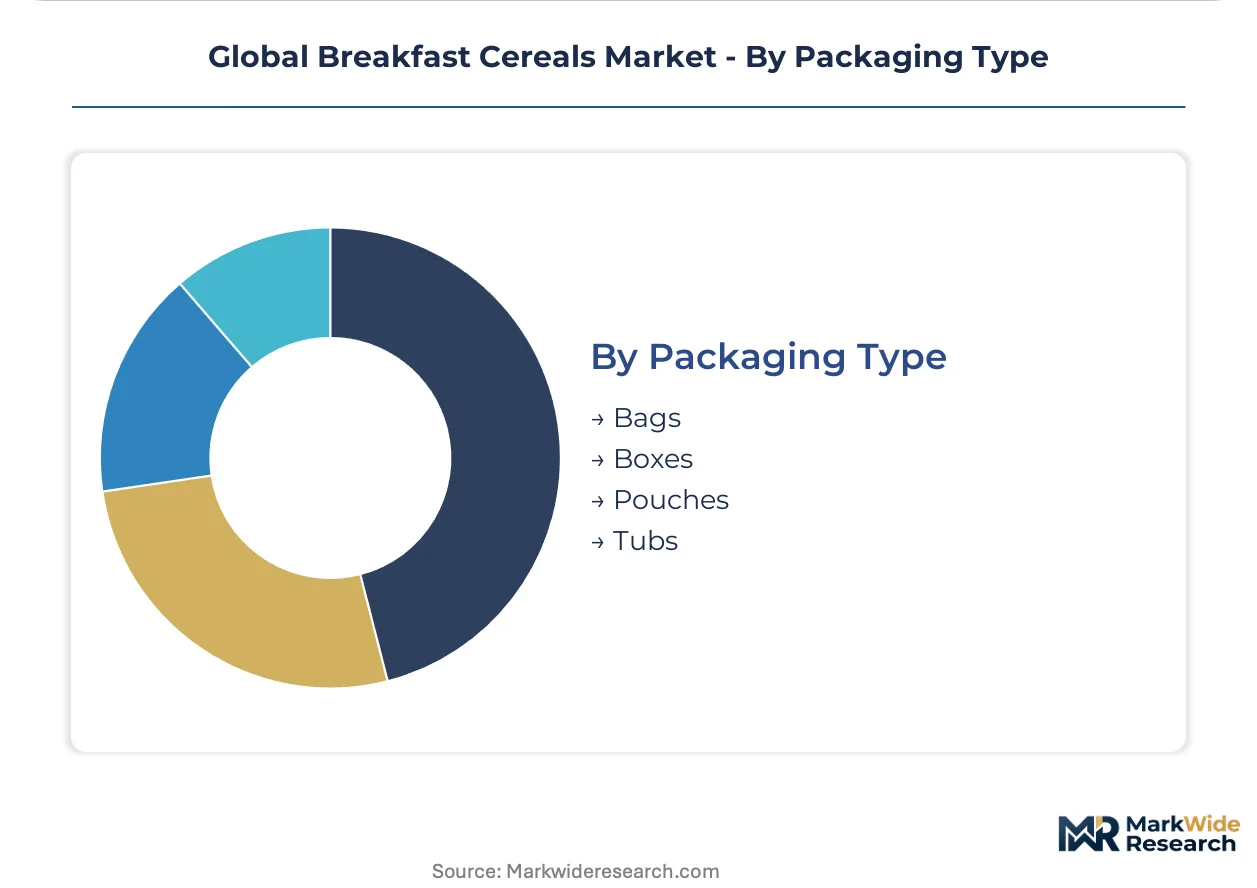
Packaging Type:
Material and format selection governs moisture barrier performance, shelf-life extension, and sustainability compliance costs that increasingly determine market access.
- Bags:Flexible film pouches reduce material weight and shipping cube but offer limited structural protection and premium shelf presence compared to rigid alternatives. Value-tier granola and muesli SKUs in European discount channels favor bag formats for cost minimization.
- Boxes:Paperboard cartons provide stacking strength, billboard surface for branding, and consumer familiarity that supports premium positioning in traditional retail. US supermarket planograms standardize box dimensions that constrain format innovation.
- Pouches:Stand-up flexible packaging with resealable closures combines portability with portion control, targeting single-serve and on-the-go consumption occasions. Japanese convenience retail and German organic specialists lead adoption for functional cereal positioning.
- Tubs:Rigid plastic containers deliver maximum moisture protection and resealability for high-humidity climates and extended pantry storage, though material intensity conflicts with EU Green Deal circular economy mandates. Hot-climate emerging markets favor tubs despite sustainability penalties.
Boxes maintain structural dominance, while Pouches are climbing the fastest on sustainability and convenience alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breakfast cereal consumption patterns diverge sharply by geography. German and Japanese households prioritize functional fortification and clean-label credentials. American buyers favor convenience and value-tier family formats. Emerging market penetration concentrates on corn-based flakes with extended shelf stability.
United States
FDA nutritional labeling updates and serving-size disclosure rules compel reformulation across heart-health and reduced-sugar SKUs. The agency's health claim substantiation framework shapes beta-glucan fortification investments. Minneapolis-St. Paul anchors North American manufacturing scale with concentrated oat contract processing and extrusion technology deployment.
Germany
EFSA health claim evidence requirements and EU Green Deal sustainability mandates drive clinical trial investments for oat beta-glucan cardiovascular positioning. CSRD-aligned carbon footprint reporting pressures Scope 3 grain sourcing transparency. Cologne and Hamburg clusters lead functional cereal R&D partnerships with university medical centers.
Japan
METI functional food standards and FOSHU regulatory pathways enable proprietary health claim differentiation for soluble fiber formulations. Precision extrusion technology preserves heat-labile micronutrients through cold-processing protocols. Tokyo and Osaka metropolitan demand concentrates subscription direct-to-consumer growth for single-serve fortified formats.
United Kingdom
Post-Brexit regulatory divergence from EFSA frameworks creates parallel compliance costs for dual-labeled export production. HFSS advertising restrictions reshape children's cereal formulation and promotional strategies. Manchester and Birmingham manufacturing corridors balance EU export compliance with domestic clean-label positioning.
Australia
FSANZ nutrition content claims standard governs fiber and whole grain assertions across domestic and Asia-Pacific export markets. Drought cycles in grain-growing regions create input cost volatility for wheat and oat formulations. Sydney and Melbourne urban professionals drive premium granola subscription adoption through health-branded direct-to-consumer channels.
Global Breakfast Cereals Market Vendor Landscape
Capability concentration sits with specialized R&D-intensive processors; scale advantage sits with diversified food conglomerates. The market structures around three tiers: global multinationals with integrated grain sourcing, regional specialists with clinical substantiation partnerships, and private-label manufacturers serving discount retail channels. Dominant competitive moves include backward integration into oat supply contracts and technology licensing for cold-extrusion processing systems.
Among North American-based multinationals, General Mills and Post Holdings exemplify scale-driven manufacturing concentration with captive supply chain control. Nestlé anchors European functional positioning through micronutrient fortification depth. Associated British Foods occupies a mid-tier position balancing heritage brand equity with reformulation adaptation to regulatory divergence. Kellogg Company represents legacy flake-category dominance navigating channel shift toward direct-to-consumer subscription models. PepsiCo diversifies across snack-cereal convergence with extrusion technology cross-application.
| Leading Market Players |
|---|
| PepsiCo |
| B&G Foods |
| General Mills |
| Migros |
| Calbee |
| Nestlé |
| Post Holdings |
| Associated British Foods |
| Kellogg Company |
| Others |
Supply Flow & Price Mechanics
Black Sea wheat supply disruptions function as the dominant risk vector that simultaneously compresses margin pools in economy-tier cornflake formulations and accelerates contract consolidation for premium oat sourcing across North American and European supply chains. This volatility propagates through the value chain as pricing tier spreads widen between commodity-dependent volume SKUs and vertically integrated functional cereal positions.
Pricing Analysis
Contract-based long-term offtake agreements dominate premium oat and granola procurement, locking in beta-glucan-rich grain stocks for heart-health positioning while spot-market exposure concentrates in wheat-based flake categories. Price differentiation hinges on fortification intensity and clean-label certification tier, with EFSA-substantiated cardiovascular claims commanding substantial premia over baseline formulations. Pricing pressure stems from input cost volatility in Australian drought cycles, eroding margins for mid-tier processors lacking captive supply. Family-segment buyers in US supermarkets exhibit highest price sensitivity, whereas Japanese urban professionals in direct-to-consumer channels accept elevated price points for single-serve functional formats.
Supply Chain Analysis
Upstream feedstock concentration centers on Canadian prairie provinces for high-beta-glucan oats, Australian wheat belts, and Midwest US corn production corridors. Raw material dependencies encompass rolled oat groats, milled wheat flour, and maize grits for extrusion bases, with binding systems drawing from certified sustainable palm oil or aqueous alternatives. Single-source vulnerability manifests in North American oat contract consolidation that gives scaled processors preferential access while marginalizing mid-tier buyers. Distribution runs through supermarket planogram-governed retail in the United States and Germany, with direct-to-consumer subscription channels accelerating fastest in Japanese and German metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global breakfast cereals trace a cyclical recovery arc as pantry-loading behaviors among remote workers normalize and subscription replenishment models stabilize demand patterns. Oat supply consolidation and clean-label regulatory tightening function as the twin cyclical drivers resetting competitive positioning.
For Market Incumbents: Pre-empt margin compression in wheat-based volume categories by securing captive oat supply contracts in Canadian growing regions before contract consolidation locks out mid-tier processors. Accelerate cold-extrusion technology licensing to preserve micronutrient retention claims under tightening EFSA substantiation requirements, defending functional positioning against emerging precision-fermentation substitutes. For New Entrants and Emerging Players: Direct-to-consumer subscription channels targeting health-conscious urban professionals in Berlin and Tokyo represent the most penetrable entry point, bypassing supermarket slotting fee barriers that entrench legacy brands. Precision fermentation-enabled protein-fiber matrices offer a go-to-market angle for replicating traditional textures without conventional grain supply dependencies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with verified Scope 3 grain sourcing data and regenerative agriculture partnerships. Long-term viability over the next decade rests on carbon footprint disclosure compliance and clinical substantiation capabilities for health claim differentiation. Watch CSRD-aligned sustainability reporting adoption rates as the signal for regulatory-driven margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Supply | Captive access to Canadian high-beta-glucan grain stocks secures heart-health positioning against contract consolidation. |
| Cold-Extrusion Technology Licensing | Japanese and German processors preserve heat-labile vitamins through sub-40°C processing, compressing R&D-to-shelf timelines. |
| Direct-to-Consumer Subscription Launch | Bypassing US and German supermarket slotting fees enables precision targeting of health-conscious urban professionals. |
| Regenerative Agriculture Partnerships | Verified Scope 3 grain sourcing data creates first-mover advantage under EU Green Deal carbon disclosure mandates. |
| Clinical Substantiation Investment | EFSA randomized controlled trial evidence defends cardiovascular benefit claims against reformulation cost pressures. |
Methodological Framework
The analysis maps granola, oats, cornflakes, and muesli sub-sectors, each validated through procurement directors at North American and European retailers, supply chain planners at grain processors, regulatory affairs leads navigating FDA and EFSA frameworks, and brand managers at functional cereal specialists. Secondary validation draws from FDA nutritional labeling databases, EFSA health claim registers, EU Green Deal sustainability disclosure filings, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down macroeconomic consumption pattern analysis.
Assumptions held fixed include regulatory stringency trajectories for clean-label and carbon disclosure requirements, while oat supply concentration patterns and extrusion technology diffusion rates were varied across sensitivity scenarios. Segmentation dimensions encompass product type, distribution channel, customer archetype, and packaging format, with regional regulatory clusters modeled separately. CAGRs derive from trend extrapolation adjusted for substitution effects from yogurt and protein bar categories. Forecast inputs include pantry-loading normalization rates and subscription channel penetration curves.
Macroeconomic conditions sit as an overlay; deviation in grain commodity price cycles, drought frequency in Australian growing regions, or Black Sea supply stability would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption curves. Cross-checking against customs trade data and retail scanner databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Rice Noodles Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Packaged Food Market