
 Gluten-Free Oats Market | 2026-2036
Gluten-Free Oats Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Oats Market Intelligence
Asset-light contract milling and third-party certified gluten-free processing is reshaping competitive entry in the oats value chain. Bob's Red Mill Natural Foods leverages its dedicated gluten-free facility network to sustain premium positioning across specialty retail channels. General Mills, Inc. anchors volume throughput by integrating Quaker Oats Company sourcing with mass-market distribution scale. Nature's Path Foods differentiates through organic-certified gluten-free oat lines that command shelf space in health food stores.
Gluten-free oats are Avena sativa grains processed, tested, and verified to contain less than 20 parts per million of gluten, typically achieved through optical sorting, mechanical separation, and dedicated handling equipment to prevent cross-contamination with wheat, barley, or rye. The primary commercial purpose is supplying safe grain-based nutrition to celiac patients, gluten-sensitive consumers, and clean-label product developers. Rolled oats occupy the largest volume share among product types due to versatile cooking applications and familiar texture profiles. Online retail channels are expanding fastest as direct-to-consumer subscription models reduce intermediaries and capture margin pools previously held by supermarkets.
The FDA enforces gluten-free labeling standards that mandate rigorous testing protocols and facility segregation, while the USDA oversees organic certification claims often paired with gluten-free positioning. The EPA monitors pesticide residue thresholds relevant to oat cultivation practices that affect export eligibility. Stakeholders must monitor evolving allergen thresholds in international markets and invest in traceability systems that satisfy both domestic and cross-border compliance requirements.
Market Dynamics
Optical sorting and mechanical separation technologies are compressing the cost premium between commodity and certified gluten-free oats, forcing processors to compete on traceability depth rather than purity alone.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The regulation mandates sub-20 ppm thresholds and facility segregation, creating enforceable quality benchmarks that reduce consumer hesitation and expand retail shelf access for compliant products.
- Celiac disease diagnostics:Serological screening expansion in gastroenterology practices is identifying latent cases, converting undiagnosed populations into structured dietary oat consumers with recurring purchase patterns.
- Clean-label bakery reformulation:Commercial bakeries are substituting wheat flour with oat derivatives to meet dual demands for allergen-free positioning and recognizable ingredient declarations on packaged goods.
Market Restraints
- Input cost volatility:Avena sativa seed prices fluctuate with North American planting cycles and drought exposure in the Canadian prairies, squeezing margin buffers for contract millers locked into fixed-price retail agreements.
- Supply concentration risk:Dedicated gluten-free processing capacity clusters in the United States and Canada, leaving buyers in Asia-Pacific and Latin America exposed to currency-adjusted landed costs and extended lead times.
- Cross-contamination detection limits:Current ELISA testing protocols struggle with fermented or hydrolyzed oat matrices, creating regulatory ambiguity for manufacturers developing extended shelf-life products.
Strategic Opportunities
- Brazil ANVISA alignment:Harmonizing Brazilian gluten-free standards with Codex Alimentarius thresholds would unlock import eligibility for North American processors and accelerate category formation in South America's largest retail market.
- Direct-to-consumer subscription channels:E-commerce platforms enable traceability storytelling and recurring revenue capture, bypassing slotting fee structures that disadvantage smaller certified producers in conventional grocery.
- Pulse-oat protein hybridization:Blending pea or lentil isolates with oat bases addresses complete amino acid profiles, opening formulation contracts with sports nutrition and clinical meal replacement developers.
Industry Challenges
- Certification timeline compression:Third-party gluten-free audits require 6-12 month validation cycles, delaying product launches and trapping working capital in inventory awaiting release approval.
- Optical sorting technician scarcity:Near-infrared spectroscopy calibration and maintenance demands specialized skill sets that agricultural engineering programs have not scaled to match equipment deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Oats Market |
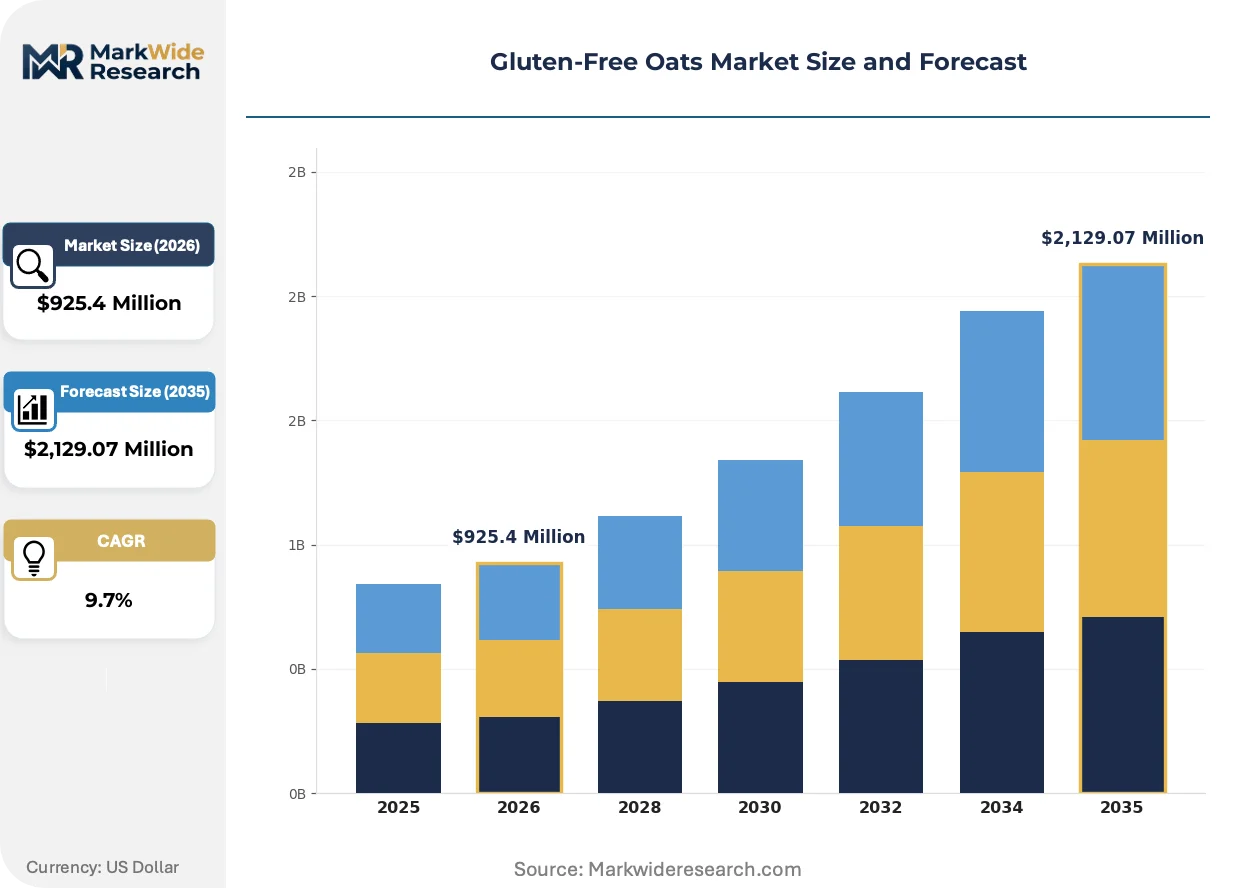
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $2,129.07 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oats, Steel-Cut Oats, Rolled Oats, Whole Grain Oats End User: Households, Food Manufacturers, Restaurants, Food Service Providers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bags, Boxes, Pouches, Bulk |
| Companies Covered | Quaker Oats Company (PepsiCo), Bob's Red Mill Natural Foods, General Mills, Inc., Nature's Path Foods, Glutenfreeda Foods, Bakery On Main, Purely Elizabeth, Freedom Foods Group, GF Harvest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Oats Market Strategic Shifts & Innovations
Processing technology convergence and regulatory precision are redefining competitive advantage away from volume throughput toward verified chain-of-custody documentation and real-time contamination monitoring.
Near-infrared spectroscopy combined with high-speed optical sorters is collapsing the labor cost differential between conventional and certified gluten-free oat processing lines. Mid-scale millers in the United States are retrofitting existing facilities rather than building greenfield dedicated plants, compressing payback periods from seven years to under four. This capital efficiency is enabling regional players to challenge established suppliers on delivery speed and custom blend flexibility.
The EU Green Deal's Farm-to-Fork Strategy is tightening pesticide residue thresholds for cereal imports, forcing oat cultivators to document integrated pest management practices or face exclusion from the European single market. Exporters are responding by securing organic certification as a defensive hedge against evolving Maximum Residue Level schedules. Scandinavian retail buyers now require dual gluten-free and organic credentials as baseline procurement conditions.
Health food stores and specialty grocers are unbundling bulk-bin distribution in favor of pre-packaged certified units with scannable provenance codes. This shift transfers inventory risk from retailers to processors while capturing margin through branded storytelling rather than commodity throughput. The pattern is most pronounced in coastal United States metropolitan markets where consumer willingness to pay for transparency exceeds national averages by measurable margins.
Gluten-Free Oats Market Segmentation
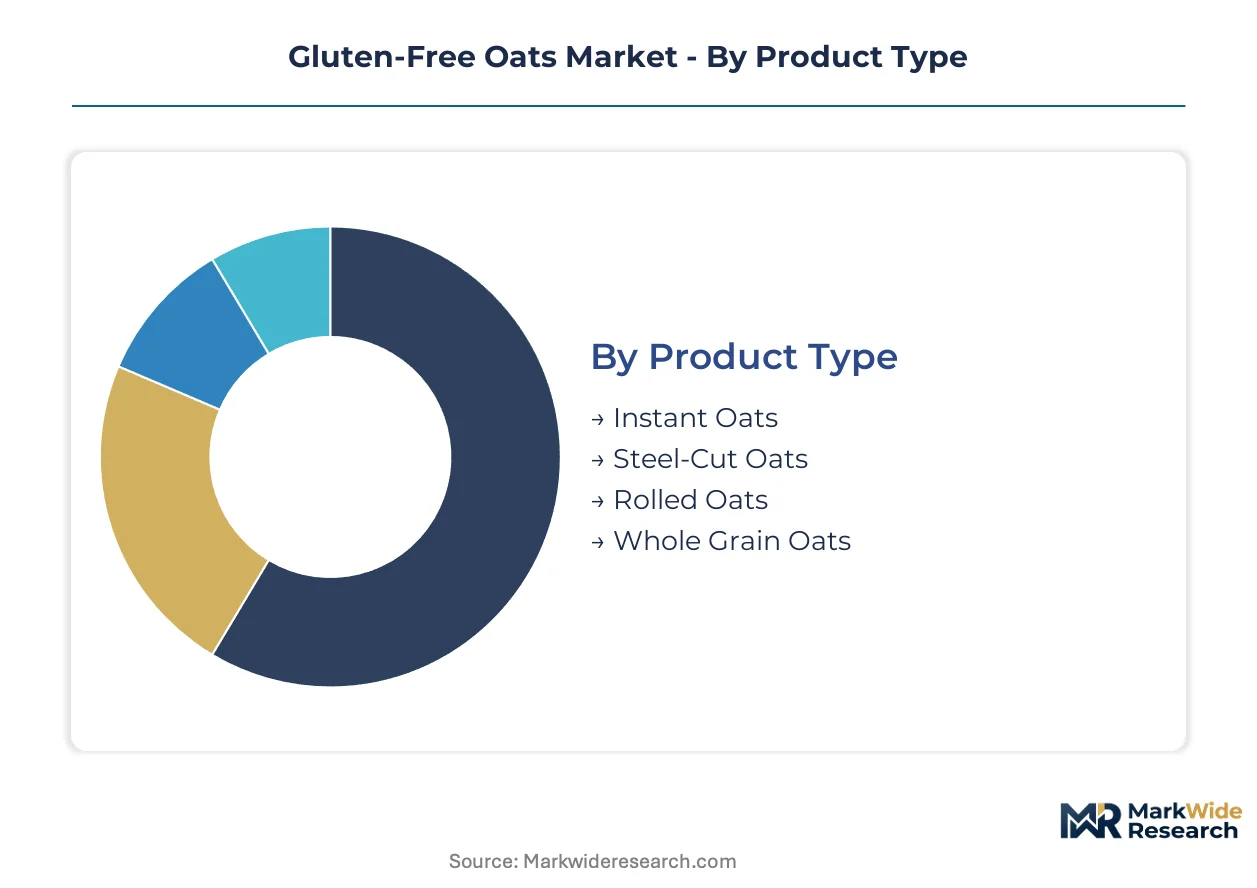
Segmentation in gluten-free oats reveals how processing intensity, buyer sophistication, and channel economics split margin capture across the value chain. Each dimension carries distinct certification burdens and pricing power.
Product Type:
Mature formats dominate volume while emerging formats capture premium positioning through processing complexity.
- Rolled Oats:Steamed and flattened groats that rehydrate quickly for hot cereal and baking applications. Households in the United States drive baseline demand through familiar preparation routines and versatile recipe integration. The FDA's gluten-free labeling compliance is most standardized for this format, reducing retail hesitation.
- Instant Oats:Pre-cooked and dried flakes designed for single-serve microwave preparation. Food manufacturers targeting grab-and-go breakfast segments concentrate procurement here, drawn by portion-control precision and reduced preparation time in commercial settings.
- Steel-Cut Oats:Groats chopped into pinhead pieces requiring longer cooking times but delivering chewier texture. Health food stores and specialty grocers favor this format for premium positioning.
- Whole Grain Oats:Unprocessed groats retaining bran, germ, and endosperm intact. Bulk bin distributors and organic-certified channels handle most volume.
Rolled oats handles the majority of throughput; instant oats is expanding most quickly on share as food manufacturers reformulate convenience lines.
End User:
Cost tier stratification separates high-frequency household purchasers from volume-contracting institutional buyers.
- Households:Individual consumers purchasing for celiac-safe home consumption. Direct-to-consumer subscription channels and online retail platforms are capturing this segment through recurring delivery models and traceability storytelling.
- Food Manufacturers:Commercial bakeries, cereal producers, and snack developers sourcing oat derivatives for ingredient inputs. Clean-label reformulation mandates from major CPG brands are accelerating certified oat flour procurement.
- Restaurants:Full-service and fast-casual operators offering gluten-free menu options. Health food stores and specialty distributors serve this channel with smaller pack sizes.
- Food Service Providers:Institutional caterers, hospital systems, and school nutrition programs. Contract specifications increasingly require third-party gluten-free certification alongside USDA organic credentials.
Food manufacturers command the largest contract volumes; households are climbing the fastest as subscription models bypass traditional retail intermediaries.
Distribution Channel:
Geography of buyer concentration shapes channel investment priority, with coastal metropolitan markets driving premium channel development.
- Supermarkets:Mass-market grocery chains with dedicated gluten-free shelf sets. Slotting fee structures disadvantage smaller certified producers, consolidating shelf access around established suppliers with dedicated facility networks.
- Online Retail:E-commerce platforms and direct-to-consumer brand sites. Traceability documentation and subscription revenue models attract venture-backed oat startups.
- Health Food Stores:Specialty grocers emphasizing organic and allergen-free positioning. Pre-packaged certified units with scannable provenance codes are displacing bulk-bin distribution.
- Specialty Stores:Regional chains and independent retailers serving niche dietary communities. Coastal United States metropolitan markets show highest willingness to pay for transparency premiums.
Supermarkets retain the dominant throughput position; online retail is gaining share fastest as logistics networks reduce delivery friction for heavy grain products.
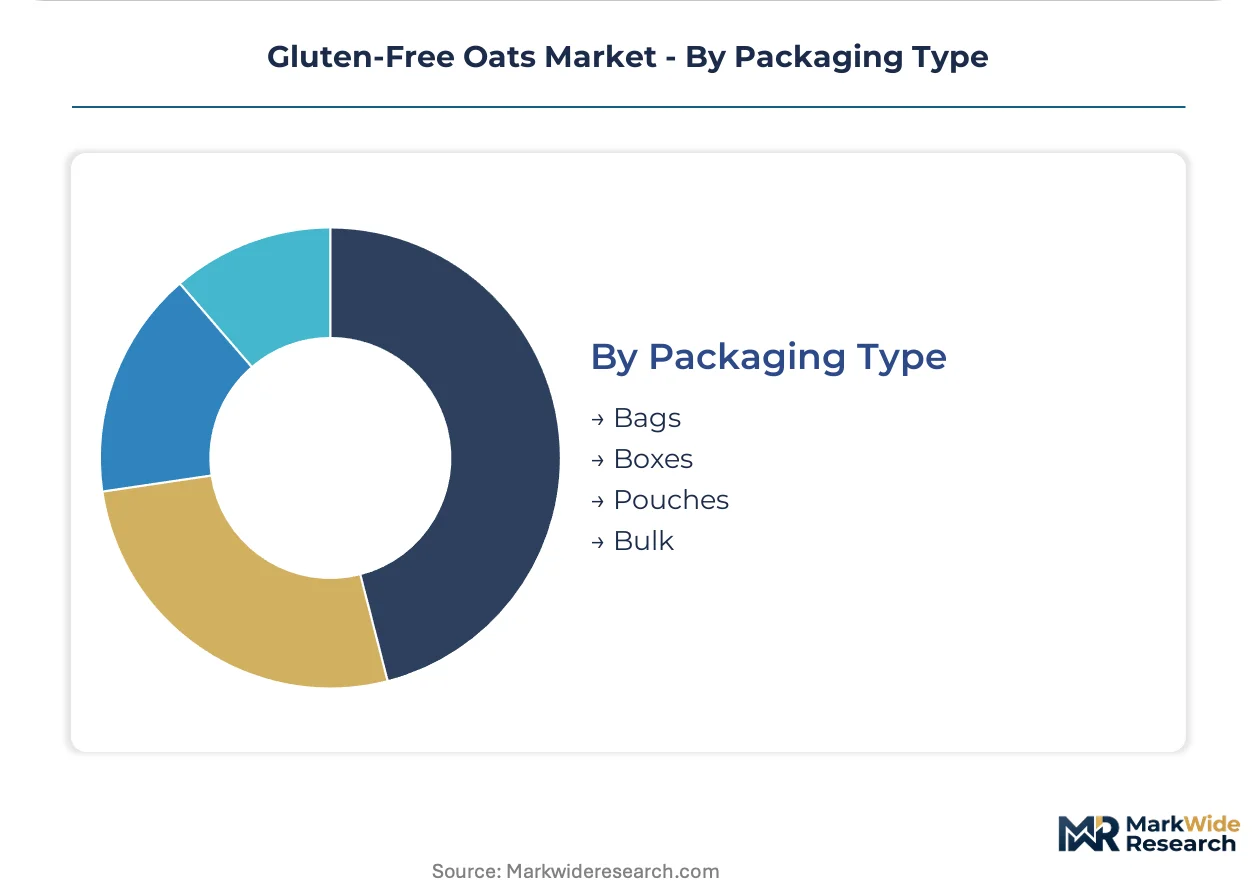
Packaging Type:
Application requirements and margin structure differentiate rigid from flexible formats.
- Bags:Multi-layer paper or plastic sacks for retail shelf presentation. Rolled and instant oats dominate this format.
- Boxes:Rigid cardboard containers with portion-control inner bags. Cereal manufacturers and premium household brands favor this for shelf impact.
- Pouches:Flexible stand-up or flat bags with resealable closures. Single-serve and travel formats are expanding here.
- Bulk:Unpackaged product dispensed from bins or sold in large food-service quantities. Food service providers and some health food stores handle most volume, though pre-packaged certified units are displacing this format in retail.
Bags handle the majority of unit volume; pouches are ascending fastest as on-the-go consumption patterns reshape portion sizing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from North American processing facilities dominate international supply, while import-dependent markets in Europe and Asia-Pacific absorb premium-priced certified volumes. Currency-adjusted landed costs and extended lead times shape procurement decisions outside the production belt.
United States
Health-conscious consumers and robust retail infrastructure sustain category expansion across coastal metropolitan markets. The FDA's gluten-free labeling rule mandates sub-20 ppm thresholds and facility segregation, creating enforceable quality benchmarks. Dedicated gluten-free processing clusters in the Pacific Northwest and Upper Midwest compress delivery timelines for domestic food manufacturers.
Canada
Avena sativa cultivation in the prairie provinces supplies raw grain to cross-border millers, though drought exposure creates input cost volatility. Health Canada and the PMRA oversee pesticide residue thresholds that affect export eligibility to European buyers. Calgary and Winnipeg anchor regional processing capacity serving both domestic health food stores and US contract manufacturers.
Germany
Scandinavian retail buyers sourcing through Hamburg and Rotterdam now require dual gluten-free and organic credentials as baseline procurement conditions. The EU Green Deal's Farm-to-Fork Strategy tightens pesticide residue thresholds for cereal imports. Bavarian and North Rhine-Westphalia distributors are securing integrated pest management documentation to defend European single market access.
Brazil
ANVISA alignment with Codex Alimentarius thresholds would unlock import eligibility for North American processors and accelerate category formation. São Paulo and Rio de Janeiro metropolitan areas concentrate demand from health food stores and specialty grocers. Regulatory harmonization efforts are drawing investment interest from certified oat exporters seeking South American market entry.
Australia
The TGA oversees therapeutic goods claims while FSANZ manages food standards including gluten-free labeling requirements. Sydney and Melbourne health food stores are displacing bulk-bin distribution in favor of pre-packaged certified units with scannable provenance codes. Direct-to-consumer subscription channels from US-based processors are capturing coastal metropolitan demand through reduced delivery friction.
Gluten-Free Oats Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the certified oat value chain. The vendor base separates into three tiers: multinational CPG conglomerates with dedicated facility networks, mid-scale organic-certified millers with regional distribution, and venture-backed direct-to-consumer startups leveraging subscription revenue models. Competitive moves concentrate on backward integration into gluten-free oat cultivation and strategic partnerships with optical sorting technology providers.
Within the multinational tier, Quaker Oats Company and General Mills anchor mass-market volume throughput through integrated sourcing and supermarket shelf dominance. Bob's Red Mill Natural Foods exemplifies the mid-scale specialist archetype with its dedicated gluten-free facility network sustaining premium positioning across specialty retail channels. These three entities collectively represent the spectrum from commodity-scale distribution to certified-origin storytelling.
| Leading Market Players |
|---|
| Quaker Oats Company (PepsiCo) |
| Bob's Red Mill Natural Foods |
| General Mills, Inc. |
| Nature's Path Foods |
| Glutenfreeda Foods |
| Bakery On Main |
| Purely Elizabeth |
| Freedom Foods Group |
| GF Harvest |
| Others |
Cost & Logistics Intelligence
The Pacific Northwest gluten-free processing cluster around Portland and Seattle concentrates dedicated facility capacity, compressing delivery timelines for domestic food manufacturers while amplifying pricing power for certified-origin suppliers serving coastal metropolitan markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the gluten-free oats value chain. Three-tier pricing structure across premium certified-organic, standard gluten-free, and economy-grade conventional tiers separates buyers by certification depth and traceability documentation. Cost compression in the standard tier is intensifying because optical sorting technology adoption collapses purity premiums. Food manufacturers with reformulation mandates show least price sensitivity; institutional food service providers exhibit highest sensitivity due to fixed-budget procurement cycles.
Supply Chain Analysis
Avena sativa seed availability from the Canadian prairies and Upper Midwest growing regions anchors upstream feedstock security for North American processors. Dedicated gluten-free processing draws from optical sorting equipment, ELISA testing protocols, and segregated handling infrastructure as critical component inputs. Single-source vulnerability concentrates in third-party certification audits with six-to-twelve-month validation cycles. Distribution runs through mass-market supermarkets for volume throughput, with direct-to-consumer channels capturing fastest expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free oats market functions as a regulatory-entrenchment defensive moat, where FDA gluten-free labeling compliance creates switching costs that lock food manufacturers into validated supplier relationships.
For Market Incumbents: Harden facility certification networks against emerging contract millers deploying retrofitted optical sorting lines. Expand dedicated gluten-free capacity in the Upper Midwest to compress delivery timelines for institutional food service contracts. Prioritize backward integration into organic-certified oat cultivation to defend margin buffers against prairie drought volatility. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where traceability storytelling commands premium positioning absent slotting fee barriers. Target coastal United States metropolitan markets with highest willingness to pay for transparency documentation. Deploy scannable provenance codes as the primary go-to-market angle to differentiate from bulk-bin commodity suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-scale organic-certified millers with regional distribution density and retrofit capital efficiency. The five-to-ten-year viability window rewards processors with integrated pest management documentation securing European single market access. Watch for ANVISA regulatory harmonization in Brazil as the inflection signal unlocking South American import eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures margin pools and secures EU Farm-to-Fork Strategy compliance for European export eligibility. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while capturing recurring revenue through traceability storytelling. |
| Optical Sorting Technology Partnership | Compresses payback periods from seven years to under four for regional competitive entry. |
| Dual Gluten-Free and Organic Certification | Meets Scandinavian retail buyer baseline procurement conditions defending European market access. |
| Pulse-Oat Protein Hybridization R&D | Opens formulation contracts with sports nutrition developers addressing complete amino acid profiles. |
Research Approach
Operator-level perspectives from plant managers at dedicated gluten-free facilities, procurement leads at commercial bakeries, category buyers at health food stores, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA gluten-free labeling guidance documents, USDA organic certification databases, EPA pesticide residue monitoring data, and customs trade records. Bottom-up volume triangulation across product type and end-user segments converged with top-down value estimates from retail audit data.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around input cost volatility and regulatory harmonization timelines. Segmentation dimensions modeled include product format, end-user cost tier, distribution channel geography, and certification credential combination. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating optical sorting adoption rates and subscription channel penetration as industry-specific forecast inputs.
Sensitivities concentrate around prairie drought exposure affecting seed supply, ELISA testing protocol evolution for hydrolyzed matrices, and ANVISA regulatory alignment progress in Brazil. Cross-checking against FDA enforcement action databases and EU Rapid Alert System for Food and Feed notifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Moringa Products Market
Specialty Foods
Goldenseal Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Halal Products Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Silver Food Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Miso Market