
 Global Turf Protection Market | 2026-2036
Global Turf Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Turf Protection Market Outlook
Qualified turfgrass agronomist supply is collapsing across mature markets, constraining product deployment velocity and forcing manufacturers to embed remote diagnostics into protective systems. Syngenta Group leverages its seed-breeding heritage to anchor premium positioning in erosion control mats. BASF SE competes through polymer chemistry depth that sustains margin capture in permeable sheet formulations.
Global Turf Protection encompasses engineered surface preservation systems—typically comprising UV-stabilized polypropylene or polyethylene substrates with specified tensile strengths exceeding 8 kN/m—designed to maintain playable, vegetated, or graded ground conditions under mechanical stress, climatic exposure, or construction activity. Protective coatings command the largest revenue pool due to recurring reapplication cycles on high-traffic sports fields, while synthetic fibers represent the fastest-expanding category as FIFA-compliant hybrid pitch installations multiply across professional stadium portfolios. Weed barriers occupy a mature, price-pressured niche where The Andersons Inc dominates agricultural channel throughput.
EPA registrations under FIFRA govern pesticide-integrated turf solutions in the United States, while REACH restricts phthalate plasticizers in European-manufactured sheets and ECHA substance evaluations are accelerating reformulation timelines. Municipal procurement teams and sports management companies must monitor evolving per- and polyfluoroalkyl substance restrictions, as these will determine which coating chemistries retain market access across successive compliance phases.
Market Dynamics
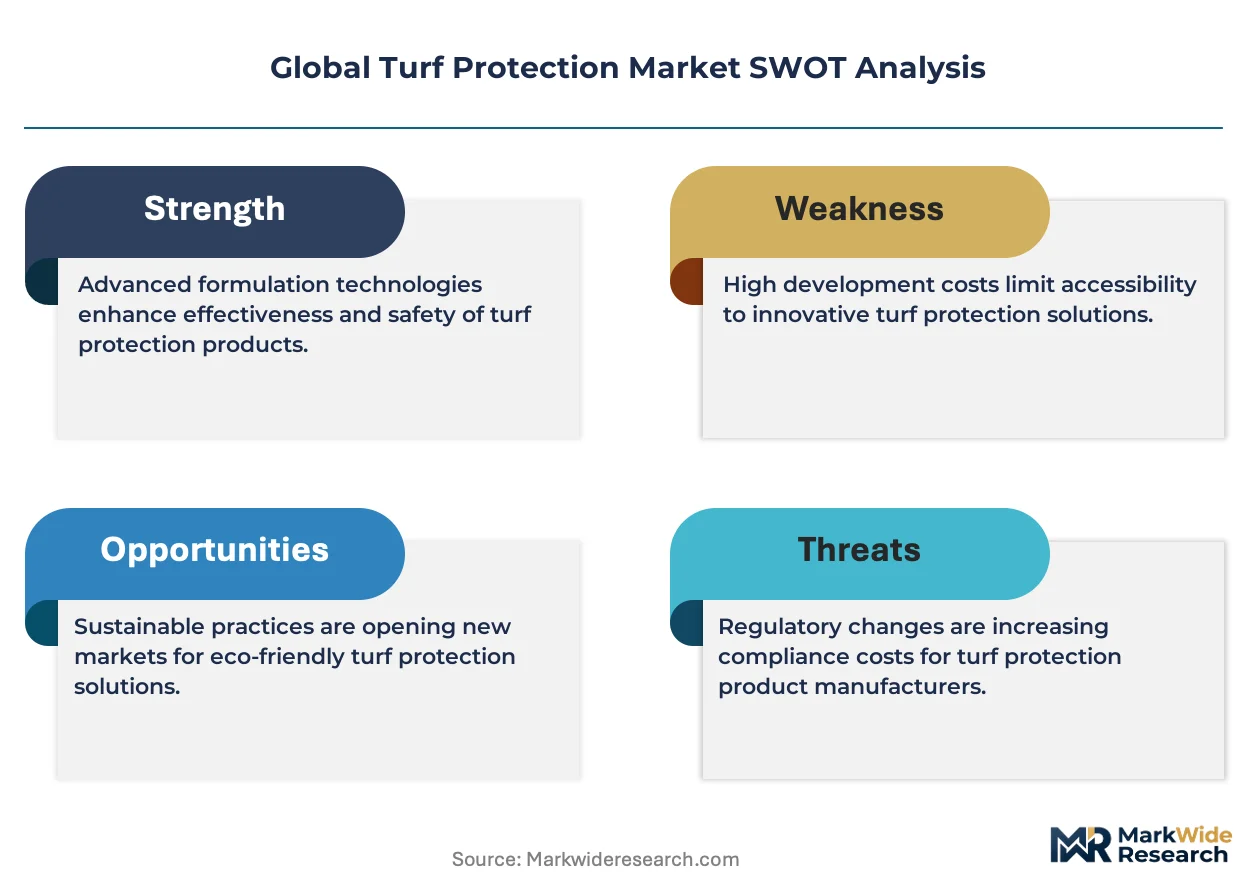
Synthetic fiber reinforcement systems are compressing replacement cycles for natural turf surfaces, while REACH and F-Gas compliance timelines force simultaneous reformulation of protective coating chemistries across European manufacturing bases.
Growth Catalysts
- Hybrid pitch mandates:FIFA-compliant stadium specifications in Germany and Spain require synthetic fiber underlayment for professional certification, pulling demand from municipal budgets into premium procurement tiers.
- California drought resilience:Municipal park systems in Los Angeles and San Diego counties prioritize erosion control mats over re-sodding cycles, embedding turf protection into water conservation infrastructure spending.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents accelerates conversion to water-blown polyurethane backing systems for synthetic turf substrates.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer supply disruptions from Gulf Coast petrochemical complexes transmit directly to geotextile margin compression.
- Phthalate plasticizer restrictions:ECHA substance evaluation timelines under REACH force premature inventory obsolescence for European sheet manufacturers holding legacy PVC formulations.
- Qualified agronomist scarcity:Turfgrass science program enrollment declines in the United States and United Kingdom constrain deployment velocity for technically complex hybrid systems.
Strategic Opportunities
- Texas municipal expansion:Houston and Dallas-Fort Worth park districts are consolidating maintenance contracts, creating bundled procurement vehicles for multi-site turf protection deployment.
- Remote diagnostics integration:IoT soil moisture and compaction sensors embedded in protective matting enable predictive maintenance contracts with sports management companies.
- Per- and polyfluoroalkyl substance transition:PFAS restriction proposals in multiple US states create first-mover advantage for fluorine-free coating chemistry suppliers.
Industry Challenges
- Certification timeline compression:EPA FIFRA registration reviews for pesticide-integrated solutions extend 18-24 months, misaligning product launch windows with seasonal procurement cycles.
- Legacy system interoperability:Retrofitting fiber reinforcement into existing sand-based natural turf rootzones requires custom engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Turf Protection Market |
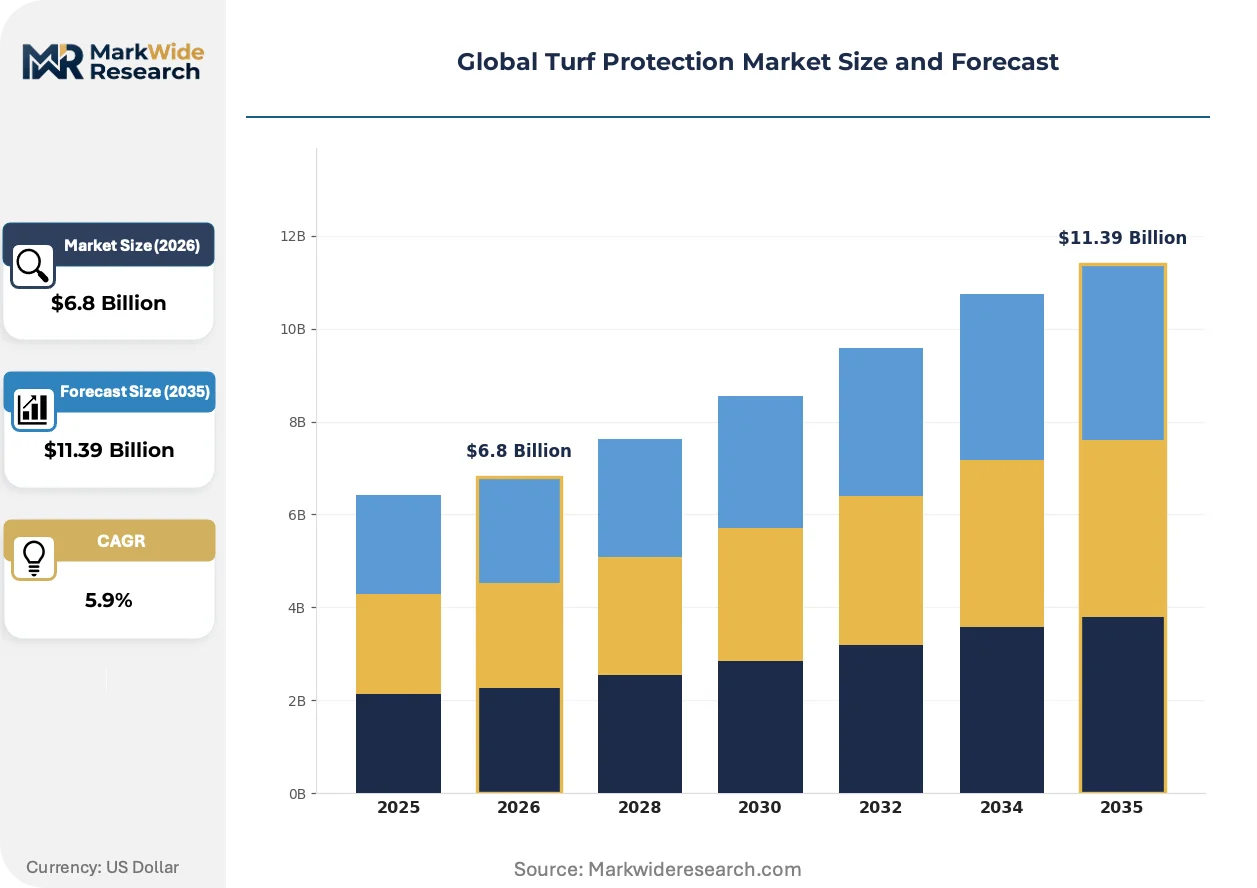
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Coatings, Synthetic Fibers, Permeable Sheets, Erosion Control Mats, Weed Barriers Application: Golf Courses, Sports Fields, Landscaping, Construction Sites, Parks & Recreation End User: Groundskeepers, Construction Contractors, Municipal Authorities, Sports Management Companies Distribution Channel: Specialty Retailers, Agricultural Suppliers, Online Platforms, Direct Sales |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, UPL Limited, Corteva Agriscience, Nufarm, FMC Corporation, The Andersons Inc, AMVAC Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Turf Protection Market Strategic Shifts
Material science convergence with digital monitoring is collapsing the feedback loop between turf stress detection and protective system deployment, compressing maintenance response times from weeks to hours.
Biodegradable erosion control matrices derived from coir and jute fiber blends are miniaturizing the environmental footprint of temporary slope stabilization. Highway construction contractors in Florida and Georgia specify these materials for shoulder stabilization during widening projects. The technology is miniaturizing disposal costs and regulatory liability for infrastructure developers managing vegetated cut-and-fill transitions.
REACH authorization requirements for diisocyanates in polyurethane systems force coating manufacturers toward aliphatic alternatives. German and Dutch formulators face 2023 sunset dates for uncontrolled consumer use, pushing industrial turf applications into tighter supply chains. Sports field managers in the Netherlands report 12-week lead time extensions as qualified applicator certification programs scale.
Performance-based service contracting now dominates professional stadium procurement in England and Spain. Facility operators contract guaranteed playable hours rather than purchasing materials, transferring surface integrity risk to turf protection vendors. This model concentrates vendor selection around remote monitoring capabilities and compresses pricing transparency across the supply base.
Global Turf Protection Market Segmentation
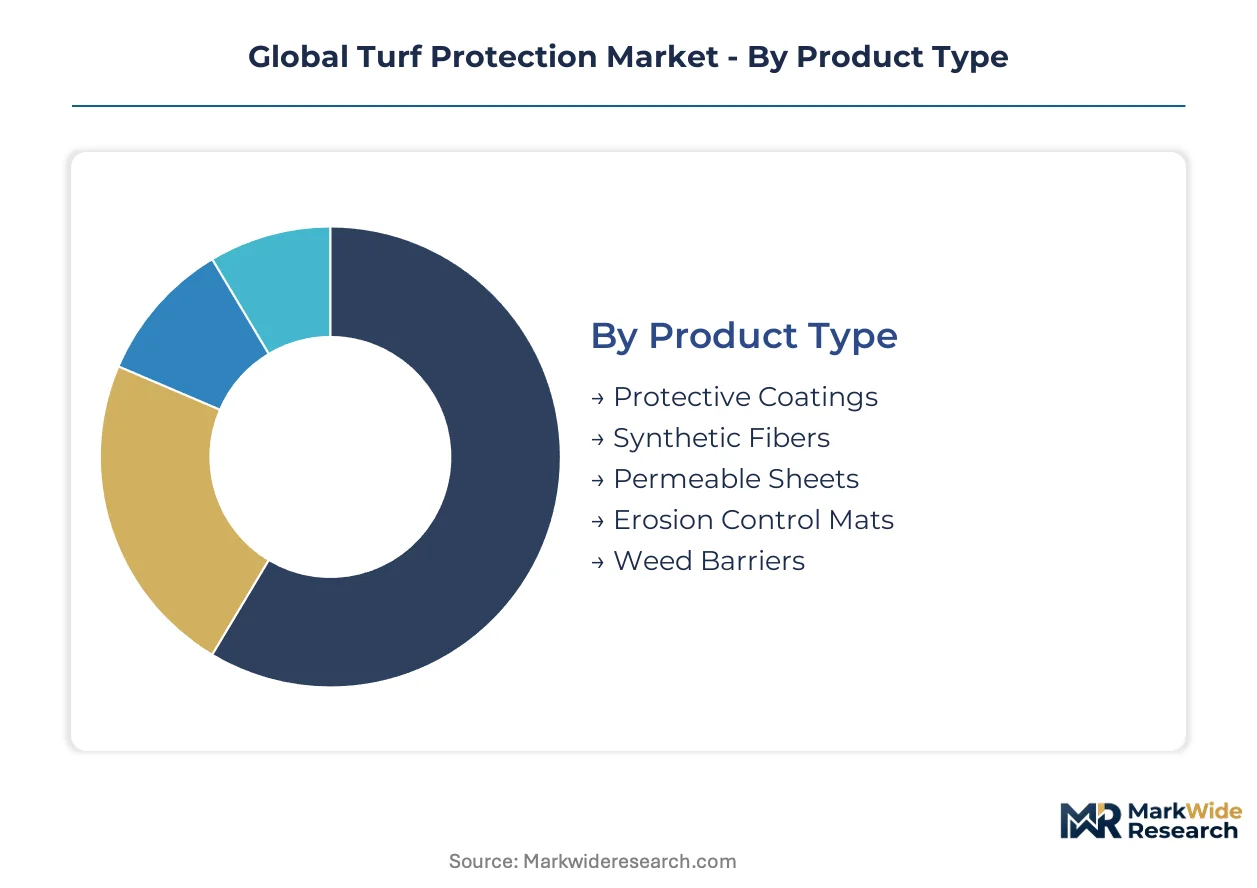
Segmentation reveals how margin pools concentrate in recurring-revenue chemistries versus capital-intensive fiber systems. Turf protection vendors calibrate R&D allocation across product physics, application stress profiles, and procurement authority types.
Product Type:
Margin pools concentrate in formulations requiring frequent reapplication and technical compliance certification.
- Protective Coatings:UV-stabilized polyurethane or acrylic formulations with specified abrasion resistance maintain playable surface integrity under cleat traffic. Municipal park systems in California and Texas specify these for drought-resilient field management, embedding coatings into water conservation infrastructure budgets.
- Synthetic Fibers:Polypropylene or polyethylene monofilaments with tensile strengths exceeding 8 kN/m anchor hybrid pitch systems. FIFA-compliant stadium specifications in Germany and Spain mandate fiber underlayment for professional certification, pulling procurement into premium tiers with extended performance guarantees.
- Permeable Sheets:Geotextile substrates manage drainage and rootzone stability for construction-phase turf preservation.
- Erosion Control Mats:Coir and jute fiber blends stabilize vegetated slopes during highway widening projects in Florida and Georgia.
- Weed Barriers:Agricultural channel products face mature pricing pressure with limited differentiation scope.
The dominant share belongs to Protective Coatings, while Synthetic Fibers is closing the gap fastest.
Application:
Volume concentrates where surface integrity directly affects revenue generation or regulatory compliance.
- Sports Fields:Professional stadium operators in England and Spain contract guaranteed playable hours rather than purchasing materials, transferring surface integrity risk to vendors with embedded remote monitoring. This performance-based model concentrates vendor selection around predictive maintenance capabilities.
- Golf Courses:Turfgrass agronomists specify hybrid reinforcement for high-traffic fairway corridors and tournament preparation zones. Qualified agronomist scarcity in the United States and United Kingdom constrains deployment velocity for technically complex systems.
- Construction Sites:Temporary slope stabilization drives biodegradable mat demand for shoulder stabilization during infrastructure projects.
- Parks & Recreation:Municipal consolidation in Houston and Dallas-Fort Worth creates bundled procurement vehicles for multi-site deployment.
- Landscaping:Residential and commercial aesthetic turf management operates at lower specification tiers with price-sensitive procurement.
Sports Fields commands the largest revenue commitment, with Golf Courses expanding most quickly as tournament standards tighten.
End User:
Procurement authority determines specification complexity and contract structure.
- Sports Management Companies:Facility operators bundle surface integrity risk into service contracts with embedded IoT soil moisture and compaction sensors, enabling predictive maintenance revenue streams.
- Municipal Authorities:Park districts in Los Angeles and San Diego counties prioritize erosion control over re-sodding cycles, embedding turf protection into drought resilience spending.
- Construction Contractors:Highway widening projects in Florida and Georgia specify biodegradable matrices to miniaturize disposal costs and regulatory liability.
- Groundskeepers:Direct technical users influence specification but lack centralized procurement authority in fragmented maintenance operations.
Sports Management Companies drive premium tier adoption, while Municipal Authorities are consolidating fastest into bundled contracts.
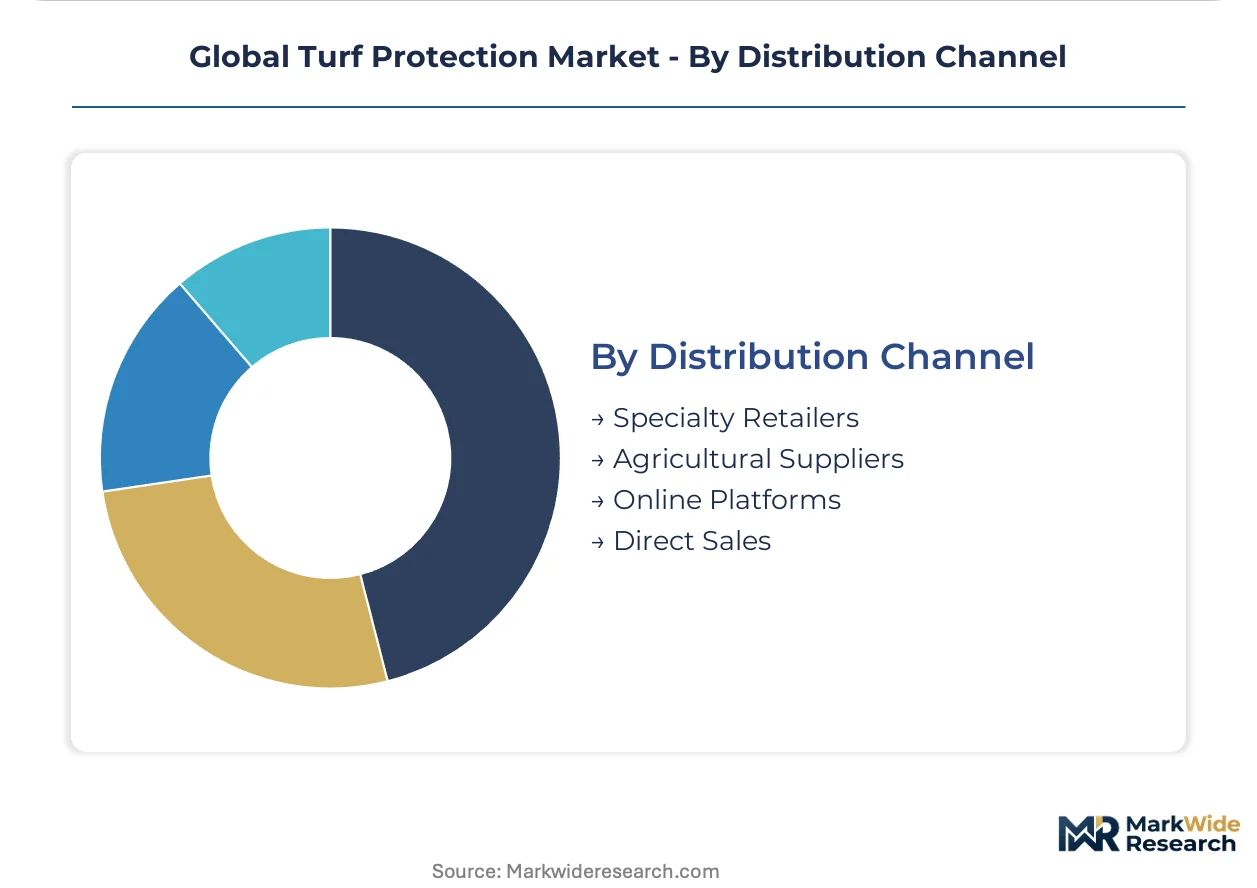
Distribution Channel:
Channel selection tracks customer technical sophistication and order scale.
- Direct Sales:Large stadium operators and municipal consolidations require custom engineering for retrofitting fiber reinforcement into existing sand-based rootzones.
- Agricultural Suppliers:Weed barrier volume moves through established crop protection distribution networks with price-competitive positioning.
- Specialty Retailers:Technical product lines with applicator certification requirements, particularly for REACH-compliant polyurethane systems in the Netherlands.
- Online Platforms:Standardized products with clear specifications and lower technical support requirements.
Direct Sales captures the highest value contracts, while Agricultural Suppliers maintain volume leadership in commoditized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and the Netherlands where REACH compliance costs filter into specification premiums, while cost-sensitive procurement in Texas and Florida compresses margins for standardized matting products.
United States
Municipal park systems in Los Angeles and San Diego counties embed erosion control mats into drought resilience infrastructure spending. EPA FIFRA registrations govern pesticide-integrated coating formulations with 18-24 month review timelines. Houston and Dallas-Fort Worth park districts consolidate maintenance contracts into bundled multi-site procurement vehicles.
Germany
FIFA-compliant stadium specifications in Munich and Dortmund mandate synthetic fiber underlayment for professional pitch certification. ECHA substance evaluations under REACH force aliphatic polyurethane conversions with 2023 sunset dates for legacy diisocyanate systems. Sports field managers in the Netherlands report 12-week lead time extensions as qualified applicator certification programs scale.
Spain
Professional stadium operators in Madrid and Barcelona contract guaranteed playable hours rather than purchasing materials directly. Performance-based service contracting transfers surface integrity risk to vendors with embedded remote monitoring capabilities. Facility procurement teams prioritize predictive maintenance capabilities over upfront material costs.
United Kingdom
Turfgrass science program enrollment declines constrain deployment velocity for technically complex hybrid reinforcement systems. Qualified agronomist scarcity across England and Scotland forces manufacturers to embed remote diagnostics into protective system offerings. Golf course superintendents in Surrey and Kent specify hybrid reinforcement for high-traffic tournament preparation zones.
China
Dual carbon goals under MEE accelerate specification of biodegradable erosion control matrices for highway shoulder stabilization projects. Infrastructure contractors in Guangdong and Jiangsu provinces prioritize coir and jute fiber blends to miniaturize disposal costs. NMPA-equivalent material standards govern synthetic turf substrate imports for professional sports venue construction.
Global Turf Protection Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the turf protection value chain. The market structures around three tiers: integrated agrochemical conglomerates with seed-breeding heritage, polymer chemistry specialists with formulation depth, and regional fabricators with agricultural channel access. Strategic moves concentrate on portfolio diversification into remote diagnostics and geographic expansion through municipal procurement consolidation.
Within the integrated agrochemical tier, Syngenta Group and Bayer AG exemplify players leveraging upstream seed-breeding capabilities to anchor premium positioning in erosion control and hybrid pitch systems. BASF SE represents the polymer chemistry archetype with depth in polyurethane and acrylic formulation science. Among agricultural channel specialists, The Andersons Inc occupies a position exemplifying volume leadership in commoditized weed barrier segments through established crop protection distribution networks.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| UPL Limited |
| Corteva Agriscience |
| Nufarm |
| FMC Corporation |
| The Andersons Inc |
| AMVAC Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin capacity utilization at Gulf Coast petrochemical complexes shapes both supply concentration and price floors across geotextile manufacturing. Scale economies in propylene monomer production anchor cost structures for synthetic fiber suppliers, while REACH compliance investments in European formulators create specification premiums that insulate margin pools from commoditization pressure.
Pricing Analysis
The customization-premium spread separates configured-to-order hybrid pitch systems from standardized erosion control matting. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FIFA-compliant stadium specifications commanding substantial premiums over municipal park procurement. Price differentiation stems from applicator certification requirements and embedded remote monitoring capabilities. Cost compression in standard-grade permeable sheets is intensifying because of polypropylene feedstock volatility. Municipal authorities exhibit highest price sensitivity, while professional sports management companies prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory lead times for aliphatic polyurethane systems have extended substantially as Dutch and German formulators convert from legacy diisocyanate chemistries. Manufacturing concentration rests on Germany, the Netherlands, and the United States for REACH-compliant coating formulations, with China and India supplying coir and jute fiber blends for biodegradable erosion control matrices. Raw material dependencies include propylene monomer, UV-stabilized polyethylene, and water-blown polyurethane precursors. Single-source vulnerability in qualified applicator certification programs creates bottleneck risk for European deployment. Distribution runs through direct sales for stadium operators, agricultural suppliers for weed barriers, and specialty retailers for certified coating systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through municipal procurement consolidation in Texas and performance-based contracting in English and Spanish stadium markets, fragmenting vendor pricing leverage.
For Market Incumbents: Shield margin pools by embedding IoT soil moisture sensors into protective matting offerings, converting transactional sales into predictive maintenance subscriptions. Accelerate backward integration into UV-stabilized polymer compounding to offset propylene monomer volatility. Prioritize REACH-compliant applicator certification programs to capture specification premiums as ECHA substance evaluations tighten. For New Entrants and Emerging Players: Remote diagnostics capability gaps among legacy formulators create entry opportunities for technology-native competitors. Target bundled municipal contracts in Houston and Dallas-Fort Worth park districts where consolidation has outpaced incumbent service adaptation. Lead with fluorine-free coating chemistry to capture first-mover advantage as PFAS restrictions multiply across US states. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer chemistry specialists with formulation depth over agricultural channel generalists. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Monitor ECHA authorization timelines for diisocyanate alternatives as inflection indicator for European manufacturing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Conversion | Aliphatic polyurethane transitions secure market access as ECHA sunset dates approach. |
| Remote Diagnostics Integration | IoT sensor embedding enables predictive maintenance contracts with sports management companies. |
| Backward Integration into Polymer Compounding | In-house UV-stabilized resin production insulates margins from Gulf Coast feedstock volatility. |
| Applicator Certification Program Scaling | Qualified technician pipelines reduce lead time compression in Netherlands and Germany. |
| Fluorine-Free Coating Development | PFAS-free chemistry captures procurement preference as state-level restrictions emerge. |
Study Parameters
Desk research of customs trade data, EPA FIFRA registration filings, and ECHA substance evaluation databases preceded structured interviews with sports field managers, municipal procurement officers, turfgrass agronomists, and polymer formulation chemists. Primary fieldwork with stadium operators in England and Spain validated performance-based contracting trends, while secondary triangulation against REACH compliance timelines and propylene monomer price series anchored supply cost assumptions. Bottom-up unit economics for hybrid pitch installations were cross-referenced against top-down municipal infrastructure spending forecasts.
Variance decomposition across product type, application stress profile, and procurement authority type structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Modeled dimensions include protective coating chemistry class, fiber reinforcement tensile specification, and end-user contracting structure. Industry-specific inputs incorporated FIFA stadium certification mandates and California drought resilience infrastructure allocations.
Forecasts assume regulatory continuity in REACH, EPA FIFRA, and EU F-Gas frameworks; material policy shifts would require re-modeling of coating chemistry conversion timelines and import substitution patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Pest Resistant Crops Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Herbicides Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Fogger Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Fumigation Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
North America Crop Protection Chemicals Market