
 Pre-Emergent Herbicide Market | 2026-2036
Pre-Emergent Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Emergent Herbicide Market Analytics
Consolidation among North American row-crop growers is recalibrating procurement patterns across the pre-emergent herbicide value chain. Bayer AG leverages its integrated seed-and-chemistry platform to bundle traited seeds with residual herbicide programs. Syngenta AG anchors its position through deep R&D investment in novel sites of action for resistance management. BASF SE competes aggressively in the soybean pre-emergent segment with specialized formulations targeting waterhemp and Palmer amaranth.
Pre-emergent herbicides are residual agrochemicals applied to soil before weed seed germination, functioning through root and shoot absorption to inhibit cell division or protein synthesis in susceptible seedlings; active ingredients such as dinitroanilines, chloroacetamides, and triazines typically require incorporation into the top two inches of soil for optimal efficacy. Their primary commercial purpose is to reduce early-season weed competition and extend the application window for post-emergent treatments. Liquid formulations dominate volume sales due to compatibility with precision spray equipment, while soil application methods command the largest share of value as growers prioritize targeted placement over broadcast foliar treatments. The oilseeds crop type represents the fastest-growing demand pool, driven by canola and soybean expansion in South America and Eastern Europe.
The EPA governs pre-emergent herbicide registration through FIFRA-mandated ecological risk assessments, while the EU's REACH framework and Sustainable Use Directive constrain atrazine and acetochlor availability across member states. Brazil's national health surveillance agency, ANVISA, imposes residue limits that directly shape which chemistries grain exporters can deploy. Stakeholders must monitor evolving resistance profiles and regulatory phase-outs to reallocate R&D spending toward next-generation molecules with favorable toxicological profiles.
Market Dynamics
Glyphosate-resistant weed proliferation across major row-crop geographies is forcing growers to rebuild their herbicide programs around residual chemistry stacks rather than single-mode post-emergent applications.
Growth Catalysts
- Herbicide Resistance Management Protocols:University extension services in Iowa, Illinois, and Indiana now mandate pre-emergent layering for soybean and corn rotations, institutionalizing demand for residual chemistries.
- Brazil's No-Till Expansion:The Cerrado and Matopiba regions require soil-applied residual control to manage weed pressure in zero-tillage systems where mechanical cultivation is impossible.
- EPA Atrazine Re-registration:Ongoing ecological risk assessments are accelerating grower migration toward metolachlor, pendimethalin, and pyroxasulfone alternatives ahead of potential use restrictions.
Market Restraints
- Active Ingredient Concentration:Three manufacturers control over 70% of global dinitroaniline and chloroacetamide technical production, creating supply vulnerability for formulators.
- Soil Incorporation Requirements:Mechanical incorporation or rainfall-dependent activation limits application windows and raises equipment costs for growers without precision tillage capability.
- EU REACH Restrictions:The European Chemicals Agency's classification of acetochlor and atrazine as substances of very high concern has eliminated these chemistries from member state crop protection programs.
Strategic Opportunities
- Ukrainian Black Belt Expansion:Large-scale commercial farming in Chernihiv and Poltava oblasts is adopting Western crop protection protocols, creating first-mover advantage for residual herbicide portfolios.
- Biological-Residual Combinations:Integration of microbial bioherbicides with synthetic pre-emergents offers reduced load rates and improved resistance management profiles for organic-transitioning operations.
- Precision Application Equipment:Section-control sprayers and variable-rate technology enable targeted soil placement that improves efficacy and reduces off-target movement liability.
Industry Challenges
- Resistance Monitoring Infrastructure:Systematic herbicide resistance testing requires sustained investment in regional diagnostic laboratories and trained field agronomists that many extension systems lack.
- Formulation Stability:Extended residual activity demands sophisticated encapsulation and controlled-release technologies that strain R&D timelines and manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Emergent Herbicide Market |
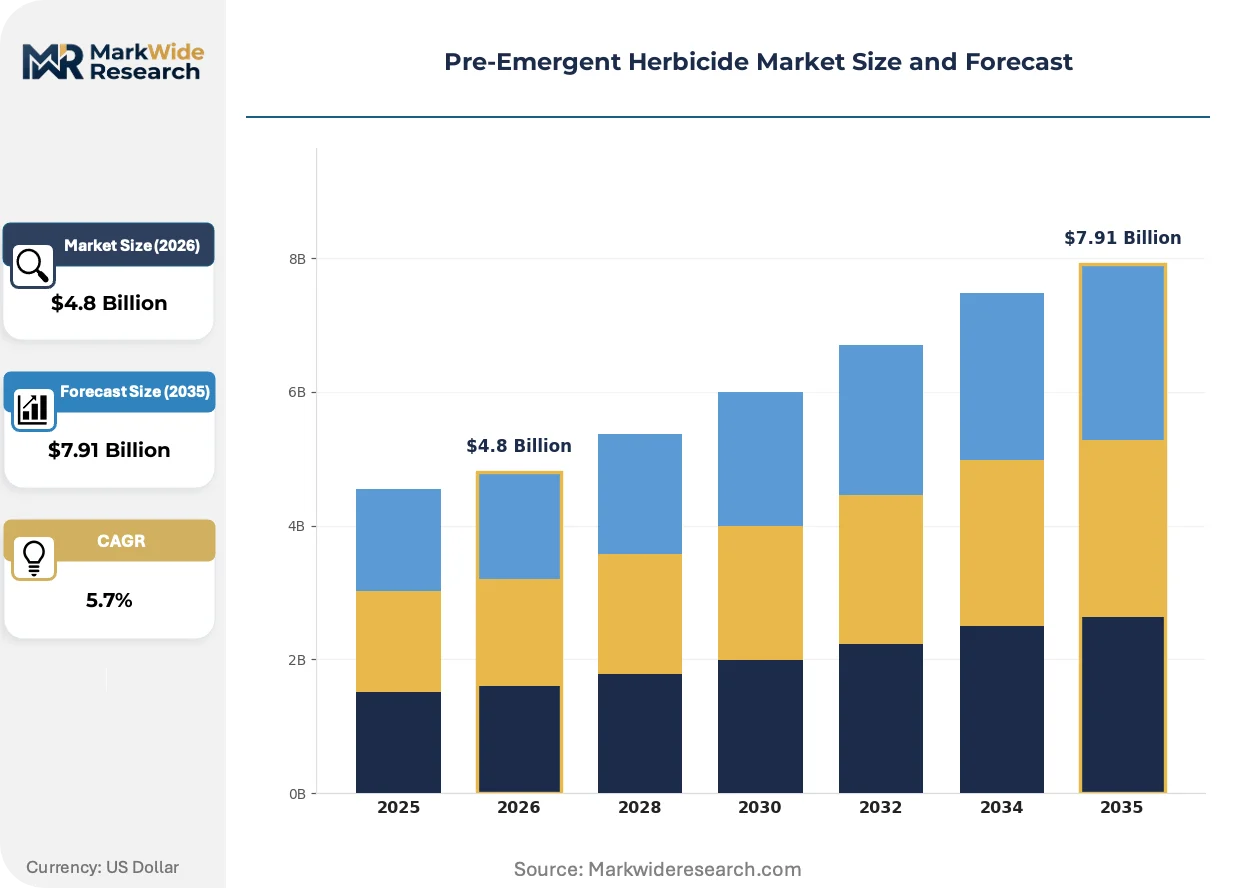
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
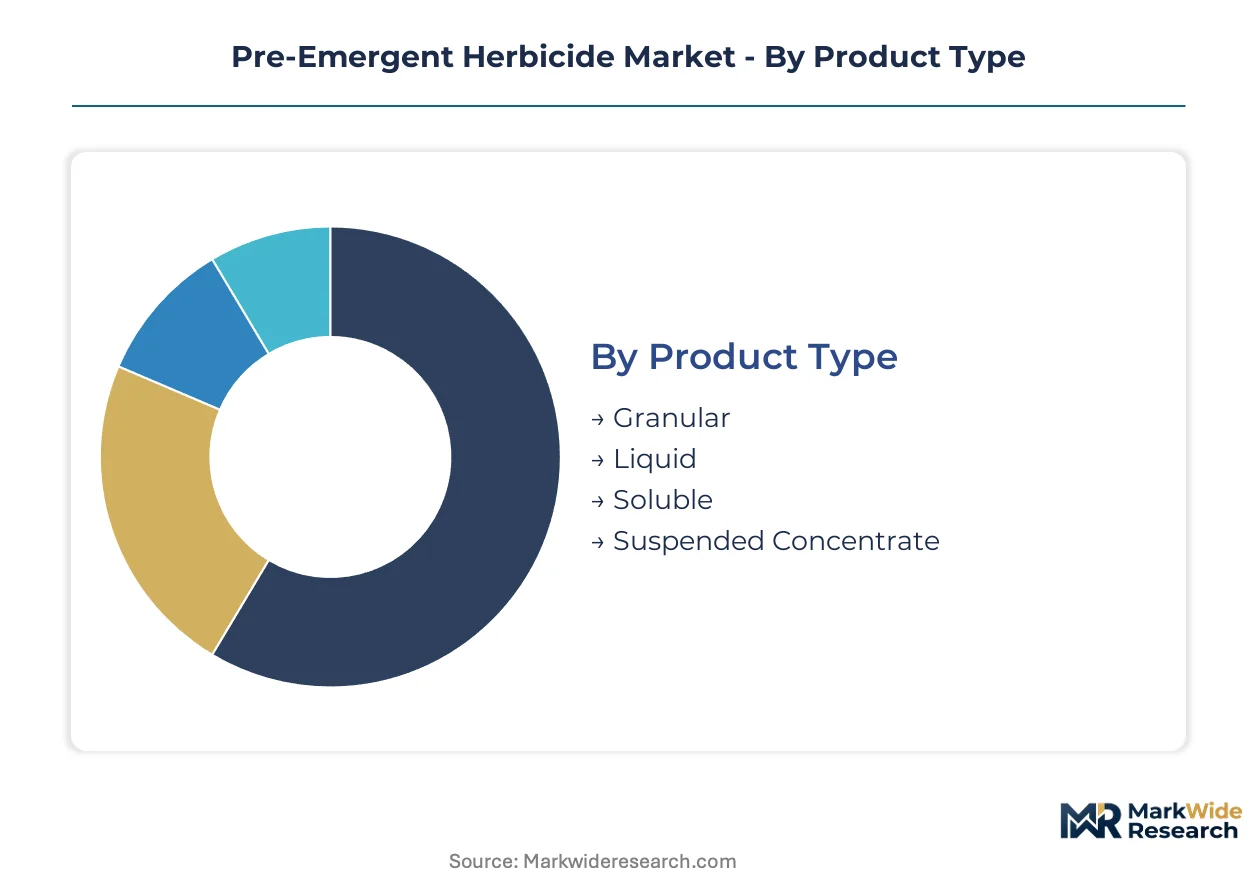
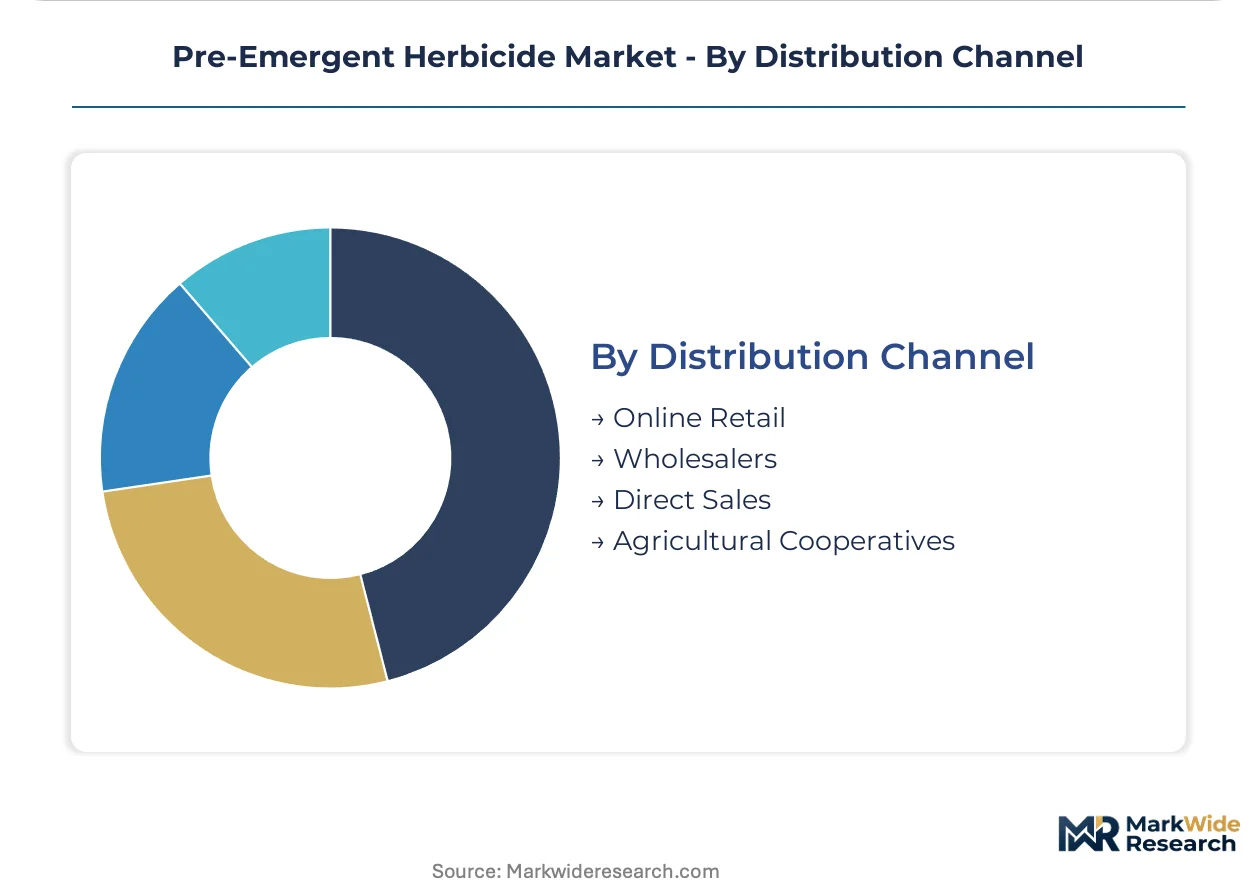
| Segmentation | Product Type: Granular, Liquid, Soluble, Suspended Concentrate Application Method: Foliar, Soil Application, Chemigation, Surface Application Crop Type: Cereal Crops, Oilseeds, Fruits, Vegetables Distribution Channel: Online Retail, Wholesalers, Direct Sales, Agricultural Cooperatives |
| Companies Covered | Bayer AG, Syngenta AG, BASF SE, Corteva Agriscience, FMC Corporation, Nufarm Limited, Adama Agricultural Solutions Ltd., Sumitomo Chemical Co., Ltd., UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Emergent Herbicide Market Evolving Landscape
Novel sites of action and precision application technologies are restructuring how residual herbicides are formulated, delivered, and integrated into broader weed management systems across major agricultural economies.
Microencapsulated pendimethalin and metolachlor formulations are consolidating grower preference in North American corn and soybean markets. These delivery systems extend soil residual activity from 4-6 weeks to 8-10 weeks, enabling growers to delay post-emergent applications until optimal weed size. Bayer and Syngenta field programs demonstrate 15-20% reduction in total herbicide applications per season, compressing the market toward premium formulation tiers.
EPA's 2024 ecological risk assessment for triazine herbicides is accelerating regulatory displacement of atrazine-dependent programs. The agency's proposed aquatic ecosystem buffers and seasonal application windows would restrict use across 60% of current corn acreage. Growers in Minnesota, Wisconsin, and the Chesapeake Bay watershed are already transitioning to HPPD-inhibitor and PPO-inhibitor residual stacks.
Consolidated procurement through grower cooperatives and regional agronomy retailers is displacing traditional distributor channels in the US Corn Belt. CHS, Growmark, and Landus cooperative systems now negotiate direct manufacturer contracts for private-label pre-emergent formulations. This concentration is most pronounced in Iowa and Nebraska, where three cooperatives control 40% of crop input purchasing.
Pre-Emergent Herbicide Market Segmentation
Pre-emergent herbicide purchasing patterns diverge sharply across formulation chemistry, application infrastructure, and crop-specific resistance pressures. Understanding these segment boundaries clarifies where manufacturers must deploy distinct R&D and commercial resources.
Product Type:
Reformulation cycles are accelerating as growers replace older emulsifiable concentrates with precision-compatible delivery systems that reduce off-target movement and extend residual windows.
- Liquid:Emulsifiable and microencapsulated liquid formulations dominate commercial corn and soybean programs in Iowa and Illinois, where compatibility with pulse-width modulation sprayers enables variable-rate application. Demand concentrates among large-scale operations seeking tank-mix flexibility with post-emergent chemistries.
- Granular:Clay-based and polymer-coated granules deliver pendimethalin and dinitroanilines in Brazil's Cerrado no-till systems where aerial application or mechanical incorporation is impractical. Formulation stability under high-temperature storage drives procurement decisions among distributors serving Matopiba expansion zones.
- Soluble:Water-soluble packets and dry flowables target specialty vegetable producers in California's Central Valley who require rapid dissolution for drip chemigation systems.
- Suspended Concentrate:Oil-based suspensions of chloroacetamides serve Eastern European canola growers needing cold-weather stability during early spring application windows.
Volume placements concentrate in Liquid; the faster expansion belongs to Granular.
Application Method:
Equipment replacement cycles are shifting investment from broadcast ground rigs to precision soil placement systems that reduce active ingredient rates per acre.
- Soil Application:Shallow incorporation or surface banding of residual chemistries commands premium pricing in North American corn belts where glyphosate-resistant waterhemp mandates pre-plant programs. Equipment manufacturers in Nebraska and Kansas report strongest order flows for coulter-mounted application systems.
- Chemigation:Injection of pre-emergent herbicides through center-pivot and drip systems is expanding fastest in Texas High Plains cotton and Kansas corn, where water constraints favor combined irrigation-chemistry operations.
- Foliar:Limited residual activity from foliar-applied pre-emergents restricts use to niche potato and vegetable seedbeds in Idaho and Washington's Columbia Basin.
- Surface Application:Rainfall-dependent activation without incorporation persists in Australia's winter grain belt where conservation tillage protocols prohibit soil disturbance.
Soil Application anchors current revenue; Chemigation is climbing the fastest as irrigation infrastructure spreads.
Crop Type:
Rotation economics and export market access are reshaping which crop systems justify premium residual chemistry investments.
- Oilseeds:Soybean and canola expansion in Brazil's Matopiba and Ukraine's Poltava oblasts is institutionalizing pre-emergent stacking against Palmer amaranth and kochia. ANVISA residue limits and EU import tolerances directly shape which chloroacetamide and HPPD-inhibitor chemistries gain regulatory clearance.
- Cereal Crops:Winter wheat and corn rotations in US Corn Belt states maintain baseline demand for atrazine alternatives as EPA ecological assessments restrict triazine use near aquatic systems.
- Vegetables:Leafy green and brassica producers in California and Arizona face the strictest residue thresholds, favoring microbial-synthetic combinations with reduced load rates.
- Fruits:Orchard and vineyard systems in Washington and Chile's Central Valley employ directed spray applications of residual herbicides in row middles, with organic transition pressures limiting synthetic chemistry windows.
Cereal Crops generate the largest absolute volumes; Oilseeds are gaining share fastest on South American and Eastern European expansion.
Distribution Channel:
Procurement consolidation is compressing margin structures for traditional distributors while rewarding direct manufacturer relationships and cooperative scale.
- Agricultural Cooperatives:CHS, Growmark, and Landus systems in Iowa and Nebraska negotiate private-label formulations and volume rebates that displace independent distributor margins. Cooperative agronomists now specify residual programs as part of bundled input packages.
- Direct Sales:Bayer and Syngenta field representatives contract directly with operations exceeding 10,000 acres, embedding herbicide programs within seed trait licensing agreements.
- Wholesalers:Regional distributors in Brazil's Mato Grosso and Goiás maintain relevance through credit extension and localized formulation services for mid-scale soybean growers.
- Online Retail:E-commerce platforms capture generic pre-emergent volumes from price-sensitive hobby farmers and specialty crop producers in secondary US markets.
Agricultural Cooperatives command the dominant placement volume; Direct Sales is expanding most quickly among consolidated farming operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chloroacetamide technical production concentrates in China's Jiangsu and Zhejiang provinces, supplying formulators across Asia-Pacific and Latin America. Brazil's Cerrado and Ukraine's Black Belt now drive fastest adoption of residual weed control programs.
United States
Iowa and Illinois soybean growers stack pre-emergent chemistries against glyphosate-resistant waterhemp and Palmer amaranth. EPA ecological risk assessments for triazine herbicides are accelerating grower migration toward metolachlor and pendimethalin alternatives. The Corn Belt's cooperative procurement systems in Nebraska and Kansas now specify residual programs as bundled input packages.
Brazil
Matopiba no-till expansion institutionalizes soil-applied residual control where mechanical cultivation is impossible. ANVISA residue limits directly shape which chloroacetamide and HPPD-inhibitor chemistries grain exporters can deploy. São Paulo-based formulators serve Cerrado soybean operations with polymer-coated granular pendimethalin for high-temperature storage stability.
Germany
Bavarian and North Rhine-Westphalia cereal rotations maintain baseline demand as ECHA REACH classifications eliminate atrazine and acetochlor from member state programs. EFSA residue thresholds constrain which residual chemistries gain clearance for export-bound grain. BASF SE anchors R&D investment in novel sites of action from Ludwigshafen headquarters.
China
Jiangsu province chloroacetamide technical plants supply 70% of global dinitroaniline and chloroacetamide active ingredient production. MEE environmental compliance inspections are consolidating manufacturing capacity among state-affiliated chemical groups. Shandong Peninsula formulators export microencapsulated metolachlor to Southeast Asian palm oil plantations.
Ukraine
Chernihiv and Poltava oblast commercial farms adopt Western crop protection protocols as Black Belt expansion creates first-mover advantage for residual herbicide portfolios. National phytosanitary service registration timelines determine which chemistries enter rotation programs. Odesa port logistics constrain import volumes during spring planting windows.
Pre-Emergent Herbicide Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biological-residual combinations and precision application technologies. Three manufacturers control over 70% of global dinitroaniline and chloroacetamide technical production, creating tiered supply vulnerability for downstream formulators. Strategic archetypes include integrated seed-chemistry platforms, specialized resistance management R&D shops, and generic technical suppliers. Dominant competitive moves involve direct cooperative procurement contracts and novel formulation patent filings.
Within the integrated platform tier, Bayer AG and Syngenta AG exemplify seed-trait bundling with residual herbicide programs. BASF SE occupies a specialized position in soybean pre-emergent formulations. These three represent divergent strategic anchors: Bayer leverages germplasm licensing to embed chemistry sales, Syngenta prioritizes novel site-of-action discovery pipelines, and BASF targets waterhemp-specific formulation development.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm Limited |
| Adama Agricultural Solutions Ltd. |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| Others |
Value Network & Pricing Analysis
Large-scale cooperative procurement systems in Iowa and Nebraska now command sufficient volume leverage to negotiate direct manufacturer contracts, compressing traditional distributor margins and anchoring contract-based long-term offtake as the dominant pricing model for residual herbicide portfolios.
Pricing Analysis
Volume placements anchor revenue in liquid microencapsulated formulations, while margin capture concentrates in premium granular delivery systems for Brazil's Cerrado no-till operations. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and cold-weather stability certification. Cost compression in generic chloroacetamide technical is intensifying because Chinese environmental compliance inspections are consolidating manufacturing capacity. Price-sensitive mid-scale Brazilian soybean growers in Mato Grosso gravitate toward economy-tier generic pendimethalin, whereas North American operations above 10,000 acres absorb premium pricing for resistance-management bundled programs.
Supply Chain Analysis
EPA registration and ANVISA residue clearance function as certification gates that filter which active ingredients enter commercial rotation programs across North and South America. Technical production concentrates in China's Jiangsu and Zhejiang provinces, with formulation finishing in São Paulo and Ludwigshafen serving regional demand pools. The supply chain draws from chloroacetamide intermediates, dinitroaniline precursors, and polymer encapsulation materials. Single-source vulnerability in Chinese technical manufacturing exposes formulators to environmental compliance disruption. Distribution runs through agricultural cooperatives and direct manufacturer field teams, displacing traditional wholesaler channels in consolidated farming regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of chloroacetamide technical to insulate margin structures from Chinese environmental enforcement volatility.
For Market Incumbents: To counter glyphosate-resistant weed proliferation eroding post-emergent chemistry demand, Bayer and Syngenta should deepen backward integration into chloroacetamide technical production in China or India, while embedding residual herbicide programs within seed trait licensing agreements to lock in multi-year contract volumes. For New Entrants and Emerging Players: Capture the biological-residual combination segment serving California leafy green producers and organic-transitioning operations in Eastern Europe, where microbial bioherbicide integration commands premium positioning and regulatory pathways remain less congested than synthetic chemistry registration queues. For Investors and Strategic Acquirers: The window for entry favors vertically integrated formulators with ANVISA-cleared portfolios and established Cerrado distribution relationships, as Brazilian no-till expansion institutionalizes residual herbicide demand; watch EPA triazine ecological assessments as the signal for accelerated grower migration toward alternative chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Production | Captive supply of chloroacetamide intermediates insulates margins from Chinese MEE enforcement actions. |
| ANVISA Registration Acceleration | Early clearance for HPPD-inhibitor residual stacks secures positioning in Brazil's Matopiba expansion zones. |
| Microencapsulation Capacity Buildout | Extended residual windows from 6 to 10 weeks command premium pricing in Iowa and Illinois corn belts. |
| Cooperative Direct Contracting | Bypassing traditional distributors captures volume share in Nebraska and Kansas procurement consolidation. |
| Biological-Synthetic Combination Development | Microbial bioherbicide integration targets California vegetable producers facing strict residue thresholds. |
Research Methodology
Document review covered EPA ecological risk assessments, ANVISA residue limit determinations, and ECHA REACH substance classifications, complemented by interviews with agronomy directors at Iowa and Nebraska agricultural cooperatives, formulation R&D leads at German and Chinese manufacturers, and procurement officers at Brazilian grain export operations. Secondary validation drew from USDA NASS planting intention surveys, Brazilian CONAB crop estimates, and customs data tracking chloroacetamide technical trade flows. Bottom-up acreage-by-crop modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Model outputs span active ingredient chemistry, formulation type, application method, crop system, and regional regulatory cluster across the projection horizon. CAGRs were derived from acreage expansion rates, resistance-driven program stacking intensity, and substitution elasticities between triazine and alternative chemistries. Forecast inputs incorporated EPA re-registration timelines, Brazilian no-till adoption curves, and Ukrainian Black Belt commercial farm consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA atrazine use restrictions, Chinese environmental enforcement intensity, and Brazilian exchange rate volatility affecting import purchasing power. Forecasts reflect documented assumptions regarding resistance evolution rates and regulatory clearance timelines. A model refresh is warranted upon material change in EPA ecological risk assessment conclusions or ANVISA residue limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Chlorpyrifos Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Fogger Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Fumigation Service Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Pest Control Services Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Europe Chemical Seed Treatment Market