
 Pest Control Products Market | 2026-2036
Pest Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Control Products Market Intelligence
The integration of microbial and botanical-derived active ingredients into formulations is tilting product development away from traditional synthetic chemistries. Bayer AG leverages its extensive R&D in crop science to develop integrated pest management solutions. Syngenta AG specializes in seed treatments that combine genetic traits with chemical and biological protection. BASF SE competes on its broad portfolio of both conventional and innovative biological fungicides for agriculture.
Pest control products are formulations containing active ingredients, either chemical or biological, designed to manage, repel, or eliminate target pests. These substances are formulated into specific forms like liquids or granules to ensure effective delivery and adherence. Insecticides for the agriculture application continue to dominate market volume, driven by the need to protect staple crops. The residential application segment, however, shows significant growth in demand for lower-toxicity rodenticides and repellents.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) dictate permissible active ingredients and residue levels. These standards directly influence product development timelines and market access for new formulations. Navigating the evolving landscape of biopesticide approvals versus the re-registration of established chemistries will determine future market leadership.
Market Dynamics
The fundamental dynamic shaping the pest control products market is the tension between agricultural demand for crop yield protection and intensifying regulatory pressure for sustainable, lower-toxicity formulations, a shift exemplified by the European Union's Green Deal.
Growth Catalysts
- Regulatory Mandates:The European Union's Green Deal and its associated Farm to Fork Strategy are accelerating the market transition towards bio-based insecticides and fungicides by setting targets to reduce chemical pesticide use.
- Agricultural Intensification:Large-scale farming operations in agricultural powerhouses like Brazil require highly effective pest control solutions to protect vast monoculture crop yields from infestation, driving market volume.
- Formulation Innovation:The integration of microbial and botanical-derived active ingredients into advanced formulations is creating new product categories that meet both efficacy and environmental compliance standards.
Market Restraints
- Regulatory Scrutiny:The costly and time-intensive re-registration processes for established synthetic chemistries under frameworks like the US EPA and ECHA create significant barriers and uncertainty for legacy product portfolios.
- Performance Limitations:Many current-generation biopesticides exhibit slower modes of action and shorter field persistence compared to synthetic counterparts, limiting their effectiveness in managing severe, acute pest outbreaks.
- Substitution from Biotechnology:The proliferation of genetically modified crops engineered with inherent pest resistance, such as Bt corn, directly reduces the addressable market for topically applied insecticides in major row crops.
Strategic Opportunities
- Residential Market Expansion:Developing novel, low-toxicity rodenticides and insect repellents tailored for safety and ease of use addresses unmet needs in the fast-growing residential and do-it-yourself (DIY) application segments.
- Precision Agriculture Integration:Combining targeted biological formulations with drone-based imaging and precision spraying systems offers a path to optimize input use, improve efficacy, and minimize environmental off-target effects.
- Biopesticide Development:Regulatory fast-track programs for biopesticides, offered by agencies like the EPA in the United States, create a clear commercial incentive for R&D investment in microbial, botanical, and biochemical active ingredients.
Industry Challenges
- Complex Compliance Pathways:Manufacturers must navigate a fragmented and constantly evolving landscape of maximum residue levels (MRLs) across key export destinations, creating significant logistical and trade-related hurdles.
- Pest Resistance Management:The emergence of pest populations resistant to common active ingredients necessitates continuous innovation in formulations and the promotion of integrated pest management (IPM) strategies to preserve product efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Control Products Market |
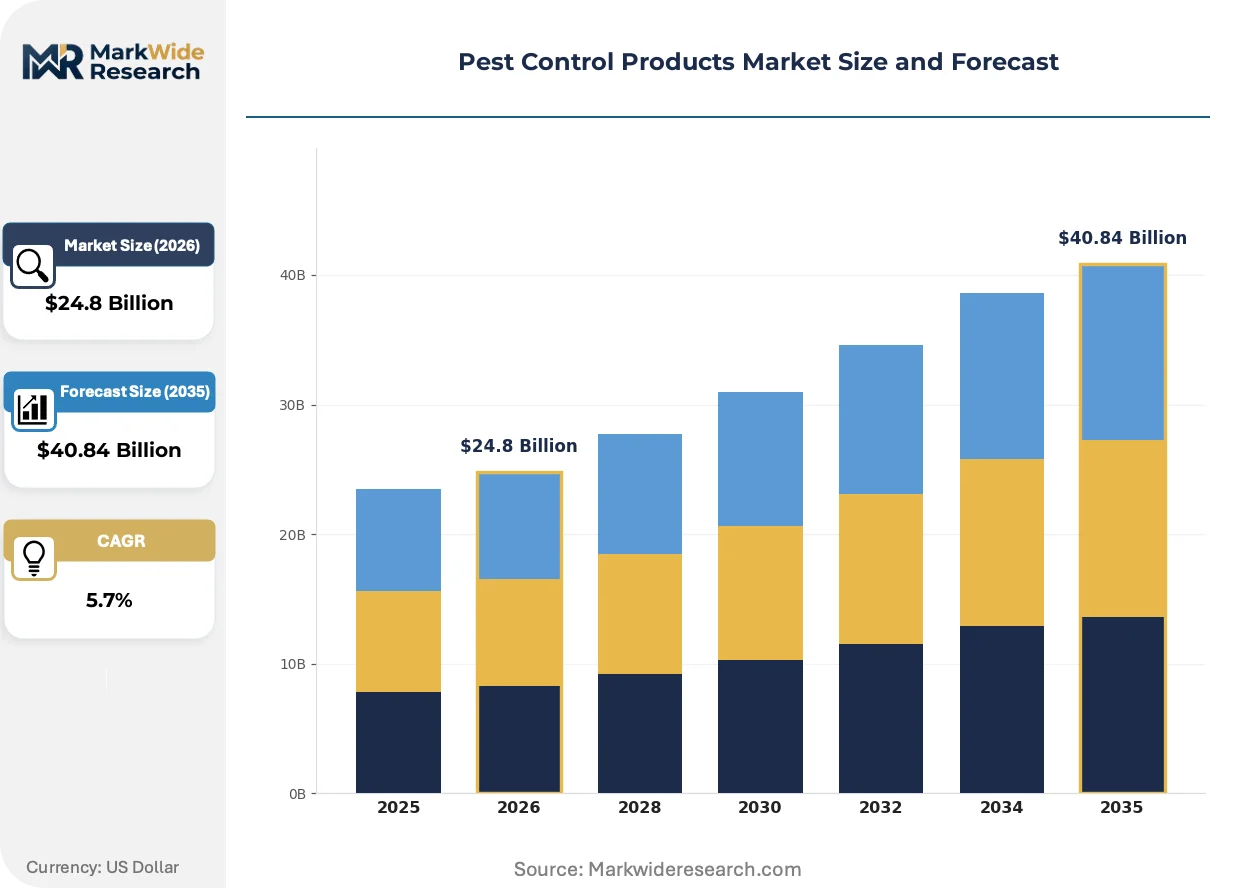
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Rodenticides, Fungicides, Herbicides, Repellents Application: Agriculture, Residential, Commercial, Public Health Form: Liquid, Powder, Aerosol, Bait, Granule End User: Farmers, Pest Management Professionals, Government Bodies, Property Managers |
| Companies Covered | Corteva Agriscience, Rentokil Initial Plc, Bayer AG, Ecolab Inc., Rollins, Inc., Syngenta AG, FMC Corporation, Sumitomo Chemical Co. Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Control Products Market Strategic Shifts & Innovations
A definitive shift from broad-spectrum chemical interventions toward targeted, integrated pest management systems is reshaping product development. This evolution combines biological sciences with digital tools to enhance selectivity and sustainability in both agricultural and residential applications.
RNA interference (RNAi) technology provides a hyper-specific mode of action by silencing essential genes in target pest species. Agricultural firms are incorporating RNAi into next-generation seed treatments and foliar sprays for high-value crops. This genetic-level precision is rendering obsolete the reliance on broad-spectrum neurotoxic insecticides that harm beneficial insects and non-target organisms.
Regulatory frameworks are actively compelling portfolio transformation. The European Union’s Farm to Fork Strategy, for instance, establishes binding targets to cut chemical pesticide usage, directly forcing a pivot in product strategy. Manufacturers supplying the EU agricultural sector are consequently accelerating investment in biological fungicides and insecticides to ensure their products remain compliant and competitive.
Consumer and commercial purchasing behavior is moving beyond simple product acquisition toward integrated, data-driven pest management services. This disrupts traditional distribution channels focused on selling chemical volumes, which are being supplanted by platforms offering digital scouting, pest forecasting, and customized treatment recommendations. The shift is most advanced in North American commercial agriculture, where farm management software is widely adopted.
Pest Control Products Market Segmentation
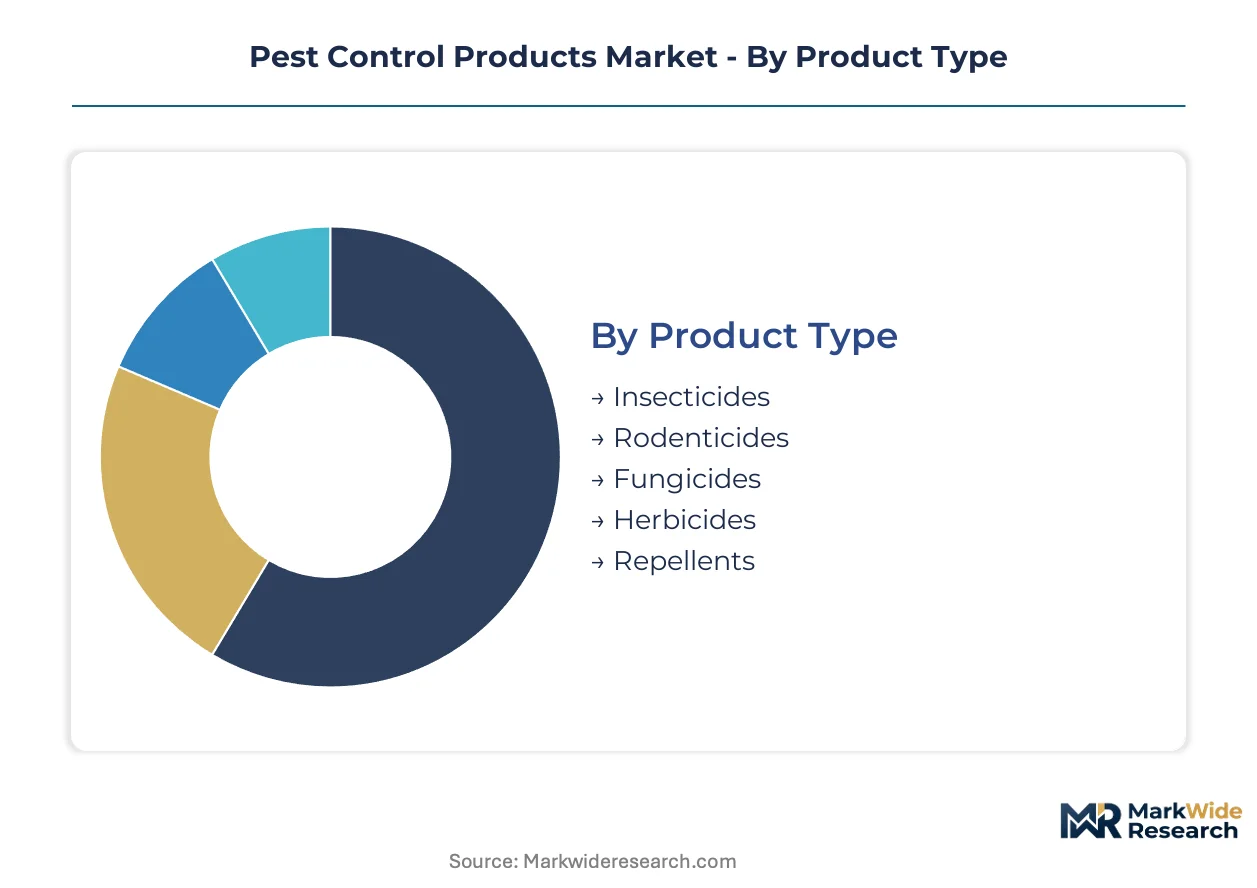
Segmentation of the pest control products market reveals distinct demand drivers and product preferences across various dimensions. Understanding these segments is crucial for manufacturers to tailor formulations and distribution strategies effectively. This granular view informs strategic product development and market penetration efforts.
Product Type:
The product type segment showcases a spectrum from mature chemical solutions to emerging biological alternatives gaining regulatory favor.
- Insecticides:Insecticides are chemical or biological agents designed to kill, harm, repel, or mitigate one or more species of insects. Demand concentrates heavily in agricultural applications, particularly in Brazil and other large-scale farming regions, driven by the imperative to protect staple crop yields.
- Fungicides:Fungicides are pesticides used to kill or inhibit fungi or fungal spores, protecting plants from fungal diseases. European agricultural markets, influenced by the EU Green Deal, are seeing a rapid shift towards bio-based fungicides to meet sustainability targets and reduce chemical load.
- Rodenticides:These formulations target rodents like rats and mice, seeing increased demand in residential and public health settings for lower-toxicity options.
- Herbicides:Herbicides are substances used to control unwanted plants, primarily in agricultural and land management contexts to maximize crop output.
- Repellents:Repellents deter pests without killing them, with household and personal use segments seeking effective, safe, and long-lasting formulations.
Insecticides retain volume leadership; bio-based fungicides hold the steepest expansion curve.
Application:
Application segments delineate where pest control products are deployed, ranging from large-scale crop protection to individual household needs.
- Agriculture:This segment encompasses products used to protect crops from pests, diseases, and weeds in farming operations worldwide. Global food security concerns and the need to protect vast monoculture yields, especially in regions like Brazil, drive substantial demand for effective solutions.
- Residential:Products in this segment are designed for use in homes and gardens to manage household pests. Demand for lower-toxicity rodenticides and repellents is particularly strong, reflecting consumer preferences for safer solutions around families and pets.
- Commercial:Commercial applications include pest management for businesses, hotels, and food service establishments, requiring discreet and efficient solutions.
- Public Health:This segment addresses vector-borne diseases and nuisance pests in public spaces, often involving government bodies for large-scale interventions.
Agricultural applications concentrate the largest volume of pest control product demand, while the residential sector demonstrates significant growth in consumer-driven innovation.
Form:
The form segment highlights diverse delivery mechanisms, each optimized for specific pest types and application environments.
- Liquid:Liquid formulations are typically concentrated solutions or emulsions that are diluted with water before spraying onto target areas. Their versatility and ease of application make them prevalent in both agricultural crop protection and professional pest management services.
- Granule:Granular products consist of active ingredients coated onto inert carriers, designed for soil application or broadcasting. These forms offer controlled release and reduced drift, making them suitable for long-term pest management in agricultural fields and turf.
- Powder:Powder formulations are dry, finely ground materials applied as dusts or wettable powders, often used in crack and crevice treatments.
- Aerosol:Aerosol products deliver fine mist sprays for immediate localized pest control, commonly found in residential and commercial spot treatments.
- Bait:Bait formulations combine a pesticide with an attractive food source, effectively drawing pests to consume the toxicant, particularly for rodents and insects.
Liquid forms offer broad utility and application flexibility, while bait formulations continue to gain preference for targeted pest elimination.
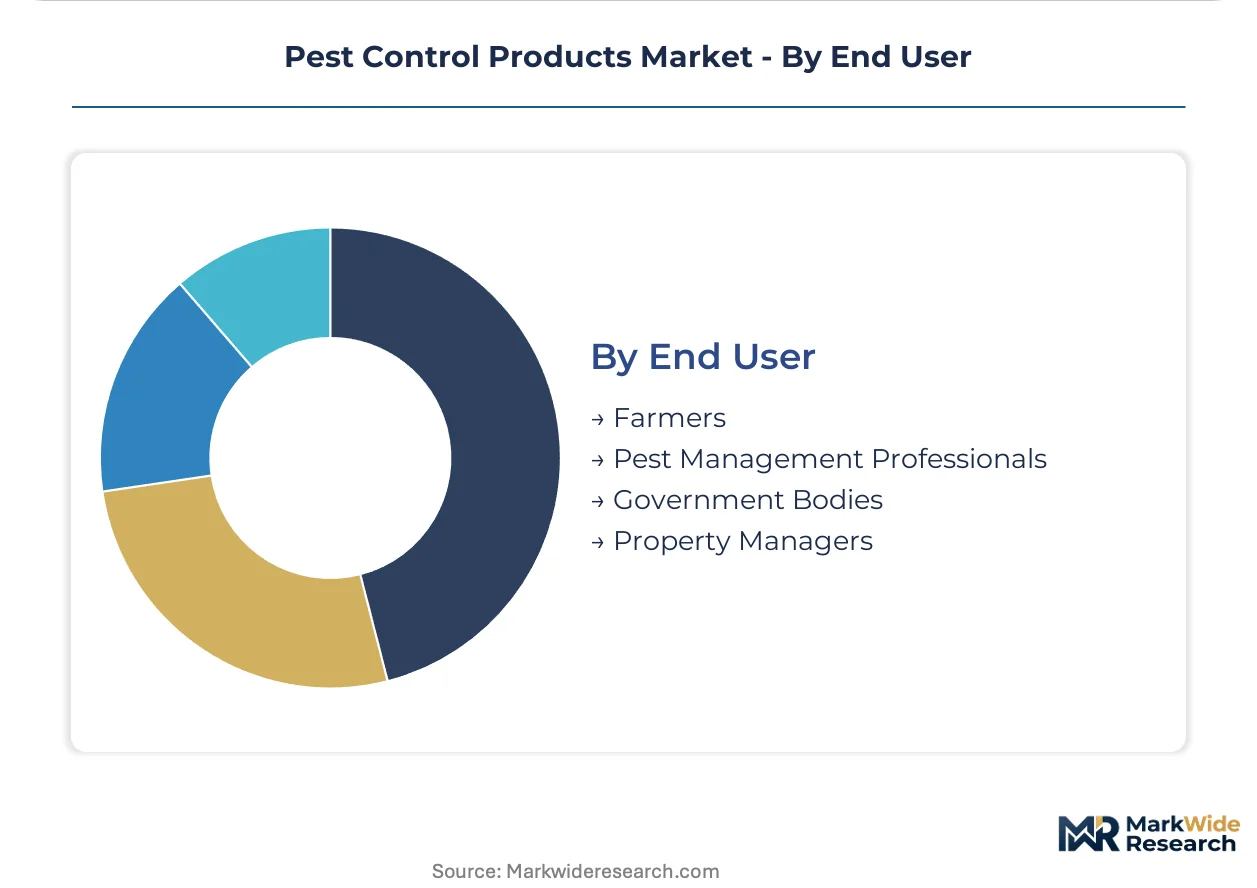
End User:
End-user segments categorize the primary purchasers and applicators of pest control products, reflecting varied operational scales and regulatory compliance needs.
- Farmers:Farmers utilize pest control products to protect their crops from infestation, ensuring yield stability and quality. Large-scale farming operations, particularly in regions with intensive agriculture, represent a significant consumer base for both conventional and biological solutions.
- Pest Management Professionals:These professionals offer specialized pest control services for residential, commercial, and industrial clients, requiring a diverse product portfolio. Their expertise in integrated pest management strategies drives demand for advanced, effective, and compliant formulations across varied environments.
- Government Bodies:Government bodies procure pest control products for public health campaigns, vector control, and management of invasive species in public lands.
- Property Managers:Property managers oversee pest control for residential and commercial properties, seeking efficient and safe solutions to maintain tenant satisfaction and property value.
Farmers represent the foundational demand for crop protection, while pest management professionals are strategically important for driving adoption of advanced and integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global pest control products market observes distinct regional dynamics, where agricultural powerhouses like Brazil drive demand for crop protection, while European regulatory shifts influence product innovation. Brazil's extensive agricultural exports to global markets, including Europe, necessitate pest control solutions that adhere to diverse international residue limits and sustainability standards.
Brazil
Brazilian agriculture drives substantial demand for effective pest control solutions to protect vast monoculture crop yields. The country's national health regulatory agency, ANVISA, influences the approval process for new pesticide formulations. Large-scale farming operations in states like Mato Grosso require highly effective and compliant solutions for soybean and corn production.
United States
The United States market exhibits strong demand for both agricultural crop protection and residential low-toxicity options. The US Environmental Protection Agency (EPA) dictates permissible active ingredients and offers fast-track programs for biopesticide approvals. California's Central Valley, a hub for specialty crop production, increasingly adopts integrated pest management strategies.
Germany
Germany's pest control market is rapidly shifting towards bio-based fungicides and insecticides, influenced by the European Union's Green Deal. The EU's Farm to Fork Strategy sets binding targets to reduce chemical pesticide use, compelling manufacturers to innovate. The Rhine-Neckar region, home to major chemical companies, focuses on research and development in biological and advanced formulations.
India
India presents significant demand for pest control products to ensure food security and protect staple crop yields for its large population. The Central Insecticides Board & Registration Committee (CIB&RC) regulates pesticide registration and usage across the country. Agricultural regions like Punjab actively implement pest resistance management strategies for wheat and rice cultivation.
China
China's vast agricultural sector requires extensive pest control to support its food production goals and address environmental concerns. The Ministry of Agriculture and Rural Affairs (MARA) oversees pesticide registration and promotes sustainable agricultural practices. Shandong Province, a major agricultural hub, increasingly adopts modern pest control technologies and biological solutions.
Pest Control Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across the pest control products market. The market structure features a mix of large, diversified agrochemical corporations and specialized biologicals developers. Strategic archetypes include integrated solution providers, biological innovation specialists, and dedicated pest management service companies. Significant competitive moves involve substantial R&D investment in biopesticides and strategic partnerships for broader distribution.
Large diversified agrochemical companies, such as Bayer AG and Syngenta AG, represent the integrated solution provider archetype, leveraging extensive R&D in crop science and seed treatments. These entities focus on combining genetic traits with chemical and biological protection. Rentokil Initial Plc, a prominent service provider, occupies a position in the professional pest management segment, offering comprehensive solutions beyond product sales.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Rentokil Initial Plc |
| Bayer AG |
| Ecolab Inc. |
| Rollins, Inc. |
| Syngenta AG |
| FMC Corporation |
| Sumitomo Chemical Co. Ltd |
| BASF SE |
| Others |
Cost & Logistics Intelligence
European manufacturing capacity for bio-based active ingredients currently faces undercapacity, driving up input costs and influencing the pricing strategies of formulators. This utilization challenge shapes investment in new production facilities and impacts market access for novel solutions.
Pricing Analysis
The pricing gap between established synthetic chemistries and next-generation biopesticides remains significant, reflecting R&D investment and regulatory approval costs. Per-unit transactional pricing dominates, with differentiation stemming from formulation efficacy and environmental compliance certifications. Pricing softness for legacy products stems from re-registration burdens and generic competition. Agricultural farmers exhibit high price sensitivity due to scale, while residential consumers prioritize safety and are less price-sensitive for novel, low-toxicity options.
Supply Chain Analysis
Upstream sourcing for active ingredients in pest control products primarily draws from chemical manufacturers in India and China for synthetic compounds. Bio-based formulations rely on specialized microbial cultures and botanical extracts, often sourced from European and North American biotechnology firms. Single-source vulnerability for patented biological active ingredients represents a significant supply chain risk. Distribution downstream primarily occurs through large agricultural cooperatives, specialized pest management professional networks, and retail channels for residential products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
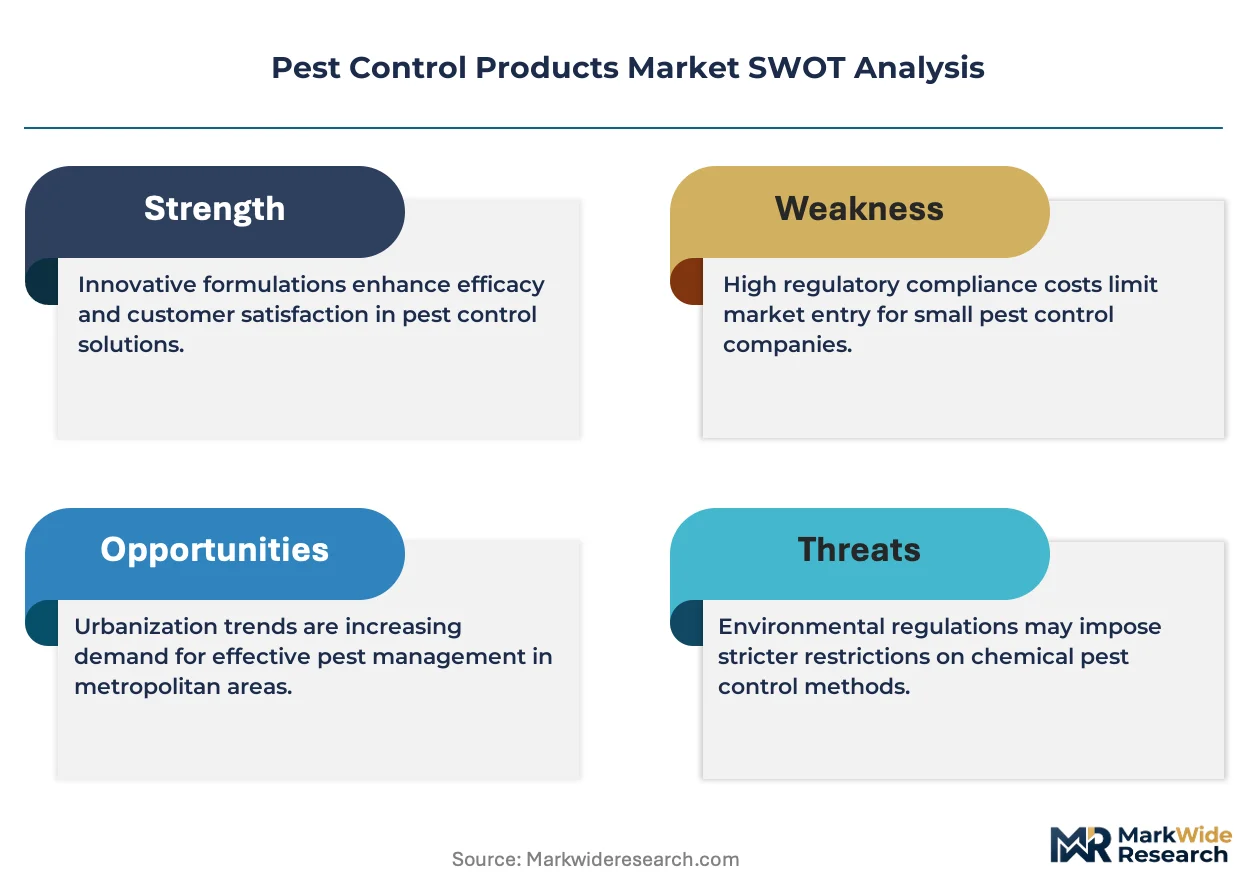
The pest control products market requires incumbents to mount a robust substitution defense against the proliferation of genetically modified crops engineered with inherent pest resistance. Navigating this evolving landscape necessitates continuous innovation and strategic adaptation.
For Market Incumbents: Entrench market position by investing heavily in biopesticide R&D and securing regulatory fast-track approvals for new active ingredients. Consolidate distribution channels in key agricultural regions like Brazil to counter emerging biologicals players. This strategy defends against the threat of biotechnology-driven pest resistance by leveraging existing market access and scientific expertise. Deepen vertical integration into specialized microbial strain production to control input quality.
For New Entrants and Emerging Players: Residential application segments in North America exhibit geographic underpenetration for novel, low-toxicity repellents. Target the do-it-yourself (DIY) market with user-friendly, bio-based formulations that address consumer safety preferences. Partner with e-commerce platforms and specialized home improvement retailers to access this highly penetrable segment. Focus on clear messaging regarding product safety and environmental benefits as a primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pest management professional service providers offering integrated pest management solutions. Long-term viability in this market hinges on companies with strong intellectual property in bio-based active ingredients and robust regulatory compliance infrastructure. Target acquisition profiles should favor mid-sized biological innovation specialists with proven product pipelines. The signal to watch is the acceleration of biopesticide approvals by agencies like the EPA.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in RNAi Technology | This advances hyper-specific pest control, reducing reliance on broad-spectrum neurotoxic insecticides. |
| Strategic Partnership for Digital Scouting | Integrating drone-based imaging optimizes input use and improves efficacy in precision agriculture. |
| Capacity Expansion for Bio-based Fungicides | This addresses rising demand in European agricultural markets driven by the EU Green Deal. |
| Acquisition of Microbial Strain Developer | Securing proprietary biological active ingredients enhances portfolio differentiation and intellectual property. |
| Regulatory Compliance Specialization | Navigating complex MRLs across export destinations ensures market access for global agricultural powerhouses like Brazil. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, regulatory affairs specialists, and distribution channel managers anchored the qualitative base for this analysis. Primary interviews were combined with rigorous secondary validation using US EPA filings, ECHA pesticide databases, agricultural trade statistics, and company 10-K filings. This approach ensured robust bottom-up and top-down triangulation across all data points.
Scenario-bracketing provided a robust framework for projecting market trajectories across the analysis window. The analytical framework modeled dimensions including product type, application, form, end user, and target pest type. Compound Annual Growth Rates were derived from historical market trends and projected regulatory influences. Key forecast inputs included biopesticide approval timelines and global crop acreage data.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices or global trade policies would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Cross-checking against FAO agricultural outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Grain Protectant Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Pest Control Services Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
North America Acaricides Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Global Acephate Market