
 Indonesia Agrochemicals Market | 2026-2036
Indonesia Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Agrochemicals Market Foresight
Subscription-based agronomy advisory bundled with input purchases is repositioning how agrochemicals reach Indonesian smallholders. Bayer AG leverages its digital farming platform to sustain direct farmer relationships across Java's corn belts. Syngenta Group anchors its position through integrated seed-crop protection packages tailored to tropical horticulture. PT Pupuk Indonesia dominates domestic fertilizer blending while competing with multinational distributors on price.
Agrochemicals comprise synthetic and biological formulations—pesticides, fertilizers, and plant growth regulators—engineered for crop yield optimization, with active ingredient concentrations typically ranging from 10% to 80% depending on application mode and target pest spectrum. These inputs serve commercial agriculture by protecting against biotic stressors and correcting soil nutrient deficits. Herbicides lead product type revenue due to labor cost pressures in palm oil estates, while fungicides represent the fastest-expanding segment as wet-season disease pressure intensifies across Kalimantan. Distributor channels capture the largest margin pool by aggregating fragmented smallholder demand, though e-commerce penetration accelerates in Java's more connected regencies.
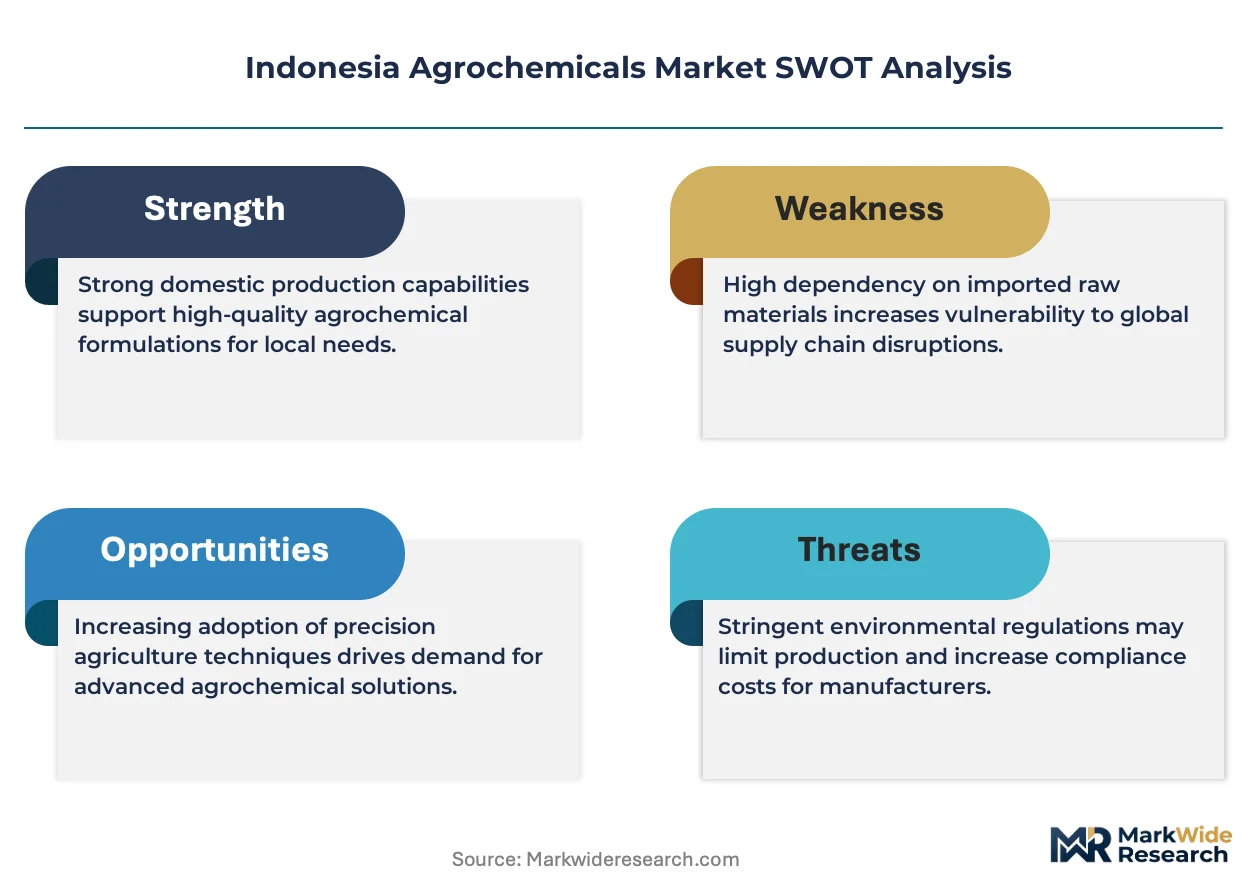
Indonesia's Ministry of Agriculture sets pesticide registration and maximum residue limits, while BIS-equivalent national standards govern fertilizer quality certification, both tightening under food security mandates. The country's agricultural regulator also enforces import licensing for active ingredients, shaping which multinationals gain market access. Stakeholders must monitor how forthcoming subsidy restructuring and biopesticide registration pathways alter competitive dynamics between synthetic incumbents and domestic biological entrants.
Market Dynamics
Indonesia's Ministry of Agriculture fertilizer subsidy reforms are redirecting farmer purchasing toward certified formulations, compressing margins for uncertified blenders while concentrating procurement through cooperative channels. This structural shift is reconfiguring competitive positioning across Sumatra's smallholder-dominated districts.
Growth Catalysts
- Palm oil plantation expansion:Rising hectarage under commercial management drives volume demand for herbicide formulations optimized for tropical perennials. Estates prioritize labor-saving chemical applications over manual weeding.
- REACH-equivalent biopesticide registration pathways:Accelerated approval timelines for microbial and botanical formulations are opening market access for domestic biological entrants competing with synthetic incumbents.
- Wet-season disease pressure intensification:Fungicide demand concentrates across Kalimantan as climate volatility extends monsoon duration, forcing smallholders into protective spray schedules.
Market Restraints
- Active ingredient import licensing:Indonesia's agricultural regulator restricts market access for unregistered multinationals, creating supply bottlenecks for novel chemistries.
- Phosphate and potash price volatility:Fertilizer blenders face margin compression from concentrated global supplier markets, particularly Moroccan phosphate rock and Belarusian potash disruptions.
- Smallholder fragmentation:Dispersed demand across millions of sub-hectare plots elevates distribution costs beyond viable returns for direct-to-farmer models outside Java's connected regencies.
Strategic Opportunities
- Digital agronomy platforms:Subscription-based advisory bundled with input purchases is repositioning how agrochemicals reach Indonesian smallholders, bypassing traditional distributor markups.
- Kalimantan smallholder cooperatives:Underpenetrated distribution infrastructure in Borneo's interior creates first-mover advantage for integrated seed-crop protection package providers.
- Food security mandate tightening:Residue limit enforcement and quality certification requirements favor compliant domestic blenders over informal suppliers in government procurement.
Industry Challenges
- Field agronomist scarcity:Technical advisory capacity lags behind digital platform deployment, limiting adoption of precision application protocols among smallholders.
- Blending facility capex requirements:Certified fertilizer production demands upgraded mixing equipment and laboratory testing infrastructure that domestic players struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Agrochemicals Market |
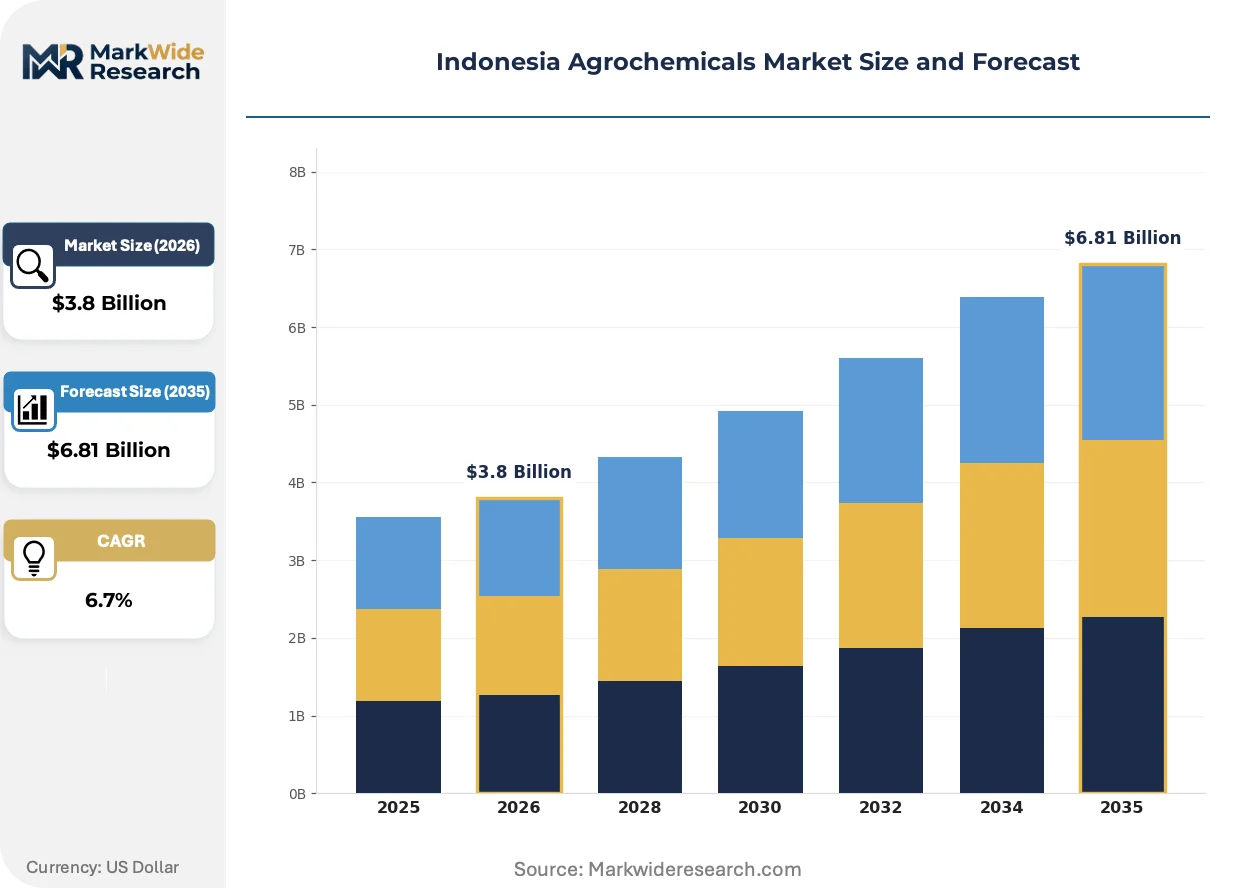
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Growth Regulators End Use Industry: Crop Protection, Horticulture, Turf Management, Aquaculture Distribution Channel: Direct Sales, Retail, E-commerce, Distributor Application Method: Foliar Spray, Soil Application, Seed Treatment, Drip Irrigation |
| Companies Covered | Bayer AG, Syngenta Group, BASF SE, Corteva Agriscience, PT Pupuk Indonesia, Yara International, Wilmar International, PT Petrokimia Gresik, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Agrochemicals Market Shifts & Advancements
Biological formulation development is converging with digital advisory platforms to reshape how Indonesian smallholders access crop protection. Three interconnected developments are compressing traditional distribution hierarchies while elevating technical service intensity.
Microbial inoculant technology is converging with precision application hardware to enable targeted delivery of biofungicides in palm oil estates. Large plantation operators in Riau and North Sumatra are piloting drone-mounted spraying systems that reduce water volumes and improve canopy penetration. This convergence is compressing the cost premium between biological and synthetic crop protection while enabling real-time dosage adjustment based on disease pressure mapping.
Indonesia's Ministry of Agriculture is tightening maximum residue limits for export-oriented horticulture under food security mandates. The industrial consequence is accelerated withdrawal of older organophosphate chemistries from registered use lists. Fresh vegetable producers in West Java's highland districts are most affected, responding with rapid substitution toward biopesticide rotations and integrated pest management certification to maintain EU and Middle East market access.
Cooperative procurement consolidation is displacing independent distributor relationships across Sumatra's smallholder belts. Village-level farmer groups are aggregating demand to negotiate direct supply contracts with fertilizer blenders, compressing intermediary margins. This pattern is most visible in Lampung's coffee and cocoa districts, where cooperative-managed input stores now capture significant local market share from traditional agrochemical retailers.
Indonesia Agrochemicals Market Segmentation
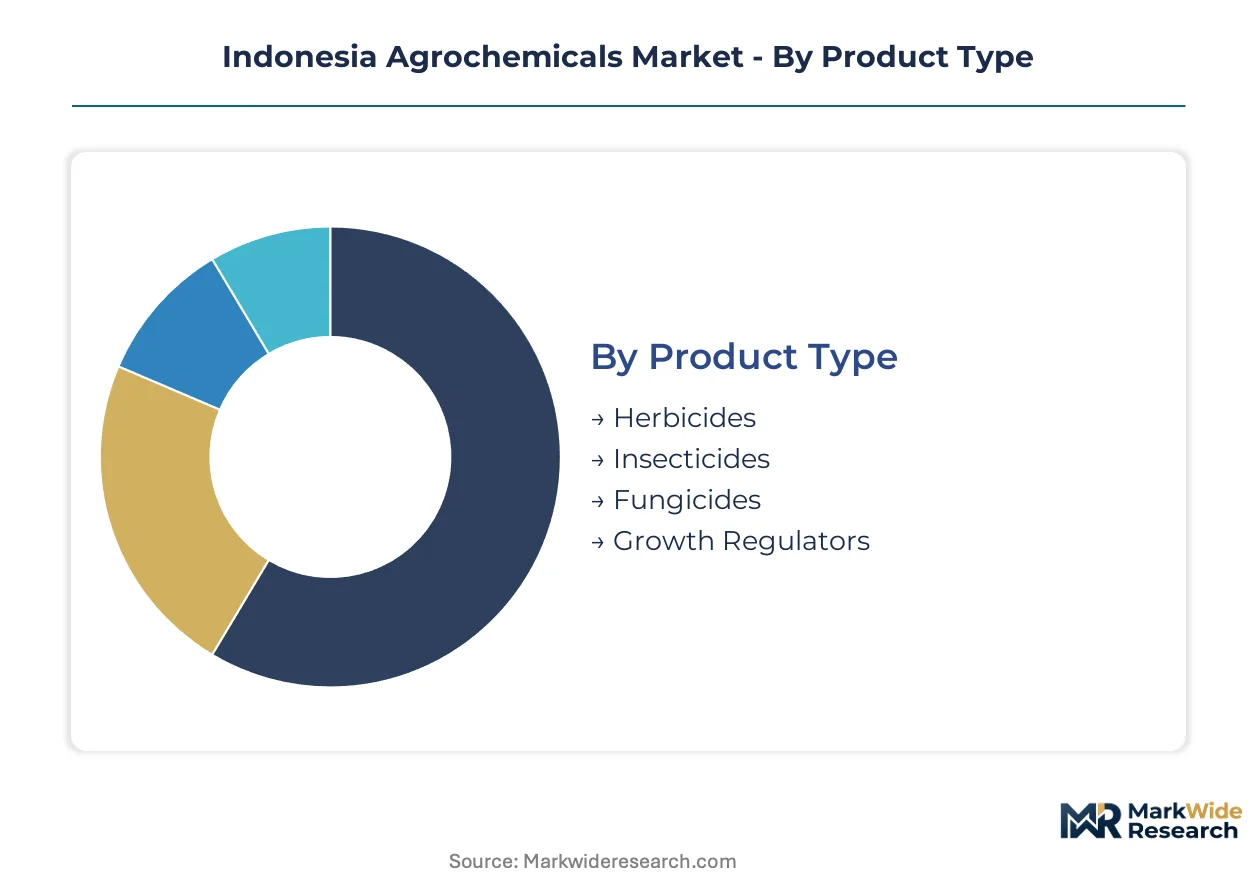
Agrochemical purchasing patterns across Indonesia fragment sharply by crop system, operational scale, and infrastructure access. Understanding these divides reveals where formulation margins concentrate and which channels can bypass traditional distributor markups.
Product Type:
Active ingredient chemistry and application mode define performance thresholds across tropical cropping systems.
- Herbicides:Glyphosate and paraquat formulations dominate volume, engineered for broad-spectrum weed control in labor-constrained palm oil estates. Demand concentrates in Riau and North Sumatra where estate managers prioritize chemical weeding over manual clearing amid rising wage pressures.
- Fungicides:Triazole and strobilurin chemistries address black pod and stem rot pressure in wet-season conditions. Application intensity is climbing fastest across Kalimantan's smallholder cocoa belts where monsoon extension forces protective spray schedules.
- Insecticides:Pyrethroid and neonicotinoid formulations target pod borers and leaf-eating caterpillars in vegetable systems.
- Growth Regulators:Gibberellin and cytokinin formulations manipulate flowering synchronization in pineapple and mango export operations.
Mature deployment sits with herbicides in established plantation belts. Newer deployment is concentrated in fungicides as climate volatility intensifies disease pressure cycles.
End Use Industry:
Operational scale and export orientation determine input specification thresholds and compliance burdens.
- Crop Protection:Large-scale rice and corn operations drive volume procurement of generic synthetic formulations. Demand aggregates through Java's cooperative networks where subsidy eligibility requirements filter purchasing toward certified suppliers.
- Horticulture:Highland vegetable producers in West Java and North Sumatra face EU and Middle East residue limit enforcement. Export certification mandates are accelerating biopesticide rotation adoption and integrated pest management documentation.
- Turf Management:Golf course and estate landscaping operations in Jakarta's periphery specify slow-release fertilizer blends and selective herbicides.
- Aquaculture:Shrimp pond operators in Sulawesi and Sumatra apply algaecides and water treatment formulations.
Margin concentration tracks horticulture's compliance premium. Volume scale anchors in crop protection's rice-dominant procurement.
Distribution Channel:
Physical infrastructure density and digital connectivity determine channel economics across the archipelago.
- Distributor:Independent aggregators and cooperative buying groups consolidate fragmented smallholder demand across Sumatra's coffee and cocoa districts. Village-level farmer groups in Lampung now negotiate direct blender contracts, compressing traditional retailer margins.
- E-commerce:Platform-based input sales accelerate in Java's connected regencies where smartphone penetration enables advisory bundling. Bayer's digital farming platform sustains direct farmer relationships across Central Java's corn belts.
- Direct Sales:Multinational technical teams serve large plantation accounts with customized application protocols.
- Retail:Independent agrochemical shops persist in underconnected outer island districts.
First-mover advantage sits with e-commerce in Java's infrastructure corridors. Distributor consolidation is advancing fastest in Sumatra's cooperative belts.
Application Method:
Equipment access and labor availability shape application technology adoption curves.
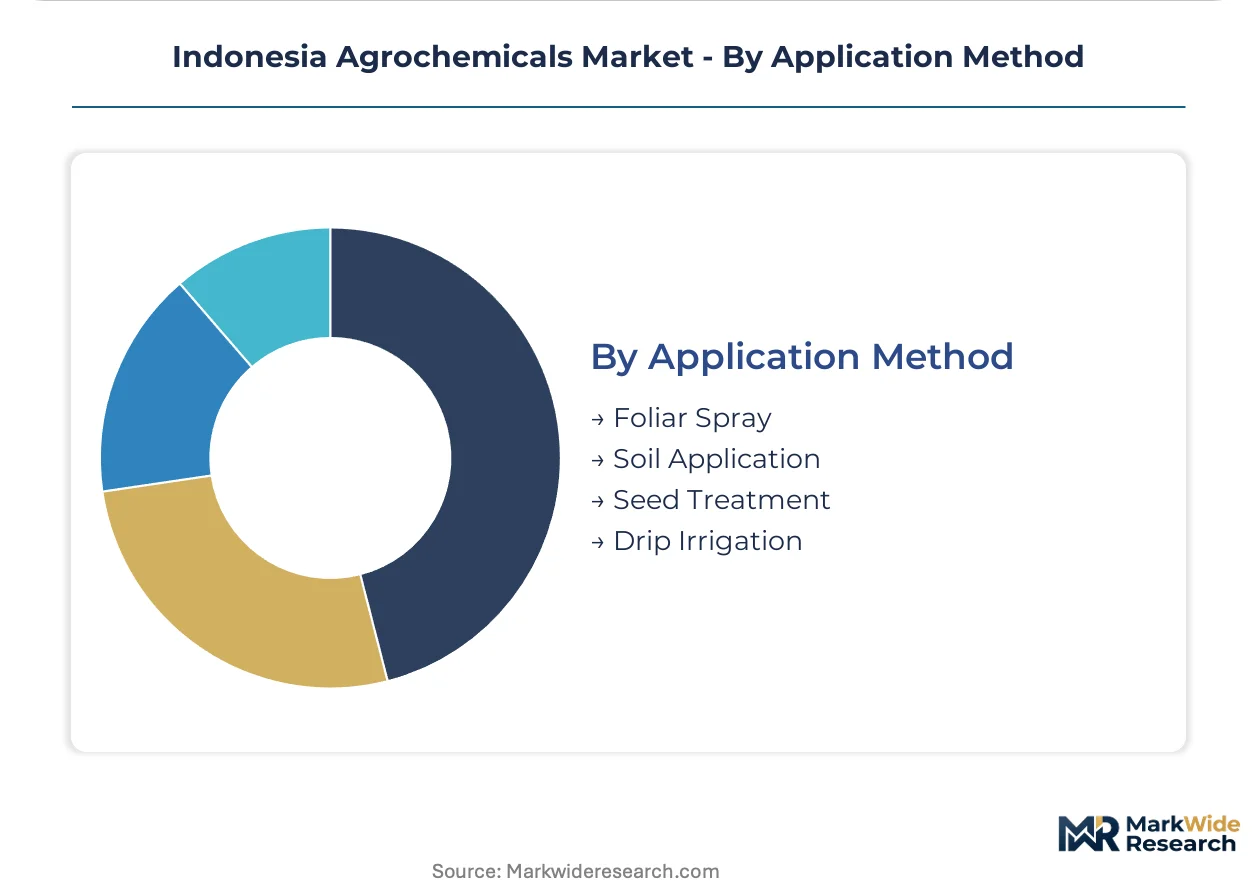
- Foliar Spray:Backpack and mechanized sprayers deliver protective chemistries across canopy surfaces. Drone-mounted systems are piloting in Riau palm estates to reduce water volumes and improve penetration.
- Soil Application:Granular fertilizer and systemic insecticide placement targets root zone uptake in rainfed rice systems. Demand concentrates in East Java's irrigated districts where precise placement improves nitrogen use efficiency.
- Seed Treatment:Fungicide and insecticide coatings protect germinating rice and corn seedlings.
- Drip Irrigation:Fertigation integration in greenhouse vegetable operations enables precise nutrient delivery.
Equipment legacy favors foliar spray across smallholder plots. Precision deployment is advancing through soil application in Java's mechanized rice systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia consumes agrochemicals at volumes exceeding domestic formulation capacity, creating import dependency for active ingredients and concentrated blending operations in Java. The archipelago's demand geography splits between estate-dominated outer islands and cooperative-organized smallholder belts.
Java
Rice and corn procurement drives fertilizer volume through East Java's irrigated districts and Central Java's cooperative networks. The Ministry of Agriculture's subsidy eligibility requirements filter purchasing toward certified domestic blenders. Surabaya and Malang anchor distribution infrastructure for synthetic formulations serving mechanized paddy systems.
Sumatra
Palm oil estates in Riau and North Sumatra generate concentrated herbicide demand as labor costs elevate chemical weeding over manual clearing. Village-level farmer groups in Lampung's coffee and cocoa belts now negotiate direct blender contracts, compressing traditional retailer margins. Medan functions as the primary import gateway for active ingredients.
Kalimantan
Smallholder cocoa operations face intensified wet-season disease pressure, accelerating fungicide application schedules across East and Central Kalimantan. Underpenetrated distribution infrastructure in Borneo's interior creates first-mover opportunity for integrated package providers. Samarinda and Pontianak emerge as logistics consolidation points.
Sulawesi
Shrimp pond aquaculture in South Sulawesi drives algaecide and water treatment formulation demand. Highland vegetable producers in North Sulawesi respond to export residue limits with biopesticide rotation adoption. Makassar serves as the chemical distribution hub for eastern Indonesia's dispersed farming systems.
Indonesia Agrochemicals Market Competitive Landscape
Capital-heavy domestic blenders compete with asset-light multinational distributors for channel access across Indonesia's fragmented smallholder base. Market structure concentrates procurement authority through cooperative buying groups and plantation direct contracts, marginalizing independent retailers. Three archetypes dominate: integrated seed-crop protection bundlers, certified fertilizer blenders with subsidy access, and digital platform operators bypassing traditional distribution. Competitive moves center on cooperative partnership lock-ins and e-commerce platform deployment in Java's connected corridors.
Among multinational agrochemical conglomerates, Bayer AG and Syngenta Group exemplify the integrated bundling archetype, while PT Pupuk Indonesia occupies the dominant domestic position in certified fertilizer blending. These three entities represent contrasting strategic approaches to Indonesia's subsidy-reformed procurement environment and cooperative channel consolidation.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| PT Pupuk Indonesia |
| Yara International |
| Wilmar International |
| PT Petrokimia Gresik |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
Cooperative procurement consolidation across Sumatra's smallholder belts anchors contract-based pricing for certified fertilizer formulations, while estate direct purchasing in Riau and North Sumatra sustains premium positioning for herbicide bundles. The subsidy reform pivot by Indonesia's Ministry of Agriculture concentrates buying power through village-level farmer groups, compressing margins for independent distributors unable to meet certification thresholds.
Pricing Analysis
Margin tightening in uncertified fertilizer blending reflects the Ministry of Agriculture's subsidy eligibility requirements filtering procurement toward compliant domestic producers. Three-tier pricing structure across premium certified, standard registered, and economy unbranded levels tracks quality grade and cooperative membership status. Cost-down pressure on synthetic incumbents accelerates as biopesticide registration pathways shorten approval timelines for domestic biological entrants. Smallholder cooperatives exhibit highest price sensitivity, while large palm oil estates prioritize labor-saving efficacy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan phosphate rock and Belarusian potash disruptions that feed Indonesian fertilizer blending operations. Active ingredient sourcing draws from China and India for generic chemistries, while proprietary formulations rest on multinational manufacturing networks in Germany and Switzerland. Tariff exposure through Indonesia's agricultural regulator import licensing creates supply bottlenecks for novel pesticide chemistries. Distribution runs through Medan and Surabaya as primary import gateways, with cooperative channels displacing independent retailer networks across Sumatra's interior.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active ingredient import licensing constraints and certified blending facility scarcity prop pricing power for compliant domestic producers, creating a supply-constrained environment favoring first-movers in cooperative channel partnerships.
For Market Incumbents: Cement cooperative procurement lock-ins across Lampung's coffee and cocoa districts before village-level farmer groups complete direct blender contract transitions. Defend margin position through backward integration into active ingredient sourcing from Chinese and Indian suppliers, circumventing import licensing bottlenecks that constrain synthetic formulation competitors. For New Entrants and Emerging Players: Launch via digital agronomy platforms bundled with input purchases in Central Java's connected corn belts, bypassing traditional distributor markups that burden established channel relationships. Kalimantan's underpenetrated smallholder cocoa belts offer white-space opportunity for integrated seed-crop protection packages as wet-season disease pressure intensifies fungicide demand. For Investors and Strategic Acquirers: The window for entry favors certified fertilizer blenders with Ministry of Agriculture subsidy access and laboratory testing infrastructure already operational. Monitor biopesticide registration approval velocity as the inflection signal indicating when domestic biological entrants achieve competitive parity with synthetic incumbents on formulation cost and efficacy.| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Channel Partnership | Locks in procurement authority across Sumatra's consolidating smallholder belts ahead of competitor entry. |
| Backward Integration into Active Ingredients | Reduces exposure to Indonesia's agricultural regulator import licensing bottlenecks for novel chemistries. |
| Digital Agronomy Platform Deployment | Bayer's Java corn belt model demonstrates direct farmer relationship sustainability bypassing distributor markups. |
| Biopesticide Registration Investment | Accelerated approval timelines favor domestic biological entrants competing with synthetic incumbents on cost. |
| Certified Blending Facility Upgrade | Subsidy eligibility requirements filter procurement toward compliant producers with laboratory testing infrastructure. |
Research Methodology
Document review covered Ministry of Agriculture subsidy policy filings, BIS-equivalent national fertilizer quality standards, and pesticide registration databases, complemented by interviews with cooperative procurement managers, estate agronomists in Riau and North Sumatra, fertilizer blending facility operators, and distribution channel partners across Java and Sumatra. Secondary validation drew from customs import records for active ingredients, plantation operator procurement disclosures, and regional agricultural extension service reports. Bottom-up demand aggregation across crop types and operational scales was cross-checked against top-down market sizing from formulation capacity and import dependency ratios.
Historical volume trajectories for herbicide, fungicide, and fertilizer segments were cross-referenced against panel input from procurement managers at palm oil estates and cooperative buying group leaders. The analytical framework modeled product type, end-use industry, distribution channel, and application method dimensions across the projection horizon. CAGRs were derived from trend extrapolation moderated by policy shift assumptions around subsidy reform implementation and biopesticide registration pathway maturation. Forecast inputs incorporated climate volatility indices affecting wet-season disease pressure and labor cost trajectories in estate-dominated regions.
Subsidy restructuring delays, biopesticide approval timeline extensions, and phosphate-potash supply disruptions are the dominant revision risks that could compress or extend growth trajectories. Forecasts reflect documented assumptions around cooperative consolidation velocity and digital platform penetration rates in Java's connected regencies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Global Buprofezin Market