
 Asia-Pacific Molluscicides Market | 2026-2036
Asia-Pacific Molluscicides Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Molluscicides Market Outlook
Australian chemical manufacturers is recalibrating production schedules to align with seasonal planting cycles across Southeast Asia. Nufarm Ltd. leverages its regional distribution network to supply ferric phosphate formulations to Australian viticulture. BASF SE anchors its Asia-Pacific molluscicide portfolio through technical service partnerships with Indian rice cooperatives. Bayer AG competes on metaldehyde efficacy claims in Japan's protected vegetable sector.
Molluscicides constitute chemical or biological agents formulated to control gastropod pests through contact, ingestion, or reproductive disruption, with active concentrations typically ranging from three to five percent in commercial baits. These products protect yield-bearing crops and aquatic infrastructure by suppressing snail and slug populations that transmit parasites or directly damage plant tissue. Metaldehyde retains dominance in tropical field applications where humidity accelerates bait degradation, while ferric phosphate gains share in greenhouse and residential segments amid tightening vertebrate toxicity standards. Agricultural fields generate the largest volume demand, though aquatic systems represent the fastest-growing application as irrigation reservoir maintenance intensifies across water-stressed regions.
India's Central Insecticides Board mandates residue limits for agricultural chemicals entering domestic food chains, compelling reformulation toward lower-dose metaldehyde granules. Australia's APVMA and Japan's Ministry of Agriculture enforce distinct efficacy data requirements that fragment registration timelines across the region. China's Ministry of Agriculture and Rural Affairs classifies molluscicides within broader agrochemical governance frameworks affecting import licensing and domestic manufacturing quotas. Stakeholders must monitor divergence between national maximum residue limits and emerging biocontrol registration pathways to anticipate portfolio restructuring requirements.
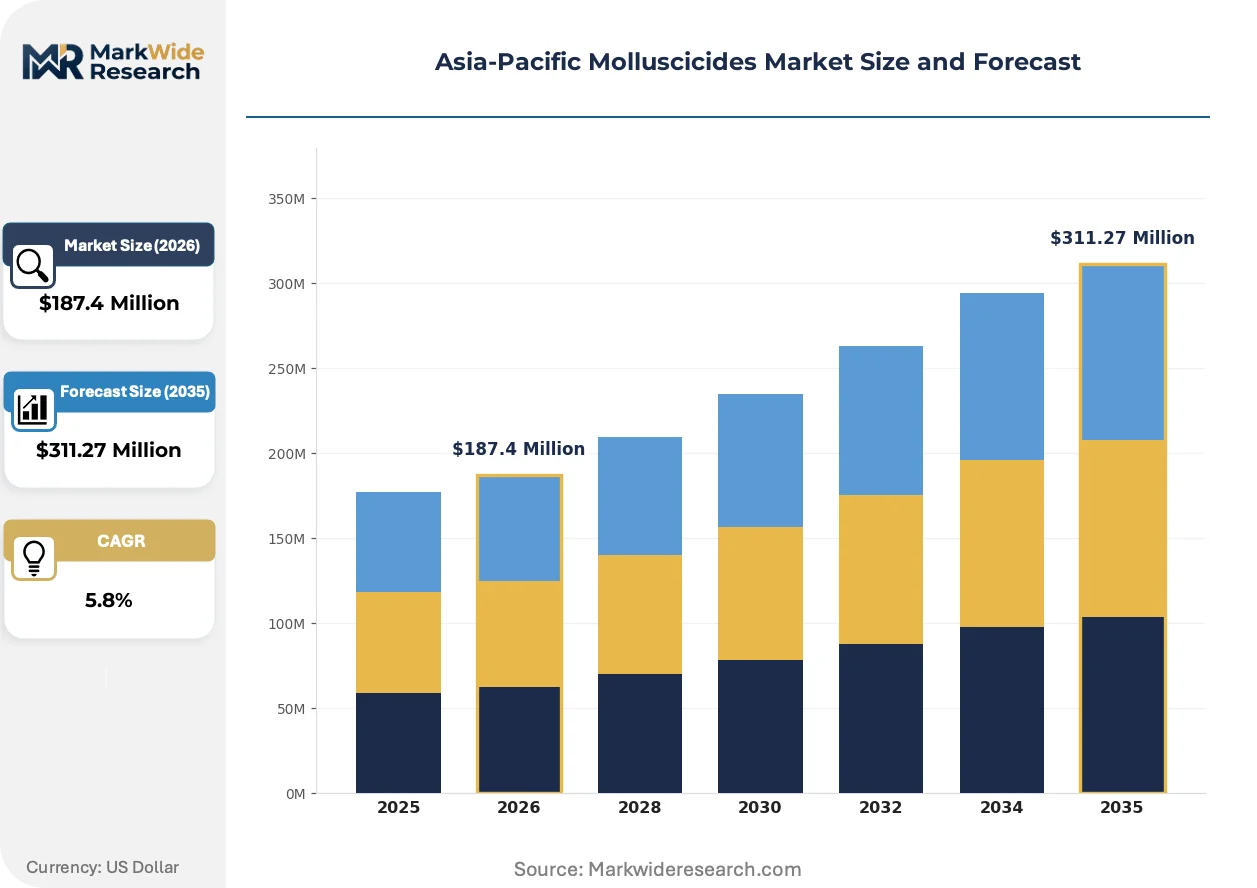
Market Dynamics
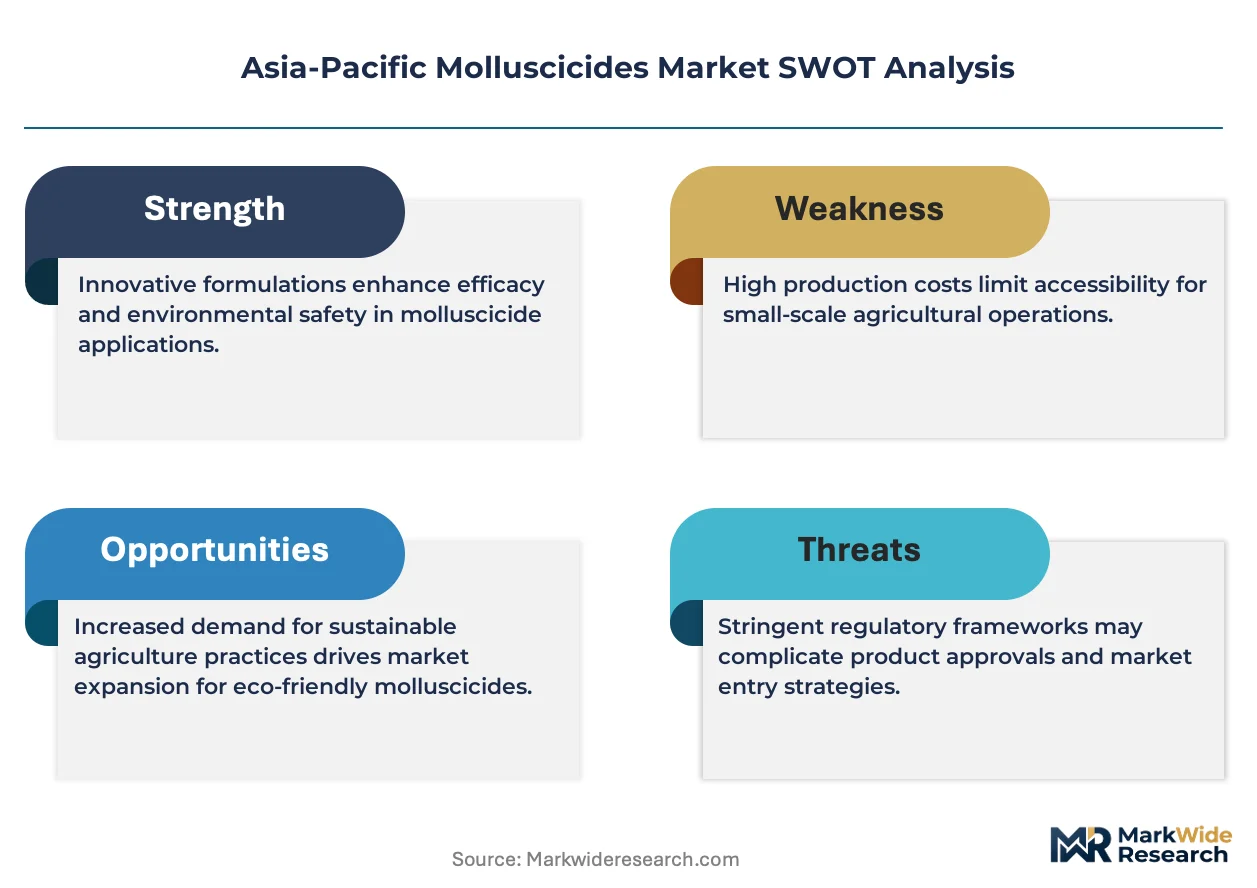
Regulatory divergence across Asia-Pacific jurisdictions is fragmenting product registration pathways and forcing manufacturers to maintain parallel formulation portfolios for metaldehyde and ferric phosphate variants.
Growth Catalysts
- Golden apple snail infestations:Rice cooperatives across Vietnam, Thailand, and the Philippines are escalating preventive treatment programs as irrigation infrastructure expands.
- India's horticulture intensification:Maharashtra and Gujarat state governments are subsidizing precision pest management equipment for protected vegetable cultivation.
- APVMA efficacy standards:Australia's rigorous field trial requirements are elevating baseline product quality expectations throughout Southeast Asian export markets.
Market Restraints
- Active ingredient cost volatility:Metaldehyde feedstock prices fluctuate with Chinese industrial chemical output cycles.
- Technical limitation:Ferric phosphate formulations exhibit reduced efficacy above 85% relative humidity, constraining tropical field deployment.
- Regulatory friction:Japan's Ministry of Agriculture mandates separate residue data packages for each crop-pest combination, extending registration timelines.
Strategic Opportunities
- Biological molluscicide development:Nematode-based products targeting snail reproduction cycles are attracting venture funding for Australian vineyard trials.
- Direct-to-cooperative distribution:Indian Farmer Producer Organizations are consolidating procurement volumes and bypassing traditional agrochemical distributors.
- China's rural revitalization subsidies:Provincial agricultural departments are allocating funds for integrated pest management demonstration projects in Jiangsu and Zhejiang.
Industry Challenges
- Field trial capacity constraints:Qualified contract research organizations for molluscicide efficacy testing are concentrated in Australia and Japan, creating bottlenecks for regional registration submissions.
- Legacy bait manufacturing equipment:Southeast Asian toll manufacturers require capital upgrades to meet ferric phosphate granule uniformity specifications demanded by Japanese importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Molluscicides Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metaldehyde, Ferric Phosphate, Sodium Nitrate, Niclosamide Application: Agricultural Fields, Aquatic Systems, Residential Areas, Greenhouses End User: Farmers, Commercial Growers, Household Consumers, Agriculture Cooperatives Distribution Channel: Online Retail, Agricultural Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Nufarm Ltd., PI Industries, BASF SE, Bayer AG, UPL Limited, Arxada, Lonza Group, Marrone Bio Innovations, ADAMA Agricultural Solutions, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Molluscicides Market Strategic Shifts
Formulation chemistry and application technology are converging to address the tension between tropical field efficacy and vertebrate safety standards. Three developments are restructuring competitive positioning.
Microencapsulated metaldehyde baits with humidity-triggered release mechanisms are extending field persistence in monsoon climates. Vietnamese rice farming cooperatives are piloting drone-dispersed applications to reduce labor exposure. This precision delivery approach is decentralizing application control from centralized spraying contractors to individual farm managers.
China's Ministry of Agriculture and Rural Affairs is tightening maximum residue limits for organophosphate alternatives in rice paddies. Domestic manufacturers are accelerating metaldehyde granule reformulation to preempt compliance deadlines. Protected vegetable growers in Shandong province are shifting procurement toward pre-certified import formulations to avoid registration delays.
Japanese protected vegetable growers are unbundling molluscicide purchases from bundled crop protection programs. Major supermarket chains are mandating supplier-specific residue documentation, forcing growers to specify active ingredient sources. This specification requirement is most pronounced in Kyushu's greenhouse tomato and strawberry sectors.
Asia-Pacific Molluscicides Market Segmentation
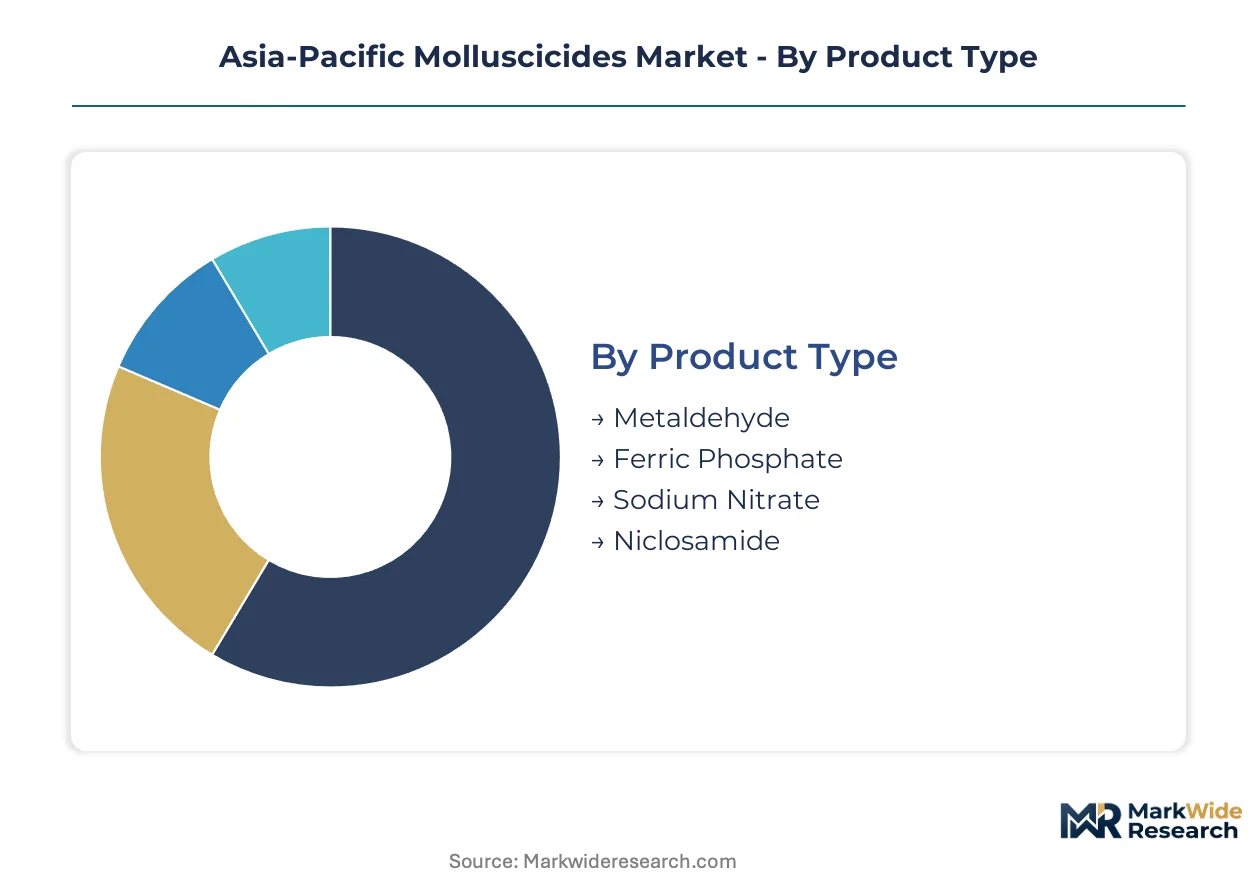
Molluscicide procurement patterns diverge sharply across Asia-Pacific, with regulatory stringency in Australia and Japan elevating certification costs for certain formulations while Indian and Vietnamese buyers prioritize unit economics. Segmentation reveals how product chemistry, application setting, and channel structure collectively determine margin architecture and registration investment priorities.
Product Type:
Metaldehyde formulations require APVMA field trial documentation for Australian registration, while ferric phosphate variants face escalating vertebrate toxicity scrutiny from Japan's Ministry of Agriculture. Sodium nitrate and niclosamide occupy narrower regulatory pathways tied to aquatic system approvals.
- Metaldehyde:Synthetic aldehyde compound formulated into moisture-activated granules and wettable powders for tropical field deployment. Rice cooperatives across Vietnam's Mekong Delta and Thailand's Central Plains specify metaldehyde for golden apple snail preventive programs, though humidity above 85% accelerates bait degradation and necessitates reapplication cycles that elevate per-hectare treatment costs.
- Ferric Phosphate:Iron-based compound engineered into palatable bait matrices with lower vertebrate toxicity profiles than aldehyde alternatives. Protected vegetable growers in Japan's Kyushu region and Australia's Yarra Valley viticulture districts are converting procurement toward ferric phosphate as supermarket chains mandate residue documentation that metaldehyde struggles to satisfy under tightened maximum residue limits.
- Sodium Nitrate:Inorganic salt deployed primarily in aquatic system applications for snail population suppression in irrigation reservoirs. Chinese provincial agricultural departments in Jiangsu specify sodium nitrate for integrated pest management demonstration projects targeting water-stressed rice cultivation zones.
- Niclosamide:Molluscicidal compound historically applied in public health programs for schistosomiasis vector control, now repurposed for agricultural aquatic systems. Philippine irrigation authorities utilize niclosamide in reservoir maintenance protocols alongside rice paddy border treatments.
Metaldehyde sits at the top of the volume ranking, with ferric phosphate climbing the fastest as vertebrate safety standards tighten across premium horticulture export corridors.
Application:
Cost tier segmentation separates capital-intensive aquatic system treatments from recurring agricultural field expenditures, with greenhouse applications commanding formulation premiums for humidity-stable variants.
- Agricultural Fields:Open-field rice paddies and broadacre horticulture generating the largest absolute volume demand across Southeast Asia. Maharashtra and Gujarat state subsidy programs for precision pest management equipment are accelerating granular bait adoption among Indian smallholders cultivating protected vegetables in peri-urban clusters.
- Aquatic Systems:Irrigation reservoirs, drainage canals, and rice paddy water management infrastructure representing the steepest expansion trajectory as water stress intensifies registration investment in molluscicidal reservoir maintenance. Vietnamese state irrigation corporations are expanding preventive treatment contracts for golden apple snail containment in newly constructed delta water control structures.
- Residential Areas:Consumer-directed slug and snail control for garden maintenance and property protection. Australian metropolitan garden centers report ferric phosphate preference among suburban consumers responding to pet toxicity awareness campaigns.
- Greenhouses:Controlled-environment horticulture requiring low-humidity degradation formulations. Japanese protected vegetable growers in Shizuoka and Chiba prefectures specify microencapsulated variants to satisfy supermarket chain residue documentation requirements.
Agricultural fields command the largest revenue pool, with aquatic systems expanding most quickly as irrigation infrastructure investment accelerates across water-stressed rice cultivation belts.
End User:
Customer type segmentation reveals procurement consolidation among Indian Farmer Producer Organizations alongside persistent fragmentation among Southeast Asian smallholders.
- Farmers:Individual smallholders and family operations constituting the broadest addressable base across Indonesia, Philippines, and Vietnam. These buyers prioritize unit cost over formulation sophistication, driving demand for basic metaldehyde granules distributed through provincial agricultural supply cooperatives.
- Commercial Growers:Corporate and contract farming operations with technical staff capable of managing application timing and residue compliance documentation. Australian viticulture estates and Japanese greenhouse tomato operations fall within this segment, specifying pre-certified import formulations to avoid registration delays.
- Household Consumers:Residential garden maintenance purchasers acquiring small-format retail packaging. Urban Australian and Japanese consumers demonstrate willingness to pay formulation premiums for vertebrate-safe ferric phosphate variants.
- Agriculture Cooperatives:Consolidated procurement entities gaining share fastest in India where Farmer Producer Organizations in Maharashtra bypass traditional distributors to negotiate direct manufacturer relationships. These cooperatives aggregate volume sufficient to justify technical service partnerships with multinational suppliers.
Farmers retain the widest population footprint, with agriculture cooperatives gaining share fastest as Indian procurement consolidation accelerates.
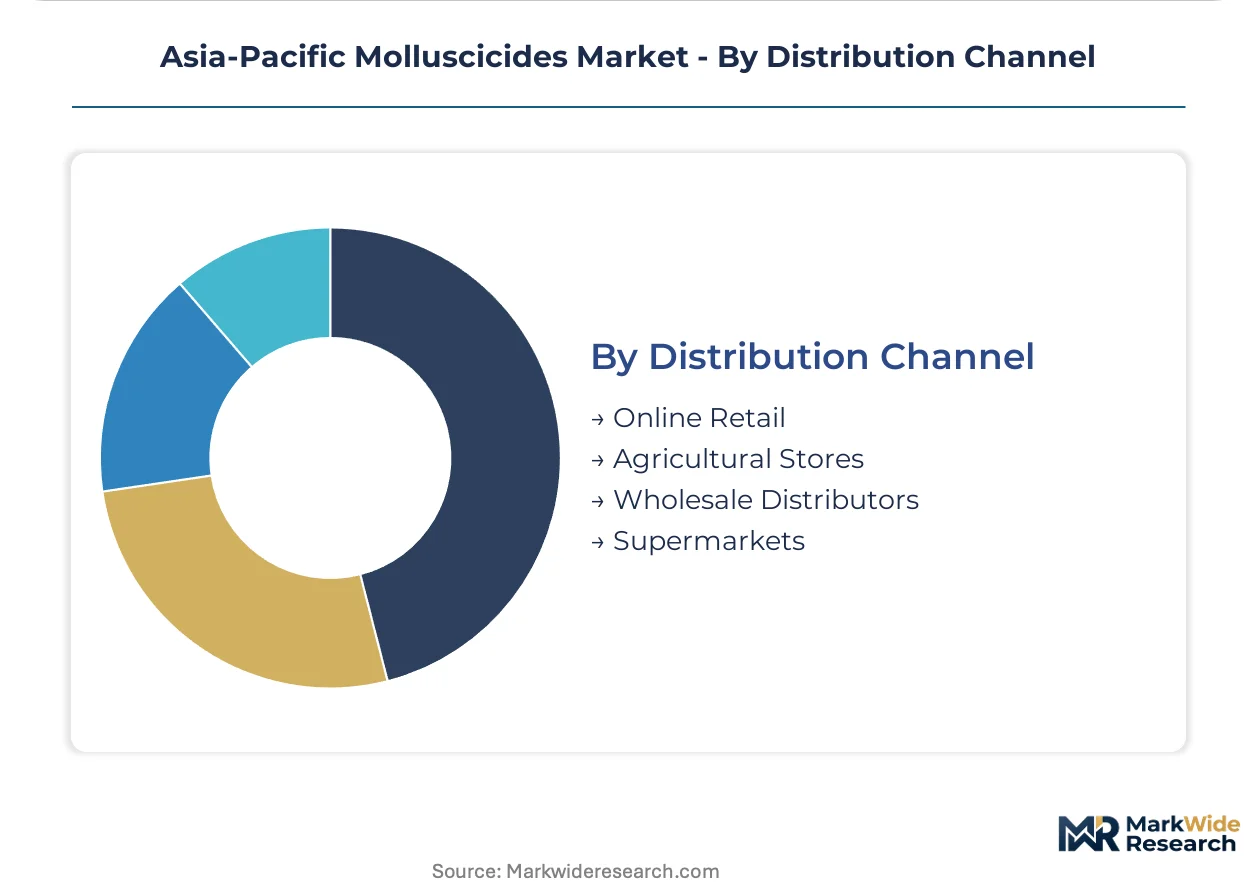
Distribution Channel:
Channel structure reflects geographic digital penetration variance, with online retail advancing in urban Australia and Japan while agricultural stores dominate Southeast Asian rural access.
- Online Retail:E-commerce platforms and direct manufacturer portals capturing urban professional growers and research institutions. Australian viticulture technical managers utilize online channels to source specialized ferric phosphate formulations with batch-specific residue certification.
- Agricultural Stores:Provincial supply cooperatives and independent rural retailers serving smallholder rice cultivation across Vietnam, Thailand, and Indonesia. These outlets maintain metaldehyde inventory aligned with monsoon planting calendars.
- Wholesale Distributors:Regional logistics networks handling bulk formulation import and toll manufacturing coordination. Nufarm Ltd. leverages wholesale infrastructure to supply Australian viticulture while managing Southeast Asian seasonal demand spikes.
- Supermarkets:Mass retail channels for consumer-format residential products. Japanese home center chains stock ferric phosphate garden baits with prominent pet safety labeling to differentiate from metaldehyde alternatives.
Agricultural stores maintain the deepest rural penetration, with online retail advancing fastest among technically sophisticated commercial growers requiring documentation traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers relocate formulation capacity to jurisdictions with streamlined agrochemical registration pathways. Cost-of-compliance gaps between Australia and Southeast Asian markets are accelerating toll manufacturing partnerships in Thailand and Vietnam.
Australia
APVMA efficacy documentation requirements for metaldehyde field trials are elevating baseline quality standards across export-oriented supply chains. Victoria's viticulture districts and New South Wales rice cultivation zones concentrate demand for ferric phosphate formulations with batch-specific residue certification. Melbourne-based technical service partnerships anchor multinational supplier relationships throughout the region.
India
Maharashtra and Gujarat state subsidy programs for precision pest management equipment are accelerating granular bait adoption among protected vegetable growers. The Central Insecticides Board mandates residue limits compelling reformulation toward lower-dose metaldehyde variants. Farmer Producer Organizations in western states are consolidating procurement volumes and negotiating direct manufacturer relationships that bypass traditional distributor networks.
China
Jiangsu and Zhejiang provincial agricultural departments are allocating rural revitalization funds toward integrated pest management demonstration projects. The Ministry of Agriculture and Rural Affairs classifies molluscicides within broader agrochemical governance frameworks affecting import licensing and domestic manufacturing quotas. Shandong province greenhouse operators are shifting procurement toward pre-certified import formulations to avoid registration delays.
Japan
Ministry of Agriculture mandates for separate residue data packages per crop-pest combination are fragmenting registration timelines and elevating compliance costs. Kyushu's greenhouse tomato and strawberry sectors are unbundling molluscicide purchases from bundled crop protection programs as supermarket chains mandate supplier-specific residue documentation. Chiba and Shizuoka prefectures specify microencapsulated variants for controlled-environment horticulture.
Vietnam
Mekong Delta rice cooperatives are escalating preventive treatment programs for golden apple snail containment as irrigation infrastructure expands. State irrigation corporations are awarding preventive treatment contracts for newly constructed delta water control structures. Vietnamese toll manufacturers are piloting drone-dispersed applications to reduce labor exposure and decentralize application control.
Asia-Pacific Molluscicides Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biological formulation development and direct-to-cooperative distribution models. The vendor base stratifies across three maturity tiers: multinational agrochemical conglomerates with technical service partnerships, regional formulators with seasonal production flexibility, and venture-funded biological specialists targeting niche vineyard applications. Two dominant competitive moves are consolidating procurement relationships with Indian Farmer Producer Organizations and securing APVMA registration documentation for Southeast Asian export positioning.
Among Asia-Pacific-based suppliers, PI Industries and UPL Limited occupy positions within the regional formulator tier, leveraging seasonal production schedules to align with monsoon planting cycles across Southeast Asia. BASF SE anchors the multinational technical service partnership model through collaborations with Indian rice cooperatives. These three entities exemplify divergent strategic archetypes: domestic Indian manufacturing scale, regional toll formulation flexibility, and global R&D-backed portfolio breadth.
| Leading Market Players |
|---|
| Nufarm Ltd. |
| PI Industries |
| BASF SE |
| Bayer AG |
| UPL Limited |
| Arxada |
| Lonza Group |
| Marrone Bio Innovations |
| ADAMA Agricultural Solutions |
| Others |
Value Chain & Pricing Dynamics
Captive integration into ferric phosphate raw material sourcing anchors supply positioning and pricing power for Japanese and Australian formulators navigating APVMA and Ministry of Agriculture certification tiers. Metaldehyde feedstock volatility from Chinese industrial chemical output cycles compresses margins for Southeast Asian toll manufacturers lacking backward integration into aldehyde production.
Pricing Analysis
Distributor margin layers in Southeast Asian agricultural stores absorb 15-25 percent of ex-factory value before reaching Vietnamese rice cooperatives. Three-tier pricing structure across certified-import, domestically-registered, and unbranded generic levels separates Japanese greenhouse operators from Indian smallholders from Indonesian provincial buyers. Pricing pressure stems from ferric phosphate active ingredient cost inflation as iron ore processing capacity concentrates in Chinese state-owned refineries. Indian Farmer Producer Organizations demonstrate highest price sensitivity through consolidated volume negotiations, while Australian viticulture estates accept formulation premiums for batch-specific residue documentation.
Supply Chain Analysis
Reverse-logistics flows for expired bait returns and packaging recovery remain underdeveloped across Asia-Pacific, constraining circular economy positioning for sustainability-conscious buyers. Manufacturing gravity centers on China for metaldehyde synthesis, India for granule formulation and toll manufacturing, and Australia for APVMA-certified export production. Feedstock dependencies encompass Chinese industrial ethanol for aldehyde synthesis, Australian iron ore derivatives for ferric phosphate, and Japanese microencapsulation polymers for humidity-stable variants. Single-source vulnerability in Chinese ethanol supply chains threatens Southeast Asian formulators during industrial policy transition periods. Distribution runs through Nufarm Ltd.'s regional wholesale networks for Australian viticulture, agricultural store cooperatives for Vietnamese rice cultivation, and direct-to-cooperative channels for Indian Farmer Producer Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific molluscicides market functions as a regulatory compounder, with Japan's Ministry of Agriculture residue documentation mandates and Australia's APVMA efficacy standards continuously elevating compliance costs that filter into formulation premiums.
For Market Incumbents: To counter biological molluscicide venture funding in Australian vineyard trials, BASF SE and Bayer AG should deepen technical service partnerships with Indian rice cooperatives while accelerating backward integration into iron ore processing for ferric phosphate cost control. Certification investment in microencapsulation capacity addresses the 85 percent humidity efficacy threshold that constrains tropical field deployment.
For New Entrants and Emerging Players: Begin with nematode-based biological formulations targeting niche premium horticulture segments in Japan's Kyushu greenhouse corridor where supermarket chain residue documentation requirements have unbundled traditional crop protection bundles. Direct-to-cooperative distribution through Maharashtra Farmer Producer Organizations offers the most penetrable channel architecture, bypassing entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional toll manufacturers with seasonal production flexibility because APVMA registration documentation creates durable switching costs for Southeast Asian export positioning. Platform consolidation targets should emphasize Vietnamese and Thai formulators with existing drone-dispersion pilot capabilities. The signal to watch is divergence between national maximum residue limits and emerging biocontrol registration pathways that would force portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Ore Processing | Captive ferric phosphate supply secures margin control against Chinese feedstock volatility. |
| APVMA Registration Documentation Investment | Field trial data packages elevate baseline quality for Southeast Asian export positioning. |
| Direct-to-Cooperative Distribution Buildout | Maharashtra Farmer Producer Organization bypass routes disintermediate traditional wholesale networks. |
| Microencapsulation Capacity Addition | Humidity-triggered release mechanisms extend field persistence in monsoon rice cultivation zones. |
| Biological Molluscicide R&D Partnership | Nematode-based reproduction disruption targets Australian vineyard premium segments. |
Study Parameters
Multiple input streams — primary interviews with agrochemical plant managers, APVMA regulatory affairs consultants, and Indian Farmer Producer Organization procurement heads; secondary validation through customs trade data, Australian Pesticides and Veterinary Medicines Authority registration databases, and SEC filings from listed suppliers — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed technical discussions with Vietnamese rice cooperative agronomists, Japanese greenhouse tomato growers, and Chinese provincial agricultural department officials across Jiangsu and Zhejiang demonstration project sites.
Historical consumption patterns were cross-referenced against panel input from multinational formulators and regional toll manufacturers to construct the analytical framework. Segmentation dimensions modeled encompass product chemistry tier, application setting, end-user procurement consolidation level, and distribution channel digital penetration. CAGRs were derived through trend extrapolation adjusted for regulatory milestone impacts and irrigation infrastructure investment trajectories. Industry-specific forecast inputs incorporated golden apple snail infestation surveillance data from Mekong Delta agricultural extension services and Maharashtra state subsidy program disbursement schedules.
Several conditions sit outside the modeled scope, including potential prohibition of metaldehyde active ingredients under vertebrate toxicity reviews, abrupt shifts in Chinese industrial chemical export licensing, and unforeseen biological control efficacy breakthroughs. Forecasts reflect assumptions regarding sustained rice cultivation intensification and irrigation infrastructure expansion that could revise materially under climate stress scenarios. Periodic stress-testing of base assumptions against APVMA registration timeline delays and Japanese Ministry of Agriculture residue limit adjustments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
India Herbicide Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
India Insecticide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Azoxystrobin Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Grape Fungicides Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Global Insect Pest Control Market