
 Asia-Pacific Acaricides Market | 2026-2036
Asia-Pacific Acaricides Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Acaricides Market Outlook
Greenhouse horticulture is rebalancing demand toward precision acaricide formulations as controlled-environment agriculture expands across East and Southeast Asia. Bayer AG leverages its biological research pipeline to sustain product differentiation in mite-specific chemistry. Syngenta Group anchors its regional position through integrated seed-protection bundles that lock in recurring acaricide demand. UPL Limited competes on price-accessible emulsifiable concentrates tailored to smallholder procurement patterns.
Acaricides are crop-protection chemicals specifically formulated to kill or repel mites and ticks, typically containing active ingredients such as abamectin, bifenazate, or etoxazole that disrupt arthropod nervous systems or growth regulation. These compounds serve commercial agriculture and horticulture by preventing yield loss from spider mite infestations that thrive in warm, dry climates prevalent across the Asia-Pacific. Among product types, pyrethroids retain volume leadership in broadacre spraying while bio-based formulations capture the fastest expansion as residue limits tighten in export-oriented supply chains. Liquid formulations dominate operational convenience in mechanized farming, though wettable powders persist in cost-sensitive segments where water access enables tank-mix flexibility.
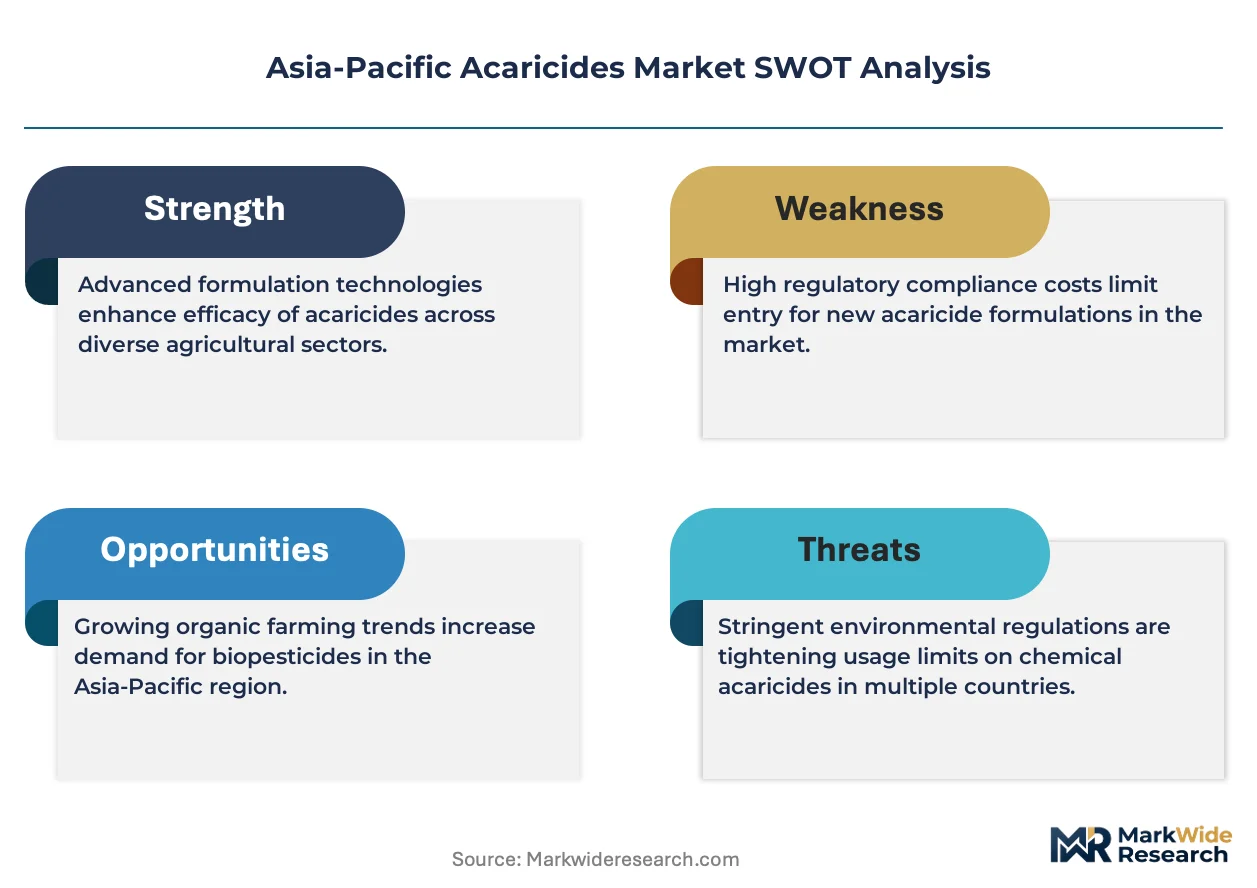
India's Central Insecticides Board regulates acaricide registration through mandatory field-efficacy trials that extend product commercialization timelines. Australia's APVMA enforces residue standards that shape export-bound formulation specifications for horticultural producers. China's Ministry of Agriculture and Rural Affairs manages pesticide production licenses that constrain unauthorized manufacturing capacity. Stakeholders must monitor how divergent national residue protocols fragment product registration strategies across the region.
Market Dynamics
Mite resistance proliferation across Shandong province's strawberry and tomato greenhouses is forcing commercial growers toward precision rotation protocols that alternate chemical modes of action rather than relying on single-active programs.
Growth Catalysts
- India's PLI scheme for agrochemical manufacturing:Production-linked incentives are drawing formulation investment toward domestic acaricide synthesis, reducing import dependency for emulsifiable concentrates used in cotton and vegetable cultivation.
- Export-oriented residue compliance:Australia's APVMA residue standards are reshaping formulation specifications for horticultural producers supplying supermarket chains in Japan and South Korea, creating premium tier demand for low-residue pyrethroids.
- Controlled-environment agriculture expansion:Greenhouse horticulture clusters across East and Southeast Asia are rebalancing procurement toward precision acaricide formulations as spider mite pressure intensifies in climate-controlled tomato and pepper operations.
Market Restraints
- Active ingredient cost volatility:Abamectin and etoxazole feedstock prices fluctuate with petrochemical input costs, compressing margin stability for generic formulation producers serving price-sensitive smallholder segments.
- Registration timeline friction:India's Central Insecticides Board mandates multi-season field-efficacy trials that extend product commercialization timelines by 24-36 months, delaying revenue realization for new molecular entries.
- Biological substitution threat:Predatory mite biocontrol products are capturing share in high-value greenhouse vegetables as residue limits tighten in Japanese and South Korean import protocols.
Strategic Opportunities
- Vietnam's Mekong Delta contract farming:Rice-to-vegetable rotation systems in An Giang and Dong Thap provinces remain underpenetrated by organized acaricide distribution, offering first-mover advantage for bundled crop-protection programs.
- Bio-based formulation convergence:Integration of microbial fermentation-derived actives with nano-delivery systems is opening premium positioning in organic-certified export supply chains serving European retailers.
- E-channel procurement platforms:Alibaba and agritech marketplaces are disintermediating traditional distributor networks in China's Shandong and Hebei provinces, enabling direct manufacturer-to-grower transactions with dynamic pricing.
Industry Challenges
- Resistance management expertise scarcity:Field agronomists capable of designing rotation protocols that preserve active ingredient efficacy are concentrated in research institutions rather than extension services serving smallholder clusters.
- Dual registration complexity:Formulators seeking to serve both domestic Chinese markets and export-oriented Australian horticulture must maintain parallel specification lines, fragmenting production runs and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Acaricides Market |
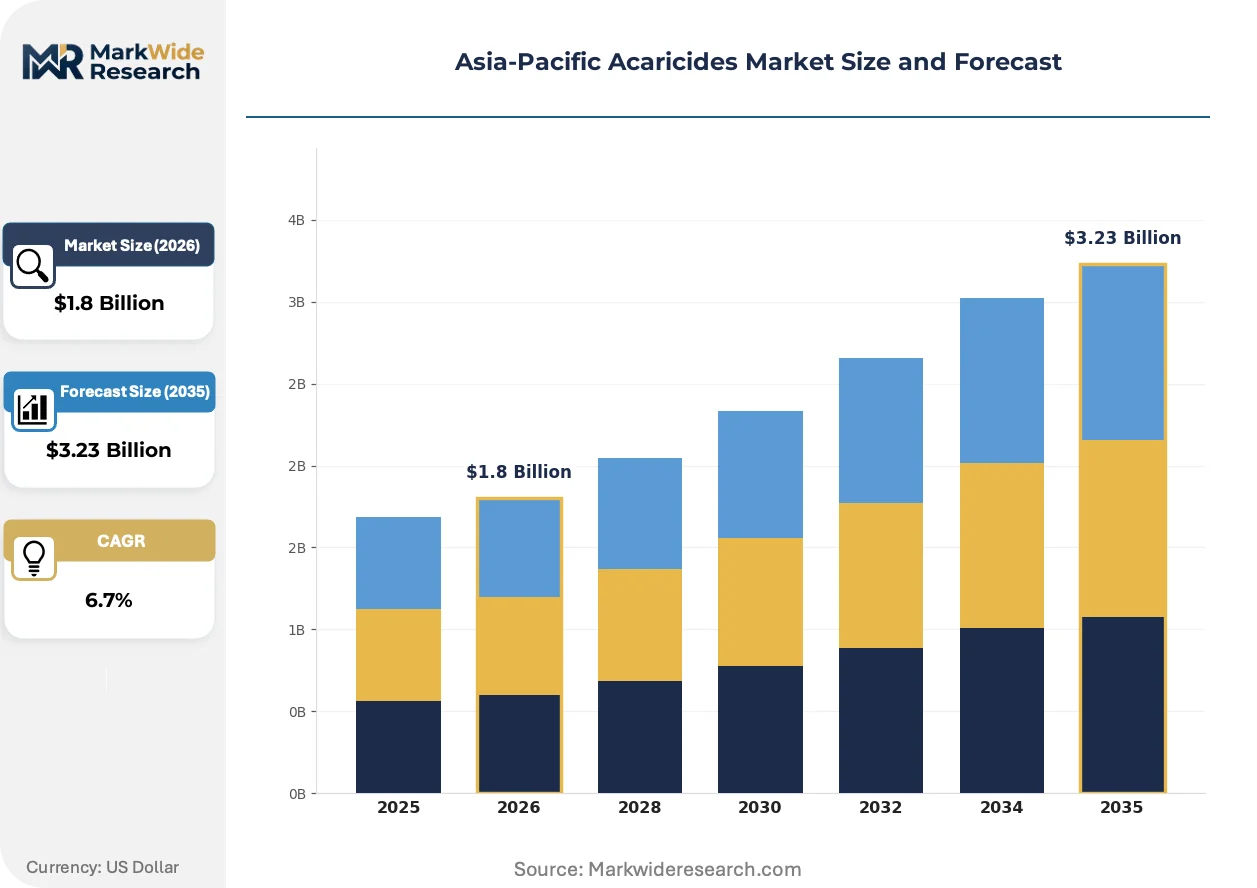
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organophosphates, Carbamates, Pyrethroids, Bio-based Application: Agriculture, Horticulture, Turf Management, Greenhouse End User: Farmers, Commercial Growers, Residential Users, Agribusiness Formulation Type: Liquid, Granular, Emulsifiable Concentrates, Wettable Powders |
| Companies Covered | Nissan Chemical Corporation, Bayer AG, BASF SE, Syngenta Group, FMC Corporation, Sumitomo Chemical Co., Ltd., ADAMA Ltd, Nufarm Limited, UPL Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Acaricides Market Strategic Shifts
Biological and synthetic chemistry boundaries are dissolving as residue thresholds harden in premium export channels, compressing development cycles toward hybrid actives that satisfy both efficacy and compliance requirements simultaneously.
RNA interference-based acaricide platforms are consolidating research investment from major agrochemical pipelines as the technology demonstrates species-specific mite suppression without broad-spectrum ecological disruption. Greenhouse operators in Japan's Chiba prefecture are piloting these formulations under METI-supervised efficacy trials. The technology is consolidating competitive advantage around firms with captive biotech research infrastructure rather than traditional chemistry synthesis capabilities.
China's Ministry of Agriculture and Rural Affairs is tightening production license enforcement through the 2024 pesticide management regulation revision, shuttering unauthorized manufacturing capacity in Shandong and Jiangsu provinces. Small-scale formulators lacking SAMR-compliant quality systems face consolidation pressure or exit. Export-bound producers are accelerating GB standard certification to maintain access to regulated Australian and Japanese markets.
Direct-to-farm digital procurement is displacing multi-tier distributor networks across India's Maharashtra and Karnataka vegetable belts, with UPL and domestic competitors deploying proprietary apps that bundle credit, weather data, and acaricide recommendations. Younger commercial growers in these clusters prefer platform-based purchasing with transparent pricing over traditional commission-based dealer relationships. This channel shift is most visible in tomato and chili cultivation regions where smartphone penetration exceeds 70 percent among farm operators under 45 years old.
Asia-Pacific Acaricides Market Segmentation
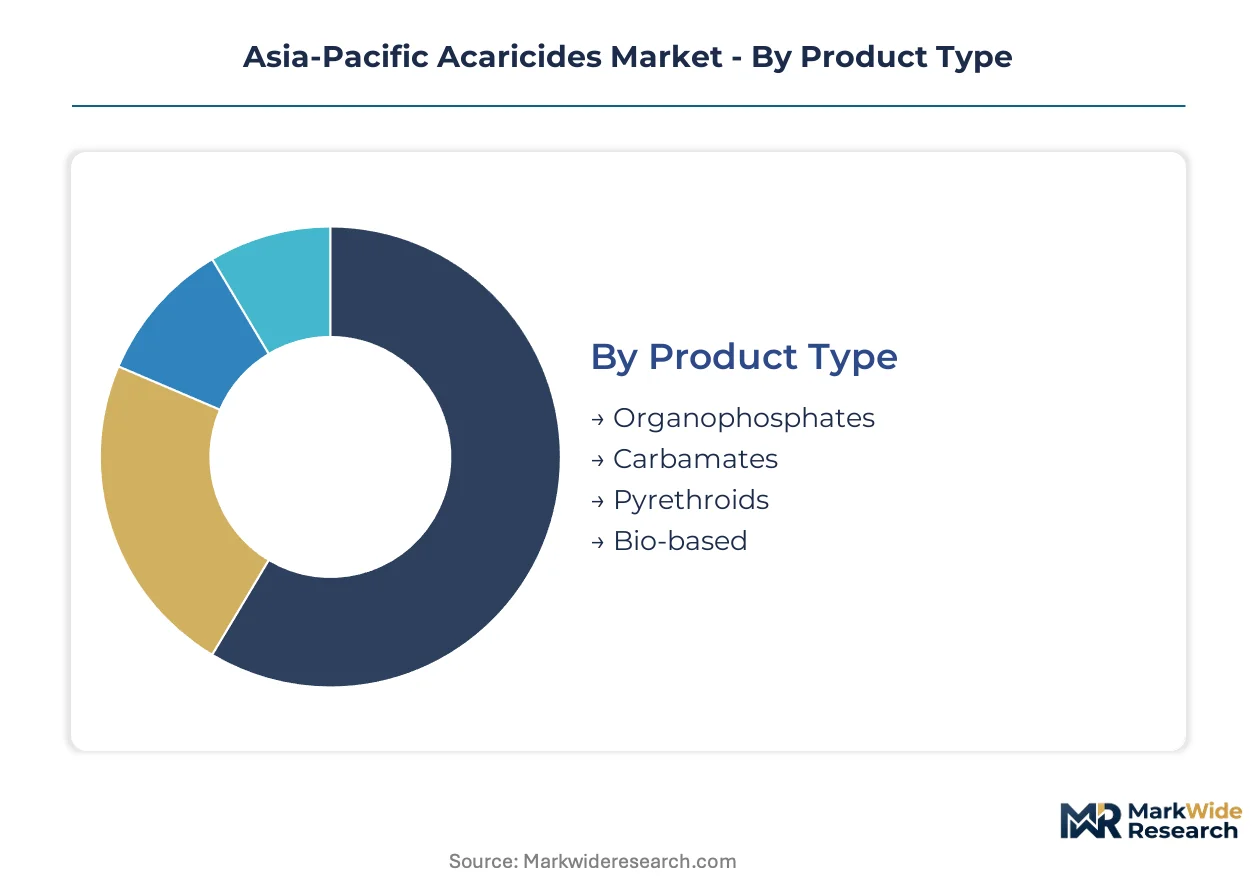
Acaricide procurement patterns diverge sharply across the Asia-Pacific based on operational scale, residue compliance requirements, and irrigation infrastructure. Buyers select formulations through distinct technical and economic filters that reshape competitive positioning within each segment cluster.
Product Type:
Commercial growers prioritize efficacy persistence and resistance management when selecting active ingredient chemistry for mite control programs.
- Pyrethroids:Synthetic esters derived from chrysanthemum acid analogs deliver rapid knockdown against spider mites in broadacre cotton and vegetable operations. Procurement concentrates in India's Maharashtra and Gujarat states where mechanized spraying equipment dominates.
- Bio-based:Fermentation-derived abamectin and botanical extracts satisfy Japan's MHLW residue limits for export-bound horticulture. Demand climbs fastest in Shandong province's organic-certified strawberry greenhouses supplying supermarket chains.
- Organophosphates:Cholinesterase inhibitors retain cost advantage in rice paddy ecosystems across Vietnam's Mekong Delta where water access enables dilute spraying.
- Carbamates:N-methyl carbamate compounds serve niche applications in Australia's citrus orchards under APVMA-mandated buffer zone restrictions.
Pyrethroids lead on scale; bio-based leads on momentum.
Application:
End-use environments dictate formulation specifications through climate control availability and harvest frequency constraints.
- Greenhouse:Climate-controlled tomato and pepper operations in Japan's Chiba prefecture require precision micro-encapsulated formulations that minimize phytotoxicity under artificial lighting. Shandong province's hydroponic clusters drive concentrated procurement of rotation-ready acaricide bundles.
- Agriculture:Open-field cotton and chili cultivation across India's Telangana and Andhra Pradesh states consumes high-volume emulsifiable concentrates through tractor-mounted boom sprayers.
- Horticulture:Orchard and vineyard applications in Australia's Riverina region prioritize rain-fast formulations with extended residual activity.
- Turf Management:Golf course and sports field maintenance in South Korea's Gyeonggi province selects low-odor formulations for aesthetic compliance.
Greenhouse commands premium pricing; agriculture commands volume throughput.
End User:
Procurement sophistication scales with operational capitalization and access to agronomic advisory services.
- Commercial Growers:Contract farming entities in Vietnam's Dong Thap province leverage consolidated purchasing power to negotiate formulation customization from domestic manufacturers.
- Farmers:Smallholder chili and tomato producers in India's Karnataka state rely on distributor credit terms and weather-indexed bundling through agritech platforms.
- Agribusiness:Integrated seed-to-shelf operators in China's Hebei province specify acaricide-seed treatment combinations that lock in recurring chemical demand.
- Residential Users:Urban garden maintenance in Australia's metropolitan fringe consumes ready-to-use aerosol formulations through retail garden centers.
Commercial growers concentrate margin capture; farmers concentrate volume dispersion.
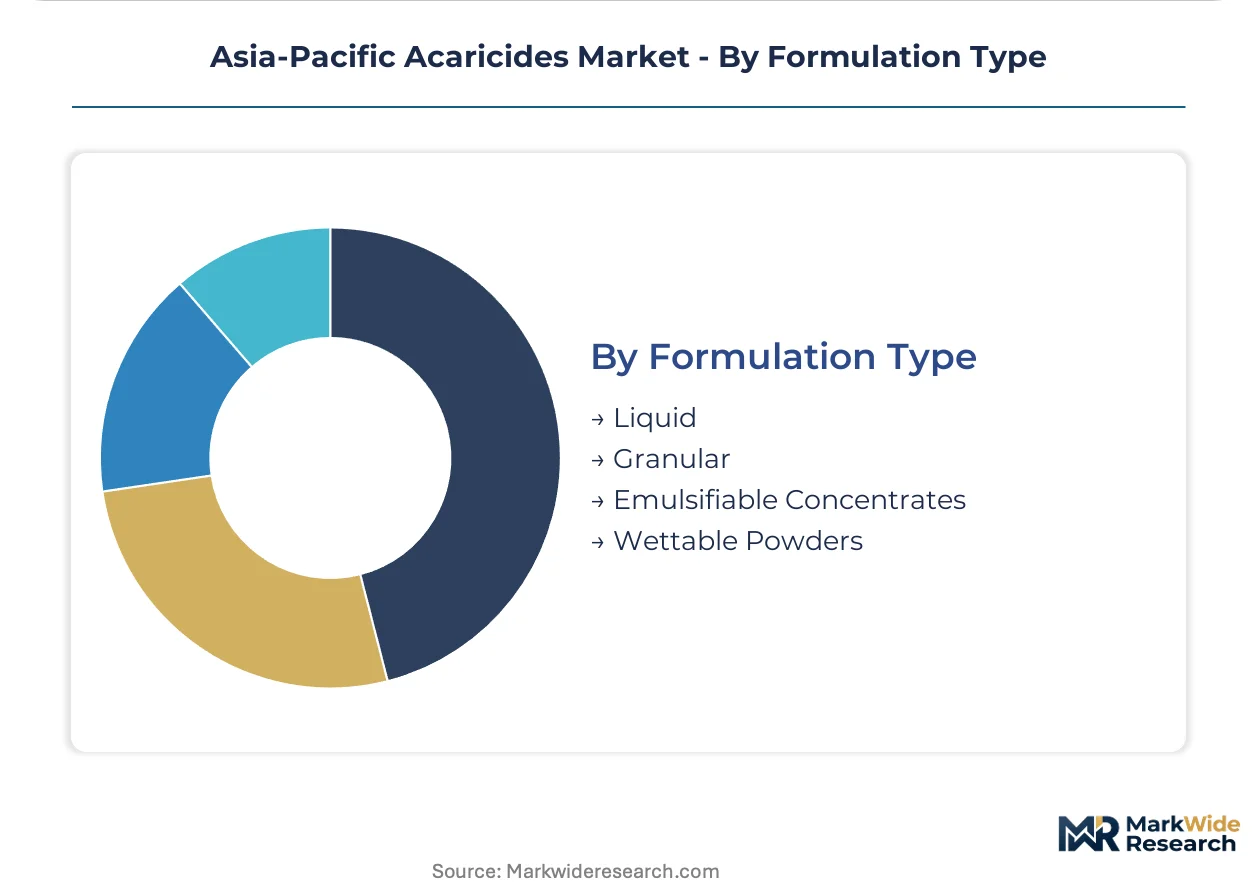
Formulation Type:
Physical form selection hinges on water access, equipment compatibility, and tank-mix flexibility requirements.
- Liquid:Pre-mixed suspensions dominate Australia's mechanical vineyard spraying where calibration precision reduces application error. East Asian greenhouse operators prefer liquid convenience for automated dosing systems.
- Emulsifiable Concentrates: Oil-in-water formulations serve India's cotton belt where hard water conditions demand surfactant stability. Smallholders value concentrated packaging that reduces transport costs from distribution hubs.
- Wettable Powders:Solid active ingredient carriers persist in cost-sensitive segments across Indonesia's vegetable highlands where on-farm water storage enables tank-mix preparation.
- Granular:Slow-release matrices apply in Australia's turf management sector for extended protection against soil-dwelling mite species.
Liquid leads on operational convenience; emulsifiable concentrates lead on cost elasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting acaricide formulation investment toward jurisdictions with streamlined registration pathways and production-linked incentive schemes, compressing lead times for new molecular entries while fragmenting compliance architectures across export-bound supply chains.
China
Shandong province's contract farming clusters drive bulk chemical offtake as greenhouse horticulture expands tomato and pepper cultivation under climate-controlled conditions. The Ministry of Agriculture and Rural Affairs tightened production license enforcement through 2024 regulation revisions, shuttering unauthorized manufacturing capacity in Shandong and Jiangsu provinces while accelerating GB standard certification for export-bound producers.
India
Maharashtra and Gujarat states concentrate mechanized cotton spraying demand for pyrethroid formulations, while Karnataka's vegetable belts shift toward platform-based procurement. The Central Insecticides Board mandates multi-season field-efficacy trials that extend commercialization timelines, though the PLI scheme for agrochemical manufacturing is drawing formulation investment toward domestic synthesis and reducing import dependency.
Japan
Chiba prefecture's greenhouse operators pilot RNA interference-based acaricide platforms under METI-supervised efficacy trials, targeting species-specific mite suppression for premium export horticulture. The Ministry of Health, Labour and Welfare enforces residue limits that reshape formulation specifications for supermarket supply chains, compressing development cycles toward hybrid actives that satisfy both efficacy and compliance requirements.
Australia
The Riverina region's citrus orchards and vineyard operations prioritize rain-fast formulations with extended residual activity under APVMA-mandated buffer zone restrictions. Australia's residue standards are reshaping specifications for horticultural producers supplying Japanese and South Korean import channels, creating premium tier demand for low-residue chemistry that exceeds domestic regulatory minimums.
Vietnam
An Giang and Dong Thap provinces in the Mekong Delta present underpenetrated rice-to-vegetable rotation systems where organized acaricide distribution remains nascent. Contract farming entities leverage consolidated purchasing power to negotiate formulation customization from domestic manufacturers, offering first-mover advantage for bundled crop-protection programs targeting chili and tomato cultivation clusters.
Asia-Pacific Acaricides Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents balance synthetic chemistry scale with biological research pipelines to capture premium positioning in residue-constrained export channels. The vendor base concentrates around three strategic archetypes: integrated agrochemical conglomerates with captive seed-protection bundles, mid-scale formulators competing on price-accessible concentrates for smallholder segments, and biotech-oriented specialists advancing RNA interference platforms. M&A activity and technology licensing partnerships represent the dominant competitive moves, with firms acquiring fermentation-derived active capabilities and nano-delivery system patents to bridge synthetic-biological formulation boundaries.
Within the integrated agrochemical tier, Bayer AG and Syngenta Group exemplify archetypes combining seed-treatment integration with recurring chemical demand lock-in, while UPL Limited occupies a position emphasizing price-accessible emulsifiable concentrates tailored to smallholder procurement patterns in India's vegetable belts. These three anchors represent divergent strategic vectors: premium bundled solutions, biological research differentiation, and cost-elastic volume penetration across fragmented grower bases.
| Leading Market Players |
|---|
| Nissan Chemical Corporation |
| Bayer AG |
| BASF SE |
| Syngenta Group |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| ADAMA Ltd |
| Nufarm Limited |
| UPL Limited |
| Others |
Value Chain & Pricing Dynamics
Abamectin feedstock price volatility cascades through Asia-Pacific acaricide supply chains into three-tier pricing structure across premium, standard, and economy levels, with petrochemical input swings compressing margin stability for generic formulators while export-certified producers capture premium tiers through residue-compliant specifications.
Pricing Analysis
Distributor margin layers in traditional agrochemical channels absorb 15-25 percent of ex-factory value before reaching smallholder buyers in India's vegetable belts, though Alibaba and agritech platforms are disintermediating these markups through direct manufacturer-to-grower transactions with dynamic pricing. Price differentiation rests on certification grade—GB standard compliance for Chinese domestic sales versus APVMA-aligned specifications for Australian export channels—and volume scale, with contract farming clusters negotiating formulation customization. Cost compression in economy-tier emulsifiable concentrates is intensifying because of abamectin and etoxazole feedstock instability. Smallholder farmers in Karnataka and Telangana exhibit highest price sensitivity, while Japanese greenhouse operators in Chiba prefecture prioritize residue compliance over unit cost.
Supply Chain Analysis
GB standard certification and APVMA registration requirements gate supply chain participation, constraining unauthorized manufacturing capacity in Shandong and Jiangsu provinces while privileging SAMR-compliant producers. Active ingredient synthesis concentrates in China and India, with formulation finishing distributed across regional hubs serving domestic markets. Raw material dependencies include petrochemical-derived intermediates for pyrethroid synthesis, fermentation substrates for abamectin production, and surfactant packages for emulsifiable concentrate stability. Single-source vulnerability persists for etoxazole technical supplies concentrated among limited Chinese manufacturers. Distribution runs through multi-tier networks in India's Maharashtra cotton belt, though platform-based procurement is displacing traditional dealer relationships in smartphone-penetrated vegetable clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific acaricide markets offer margin expansion through bio-based formulation premiumization and e-channel disintermediation, with residue-compliant chemistry capturing pricing power as Japanese and South Korean import thresholds tighten.
For Market Incumbents: Cement seed-protection bundle lock-in across China's Hebei province contract farming clusters, integrating acaricide-seed treatment combinations that generate recurring chemical demand. Deepen backward integration into fermentation-derived active production to secure captive supply of abamectin technical and reduce exposure to petrochemical feedstock volatility. Prioritize GB standard certification acceleration for export-bound capacity in Shandong province ahead of anticipated Ministry of Agriculture and Rural Affairs enforcement waves.
For New Entrants and Emerging Players: India's PLI scheme for agrochemical manufacturing opens a window for domestic formulation investment, enabling first-mover positioning in Maharashtra and Gujarat pyrethroid demand. Target Vietnam's Mekong Delta rice-to-vegetable rotation systems in An Giang and Dong Thap provinces, where organized acaricide distribution remains underpenetrated and contract farming entities seek bundled crop-protection programs. Deploy proprietary agritech apps bundling credit, weather data, and acaricide recommendations to capture Karnataka smallholder procurement shifting from traditional dealer relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotech-oriented specialists advancing RNA interference platforms under METI-supervised efficacy trials in Japan, where species-specific mite suppression commands premium positioning in residue-constrained export channels. Long-term viability centers on firms bridging synthetic-biological formulation boundaries through microbial fermentation-derived actives and nano-delivery system integration. Monitor predatory mite biocontrol adoption rates in Japanese greenhouse vegetables as inflection indicator for biological substitution threat intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Actives | Captive abamectin supply reduces petrochemical feedstock exposure for Indian formulators. |
| E-Channel Platform Development | Alibaba and proprietary apps disintermediate distributor markups in Shandong greenhouse clusters. |
| GB Standard Certification Acceleration | SAMR-compliant quality systems preserve export access to Australian and Japanese markets. |
| RNA Interference Platform Investment | Species-specific suppression technology consolidates advantage around biotech research infrastructure. |
| Seed-Protection Bundle Expansion | Integrated seed-treatment combinations lock in recurring demand across Hebei contract farming. |
Study Parameters
Coverage spans China, India, Japan, Australia, and Vietnam, with primary inputs from each market's commercial growers, formulation plant managers, Central Insecticides Board regulatory affairs leads, and distributor channel partners. Secondary validation draws from Ministry of Agriculture and Rural Affairs production license databases, APVMA residue standard filings, Indian customs trade data for agrochemical imports, and Alibaba agritech marketplace transaction records. Bottom-up volume estimates from state-level cultivation data and top-down value triangulation from manufacturer revenue disclosures were cross-referenced to ensure consistency.
Rate-of-change decomposition separates volume drivers—greenhouse horticulture expansion rates, cotton planting area shifts, mite resistance incidence—from value drivers including bio-based formulation mix shifts and premium tier penetration. Segmentation dimensions modeled include active ingredient chemistry class, application environment, end-user operational scale, and physical formulation type. CAGRs were derived from regression analysis against historical acreage trends and procurement intensity ratios, with RNA interference platform adoption curves incorporated as technology disruption scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory restriction scenarios such as unanticipated residue limit tightening or production license revocation waves. Model assumptions reflect current PLI scheme continuation, petrochemical price band stability, and platform-based procurement penetration trajectories. A model refresh is warranted upon material change in Ministry of Agriculture and Rural Affairs enforcement intensity or METI RNA interference trial acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Azoxystrobin Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
South America Insecticide Market
Crop Protection
Europe Herbicide Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Pest Management Services Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Soil Fumigant Market
Crop Protection
Pest Control Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
North America Insecticide Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Fruit and Vegetable Crop Protection Market