
 Vietnam Herbicide Market | 2026-2036
Vietnam Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Herbicide Market Insights
CE marking equivalence under Vietnam's BIS-aligned agricultural chemical registration protocol is bifurcating the competitive landscape into qualified multinationals and unregistered traders. Bayer CropScience AG leverages its integrated glyphosate technical manufacturing base in the region to sustain cost-advantaged supply. Syngenta Group anchors its position through proprietary mesotrione formulations tailored to tropical weed spectrums. BASF SE differentiates via glufosinate-ammonium technologies positioned against rising resistance concerns.
Herbicides constitute synthetic or biological agents engineered to inhibit photosystem II enzymes, disrupt amino acid biosynthesis, or interfere with cell division, typically formulated as emulsifiable concentrates or soluble powders with active ingredient loadings between 10% and 75%. Their commercial purpose centers on selective or total vegetation management across annual and perennial cropping systems. Non-selective herbicides command dominant volume share in Vietnam's industrial plantation sector, while post-emergent applications gain traction in horticulture where precision timing against established weed flushes protects yield. Liquid concentrates lead formulation preferences due to farmer familiarity with backpack sprayer delivery, though granules expand in mechanized rice transplanting zones.
Vietnam's Ministry of Agriculture and Rural Development (MARD) governs pesticide registration through Circular 21, while MEE enforces environmental release thresholds that restrict paraquat and certain organophosphate chemistries. These frameworks compel reformulation investments and accelerate bioherbicide pipeline prioritization. Stakeholders must monitor MARD's evolving positive list revisions and MEE effluent discharge mandates to anticipate product phase-outs and preemptive portfolio restructuring.
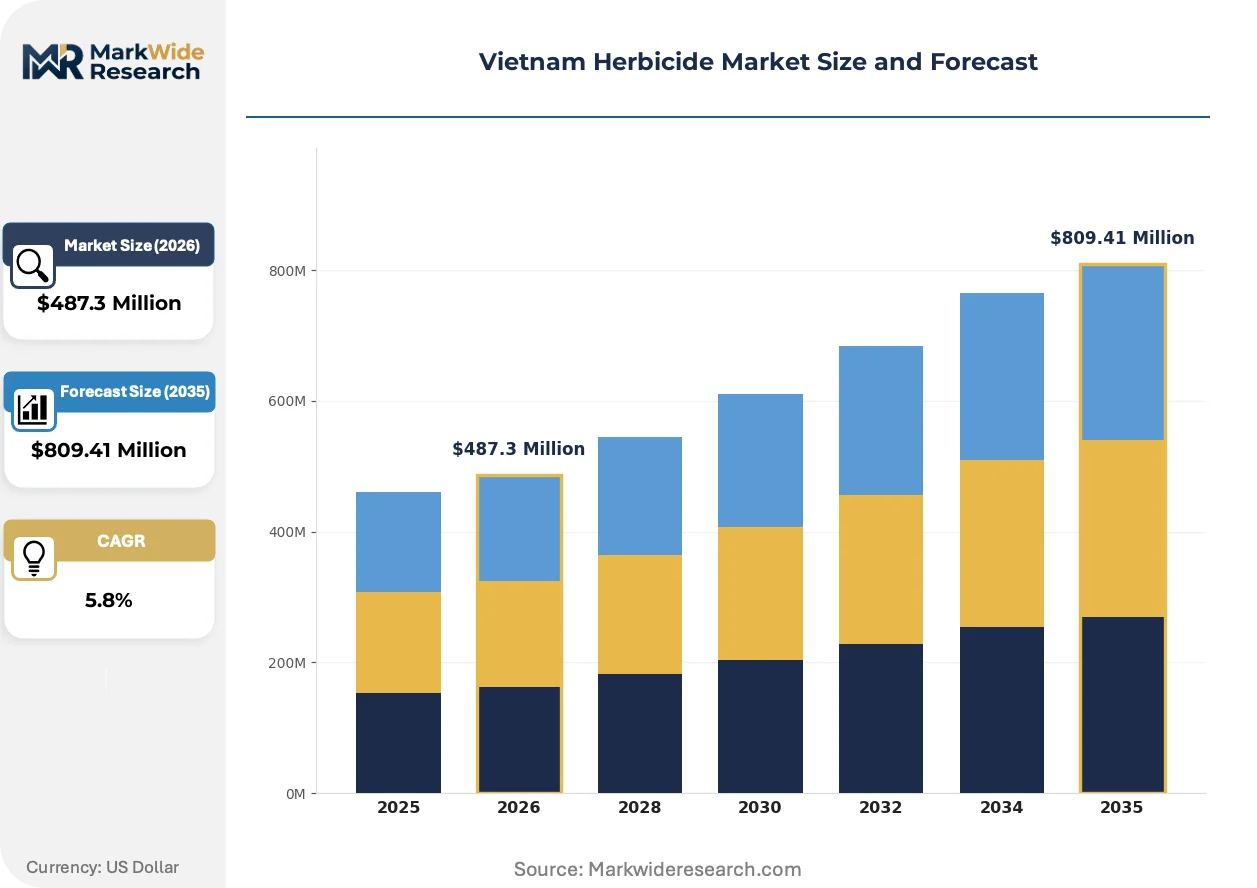
Market Dynamics
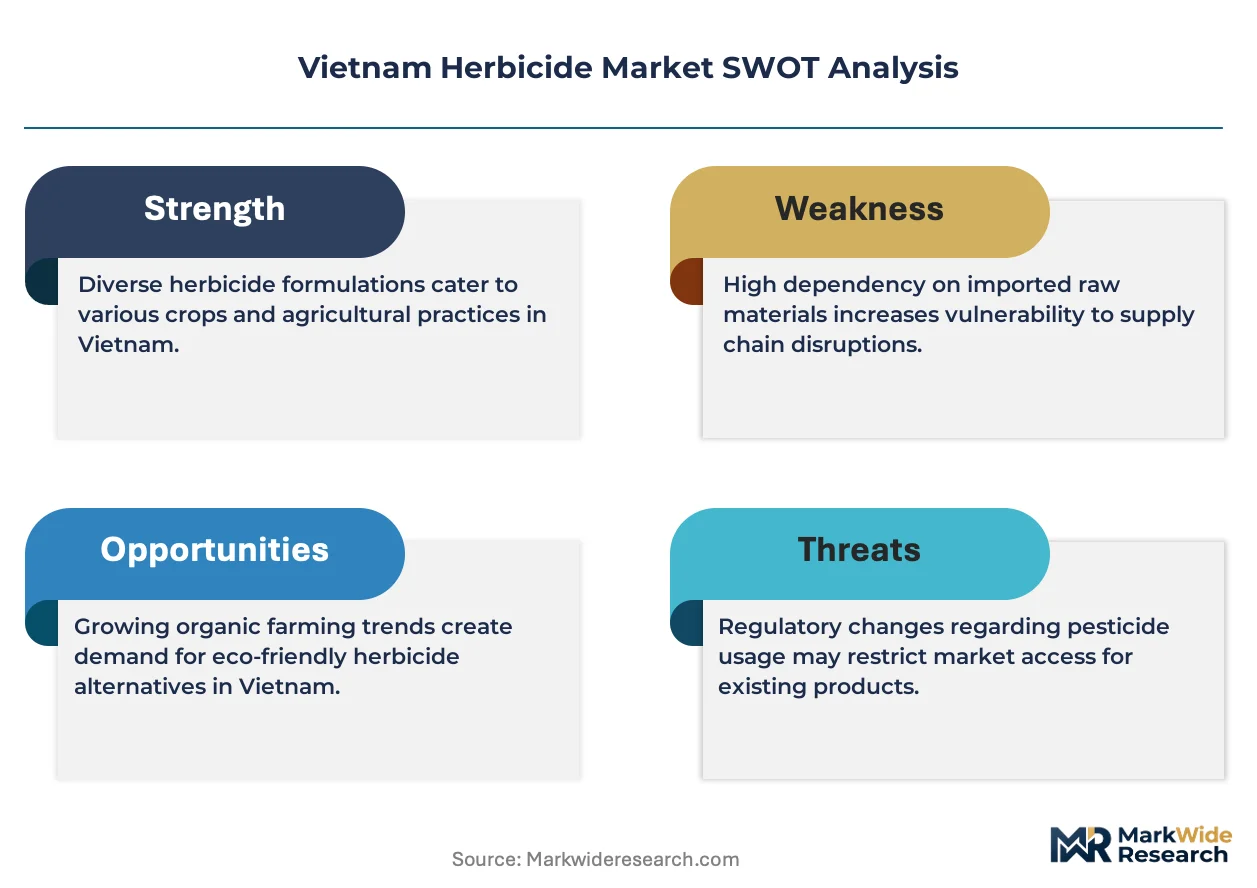
Vietnam's tightening MEE environmental standards on glyphosate residues are forcing rapid portfolio restructuring among registrants, bifurcating supply between compliant multinationals and informal traders operating outside Circular 21 protocols.
Growth Catalysts
- MEE Effluent Mandates:Stricter discharge thresholds for paraquat and organophosphates accelerate reformulation toward bioherbicide alternatives, creating first-mover advantages for compliant suppliers.
- Mekong Delta Rice Intensification:Expanded double-cropping schedules in An Giang and Dong Thap provinces drive post-emergent herbicide volume as farmers combat resistant barnyard grass flushes.
- Drone Application Technology:Precision aerial spraying reduces labor costs in mechanized transplanting zones, enabling higher-value formulated products to penetrate smallholder cooperatives.
Market Restraints
- Active Ingredient Import Dependence:Technical glyphosate and glufosinate-ammonium concentrate in Chinese supply corridors, exposing Vietnamese formulators to tariff volatility and shipping disruptions.
- Circular 21 Registration Timelines:MARD's extended field trial requirements and residue study protocols stretch product commercialization to 36-48 months, freezing pipeline investments.
- Weed Resistance Proliferation:Echinochloa crus-galli and Leptochloa chinensis populations across Red River Delta vegetable corridors exhibit reduced sensitivity to ALS-inhibiting chemistries, compressing effective product lifecycles.
Strategic Opportunities
- Central Highlands Coffee Expansion:Industrial plantation operators in Dak Lak and Lam Dong seek non-selective burn-down alternatives to manual weeding, opening volume contracts for systemic herbicides.
- Granule Formulation Uptake:Mechanized rice transplanting in Thai Binh and Nam Dinh provinces creates demand for controlled-release granules compatible with seedling establishment protocols.
- Positive List Pre-Positioning:Early registration of microbial bioherbicide candidates under MARD's evolving priority review track secures shelf space ahead of synthetic chemistry phase-outs.
Industry Challenges
- Residue Analytical Capacity:MEE's expanded monitoring requirements for export-bound rice and vegetables outstrip certified laboratory throughput in Hanoi and Ho Chi Minh City, delaying shipment clearances.
- Extension Service Fragmentation:Provincial agriculture departments lack trained personnel to diagnose resistance patterns and prescribe rotation strategies, leading to farmer over-application and accelerated chemistry failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Herbicide Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Herbicides, Non-Selective Herbicides, Pre-Emergent Herbicides, Post-Emergent Herbicides Application: Agricultural Crops, Horticulture, Turf & Ornamentals, Soil Treatment Formulation Type: Granules, Liquid Concentrates, Soluble Powders, Emulsifiable Concentrates Distribution Channel: Retail, E-Commerce, Distributors, Direct Sales |
| Companies Covered | Bayer CropScience AG, Syngenta Group, BASF SE, Corteva Agriscience, UPL Limited, FMC Corporation, Nufarm Limited, Adama Agricultural Solutions, Sumitomo Chemical Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Herbicide Market Trends and Innovations
Formulation chemistry and application methodology are converging to address resistance management and labor scarcity simultaneously, reshaping how Vietnamese farmers deploy weed control inputs across diverse cropping systems.
Mesotrione-based premix formulations are supplanting atrazine blends in maize and sugarcane systems across the Southeast region. Industrial plantation managers in Binh Phuoc and Tay Ninh provinces are transitioning acreage to these HPPD-inhibitor combinations at pace. This chemistry shift is compressing the effective market window for photosystem II inhibitors while elevating grower willingness to pay for resistance-delaying rotation tools.
MEE's 2023 amendment to QCVN 02:2009/BTNMT tightens maximum residue limits for glyphosate in aquatic ecosystems, directly impacting Mekong Delta paddy applications. Formulators must now submit expanded environmental fate data to maintain registrations. Rice-focused suppliers are responding by accelerating glufosinate-ammonium and pelargonic acid derivative pipelines to preserve aquatic safety certifications.
Cooperative procurement collectives in Hai Duong and Hung Yen provinces are aggregating smallholder demand to negotiate direct manufacturer contracts, bypassing traditional district-level agrochemical distributors. These buyer groups now specify formulation type, active ingredient concentration, and delivery timing in annual tenders. The model is most visible in protected vegetable corridors where export compliance requirements demand traceable input sourcing.
Vietnam Herbicide Market Segmentation
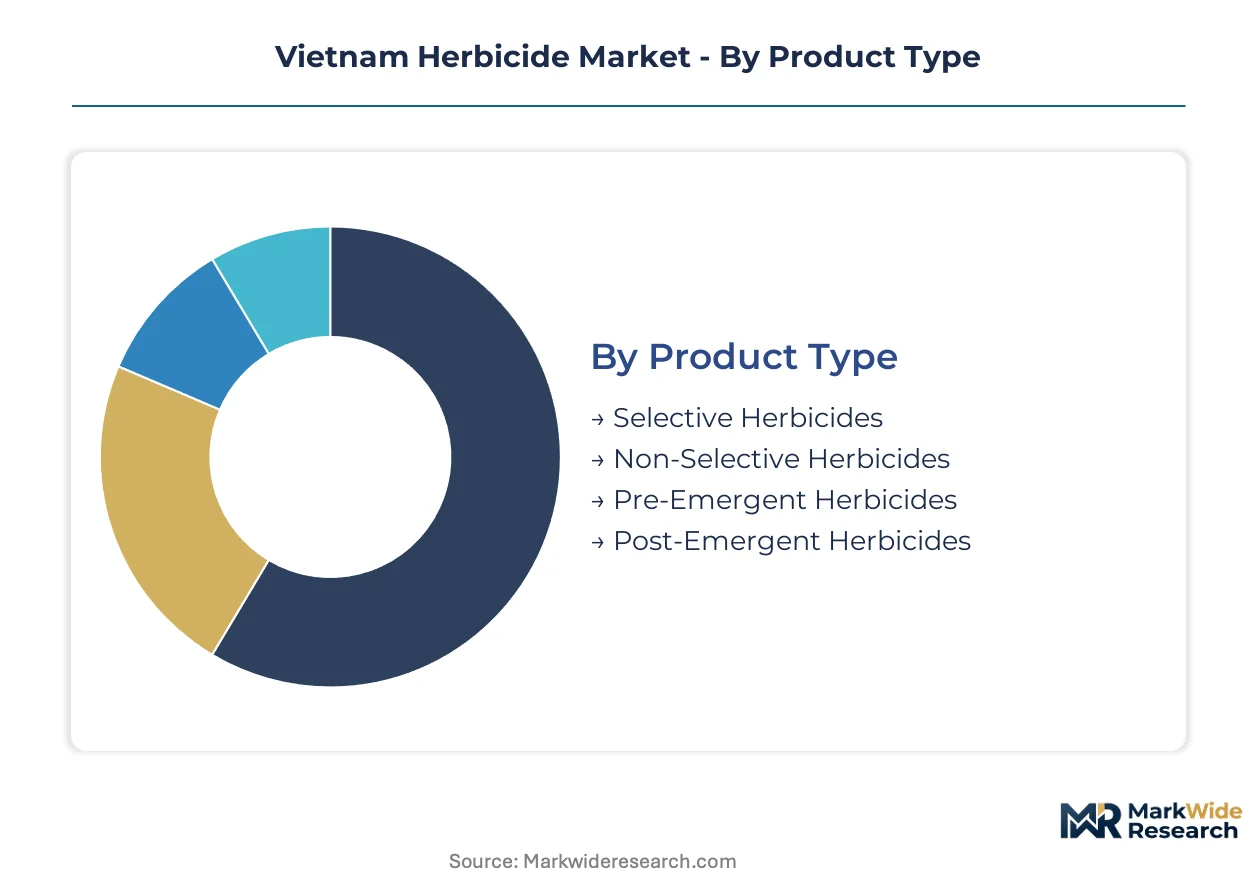
Segmentation in Vietnam's herbicide market reveals how regulatory pressure and cropping system diversity reshape commercial priorities across product categories. Understanding where substitution threats concentrate helps suppliers allocate reformulation investments and distribution resources effectively.
Product Type:
Non-selective herbicides face the steepest substitution pressure as MEE aquatic toxicity standards force rapid chemistry transitions in Mekong Delta rice systems.
- Selective Herbicides:These agents target specific weed species while preserving crop physiology through enzyme-specific inhibition pathways. Demand clusters in Red River Delta vegetable corridors where farmers combat resistant Echinochloa crus-galli without damaging transplanted seedlings. ALS-inhibiting chemistries dominate current use, though HPPD-inhibitor premixes gain ground as rotation alternatives.
- Non-Selective Herbicides:Broad-spectrum vegetation control agents function through contact or systemic action to eliminate all plant tissue. Central Highlands coffee plantations in Dak Lak and Lam Dong provinces drive volume for burn-down applications prior to replanting cycles. MEE glyphosate residue limits are accelerating glufosinate-ammonium adoption as growers seek aquatic-safe certifications.
- Pre-Emergent Herbicides:Soil-applied formulations create chemical barriers inhibiting weed seed germination before crop emergence. Mechanized rice transplanting zones in Thai Binh and Nam Dinh provinces favor these products for early-season weed suppression.
- Post-Emergent Herbicides:Foliar-active compounds target established weed flushes after crop establishment. Double-cropping intensification in An Giang and Dong Thap provinces expands demand for precision-timed applications against barnyard grass.
Non-selective herbicides anchor the volume base while selective herbicides gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity rice applications from premium horticulture segments requiring residue-compliant inputs for export certification.
- Agricultural Crops:Herbicide deployment across rice, maize, and sugarcane systems constitutes the dominant value pool. Mekong Delta double-cropping schedules and Central Highlands plantation expansion sustain post-emergent and non-selective volume.
- Horticulture:Protected vegetable cultivation in Hai Duong and Hung Yen provinces demands traceable input sourcing for EU and Japanese export compliance. Cooperative procurement collectives now specify formulation type and active ingredient concentration in annual manufacturer tenders.
- Turf & Ornamentals:Golf course and urban landscape maintenance applications favor selective chemistries with rapid degradation profiles. Ho Chi Minh City and Hanoi metropolitan green space expansion drives niche demand.
- Soil Treatment:Pre-plant incorporated herbicides address perennial weed pressure in perennial crop establishment. Coffee and pepper replanting cycles in Lam Dong create seasonal demand spikes.
Agricultural crops dominate absolute volume while horticulture commands the highest per-hectare input expenditure.
Formulation Type:
Application methodology constraints favor liquid delivery systems, though mechanization trends create openings for controlled-release alternatives.
- Liquid Concentrates:Backpack sprayer compatibility and farmer familiarity sustain dominance across smallholder operations. These formulations typically carry 10-50% active ingredient loadings with surfactant packages enhancing leaf penetration.
- Granules:Controlled-release matrices synchronize herbicide availability with seedling establishment protocols. Mechanized rice transplanting adoption in Thai Binh and Nam Dinh provinces accelerates uptake for labor-saving application.
- Soluble Powders:Dry formulations dissolve in water prior to spraying, offering storage stability and reduced shipping costs. District-level distributors favor these products for remote Mekong Delta communes with limited cold chain infrastructure.
- Emulsifiable Concentrates:Oil-in-water systems enhance lipophilic active ingredient penetration through waxy cuticles. Plantation operators in Binh Phuoc and Tay Ninh specify these formulations for mature tree crop applications.
Liquid concentrates retain the installed base while granules expand most quickly in mechanized transplanting zones.
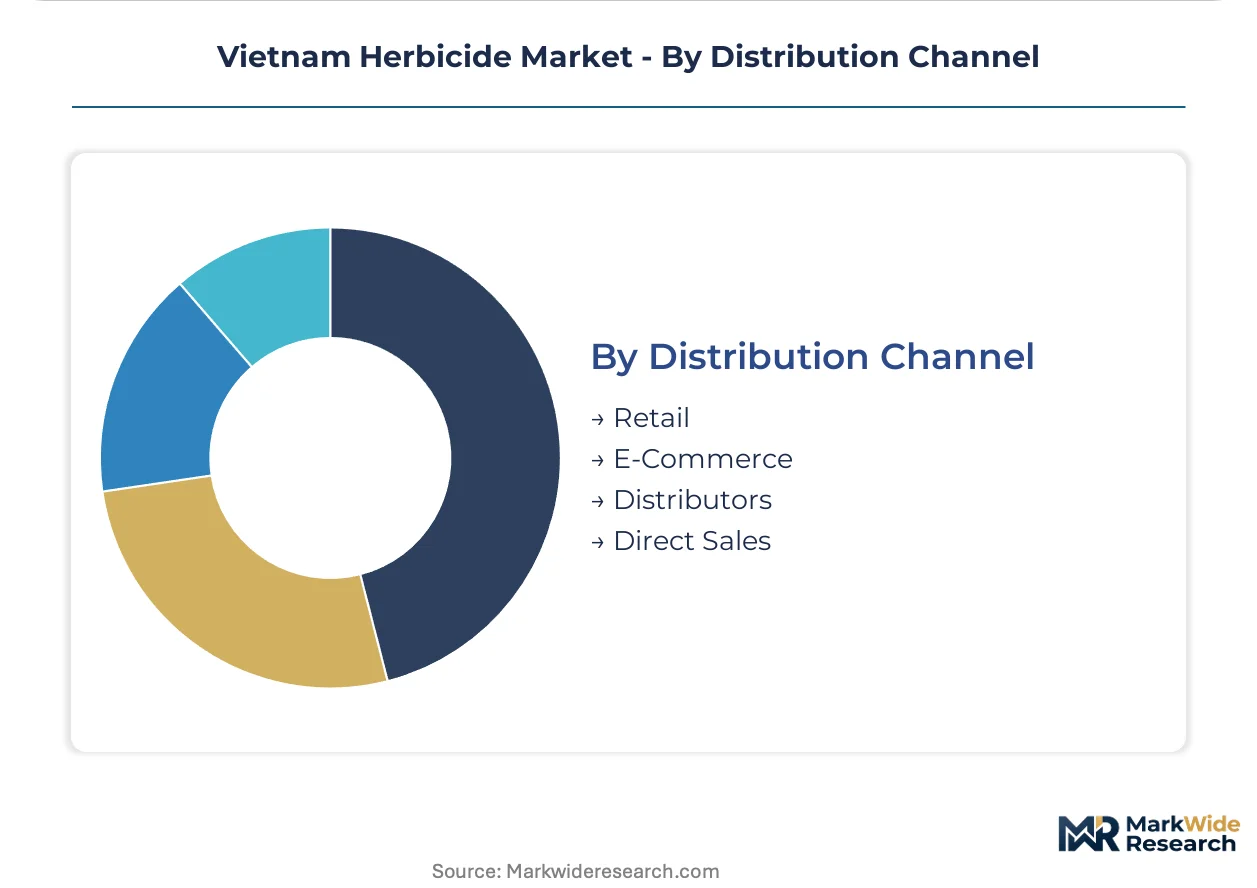
Distribution Channel:
Customer type fragmentation separates cooperative collectives seeking direct manufacturer relationships from traditional retail-dependent smallholders.
- Distributors:Provincial and district-level agrochemical traders maintain network coverage across remote rice-growing communes. These intermediaries provide credit terms and technical advice that smallholders depend on during planting seasons.
- Direct Sales:Cooperative procurement collectives in export-oriented vegetable corridors bypass traditional channels to negotiate volume contracts with formulators. Traceability requirements for EU-bound produce drive this disintermediation.
- Retail:Mom-and-pop agricultural supply shops serve immediate purchase needs in peri-urban farming zones. Ho Chi Minh City and Hanoi periphery stores stock fast-moving glyphosate and paraquat alternatives.
- E-Commerce:Digital platforms aggregate demand from younger farmers and commercial cooperatives seeking price transparency. Drone service providers increasingly bundle herbicide procurement with aerial application packages.
Distributors retain the broadest geographic footprint while direct sales channels climb the fastest among export-certified farming cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MARD's Circular 21 registration protocol and MEE's tightening glyphosate residue limits are redistributing commercial activity across Vietnam's agricultural zones. Provincial agriculture departments align local extension services with national environmental mandates.
Mekong Delta
Double-cropping rice intensification in An Giang and Dong Thap provinces sustains post-emergent herbicide volume against resistant barnyard grass flushes. MEE's 2023 amendment to QCVN 02:2009/BTNMT tightens aquatic ecosystem discharge thresholds, compelling formulators to submit expanded environmental fate data. Drone service providers in Can Tho aggregate smallholder demand for precision aerial spraying packages.
Red River Delta
Protected vegetable cultivation in Hai Duong and Hung Yen provinces commands the highest per-hectare herbicide expenditure for EU and Japanese export compliance. Cooperative procurement collectives negotiate direct manufacturer contracts specifying formulation type and active ingredient concentration. MARD's positive list revisions prioritize residue-compliant chemistries in these export corridors.
Central Highlands
Industrial coffee and pepper plantation expansion in Dak Lak and Lam Dong provinces drives non-selective burn-down volume prior to replanting cycles. MEE effluent mandates restrict paraquat applications, accelerating glufosinate-ammonium adoption among aquatic-certified growers. Mechanized weeding substitution creates seasonal demand spikes for systemic herbicides.
Southeast Region
Maize and sugarcane systems in Binh Phuoc and Tay Ninh provinces transition acreage to HPPD-inhibitor premixes, compressing the market window for photosystem II inhibitors. Circular 21's extended field trial requirements stretch product commercialization timelines, freezing pipeline investments for regional distributors. Industrial plantation managers specify emulsifiable concentrates for mature tree crop applications.
North Central Coast
Mechanized rice transplanting adoption in Thai Binh and Nam Dinh provinces expands demand for controlled-release granules compatible with seedling establishment protocols. Provincial agriculture departments lack trained personnel to diagnose resistance patterns, leading to farmer over-application. MARD's evolving bioherbicide priority review track attracts early registrants seeking shelf space ahead of synthetic chemistry phase-outs.
Vietnam Herbicide Market Competitive Landscape
Player mix skews toward integrated multinationals with captive technical manufacturing and specialized formulators serving cooperative procurement channels. Tiered concentration separates qualified registrants from informal traders operating outside Circular 21 protocols. Strategic archetypes include integrated agrochemical conglomerates with regional manufacturing bases, formulation specialists leveraging proprietary tropical-adapted chemistries, and bioherbicide developers positioning for MARD's priority review track. Dominant competitive moves encompass portfolio restructuring around MEE-compliant alternatives and direct contracting with export-certified farming cooperatives.
Within the integrated multinational tier, Bayer CropScience AG, Syngenta Group, and BASF SE exemplify archetypes visible in the competitive landscape. Bayer CropScience AG represents the vertically integrated model with technical manufacturing presence in the region. Syngenta Group occupies a position emphasizing proprietary formulation capabilities. BASF SE anchors the glufosinate-ammonium specialization vector against rising resistance concerns. These entities collectively illustrate how regulatory pressure bifurcates competitive positioning between compliant registrants and informal supply channels.
| Leading Market Players |
|---|
| Bayer CropScience AG |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| UPL Limited |
| FMC Corporation |
| Nufarm Limited |
| Adama Agricultural Solutions |
| Sumitomo Chemical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Thirty-six to forty-eight month registration timelines under MARD Circular 21 compress inventory turnover and amplify pricing power for qualified multinationals with pre-registered portfolios, while informal traders absorb residual demand at compressed margins. This lead-time band concentrates cost pass-through capability among integrated formulators with captive technical supply, fragmenting price realization across compliant and non-compliant supply channels.
Pricing Analysis
Certification level under MEE aquatic toxicity standards creates the primary spread between premium-registered and informal-channel products. Contract-based long-term offtake dominates procurement for Central Highlands plantation operators, while spot purchasing persists among Mekong Delta smallholders. Price differentiation hinges on Circular 21 compliance status and formulation sophistication, with drone-service bundling emerging as a secondary tier. Pricing pressure stems from Chinese technical concentrate tariff volatility, compressing margins for import-dependent formulators. Export-certified vegetable cooperatives in Hai Duong exhibit lowest price sensitivity; peri-urban rice smallholders in An Giang face acute cost pressure.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo and Shenzhen corridors elevates inbound logistics costs for technical glyphosate and glufosinate-ammonium shipments. Supply concentrates in Chinese manufacturing clusters for active ingredient synthesis, Vietnamese formulation facilities in Binh Duong and Dong Nai, and Thai technical packaging operations. Raw material dependencies span glyphosate technical, surfactant packages, and pelargonic acid derivatives. Single-source vulnerability runs through Chinese technical concentrate corridors, exposing formulators to shipping disruption cascades. Distribution runs through provincial agrochemical distributors with credit-extension capabilities, though cooperative collectives in export corridors accelerate direct-manufacturer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative procurement collectives in Hai Duong and Hung Yen provinces, fragmenting traditional distributor influence and forcing supply-side consolidation responses.
For Market Incumbents: Fortify registration portfolios by accelerating bioherbicide submissions under MARD's priority review track, preempting synthetic chemistry phase-outs. Deepen backward integration into technical manufacturing through regional joint ventures, reducing exposure to Chinese tariff volatility. Secure exclusive supply contracts with drone service providers in Can Tho to lock in application-channel access against emerging competitors.
For New Entrants and Emerging Players: Differentiate on microbial bioherbicide formulations tailored to tropical weed spectrums, targeting MARD's evolving positive list revisions. Penetrate the Central Highlands coffee replanting segment, where non-selective burn-down demand outstrips qualified supplier capacity. Pursue cooperative direct-contracting models in Red River Delta vegetable corridors, leveraging traceability requirements as entry wedge.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational parents seeking to divest non-core tropical-formulation assets amid portfolio restructuring pressures. Long-term viability centers on regulatory compliance infrastructure rather than volume scale, favoring targets with established MEE certification pathways. Monitor MARD positive list revision timing as inflection signal for bioherbicide valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| MEE Compliance Certification | Aquatic toxicity testing investments preserve market access in Mekong Delta rice systems. |
| Backward Integration into Technical Manufacturing | Captive glyphosate synthesis reduces tariff exposure and secures cost-advantaged supply. |
| Drone Service Provider Partnership | Aerial application bundling penetrates smallholder cooperatives in mechanized transplanting zones. |
| Bioherbicide Pipeline Prioritization | Microbial candidate registration secures shelf space ahead of synthetic chemistry phase-outs. |
| Cooperative Direct Contracting | Traceable input sourcing meets EU export compliance demands in Red River Delta vegetable corridors. |
Research Methodology
A spread of perspectives from MARD registration officials, provincial agriculture extension directors, cooperative procurement managers, and technical directors at formulation facilities converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with downstream channel audits across Mekong Delta distributor networks. Secondary validation drew from MARD Circular 21 filings, MEE effluent discharge records, customs import data for technical concentrates, and Circular 21 registration databases. Bottom-up volume estimates from provincial herbicide consumption surveys triangulated against top-down value projections from manufacturer revenue disclosures.
Segmentation dimensions modeled span product type, application crop, formulation technology, and distribution channel across the projection horizon. Analytical framework development incorporated mechanized transplanting adoption rates, drone penetration curves in rice systems, and MEE regulatory amendment implementation timelines. CAGRs were derived from regression analysis against historical consumption patterns and forward scenario weighting. Forecast inputs included resistance pattern proliferation rates in Red River Delta vegetable corridors and cooperative procurement collective formation velocity.
Decision-makers should treat outputs as directional under assumptions of sustained MEE enforcement intensity and stable China-Vietnam trade corridors; material deviation would warrant model refresh. Specific risk factors encompass abrupt Circular 21 registration suspension, technical concentrate supply disruption, and accelerated bioherbicide substitution curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Acaricides Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Global Insecticides Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Isoxaflutole Market
Crop Protection
Canada Nematicides Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
South America Insecticide Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
North America Molluscicides Market