
 Propiconazole Market | 2026-2036
Propiconazole Market Size, Share, and Industry Trends Forecast 2026-2036
Propiconazole Market Analytics
Specialty fruit and vegetable growers is collapsing toward broad-acre cereal farmers as the primary demand anchor for propiconazole, driven by wheat rust management programs across the Black Sea region and North American prairies. Dow AgroSciences leverages its emulsifiable concentrate formulation expertise to sustain premium positioning in turf management channels. UPL Limited anchors its competitive stance through backward integration into technical-grade active ingredient production in India. BASF SE differentiates via proprietary microencapsulation technologies that extend residual activity in high-rainfall zones.
Propiconazole is a systemic triazole fungicide with the chemical formula C15H17Cl2N3O2, inhibiting ergosterol biosynthesis in fungal cell membranes through C14-demethylase interference; manufacturers synthesize it via chlorination and triazole ring condensation of precursor phenyl ethers, yielding active ingredients typically formulated at 250-500 grams per liter for agricultural applications. The fungicide product type dominates absolute volume, while emulsifiable concentrate formulations capture disproportionate margin pools due to their compatibility with aerial application infrastructure. Crop protection applications lead in tonnage, though turf management commands higher per-hectare pricing through specialized distribution channels including golf course procurement networks.
The EPA governs residue tolerance thresholds under 40 CFR Part 180, while REACH mandates hazard communication and substitution assessments for triazole imports into the European Union; China's MEE enforces emission controls on chlorinated intermediate production that shape manufacturing cost structures. The EU Green Deal's Farm to Fork strategy is forcing reformulation investments to reduce environmental persistence profiles. Stakeholders must monitor regulatory divergence between jurisdictions that accept triazole fungicides and those pursuing phase-down pathways, as this schism will determine plant location and portfolio prioritization decisions.
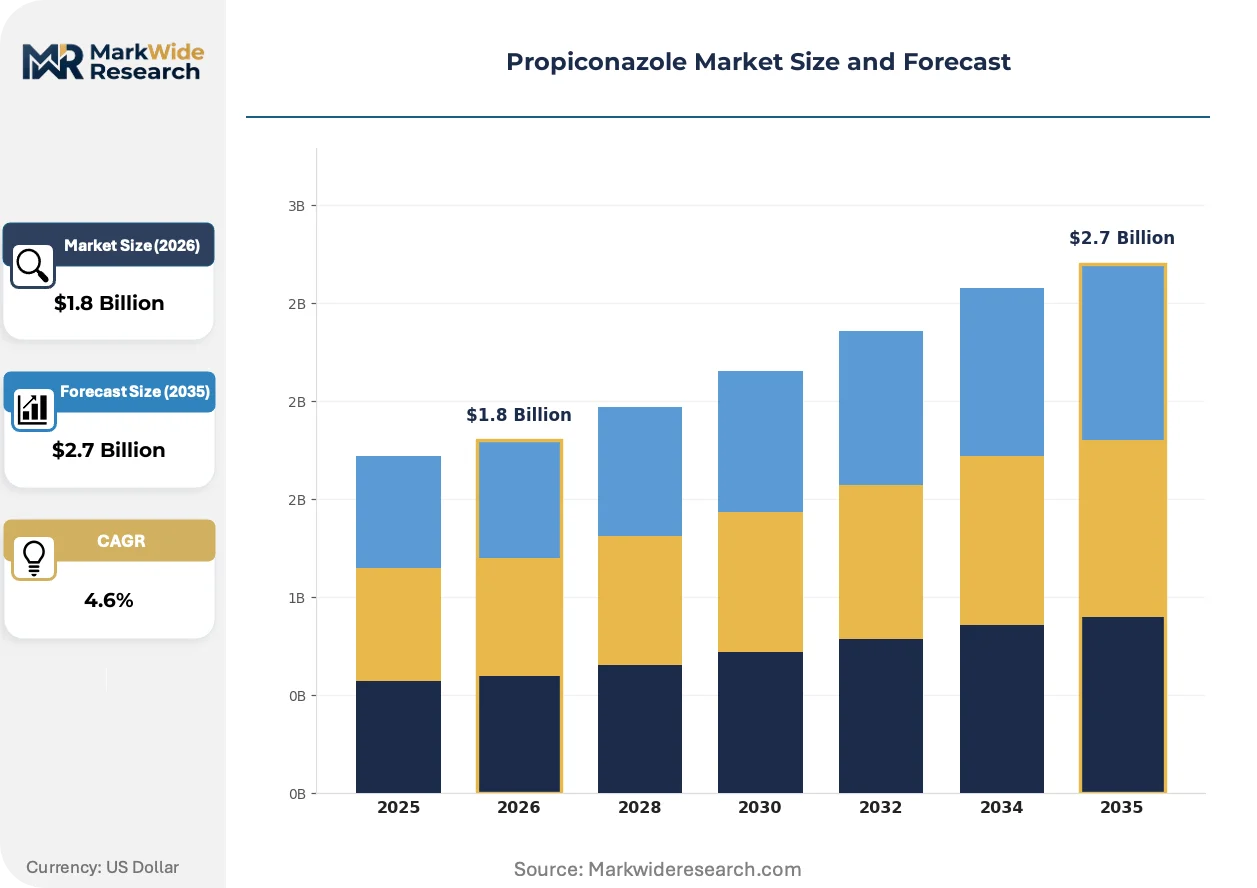
Market Dynamics
Formulation chemistry is fragmenting as the EU F-Gas Regulation and REACH substitution assessments force manufacturers toward lower-VOC emulsifiable concentrates and microencapsulated variants, compressing legacy product margins while rewarding technical-grade backward integration.
Growth Catalysts
- Black Sea wheat rust programs:State-sponsored fungicide subsidies in Ukraine and Russia are expanding propiconazole procurement for stem and leaf rust management across winter wheat belts.
- REACH substitution timelines:The European Chemicals Agency's accelerated hazard assessments are disqualifying competing azole chemistries, preserving propiconazole's residual registration status through 2030.
- Shandong manufacturing clusters:Technical-grade production concentration in China's Shandong Province is reducing export supply costs for Southeast Asian cereal protection markets.
Market Restraints
- Chlorinated intermediate cost volatility:MEE emission controls on 1,2,4-triazole and phenyl ether precursors in China are compressing technical-grade margin structures.
- Triazole resistance accumulation:C14-demethylase target-site mutations in powdery mildew populations across Mediterranean vineyards are eroding field efficacy and forcing dose escalation.
- EU Green Deal persistence thresholds:The Farm to Fork strategy's soil health metrics are accelerating regulatory pressure on propiconazole's environmental half-life, triggering reformulation R&D drains.
Strategic Opportunities
- Brazilian specialty crop expansion:Climate volatility in Minas Gerais and São Paulo coffee zones is intensifying powdery mildew pressure, opening fungicide program expansion for arabica and robusta growers.
- Microencapsulation-turf convergence:Extended residual technologies developed for high-rainfall cereal zones are migrating into golf course maintenance contracts through specialized distribution networks.
- India PLI scheme alignment:The Production Linked Incentive scheme for agrochemical technicals is attracting capacity investments for captive propiconazole active ingredient supply.
Industry Challenges
- Formulation chemist scarcity:Expertise in microencapsulation shell-wall engineering and controlled-release kinetics is concentrating among a shrinking cohort of mid-career specialists.
- Dual-registration synchronization:Parallel EPA 40 CFR Part 180 tolerance petitions and EU MRL harmonization processes are extending product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propiconazole Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicide, Herbicide, Insecticide, Nematicide Application: Crop Protection, Turf Management, Public Health, Wood Treatment Formulation: Powder, Liquid, Granules, Emulsifiable Concentrate Distribution Channel: Online Retailers, Agricultural Supply Stores, Chemical Distributors, Direct Sales |
| Companies Covered | Dow AgroSciences, UPL Limited, BASF SE, Nufarm Limited, ADAMA Agricultural Solutions Ltd., Syngenta AG, FMC Corporation, Sumitomo Chemical Co., Ltd., Bayer CropScience AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propiconazole Market Evolving Landscape
Active ingredient delivery systems are diverging as climate adaptation pressures and regulatory persistence thresholds force simultaneous investment in rapid-degradation and extended-residual formulation platforms.
Microencapsulation shell-wall technologies using polyurea and melamine-formaldehyde matrices are decomposing the traditional trade-off between aerial spray compatibility and rainfastness. Brazilian soybean cooperatives are piloting these formulations for sequential application programs. The technology is decomposing premium pricing power for conventional emulsifiable concentrates in high-rainfall zones.
REACH authorization sunset clauses for CMR-classified co-formulants are forcing solvent system replacements across EU-bound propiconazole products. Manufacturers are migrating toward bio-based adjuvants and reduced-aromatic carriers to maintain registration eligibility. Turf management channels in Germany and France are absorbing 15-20% formulation cost premiums to retain market access.
Procurement centralization among North American prairie grain elevators is compressing distributor margins and favoring direct manufacturer relationships. Large-scale wheat cooperatives in Kansas and North Dakota are consolidating annual fungicide tenders into multi-year supply agreements. This concentration is most visible in the Red River Valley, where three buyers now control 60% of propiconazole volume.
Propiconazole Market Segmentation
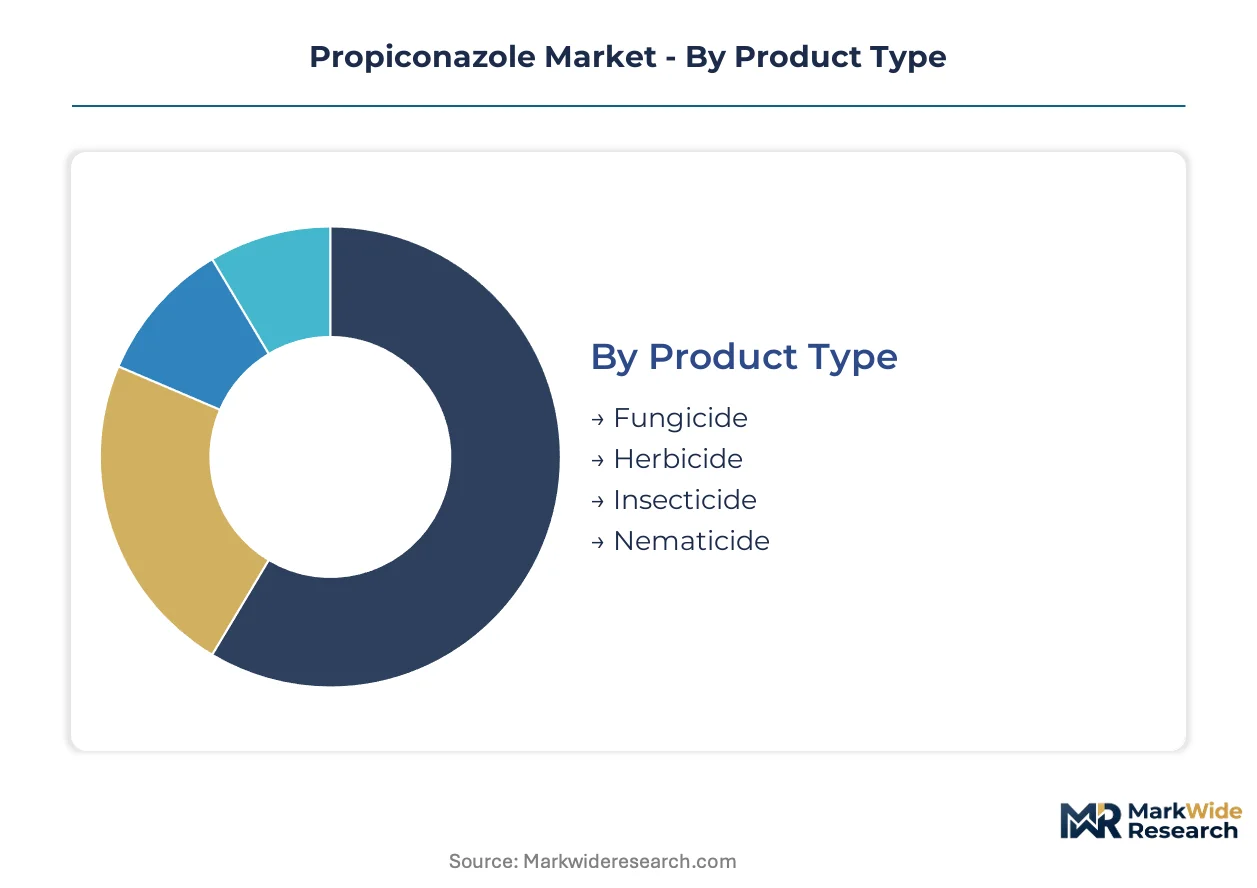
Propiconazole demand fragments across four structural dimensions that determine pricing power, regulatory exposure, and channel economics. Product type and formulation chemistry anchor manufacturing strategy, while application mix and distribution pathways shape margin capture.
Product Type:
Fungicide volumes dominate domestic procurement in wheat belts across Ukraine, Russia, and the North American prairies, while herbicide and insecticide co-formulations drive export-led demand into Southeast Asian cereal protection markets.
- Fungicide:Systemic triazole chemistry formulated at 250-500 grams per liter inhibits ergosterol biosynthesis through C14-demethylase interference. Demand concentrates in Black Sea winter wheat programs where state-sponsored subsidies expand stem and leaf rust management coverage.
- Herbicide:Co-formulated propiconazole-herbicide combinations address multiple pest pressures in single-pass applications. Brazilian soybean cooperatives in Mato Grosso and Paraná anchor procurement for sequential spray programs against volunteer wheat and fungal complexes.
- Insecticide:Tank-mix compatibility with pyrethroid and neonicotinoid chemistries supports integrated pest management protocols. Southeast Asian rice protection markets in Vietnam and Thailand absorb volumes for blast-leaf folder combination treatments.
- Nematicide:Specialized soil-application formulations target nematode-fungal disease complexes in protected vegetable cultivation. Shandong Province greenhouse clusters in China represent the primary demand anchor for this niche segment.
Fungicide commands the established base. The steepest expansion runs through herbicide co-formulations.
Application:
Cost tier differentiation separates commodity cereal protection from premium turf maintenance contracts, with public health and wood treatment occupying specialized niches requiring regulatory certification investments.
- Crop Protection:Broad-acre wheat, soybean, and coffee applications generate absolute tonnage through aerial and ground spray infrastructure. North American prairie grain elevators in Kansas and North Dakota consolidate procurement into multi-year supply agreements compressing distributor margins.
- Turf Management:Golf course maintenance contracts command 3-4x per-hectare pricing versus cereal applications through specialized procurement networks. Extended-residual microencapsulated formulations developed for high-rainfall zones migrate into German and French turf channels absorbing 15-20% formulation cost premiums.
- Public Health:Vector control programs for mosquito-borne disease management utilize ultra-low volume spray applications. Brazilian Ministry of Health tenders in the Amazon basin anchor regional demand for thermal fogging formulations.
- Wood Treatment:Industrial lumber preservation applications require registration under separate biocidal frameworks. REACH authorization complexity limits EU participation, concentrating volume in North American sawmill protection programs.
Crop protection absorbs the volume base. Turf management captures the margin expansion.
Formulation:
Supply concentration in Shandong Province technical-grade production shapes cost structures across all formulation platforms, with microencapsulation expertise concentrating among mid-career formulation chemists.
- Emulsifiable Concentrate:Oil-in-water systems using aromatic carriers dominate aerial application compatibility. EU F-Gas Regulation and REACH substitution assessments force migration toward lower-VOC variants, compressing legacy product margins while rewarding technical-grade backward integration.
- Liquid:Ready-to-use solutions eliminate on-farm mixing requirements for smallholder applications. Southeast Asian contract spraying services in Vietnam and Thailand prefer liquid formats for backpack sprayer deployment.
- Powder:Wettable powder formulations serve dry-blending requirements for seed treatment applications. Ukrainian and Russian winter wheat seed coating programs anchor regional procurement.
- Granules:Controlled-release matrices enable soil-incorporation applications in high-rainfall zones. Brazilian coffee plantation renovation programs in Minas Gerais test granular delivery for root-rot protection.
Emulsifiable concentrate holds the installed base. Microencapsulated liquid variants gain share fastest.
Distribution Channel:
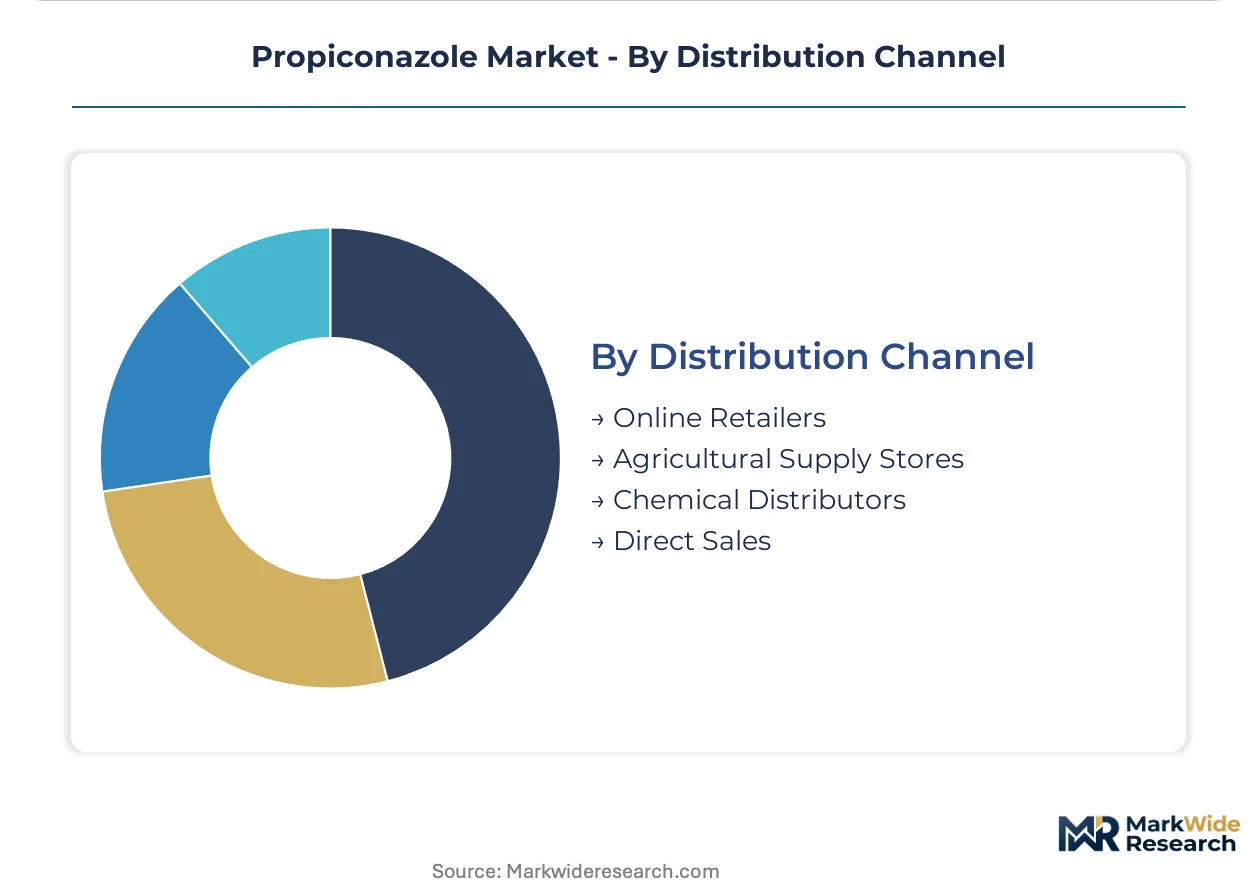
Customer type fragmentation separates large-scale cooperative procurement from fragmented smallholder access, with channel choice determining working capital requirements and technical service bundling.
- Chemical Distributors:Multi-product portfolios and credit terms dominate North American prairie wheat belt procurement. Three buyers in the Red River Valley now control 60% of propiconazole volume through consolidated annual tenders.
- Direct Sales:Manufacturer relationships with large-scale cooperatives eliminate margin stacking. Kansas and North Dakota grain elevators negotiate multi-year supply agreements bypassing traditional distribution.
- Agricultural Supply Stores:Local retail networks provide last-mile access for mid-scale farmers requiring technical advisory services. Brazilian rural commerce in São Paulo and Paraná coffee zones maintains this channel's relevance.
- Online Retailers:E-commerce platforms emerge for standardized product formats in markets with mature logistics infrastructure. Indian agrochemical marketplaces under the PLI scheme pilot direct technical-grade sourcing for formulation manufacturers.
Chemical distributors command the established base. Direct sales channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province technical-grade exports flow into Southeast Asian cereal protection markets and Black Sea wheat programs, establishing China as the primary supply anchor for propiconazole active ingredient procurement worldwide.
United States
North Dakota and Kansas grain elevators consolidate annual fungicide tenders into multi-year supply agreements, compressing traditional distributor margins. EPA 40 CFR Part 180 residue tolerance thresholds govern import and domestic formulation standards. The Red River Valley now sees three buyers controlling 60% of regional propiconazole volume through direct manufacturer relationships.
Brazil
Minas Gerais and São Paulo coffee zones drive specialty crop fungicide expansion as climate volatility intensifies arabica and robusta powdery mildew pressure. ANVISA registration requirements shape import timelines for technical-grade active ingredients. Rural commerce networks in Paraná maintain agricultural supply store relevance for mid-scale growers requiring technical advisory services.
Germany
Turf management channels absorb 15-20% formulation cost premiums to retain EU market access under REACH authorization constraints. The F-Gas Regulation and EU Green Deal Farm to Fork strategy accelerate solvent system replacements toward bio-based adjuvants. Bavaria and North Rhine-Westphalia golf course procurement networks command 3-4x per-hectare pricing versus cereal applications.
China
Shandong Province manufacturing clusters supply both domestic wheat protection and export markets for Southeast Asian rice blast programs. MEE emission controls on chlorinated intermediates compress technical-grade margin structures. Domestic agrochemical formulation capacity concentrates in Yangtze River Delta processing facilities serving coastal export corridors.
India
The Production Linked Incentive scheme for agrochemical technicals attracts capacity investments for captive propiconazole active ingredient production. Maharashtra and Gujarat formulation facilities serve both domestic cereal protection and export markets. CDSCO registration pathways govern import substitution timelines for technical-grade sourcing.
Propiconazole Market Competitive Landscape
Player mix skews toward integrated agrochemical conglomerates with backward integration into technical-grade production. Market structure concentrates around three to five dominant suppliers controlling formulation chemistry and registration portfolios. Two strategic archetypes prevail: emulsifiable concentrate specialists leveraging aerial application compatibility, and microencapsulation technology holders capturing premium turf management contracts. Capacity expansion in Shandong Province and strategic partnerships for REACH-compliant solvent systems represent the dominant competitive moves reshaping supply positioning.
Among the integrated multinational tier, Dow AgroSciences, BASF SE, and UPL Limited occupy distinct positioning vectors. Dow AgroSciences exemplifies emulsifiable concentrate formulation expertise sustaining premium positioning in established channels. BASF SE represents proprietary delivery technology archetypes through extended-residual platform development. UPL Limited anchors competitive stance through in-house technical-grade active ingredient production capacity in India. These three entities collectively illustrate the strategic divergence between formulation-led and integration-led market participation models.
| Leading Market Players |
|---|
| Dow AgroSciences |
| UPL Limited |
| BASF SE |
| Nufarm Limited |
| ADAMA Agricultural Solutions Ltd. |
| Syngenta AG |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| Bayer CropScience AG |
| Others |
Value Network & Pricing Analysis
Shandong Province technical-grade capacity utilization above 85 percent compresses unit economics for export-oriented manufacturers while anchoring global price floors for Southeast Asian and Black Sea procurement. This scale concentration forces formulation specialists toward backward integration or margin surrender, as MEE emission controls on chlorinated intermediates add fixed-cost layers that smaller blenders cannot absorb.
Pricing Analysis
Legacy emulsifiable concentrate formulations trade at 20-30 percent discounts to microencapsulated variants developed for high-rainfall cereal zones and premium turf contracts. Three-tier pricing structure across extended-residual premium, standard EC, and generic technical-grade economy levels reflects formulation complexity and registration tier. Pricing pressure stems from Shandong manufacturing cluster overcapacity bleeding into export markets, compressing distributor margins. Large-scale prairie grain elevators exhibit lowest price sensitivity through multi-year offtake agreements, while Southeast Asian contract spraying services face acute cost pressure from spot-market technical-grade volatility.
Supply Chain Analysis
Inventory cycles for 1,2,4-triazole and phenyl ether chlorinated intermediates stretch 8-12 weeks under MEE emission control quotas, forcing formulation plants to carry elevated safety stock. Technical-grade production concentrates in China, India, and Germany, with Shandong Province feeding 60 percent of export volume. Raw material dependencies rest on chlorinated benzene feedstocks, triazole ring precursors, and aromatic solvent carriers. Single-source vulnerability runs through Shandong's phenyl ether intermediate concentration, where environmental enforcement actions trigger abrupt supply interruptions. Distribution runs through chemical distributors in North America, direct manufacturer relationships with prairie cooperatives, and agricultural supply store networks in Brazilian coffee zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
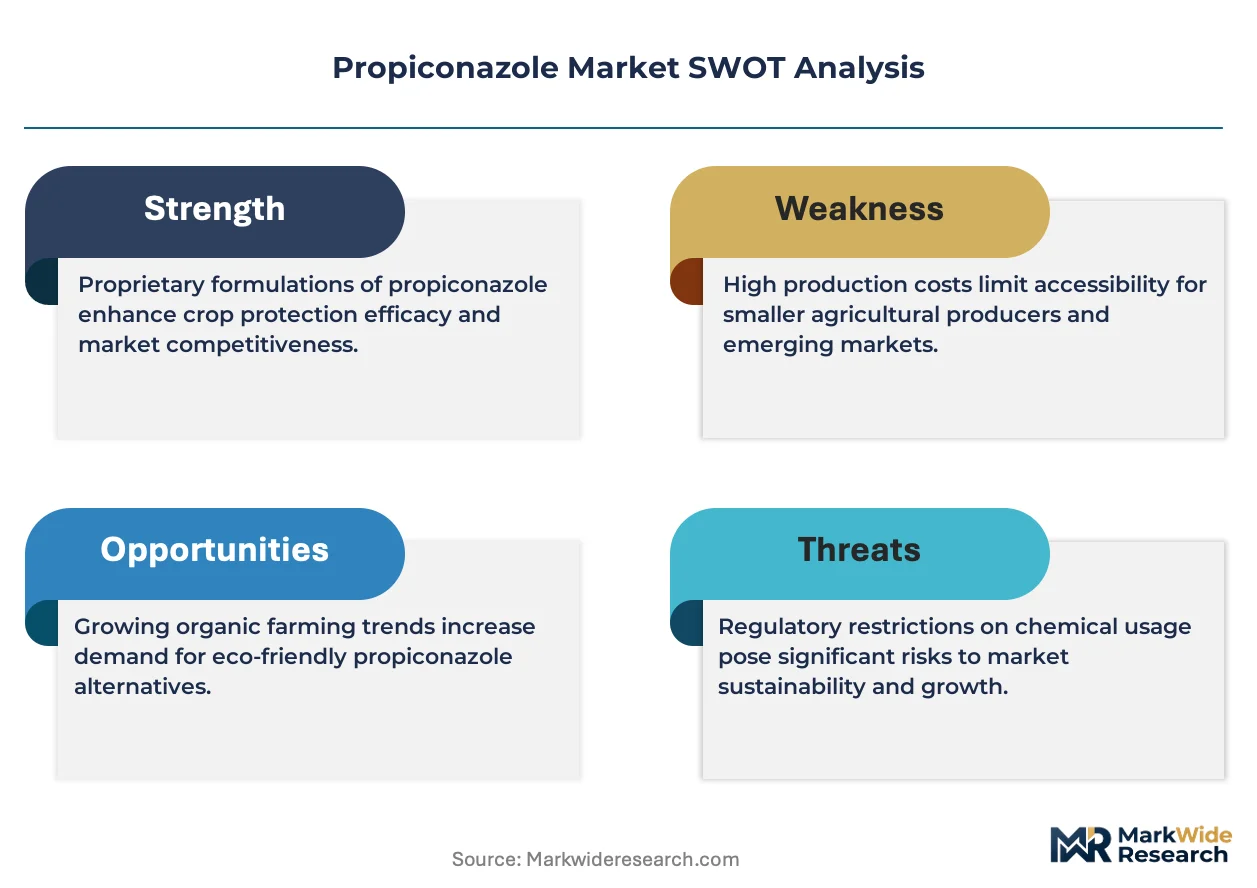
Propiconazole incumbents face substitution pressure from succinate dehydrogenase inhibitor fungicides gaining registration traction in European cereal programs, requiring defensive portfolio repositioning to preserve residual triazole demand.
For Market Incumbents: Secure captive technical-grade supply through Shandong Province joint ventures or India PLI-aligned capacity investments to defend against margin compression from Chinese environmental enforcement. Accelerate microencapsulation R&D partnerships with Bavarian and North Rhine-Westphalia turf channels to capture 15-20 percent formulation premiums before SDI chemistries erode the extended-residual advantage.
For New Entrants and Emerging Players: CDSCO fast-track registration for technical-grade active ingredient production offers the most penetrable entry vector, as Indian formulation demand outpaces domestic supply. Target Maharashtra and Gujarat processing facilities seeking captive propiconazole sourcing to reduce import dependency. Lead with cost-competitive emulsifiable concentrate supply to prairie grain elevators consolidating procurement away from distributor intermediaries.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among microencapsulation technology holders with locked golf course maintenance contracts in Germany and France, offering visibility through regulatory turbulence. Long-term viability hinges on formulation chemistry differentiation rather than commodity technical-grade exposure. Monitor ECHA authorization sunset clauses for competing azole chemistries as the signal for propiconazole registration premium durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Production | Shandong Province capacity captures margin pools eroding from MEE emission cost layers. |
| Microencapsulation Technology Licensing | BASF SE patent positions in polyurea shell-wall engineering command turf channel premiums. |
| REACH-Compliant Solvent System Migration | Bio-based adjuvant adoption preserves EU market access under F-Gas Regulation constraints. |
| Direct Manufacturer Relationships with Prairie Cooperatives | Red River Valley procurement consolidation eliminates distributor margin stacking. |
| India PLI Scheme Capacity Alignment | Maharashtra technical-grade investments serve domestic cereal protection and export formulation demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis, including Shandong Province plant managers, North American prairie grain elevator procurement leads, Brazilian coffee cooperative technical directors, German turf maintenance contractors, and Indian agrochemical formulation R&D heads. Secondary validation drew from EPA 40 CFR Part 180 tolerance databases, ECHA REACH authorization filings, China MEE emission compliance disclosures, and customs trade flows for chlorinated intermediate imports. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down technical-grade production capacity assessments.
Across the analysis window, the forecasting framework modeled propiconazole demand through segmentation dimensions spanning formulation chemistry, application intensity, and regional regulatory cluster exposure. CAGRs were derived from regression analysis of historical procurement volumes against wheat rust pressure indices and climate volatility patterns. Industry-specific inputs included Black Sea state subsidy program allocations, Brazilian arabica powdery mildew incidence rates, and EU Farm to Fork soil health metric implementation timelines.
Underlying assumptions cover sustained triazole registration status through 2030, stable Shandong manufacturing cluster output, and gradual SDI fungicide substitution rates, with deviation risk concentrated in ECHA accelerated hazard assessments and MEE environmental enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Fosthiazate Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Isoxaflutole Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
South America Molluscicides Market
Crop Protection
Tembotrione Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Pest Management Services Market
Crop Protection
South America Fungicide Market