
 Latin America AI in Insurance Market | 2026-2036
Latin America AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America AI in Insurance Market Analytics
Claims processing revenue is tilting toward algorithmic triage and automated settlement workflows across Latin American insurers. MAPFRE leverages proprietary risk-scoring engines to sustain pricing precision in catastrophe-prone markets. Bradesco anchors its competitive position through deep integration of predictive models across auto and health portfolios. Nubank competes by embedding AI-native underwriting directly into its digital banking interface, bypassing traditional broker channels entirely.
Artificial intelligence in insurance denotes the application of machine learning algorithms, natural language processing systems, and predictive statistical models to automate underwriting decisions, detect anomalous claims patterns, and personalize policy pricing at individual risk granularity. The technology stack serves primarily to compress loss ratios and accelerate policy lifecycle throughput from quote to claim resolution. Machine learning and predictive analytics together constitute the dominant technology pairing, with natural language processing gaining traction in customer service automation as Portuguese and Spanish conversational interfaces mature. Cloud-based deployment leads among mid-market insurers seeking elastic compute for seasonal premium cycles, while on-premises infrastructure persists among carriers with strict data residency requirements under national privacy statutes.
Brazil's LGPD and Mexico's data protection framework impose strict governance requirements on algorithmic decision-making in insurance, compelling carriers to invest in explainable AI architectures and audit-ready model documentation. Open banking regulations across Colombia, Brazil, and Mexico are reshaping data access patterns, enabling insurers to integrate real-time financial behavior signals into risk assessment pipelines. Stakeholders must monitor how forthcoming central bank digital currency pilots and biometric authentication standards alter fraud detection investment priorities and customer verification cost structures.
Market Dynamics
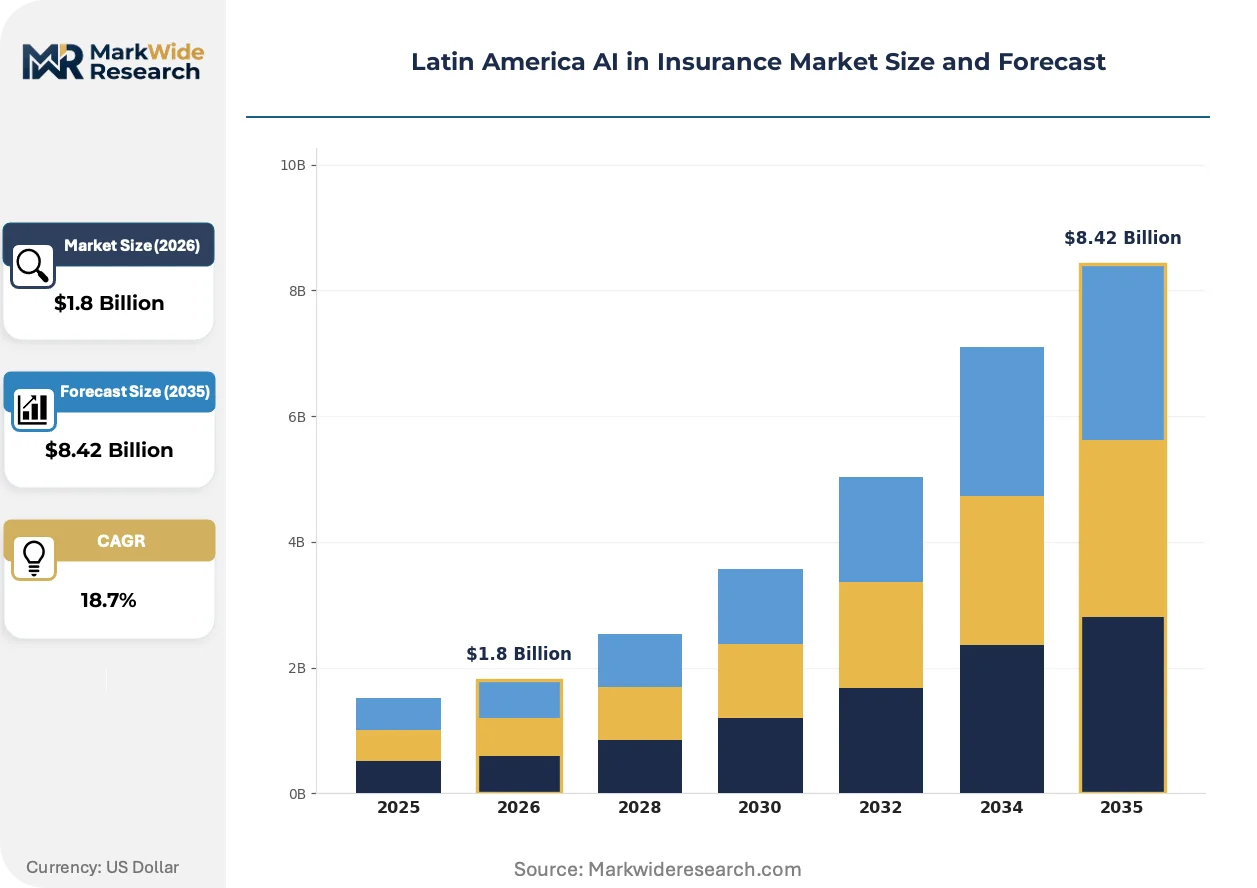
Brazil's LGPD enforcement and Mexico's open banking mandates are compressing legacy underwriting timelines while forcing carriers to rebuild data infrastructure around explainable AI architectures and real-time financial signal integration.
Growth Catalysts
- Open banking APIs:Brazil's Central Bank mandates enable insurers to ingest real-time transaction flows for dynamic risk scoring, collapsing traditional static credit assessments.
- Catastrophe modeling demand:P&C carriers across Mexico and Colombia deploy machine learning to price climate volatility, accelerating parametric policy development for agricultural and coastal exposures.
- Cloud infrastructure elasticity:Mid-market insurers leverage AWS and Azure regions in São Paulo and Querétaro to scale compute during seasonal premium surges without on-premises capex.
Market Restraints
- Data residency compliance:Brazil's LGPD and Mexico's data protection laws impose strict local storage requirements, fragmenting cloud architectures and inflating infrastructure costs for multinational carriers.
- Portuguese-Spanish NLP gap:Conversational AI models trained on English corpora underperform in regional dialects, forcing insurers to fund expensive proprietary language model development.
- Actuarial talent scarcity:The intersection of traditional underwriting expertise and machine learning engineering remains underdeveloped across São Paulo and Mexico City labor markets.
Strategic Opportunities
- Colombian market entry:Regulatory sandbox frameworks for InsurTechs create first-mover advantages for AI-native carriers targeting Bogotá's underpenetrated middle-class segments.
- Embedded insurance distribution:Partnerships with neobanks and e-commerce platforms enable zero-click policy origination at transaction points, bypassing legacy broker networks entirely.
- Biometric fraud prevention:Central bank digital currency pilots across Brazil and Mexico will mandate enhanced identity verification, creating demand for voice and facial recognition integration.
Industry Challenges
- Model explainability documentation:LGPD's algorithmic accountability requirements demand audit-ready decision trails that most legacy policy administration systems cannot generate without expensive retrofitting.
- Core system integration friction:Predictive models face API incompatibility with 1990s-era mainframe policy engines still dominant at established Brazilian carriers.
- Cross-border data harmonization:Divergent national privacy interpretations between Brazil, Mexico, and Colombia complicate regional product standardization and shared service center strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America AI in Insurance Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Chatbots, Predictive Analytics End User: Insurance Companies, Brokers, Third-Party Administrators, Reinsurers Application: Fraud Detection, Risk Assessment, Claims Management, Customer Service Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | MAPFRE, Bradesco, Talanx, Zurich, Ebix Latin America, IBM, Microsoft, Nubank, BBVA Mexico, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America AI in Insurance Market Evolving Landscape
Algorithmic underwriting is collapsing traditional risk assessment timelines while conversational interfaces and real-time data pipelines reshape how carriers acquire and retain policyholders across the region.
Transformer-based natural language processing is collapsing the cost structure of customer service operations across Latin American insurers. Bradesco and BB Seguridade deploy Portuguese-fluent chatbots to handle first-line claims intake and policy inquiries, compressing average resolution times from hours to minutes. The technology is collapsing agent headcount requirements in São Paulo's call center corridors while elevating human staff to exception-handling roles.
Brazil's Central Bank open banking regulations and Mexico's Fintech Law are mandating standardized API access to customer financial data, enabling insurers to build dynamic risk profiles from transaction histories rather than static credit scores. Carriers must now reconstruct underwriting engines to ingest real-time cash flow signals from neobank partners. The regulatory pressure is concentrating most intensely on auto and micro-insurance products where traditional actuarial tables underprice behavioral risk.
Policyholder acquisition through embedded distribution is displacing traditional broker channels across Brazil's digital banking ecosystem. Nubank and Inter embed micro-insurance offerings directly into mobile banking interfaces, capturing customers at moments of financial transaction rather than through dedicated insurance shopping journeys. This behavioral shift is most visible in São Paulo's metropolitan zone where smartphone penetration and digital wallet usage exceed national averages.
Latin America AI in Insurance Market Segmentation
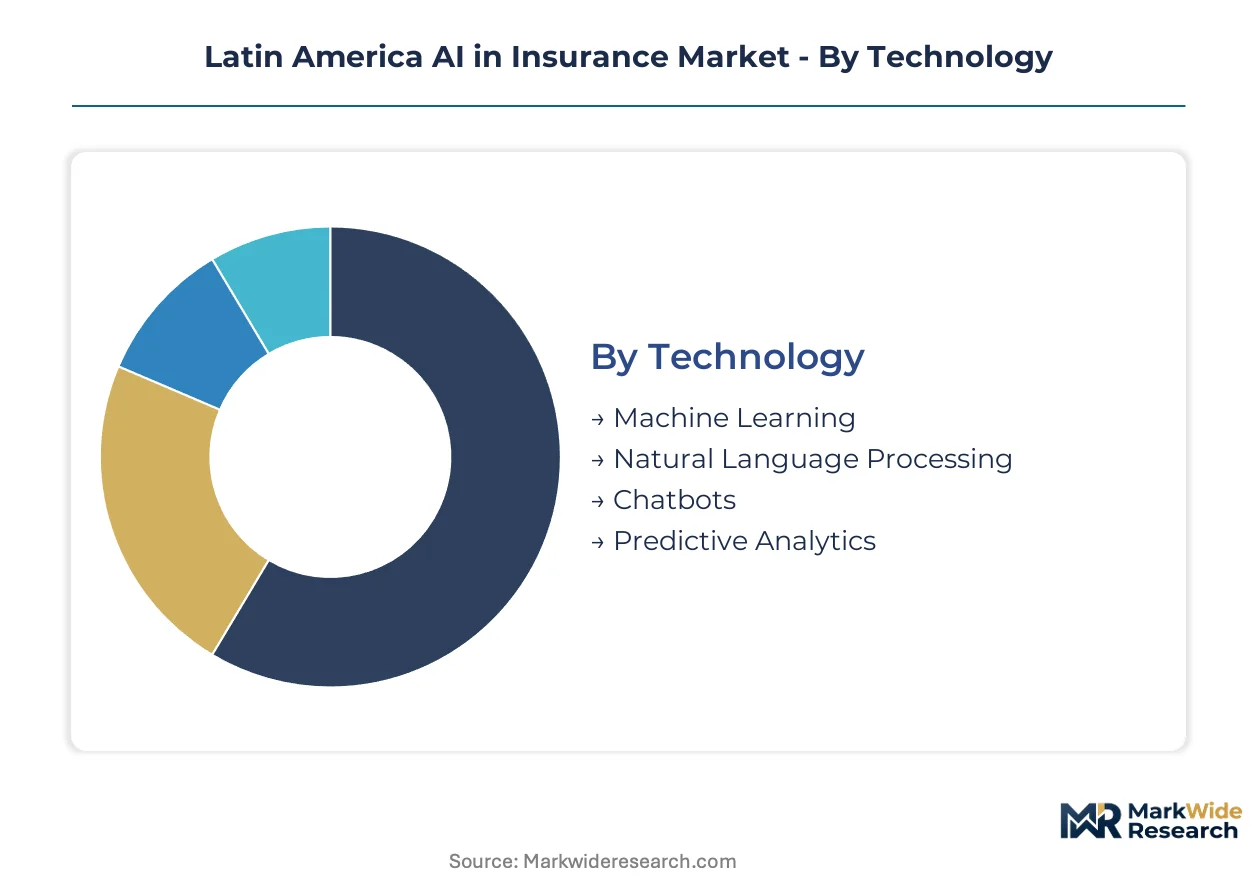
AI deployment patterns across Latin American insurance carriers diverge sharply by technology maturity, regulatory pressure, and legacy system constraints. Segment-specific investment priorities reveal where carriers are placing bets on automation returns versus compliance risk.
Technology:
After-sales service intensity peaks with technologies requiring continuous model retraining and explainability documentation under Brazil's LGPD audit requirements.
- Machine Learning:Supervised and unsupervised algorithms power risk-scoring engines and claims triage systems. Brazilian P&C carriers in São Paulo's financial corridor deploy these for catastrophe pricing models where static actuarial tables fail.
- Predictive Analytics:Statistical forecasting models project loss ratios and customer lifetime value. Mexico City InsurTech clusters concentrate demand here for dynamic premium adjustments tied to real-time behavioral signals from open banking APIs.
- Natural Language Processing:Portuguese and Spanish language models automate document extraction and sentiment analysis.
- Chatbots:Conversational interfaces handle first-line customer queries and claims intake.
By volume, Machine Learning leads. By growth pace, Natural Language Processing is ahead.
End User:
Cost tier structures separate enterprise-grade AI deployments at major carriers from lightweight SaaS implementations at intermediaries.
- Insurance Companies:Direct carriers bear the full infrastructure burden of compliant AI architectures. Bradesco and MAPFRE anchor regional investment in proprietary model development and core system integration.
- Brokers:Intermediary channels adopt AI-powered comparison tools and automated quoting. São Paulo's independent broker networks drive demand for low-code platforms that ingest multiple carrier APIs.
- Third-Party Administrators:Claims processing outsourcers deploy AI for fraud pattern detection across multiple carrier portfolios.
- Reinsurers:Risk transfer specialists leverage machine learning for portfolio aggregation and catastrophe bond pricing.
By deployment scale, Insurance Companies dominate. By adoption velocity, Third-Party Administrators are climbing fastest.
Application:
Application maturity correlates with data availability and regulatory clarity on algorithmic decision boundaries.
- Claims Management:End-to-end automation of intake, triage, and settlement compresses resolution timelines. Brazilian auto insurers deploy computer vision for damage assessment, cutting adjuster dispatch costs.
- Fraud Detection:Anomaly detection algorithms flag suspicious claim patterns and policy applications. Mexican carriers facing staged accident rings concentrate investment here for behavioral biometrics integration.
- Risk Assessment:Dynamic underwriting models incorporate alternative data streams.
- Customer Service:AI-powered query resolution and policy servicing.
By current spend, Claims Management captures the largest share. By expansion trajectory, Fraud Detection shows the steepest climb.
Deployment:
Customer type splits between multinationals demanding data sovereignty and mid-market carriers prioritizing capital efficiency.
- Cloud-Based:Elastic compute resources scale with seasonal premium cycles. Colombian and Chilean mid-market insurers favor AWS São Paulo and Azure Querétaro regions for rapid deployment without datacenter investment.
- On-Premises:Local infrastructure satisfies strict data residency mandates. Established Brazilian carriers maintain captive servers for core policy systems subject to LGPD localization requirements.
- Hybrid:Split architectures isolate sensitive data on-premises while bursting compute to cloud.
- Managed Services:Outsourced AI operations reduce talent acquisition burdens.
By new project starts, Cloud-Based leads. By committed investment, Hybrid architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexico City and São Paulo demonstrate the lowest price elasticity for AI-enabled underwriting solutions, while mid-market carriers in Colombia and Chile remain highly sensitive to implementation costs and compliance overhead.
Brazil
MAPFRE and Bradesco drive enterprise AI deployment for catastrophe modeling and predictive claims triage. The country's national data protection authority enforces LGPD algorithmic accountability requirements that mandate explainable AI documentation. São Paulo's financial corridor concentrates vendor activity, with insurers rebuilding core systems around compliant machine learning architectures.
Mexico
Open banking API mandates from the central bank enable real-time financial signal integration into dynamic risk scoring engines. The Fintech Law establishes standardized data access protocols that accelerate InsurTech partnerships. Mexico City's InsurTech cluster hosts the region's densest concentration of AI-native underwriting startups targeting auto and micro-insurance segments.
Colombia
Regulatory sandbox frameworks for InsurTechs create first-mover opportunities for algorithmic carriers entering Bogotá's underpenetrated middle-class insurance market. The national financial regulator supervises pilot programs for embedded insurance distribution through digital banking platforms. Caribbean coastal carriers invest in parametric policy AI for agricultural climate risk.
Chile
Mid-market insurers leverage AWS Santiago and Azure elastic compute for seasonal premium scaling without datacenter capital expenditure. The country's banking and securities supervisor oversees open finance implementation timelines. Santiago's financial district hosts regional shared service centers processing cross-border AI operations under strict data localization protocols.
Argentina
Currency volatility and capital controls compress AI infrastructure investment timelines for domestic carriers seeking rapid operational returns. The national insurance supervisor maintains conservative stances on algorithmic decision-making in consumer policies. Buenos Aires maintains legacy broker network dominance, slowing embedded distribution adoption relative to regional peers.
Latin America AI in Insurance Market Competitive Landscape
Capability concentration sits with global technology vendors and data-rich incumbent carriers; scale advantage sits with digitally native challengers and cloud-first mid-market insurers. The market structures around three archetypes: established multi-line carriers with captive AI development, global technology platforms licensing infrastructure, and neobank-embedded InsurTechs bypassing traditional distribution. Dominant competitive moves include strategic cloud partnerships for elastic compute access and regulatory sandbox positioning for first-mover data advantages.
Within the established carrier tier, MAPFRE and Bradesco exemplify proprietary model development strategies anchored in catastrophe-prone market specialization. Nubank occupies a distinct position as a digital-native challenger embedding AI underwriting directly within banking interfaces, eliminating broker intermediation entirely. IBM and Microsoft represent the global technology platform archetype, supplying cloud infrastructure and machine learning toolkits to carriers lacking internal development capacity.
| Leading Market Players |
|---|
| MAPFRE |
| Bradesco |
| Talanx |
| Zurich |
| Ebix Latin America |
| IBM |
| Microsoft |
| Nubank |
| BBVA Mexico |
| Others |
Value Network & Pricing Analysis
São Paulo's financial corridor concentrates cloud infrastructure capacity for AI-native underwriting platforms, compressing margins for mid-market insurers lacking elastic compute scale while amplifying pricing power for carriers with captive data center investments under LGPD localization mandates.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise AI procurement at established Brazilian carriers, while project-based engagements prevail among Colombia's sandbox-authorized InsurTech entrants. Price differentiation rests on explainability certification tiers and after-sales model retraining obligations under Brazil's national data protection authority audit protocols. Pricing pressure stems from open banking API commoditization of basic risk-scoring modules. Mid-market carriers in Chile exhibit highest price sensitivity; MAPFRE and Bradesco anchor the least elastic tier.
Supply Chain Analysis
Export control restrictions on GPU-accelerated computing hardware from United States suppliers constrain infrastructure scaling timelines for Latin American carriers building training clusters for Portuguese-Spanish language models. Supply concentration centers on United States cloud hyperscalers, Brazilian captive data centers, and Mexican edge compute facilities. Raw material dependencies span specialized AI accelerators, high-bandwidth memory modules, and optical interconnect hardware. Single-source vulnerability runs through United States semiconductor fabrication for advanced training chips. Distribution runs through direct hyperscaler partnerships and regional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent carriers must defend against embedded insurance substitution by neobank-native challengers that bypass traditional broker networks entirely, collapsing policy origination into transactional moments.
For Market Incumbents: Harden core system API compatibility through middleware investments that bridge 1990s-era policy engines with real-time underwriting models. Acquire explainable AI documentation capabilities to satisfy Brazil's national data protection authority audit requirements. Channel control over São Paulo's independent broker networks remains critical as Nubank and Inter capture digital-native customers.
For New Entrants and Emerging Players: Bogotá's underpenetrated middle-class segments offer lowest competitive density for algorithmic auto and micro-insurance products. Colombia's regulatory sandbox frameworks enable first-mover data advantages before established carriers retrofit legacy infrastructure. Embedded distribution partnerships with regional e-commerce platforms provide zero-click customer acquisition at transaction points.
For Investors and Strategic Acquirers: Long-term, this sits as a data-aggregation play because open banking API access determines underwriting precision advantages that compound across policy lifecycles. Target carriers with proprietary Portuguese-Spanish NLP development and established neobank distribution rails. Monitor central bank digital currency pilot implementations as inflection signals for biometric fraud prevention investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | LGPD compliance mandates audit-ready decision trails that legacy systems cannot generate without retrofit. |
| Open Banking API Integration | Brazil's Central Bank mandates enable real-time transaction flow ingestion for dynamic risk scoring. |
| Embedded Insurance Partnership | Neobank distribution through Nubank and Inter interfaces captures customers at financial transaction moments. |
| Portuguese-Spanish NLP Development | Conversational AI models trained on English corpora underperform in regional dialects, forcing proprietary investment. |
| Hybrid Cloud Infrastructure Deployment | Split architectures satisfy LGPD data residency while bursting compute to AWS São Paulo during seasonal surges. |
Research Methodology
Desk research of regulatory filings from Brazil's national data protection authority and Mexico's central bank, SEC disclosures from listed carriers, and open banking API documentation preceded structured interviews with chief technology officers at São Paulo insurers, Mexico City InsurTech founders, and Bogotá regulatory sandbox administrators. Secondary validation drew from ANVISA pharmaceutical data protection precedents, Brazilian insurance supervisor circulars, and cloud hyperscaler regional capex disclosures. Bottom-up policy administration system deployment counts were triangulated against top-down carrier AI investment estimates.
Assumptions held LGPD enforcement intensity and open banking API standardization timelines fixed across the projection horizon, while varying catastrophe frequency severity and central bank digital currency adoption pace. Segmentation modeling spanned technology maturity tiers, deployment architectures, end-user scale categories, and application complexity levels. CAGRs were derived from carrier capital expenditure trajectories and vendor booking patterns. Forecast inputs included seasonal premium cycle amplitude and explainable AI certification cost curves.
Practitioners should monitor regulatory sandbox expansion beyond Colombia, LGPD fine issuance patterns, and central bank digital currency biometric authentication mandates for early signals of forecast revision triggers. Material shifts in data residency enforcement strictness or open banking API scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
North America Insurtech Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurance Software Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Middle East and Africa Insurtech Market