
 Europe Insurtech Market | 2026-2036
Europe Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insurtech Market Foresight
CE marking for digital health and insurance software is collapsing the barrier between traditional carriers and technology entrants. Wefox Group leverages its full-stack brokerage platform to sustain direct customer relationships across multiple European jurisdictions. Clark anchors its growth in automated policy comparison and switching services for German consumers. FRISS differentiates through fraud detection algorithms embedded in property and casualty workflows.
Insurtech denotes technology-enabled platforms that digitize insurance distribution, underwriting, claims processing, and risk assessment through API-connected infrastructure and machine-learning models. These systems replace legacy policy administration with real-time data ingestion, dynamic pricing engines, and automated claims triage. Health Insurance technology attracts disproportionate development investment due to regulatory complexity and recurring premium structures. Blockchain applications in policy verification occupy narrower but higher-margin implementation channels. SME-facing platforms lead customer type expansion as embedded insurance partnerships proliferate across e-commerce and logistics software.
GDPR constraints on personal data processing shape product design across all customer-facing insurtech interfaces. The EU AI Act imposes risk-classification requirements on automated underwriting decisions, compelling platform redesigns. EIOPA's supervisory convergence mandates create compliance baselines that smaller entrants must meet for cross-border passporting. Stakeholders must monitor how national regulators transpose framework-level rules into licensing conditions that determine market access velocity.
Market Dynamics
The EU AI Act's risk-classification framework for automated underwriting is forcing platform redesigns across member states, compressing time-to-market for algorithmic products while elevating compliance costs.
Growth Catalysts
- GDPR-compliant data architectures:Platforms embedding privacy-by-design principles unlock cross-border passporting under EIOPA convergence mandates.
- SME embedded insurance partnerships:E-commerce and logistics software integrations create distribution density without traditional broker networks.
- Blockchain policy verification:Distributed ledger applications in property and casualty workflows reduce fraud-related loss ratios.
Market Restraints
- EIOPA licensing fragmentation:National transposition of framework-level rules creates variable market access velocity across Germany, France, and Italy.
- Legacy system integration costs:Traditional carriers face capital intensity when retrofitting API-connected infrastructure to core policy administration.
- Algorithmic bias liability exposure:The EU AI Act's high-risk system designation exposes underwriters to supervisory scrutiny and potential suspension.
Strategic Opportunities
- Health insurance recurring premium structures:Regulatory complexity in German and Dutch markets creates defensible moats for specialized platforms.
- CE marking convergence:Digital health and insurance software certification standards collapse barriers between technology entrants and established carriers.
- Dynamic pricing engine deployment:Real-time data ingestion capabilities enable usage-based models in commercial auto and cyber coverage.
Industry Challenges
- Actuarial-technologist skill gaps:Shortage of professionals fluent in both machine-learning model development and Solvency II capital requirements.
- Cross-border data residency compliance:GDPR localization mandates complicate cloud infrastructure decisions for multi-jurisdiction platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insurtech Market |
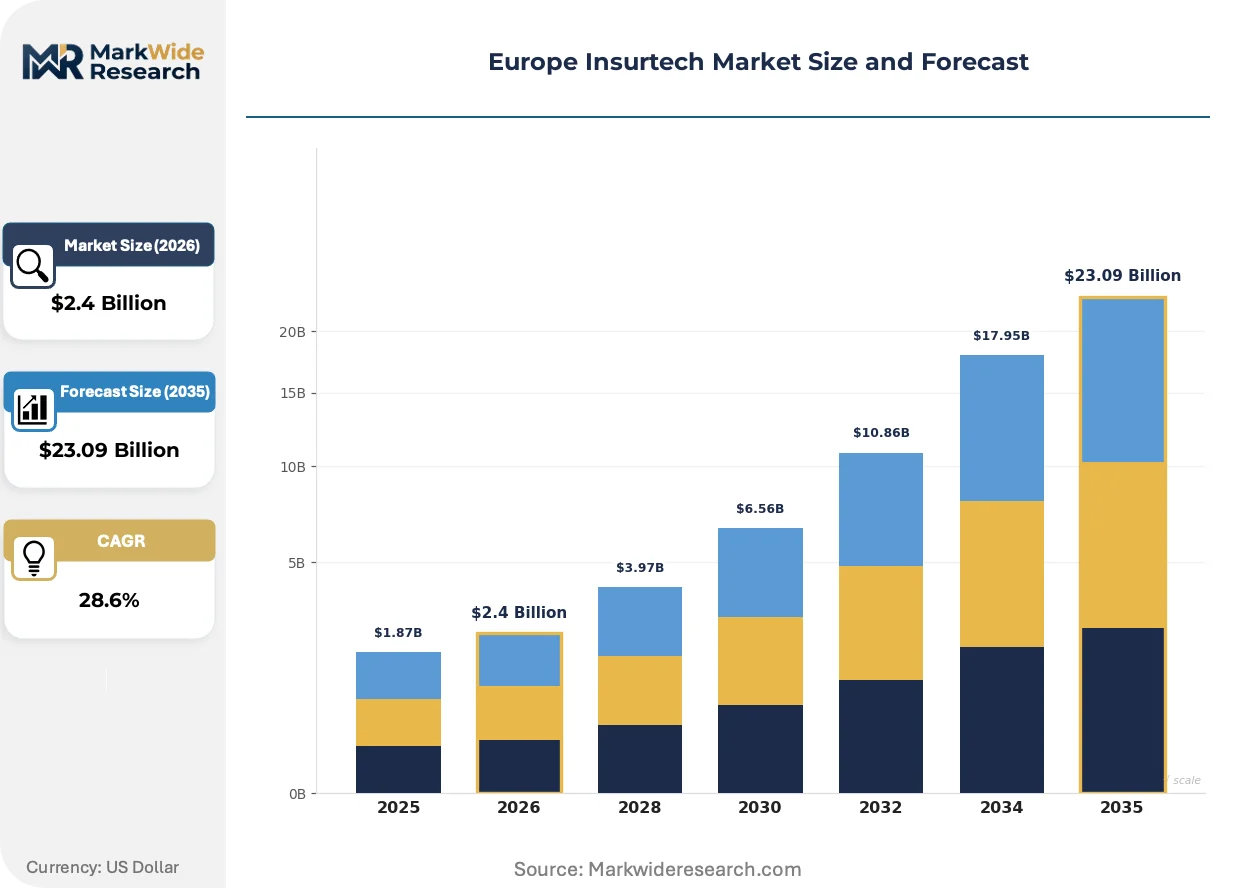
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Technology: Blockchain, AI, IoT, Big Data Customer Type: Individuals, SMEs, Corporates, Startups Distribution Channel: Online, Brokers, Agents, Direct Sales |
| Companies Covered | Wefox Group, Clark, Alan SA, FRISS, Shift Technology, Akur8, INZMO, Qover SA, Descartes Underwriting, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insurtech Market Shifts & Advancements
Machine-learning underwriting models are compressing risk assessment cycles from weeks to minutes, rewiring competitive advantage toward data velocity and algorithmic precision.
API-connected infrastructure is supplanting monolithic policy administration systems in mid-market carriers. German and Dutch insurers are adopting modular architectures fastest, with full-stack replacements projected to dominate new platform builds. This shift is enabling real-time premium adjustments and automated claims triage that legacy batch processing cannot match.
The EU AI Act's high-risk system classification is reshaping product development roadmaps for automated underwriting tools. Platforms must now maintain human oversight interfaces and algorithmic transparency documentation. Health and property segments face the steepest compliance curves, with German regulators already embedding these requirements into BaFin licensing conditions.
Embedded insurance distribution through B2B software marketplaces is displacing direct-to-consumer acquisition in commercial lines. Logistics platforms and payroll systems in France and the Netherlands now bundle coverage at point-of-transaction. This channel shift concentrates demand among SMEs seeking streamlined policy management without broker intermediation.
Europe Insurtech Market Segmentation
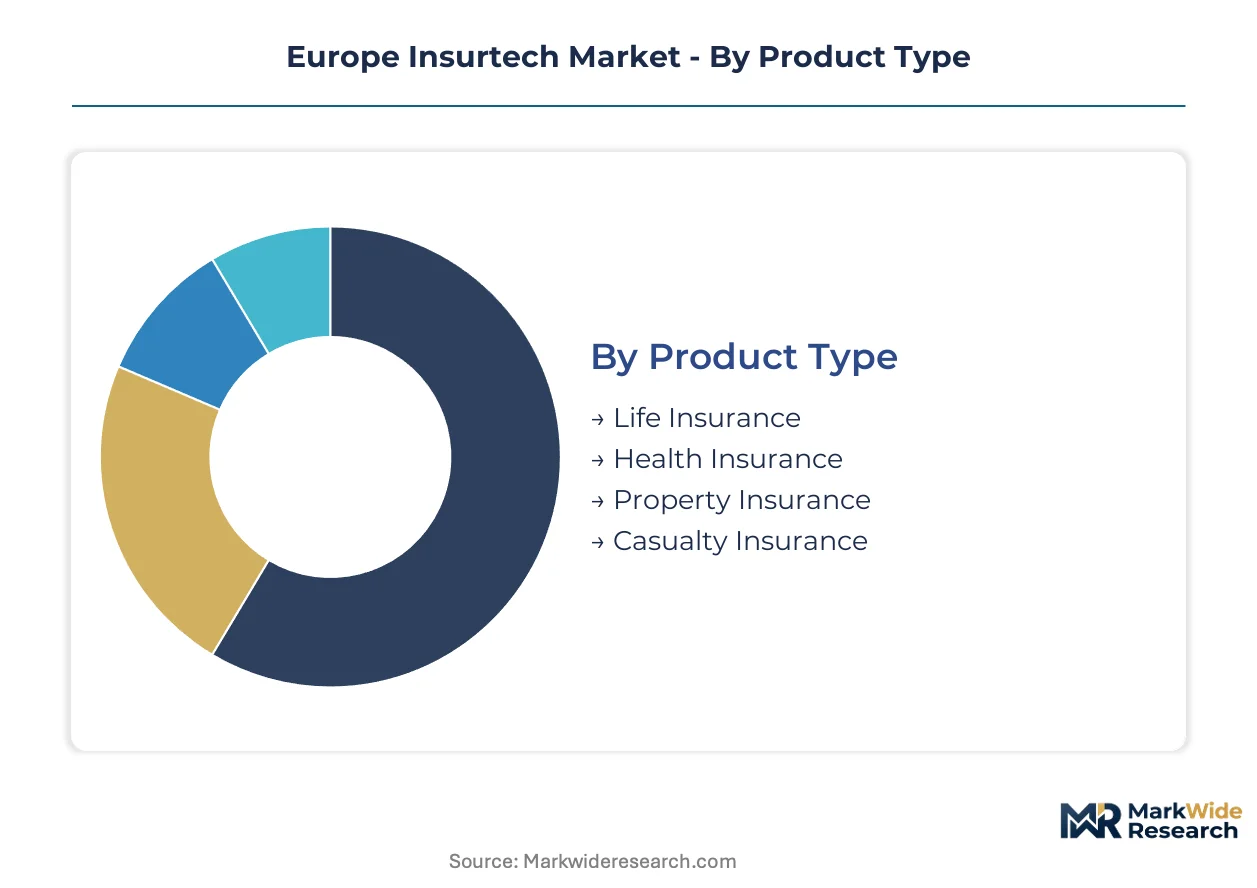
Segmentation in the European insurtech landscape reveals how regulatory complexity and technology maturity create divergent investment returns across product lines and customer categories. Understanding these partitions enables stakeholders to allocate capital toward segments where compliance architecture and distribution economics align most favorably.
Product Type:
GDPR and the EU AI Act impose tiered compliance burdens that fragment product development economics across life, health, and property lines.
- Life Insurance:Long-duration liabilities demand Solvency II capital modeling that few insurtech platforms have mastered. German and Dutch carriers dominate this segment through captive reinsurance structures that technology entrants struggle to replicate.
- Health Insurance:Recurring premium structures attract disproportionate development investment, though national health system fragmentation—particularly between Germany's statutory framework and the Netherlands' managed competition model—forces jurisdiction-specific platform builds.
- Property Insurance:IoT-enabled risk monitoring is compressing loss ratios for commercial portfolios across France and Italy.
- Casualty Insurance:Cyber coverage extensions are driving fastest policy innovation in SME-facing platforms.
Established volume favors Life Insurance; emerging adoption favors Health Insurance.
Technology:
Implementation costs and regulatory scrutiny intensity separate deployable solutions from experimental architectures.
- AI:Automated underwriting engines face the EU AI Act's high-risk system designation, compelling human oversight interfaces and algorithmic transparency documentation that extend development timelines. BaFin and France's national regulator have embedded these requirements into licensing conditions ahead of full transposition deadlines.
- Blockchain:Distributed ledger applications in policy verification occupy narrower but higher-margin implementation channels, particularly in cross-border commercial lines where smart contracts reduce counterparty friction.
- IoT:Telematics integration in commercial auto and property monitoring is gaining fastest traction among German mid-market carriers.
- Big Data:GDPR constraints on personal data processing limit ingestion scope for consumer-facing pricing models.
Capital deployment concentrates on AI; regulatory headwinds are shifting investment toward Blockchain for B2B verification use cases.
Customer Type:
Acquisition economics and retention mechanics vary sharply across the sophistication spectrum from individual consumers to corporate risk managers.
- SMEs:Embedded insurance partnerships through e-commerce and logistics software create distribution density without traditional broker networks. French payroll platforms and Dutch supply chain systems now bundle coverage at point-of-transaction, compressing customer acquisition costs below direct-to-consumer benchmarks.
- Corporates:Complex risk placement demands hybrid digital-broker relationships that full-stack platforms struggle to serve profitably.
- Individuals:Automated policy comparison tools dominate in Germany's price-transparent personal lines market.
- Startups:Venture-backed firms represent a narrow but high-visibility segment seeking flexible coverage structures.
Platform economics favor SME embedded distribution; corporate complexity sustains incumbent broker relationships.
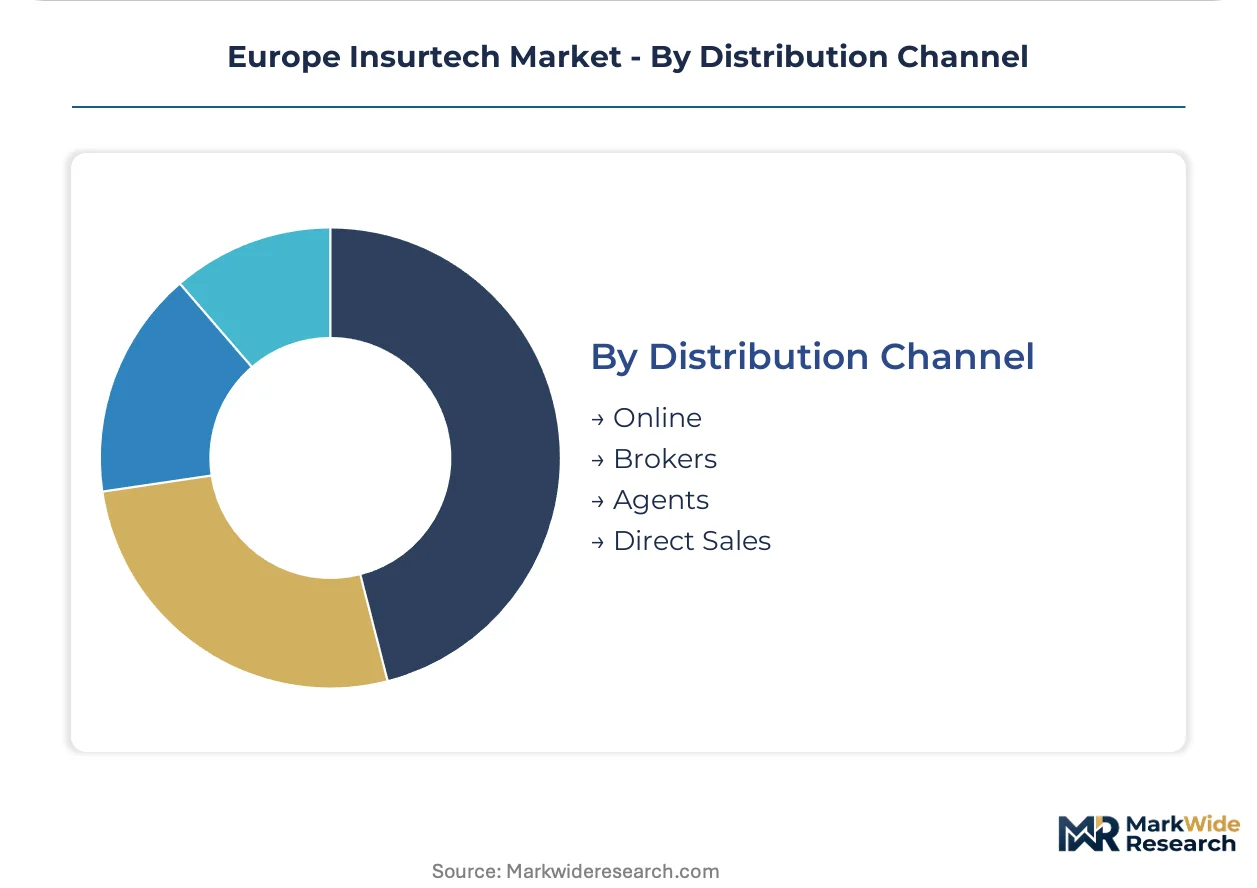
Distribution Channel:
Channel mix determines both regulatory exposure and margin capture potential across European jurisdictions.
- Online:Direct digital acquisition platforms face EIOPA's supervisory convergence mandates on disclosure and suitability requirements. German consumers demonstrate highest comfort with fully automated purchasing for standardized personal lines.
- Brokers:Traditional intermediaries retain dominance in commercial lines where risk customization exceeds algorithmic capability.
- Agents:Tied distribution networks are contracting fastest in markets with established digital infrastructure.
- Direct Sales:Carrier-owned channels concentrate in life insurance where relationship depth supports cross-selling.
Online platforms capture volume growth; broker relationships defend margin in complex commercial placements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's risk-classification framework for automated underwriting is accelerating platform redesigns across member states, compressing time-to-market for algorithmic products while elevating compliance costs for technology entrants seeking EIOPA passporting rights.
Germany
BaFin has embedded high-risk system requirements into licensing conditions ahead of full EU AI Act transposition deadlines. Embedded insurance partnerships through payroll platforms and logistics software are compressing customer acquisition costs below direct-to-consumer benchmarks. Berlin and Munich anchor the densest cluster of full-stack brokerage platforms serving SME distribution channels.
United Kingdom
Post-Brexit regulatory divergence from Solvency II is creating jurisdictional complexity for cross-border platform operators. The Financial Conduct Authority's sandbox framework permits controlled testing of automated underwriting engines without full authorization. London's Lloyd's market integration with API-connected infrastructure is accelerating real-time premium adjustments in specialty commercial lines.
France
ANSM and CNIL coordination on health data processing is shaping product design for digital health insurance interfaces. Automated policy comparison tools dominate personal lines distribution through price-transparent aggregator platforms. Paris and Lyon concentrate insurtech development investment focused on fraud detection algorithms embedded in property and casualty workflows.
Netherlands
The managed competition model for health insurance forces jurisdiction-specific platform builds distinct from Germany's statutory framework. DNB supervisory convergence mandates create compliance baselines for cross-border passporting into Belgian and Luxembourg markets. Amsterdam anchors embedded insurance distribution through supply chain software bundling coverage at point-of-transaction.
Italy
IVASS licensing fragmentation creates variable market access velocity compared to German and French regulatory environments. IoT-enabled risk monitoring is compressing loss ratios for commercial property portfolios in northern industrial corridors. Milan concentrates insurtech partnerships with traditional carriers retrofitting API-connected infrastructure to legacy policy administration systems.
Europe Insurtech Market Competitive Landscape
Player mix skews toward full-stack brokerage platforms and specialized algorithmic service providers rather than monolithic carriers. Market structure exhibits moderate consolidation around technology-enabled distributors with direct customer relationships. Three archetypes dominate: vertically integrated brokerages owning end-to-end policy lifecycle management, point-solution specialists embedding fraud detection or dynamic pricing engines into carrier workflows, and embedded insurance orchestrators powering B2B software marketplace distribution. Competitive dynamics center on M&A activity consolidating SME-facing distribution channels and strategic partnerships between technology entrants and established carriers seeking API-connected infrastructure retrofit.
Within the full-stack brokerage tier, Wefox Group and Clark exemplify divergent approaches to customer relationship ownership across multiple European jurisdictions. Among algorithmic specialists, FRISS occupies a position representing fraud detection archetypes embedded in property and casualty workflows. These three companies anchor the competitive landscape's technology-forward segment, with each sitting within distinct strategic postures toward carrier partnership versus direct distribution.
| Leading Market Players |
|---|
| Wefox Group |
| Clark |
| Alan SA |
| FRISS |
| Shift Technology |
| Akur8 |
| INZMO |
| Qover SA |
| Descartes Underwriting |
| Others |
Supply & Pricing Matrix
Sixty-day implementation timelines for API-connected policy administration systems concentrate vendor pricing power among German and Dutch full-stack platform providers, while compressing margins for retrofit-dependent legacy carriers facing EIOPA compliance deadlines. This lead-time asymmetry between greenfield builds and legacy integration creates tiered pricing structures where technology entrants capture premium economics against incumbent cost disadvantages.
Pricing Analysis
Certification level under the EU AI Act's high-risk system designation creates the primary spread between premium-tier algorithmic underwriting platforms and standard workflow automation tools. Three-tier pricing structure across premium, standard, and economy levels reflects compliance documentation depth, human oversight interface sophistication, and BaFin licensing advancement. Pricing pressure stems from embedded insurance partnerships compressing SaaS margins as logistics and payroll platforms demand volume-scaled economics. SME-facing distributors exhibit highest price sensitivity, while corporate risk managers prioritize algorithmic precision over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound cloud infrastructure costs for multi-jurisdiction platforms requiring GDPR-compliant data residency across German, Dutch, and French server clusters. Technology sourcing concentrates in Ireland, Estonia, and Lithuania for API development talent, while actuarial modeling expertise clusters in Germany and the United Kingdom. Raw material dependencies include proprietary machine-learning training datasets, Solvency II capital modeling libraries, and EIOPA convergence documentation frameworks. Single-source vulnerability sits with cloud hyperscalers dominating compliant infrastructure provisioning. Distribution runs through B2B software marketplaces and direct carrier API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national health system architectures and variable EIOPA transposition timelines creates niche opportunities for jurisdiction-specialized platforms. Embedded insurance distribution through payroll and logistics software is fragmenting demand into discrete regulatory clusters.
For Market Incumbents: Shield core SME relationships by accelerating API-connected infrastructure deployment ahead of EU AI Act enforcement windows. Acquire specialized algorithmic service providers in fraud detection and dynamic pricing to offset vertical integration disadvantages against full-stack entrants. Prioritize BaFin and DNB licensing advancement to compress competitor passporting velocity. For New Entrants and Emerging Players: Lead with health insurance recurring premium structures in the Netherlands' managed competition model, where regulatory complexity deters generalized platforms. Target Italian commercial property IoT monitoring, where IVASS licensing fragmentation delays established carrier response times. Pursue white-label embedded distribution through French payroll platforms as the primary go-to-market channel. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EIOPA convergence mandates will consolidate passporting rights among pre-compliant platforms, creating acquisition scarcity for licensed entities. Focus on algorithmic specialists with existing high-risk system documentation and human oversight interfaces. Monitor BaFin licensing condition updates as the signal for transposition velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Pathway | BaFin and DNB licensing conditions now embed high-risk system requirements ahead of full transposition deadlines. |
| Embedded Insurance Partnership | French payroll platforms and Dutch supply chain systems bundle coverage at point-of-transaction, displacing broker networks. |
| API Infrastructure Integration | Modular architectures enable real-time premium adjustments that legacy batch processing cannot match. |
| Acquisition of Algorithmic Specialist | Fraud detection and dynamic pricing capabilities compress development timelines for automated underwriting deployment. |
| Geographic Licensing Expansion | EIOPA passporting rights unlock cross-border distribution without duplicative national authorization processes. |
Research Methodology
Operator-level perspectives from insurtech platform CTOs, BaFin licensing officers, EIOPA supervisory convergence specialists, and German health insurance product directors anchored the qualitative base for this analysis. Secondary validation drew from EU AI Act implementation guidance, EIOPA passporting statistics, Dutch DNB supervisory reports, and French ANSM health data processing frameworks. Bottom-up platform deployment metrics triangulated against top-down regulatory timeline assessments.
Sensitivity analysis across algorithmic risk-classification scenarios, embedded partnership penetration rates, and national transposition velocity variations shaped the forecast framework. Segmentation dimensions modeled include product type, technology implementation tier, customer sophistication level, and distribution channel regulatory exposure. CAGRs derived from technology adoption curve analysis applied to insurance premium volume baselines, with inputs from cloud infrastructure provisioning costs and compliance documentation development timelines.
The analysis sits within stated boundaries; outcomes outside EIOPA convergence adherence, GDPR data residency maintenance, or EU AI Act high-risk system designation would require recalibration. Forecasts reflect assumptions regarding regulatory transposition schedules and technology integration feasibility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Insurtech Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Global Blockchain in Insurance Market