
 Global Insurance Agency Software Market | 2026-2036
Global Insurance Agency Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insurance Agency Software Market Outlook
The capital-intensity divergence between legacy platform providers and cloud-native entrants is reorganizing competitive dynamics across the sector. Vertafore leverages decades of installed-base relationships to sustain recurring revenue from independent agency networks. Applied Systems anchors its position through deep integration with carrier rating systems and comparative quoting engines.
Insurance agency software encompasses policy administration, claims management, underwriting automation, and billing solutions delivered through cloud, on-premises, or hybrid architectures, typically featuring API-first design for carrier connectivity and real-time data synchronization. Its primary commercial purpose is reducing manual processing overhead while ensuring regulatory compliance across policy lifecycles. Claims management and policy administration occupy the largest solution segments, reflecting persistent demand for end-to-end workflow consolidation. Cloud-based deployment is accelerating fastest as agencies abandon server maintenance and embrace remote accessibility.
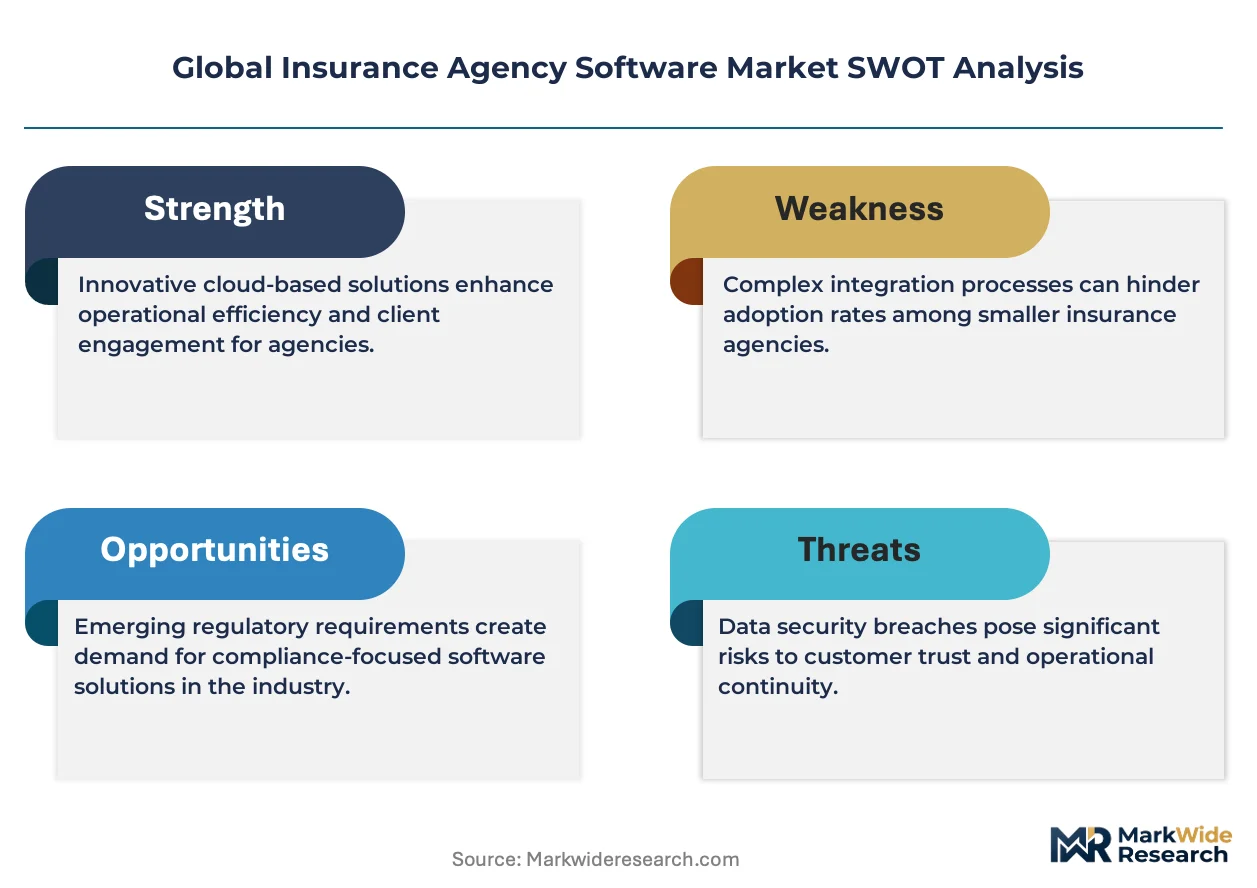
The EU AI Act, state-level NAIC model laws, and HIPAA privacy standards collectively shape product development roadmaps and market access conditions for software vendors serving regulated insurance channels. Compliance with algorithmic accountability requirements is forcing vendors to embed audit trails and explainability features into underwriting modules. Stakeholders must monitor how fragmented state regulations interact with emerging federal frameworks to anticipate certification burdens and competitive positioning requirements.
Market Dynamics
Cloud migration is compressing infrastructure timelines while the EU AI Act imposes algorithmic accountability requirements on automated underwriting modules, forcing vendors to rebuild core architectures.
Growth Catalysts
- Independent agency networks:Cloud-based policy administration tools reduce server maintenance burdens and enable remote accessibility for distributed agent workforces.
- EU AI Act compliance mandates:Automated underwriting systems require embedded audit trails and explainability features, creating replacement demand for legacy platforms.
- Comparative rating engines:Real-time carrier connectivity through API-first designs accelerates quote-to-bind velocity for commercial lines.
Market Restraints
- Legacy system entrenchment:Decades-old policy administration platforms create switching friction and data migration complexity for established agencies.
- Fragmented state regulations:NAIC model law variations across US jurisdictions multiply compliance certification burdens for multi-state software deployments.
- Specialized talent scarcity:Actuarial-technical hybrid skills required for underwriting automation development command premium compensation.
Strategic Opportunities
- Embedded insurance APIs:Non-traditional distribution channels including automotive dealerships and e-commerce platforms seek white-labeled policy origination capabilities.
- Claims fraud detection convergence:Machine learning integration with computer vision enables automated damage assessment for property and auto lines.
- US agency modernization wave:Aging on-premises infrastructure at mid-sized independent agencies creates replacement demand for cloud-native alternatives.
Industry Challenges
- HIPAA privacy compliance:Health insurance agency software must maintain protected health information safeguards across policy lifecycle workflows.
- Carrier system integration:Proprietary rating algorithms and legacy EDI formats require custom mapping for each carrier connection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insurance Agency Software Market |
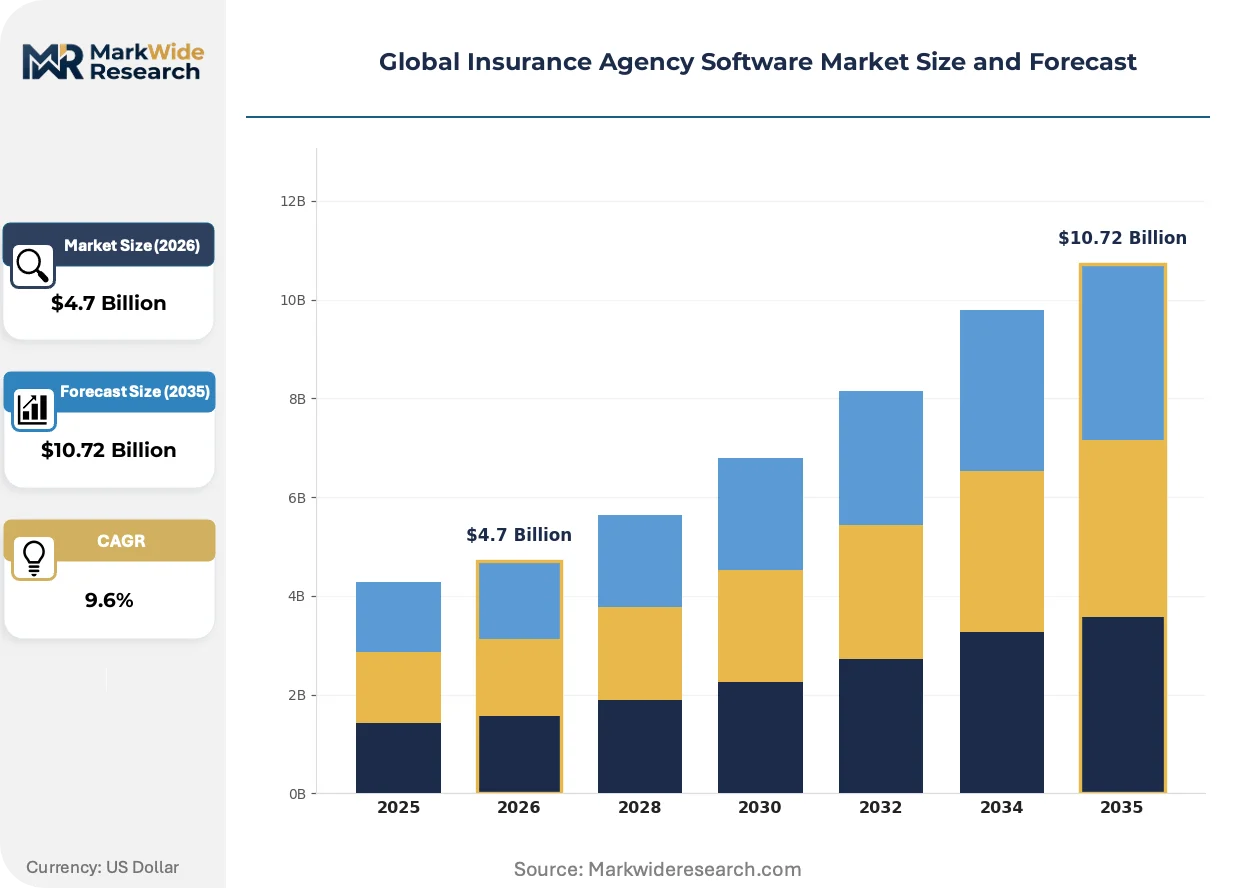
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Claims Management, Policy Administration, Underwriting Software, Billing Solutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions End User: Independent Agents, Brokers, Insurers, Adjusters Customer Type: Commercial, Personal, Specialty, Reinsurance |
| Companies Covered | Vertafore, Applied Systems, EZLynx, Hawksoft, Salesforce, Oracle, NowCerts, Jenesis Software, AgencyBloc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insurance Agency Software Market Strategic Shifts
API-first architectures are dissolving traditional boundaries between agency management systems and carrier core platforms, enabling real-time data synchronization that reconfigures competitive advantage around connectivity depth rather than feature breadth.
Embedded analytics engines within policy administration modules are miniaturizing risk assessment workflows into real-time decision points. Mid-sized commercial lines agencies are adopting these capabilities fastest, compressing quote turnaround from days to minutes. This compression is miniaturizing the traditional underwriter role into exception-handling functions while elevating algorithmic model governance.
The EU AI Act's algorithmic accountability requirements are mandating explainability documentation for automated underwriting decisions. Vendors must now embed decision audit trails and bias testing protocols into production systems. Commercial property and casualty modules face the steepest compliance redesign timelines as carriers demand certification before algorithmic deployment.
Subscription pricing for core agency management functions is displacing perpetual license models that dominated the 2010s. Independent agency networks in the United States are consolidating vendor relationships to capture volume discounts, reducing the number of simultaneous platform relationships per agency from four to two. This consolidation concentrates negotiating leverage with the largest cloud-native providers.
Global Insurance Agency Software Market Segmentation
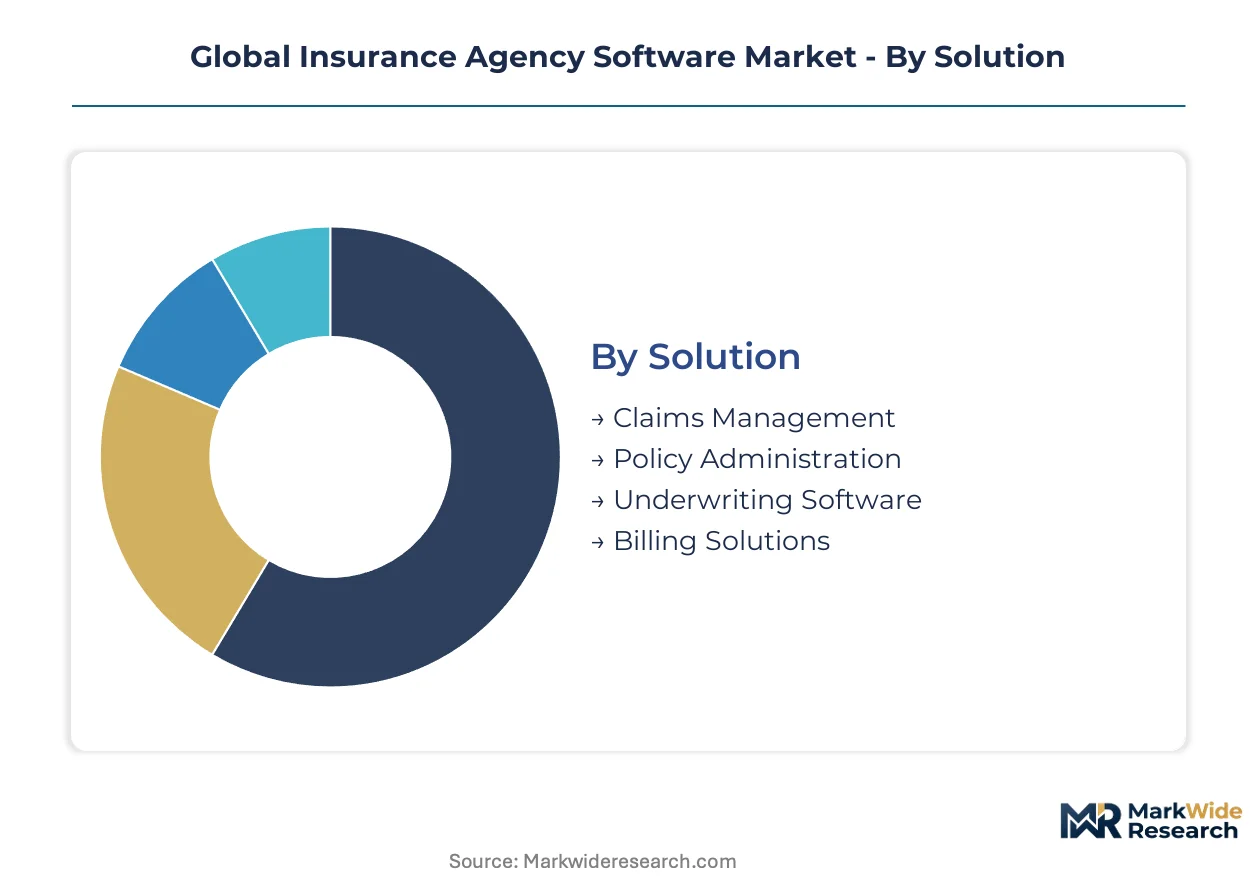
Segmentation reveals how software vendors allocate R&D resources across divergent technical architectures and buyer sophistication levels. Margin capture varies sharply between legacy maintenance contracts and cloud-native subscription streams, reshaping competitive positioning across each dimension.
Solution:
Margin pools concentrate in modules that automate high-touch, regulated workflows where switching costs compound over time.
- Policy Administration:Core systems managing policy lifecycle from quote through renewal, featuring rating engine integration and document generation. Demand concentrates among United States independent agencies modernizing decades-old infrastructure to meet remote workforce requirements. Cloud-native architectures with embedded compliance updates command premium pricing against legacy maintenance contracts.
- Claims Management:Workflow platforms handling first notice of loss through settlement, increasingly incorporating computer vision for damage assessment. Commercial lines carriers in Germany and France are driving adoption as EU AI Act mandates force rebuilds of automated decision modules with full audit trails and explainability documentation.
- Underwriting Software:Risk scoring and decision-support tools with algorithmic accountability features.
- Billing Solutions:Premium collection, commission tracking, and reconciliation systems.
Policy Administration holds installed capacity. Claims Management is rotating up the share rankings.
Deployment:
Cost tier stratification separates enterprise buyers maintaining control over sensitive data from mid-market agencies prioritizing operational agility.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and API-first carrier connectivity. United States independent agency networks are consolidating onto these platforms fastest, abandoning server maintenance to capture volume discounts through vendor consolidation.
- Hybrid:Split architectures keeping sensitive rating algorithms on-premises while pushing customer-facing functions to cloud. German and French carriers favor this model for commercial property lines where EU AI Act compliance documentation must remain auditable within sovereign data boundaries.
- On-Premises:Legacy single-tenant installations requiring dedicated infrastructure management.
- Mobile Solutions:Field-accessible applications for adjusters and remote agents.
Cloud-Based deployment captures the steepest expansion trajectory. Hybrid architectures are gaining share fastest among regulated commercial lines.
End User:
Volume concentration tracks the fragmentation of insurance distribution, with technology needs diverging across captive and independent channels.
- Independent Agents:Small to mid-sized agencies representing multiple carriers, requiring comparative quoting and consolidated policy views. These buyers in the United States are reducing simultaneous platform relationships from four to two, concentrating negotiating leverage with largest cloud-native providers.
- Brokers:Intermediaries handling complex commercial risks across international markets.
- Insurers:Direct writers and carriers with captive agency forces.
- Adjusters:Third-party and staff claims professionals requiring field documentation tools.
Independent Agents hold installed capacity. Brokers are rotating up the share rankings.
Customer Type:
Maturity curves separate lines with standardized data formats from specialty risks requiring bespoke underwriting workbenches.
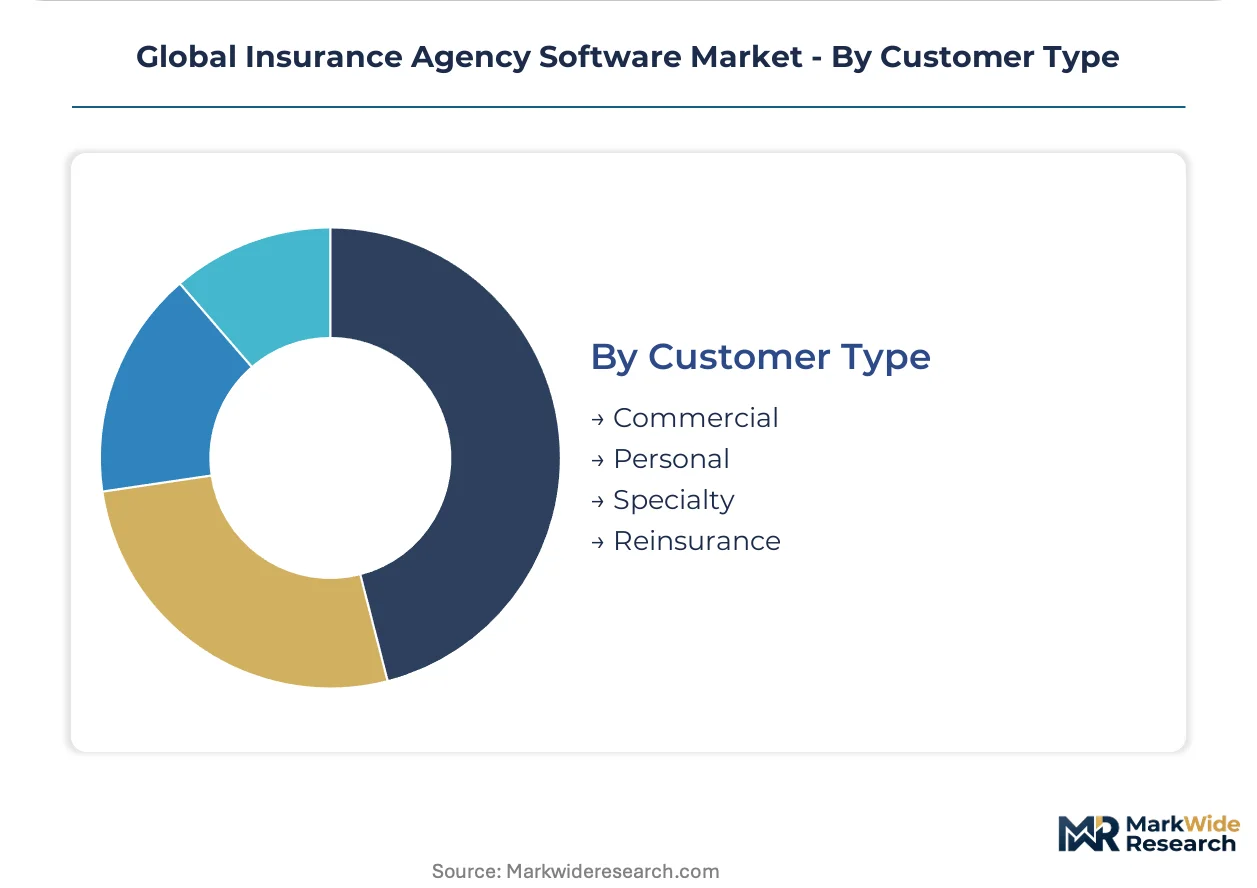
- Commercial:Business insurance spanning property, liability, and workers compensation with complex rating algorithms. Mid-sized agencies in Illinois, Texas, and California are adopting embedded analytics engines fastest, compressing quote turnaround through real-time decision points.
- Personal:Auto and homeowners lines with high transaction volumes and standardized forms.
- Specialty:Niche coverages including marine, aviation, and cyber requiring custom underwriting modules.
- Reinsurance:Treaty and facultative placement systems handling layered risk transfers.
Commercial lines hold installed capacity. Specialty lines are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers show the lowest price elasticity as legacy modernization demands override budget constraints, while German and French carriers exhibit higher sensitivity to sovereign data requirements. This divergence shapes vendor pricing power and compliance investment priorities.
United States
Independent agency networks in Illinois, Texas, and California are consolidating vendor relationships from four platforms to two, capturing volume discounts. HIPAA compliance mandates shape health insurance software procurement at state-regulated exchanges. Chicago and Dallas-Fort Worth clusters host the densest concentration of mid-sized commercial lines agencies adopting embedded analytics engines.
Germany
Commercial property and casualty carriers favor hybrid architectures keeping rating algorithms on-premises per sovereign data boundaries. The EU AI Act forces rebuilds of automated underwriting modules with full audit trails and explainability documentation. Munich and Frankfurt insurance clusters drive demand for compliance-certified decision-support tools.
France
Claims management platforms incorporating computer vision for damage assessment gain traction among auto and property lines carriers. ANSM and CNIL oversight extends to algorithmic accountability in automated settlement workflows. Lyon and Paris commercial lines hubs prioritize modules with embedded bias testing protocols.
United Kingdom
Lloyd's market brokers and international risk intermediaries seek API-first platforms enabling real-time carrier connectivity across multiple jurisdictions. GDPR compliance requirements intersect with FCA conduct standards for algorithmic transparency. London's insurance technology corridor concentrates demand for white-labeled policy origination capabilities.
Japan
Personal lines insurers modernize legacy policy administration systems to support aging workforce transitions and remote agent accessibility. METI guidelines on AI governance influence procurement criteria for automated underwriting tools. Tokyo and Osaka metropolitan areas anchor adoption of cloud-native billing solutions with embedded commission tracking.
Global Insurance Agency Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertafore and Applied Systems anchor the premium tier through decades-long installed-base relationships and deep carrier integration capabilities. Cloud-native specialists occupy the mid-market with API-first architectures and subscription pricing models. Competitive moves concentrate on vendor consolidation partnerships and embedded insurance API development for non-traditional distribution channels.
Within the legacy-anchored tier, Vertafore and Applied Systems exemplify archetypes sustained by recurring revenue from independent agency networks and comparative quoting engine dominance. Salesforce and Oracle represent diversified technology conglomerates extending horizontal CRM and database platforms into insurance-specific workflows through vertical configuration. These players occupy positions shaped by platform breadth rather than sector depth.
| Leading Market Players |
|---|
| Vertafore |
| Applied Systems |
| EZLynx |
| Hawksoft |
| Salesforce |
| Oracle |
| NowCerts |
| Jenesis Software |
| AgencyBloc |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS architectures displacing perpetual license models simultaneously redistribute supply geography toward US-based hyperscaler infrastructure and compress pricing economics through subscription bundling. This substitution collapses upfront implementation revenue into recurring streams while concentrating vendor negotiating leverage with independent agency networks consolidating platform relationships.
Pricing Analysis
Maintenance and support contracts anchored in legacy installed bases generate lifetime value exceeding initial license fees by substantial multiples. Pricing stratifies across premium, standard, and economy tiers differentiated by API integration depth and embedded compliance automation. Cost compression in mid-market SaaS tiers intensifies as vendor consolidation from four platforms to two per agency concentrates volume discount leverage. Independent agents in Illinois and Texas exhibit lowest price sensitivity due to legacy modernization urgency, while German carriers show higher elasticity tied to sovereign data requirements.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native delivery, eliminating physical inventory while introducing hyperscaler dependency as the critical supply node. Software development draws from engineering talent pools concentrated in the United States, India, and Ireland, with carrier connectivity modules resting on proprietary rating algorithm access. Single-source vulnerability concentrates around AWS, Azure, and Google Cloud infrastructure for multi-tenant SaaS architectures. Distribution runs through direct vendor sales organizations and value-added resellers serving independent agency networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in insurance agency software hinge on API interoperability standards dissolving boundaries between agency management systems and carrier core systems, reconfiguring competitive advantage around connectivity depth.
For Market Incumbents: Secure carrier integration exclusivity through deeper rating engine partnerships before cloud-native entrants achieve comparable connectivity density. Prioritize HIPAA and EU AI Act certification investment as switching cost amplifiers against mid-market SaaS challengers. Vertical integration into embedded insurance APIs for automotive dealerships and e-commerce platforms defends margin position against horizontal technology conglomerates extending CRM platforms into insurance workflows. For New Entrants and Emerging Players: Differentiate on explainability-first underwriting modules targeting German and French commercial property carriers facing EU AI Act compliance deadlines. White-space concentration sits with specialty lines marine and aviation segments where custom underwriting workbenches remain underpenetrated by cloud-native alternatives. Go-to-market execution should anchor in Lloyd's market brokers seeking API-first platforms with multi-jurisdictional carrier connectivity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed policy administration specialists holding decade-long maintenance contracts at mid-sized US independent agencies. Five-to-ten year viability hinges on successful cloud migration execution and retention through subscription conversion. Acquisition targets should demonstrate embedded analytics engine adoption among commercial lines agencies in Illinois, Texas, and California. The signal to watch is carrier certification velocity for automated underwriting modules ahead of EU AI Act enforcement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable real-time carrier connectivity that compresses quote-to-bind velocity for commercial lines agencies. |
| Acquisition of Specialist Firm | Computer vision capabilities for automated damage assessment address EU AI Act audit trail requirements in claims management. |
| Strategic Partnership | Embedded insurance API alliances with automotive dealerships open non-traditional distribution channels beyond independent agency networks. |
| Geographic Expansion | Hybrid deployment models in Germany and France satisfy sovereign data boundaries while capturing commercial property and casualty demand. |
| Product Launch | Explainability documentation tools for automated underwriting decisions meet EU AI Act algorithmic accountability mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, NAIC regulatory databases, carrier technology disclosures, and EU AI Act implementation guidance. Interviews with independent agency principals, carrier IT procurement officers, compliance officers at German and French insurers, and API integration specialists informed demand-side validation. Bottom-up aggregation of vendor subscription metrics and top-down triangulation against cloud infrastructure spending patterns anchored value estimates.
Segmentation dimensions modeled span deployment architecture, solution module type, end-user channel, customer line of business, and regional regulatory cluster across the analysis window. CAGRs derive from logistic adoption curves fitted to cloud migration timelines and compliance-driven replacement cycles. Forecast inputs incorporate EU AI Act implementation schedules, HIPAA enforcement patterns at state-regulated exchanges, and independent agency consolidation trajectories from four platforms to two.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration momentum and fragmented state regulation persistence; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement timelines accelerate or carrier certification requirements for algorithmic underwriting expand beyond current documentation standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Insurance Software Market
Insurance Technology
Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market