
 China AI in Insurance Market | 2026-2036
China AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China AI in Insurance Market Insights
Multi-source AI procurement is consolidating as insurers reduce vendor fragmentation for core underwriting engines. Ping An Insurance leverages its Ping An Cloud infrastructure to anchor proprietary model development across life and health lines. ZhongAn Online P&C Insurance competes through fully digital-native policy administration, while Ant Insurance Services extends its embedded insurance distribution through Alipay's transaction data ecosystem.
China AI in Insurance denotes the deployment of machine learning algorithms, natural language processing systems, and predictive analytics platforms to automate risk evaluation, claims adjudication, and customer interaction workflows across China's regulated insurance sector. These systems process structured policy data and unstructured medical or accident documentation to generate actuarial decisions within seconds rather than days. Fraud detection solutions lead current deployment, absorbing disproportionate capital as synthetic identity schemes proliferate in digital channels. Underwriting automation represents the fastest-expanding segment, with margin pools concentrating where computer vision integrates with telematics for auto and agricultural coverage. Natural language processing capabilities mature fastest in customer service chatbots, though differentiation now shifts toward multimodal claim intake combining image recognition with voice transcription.
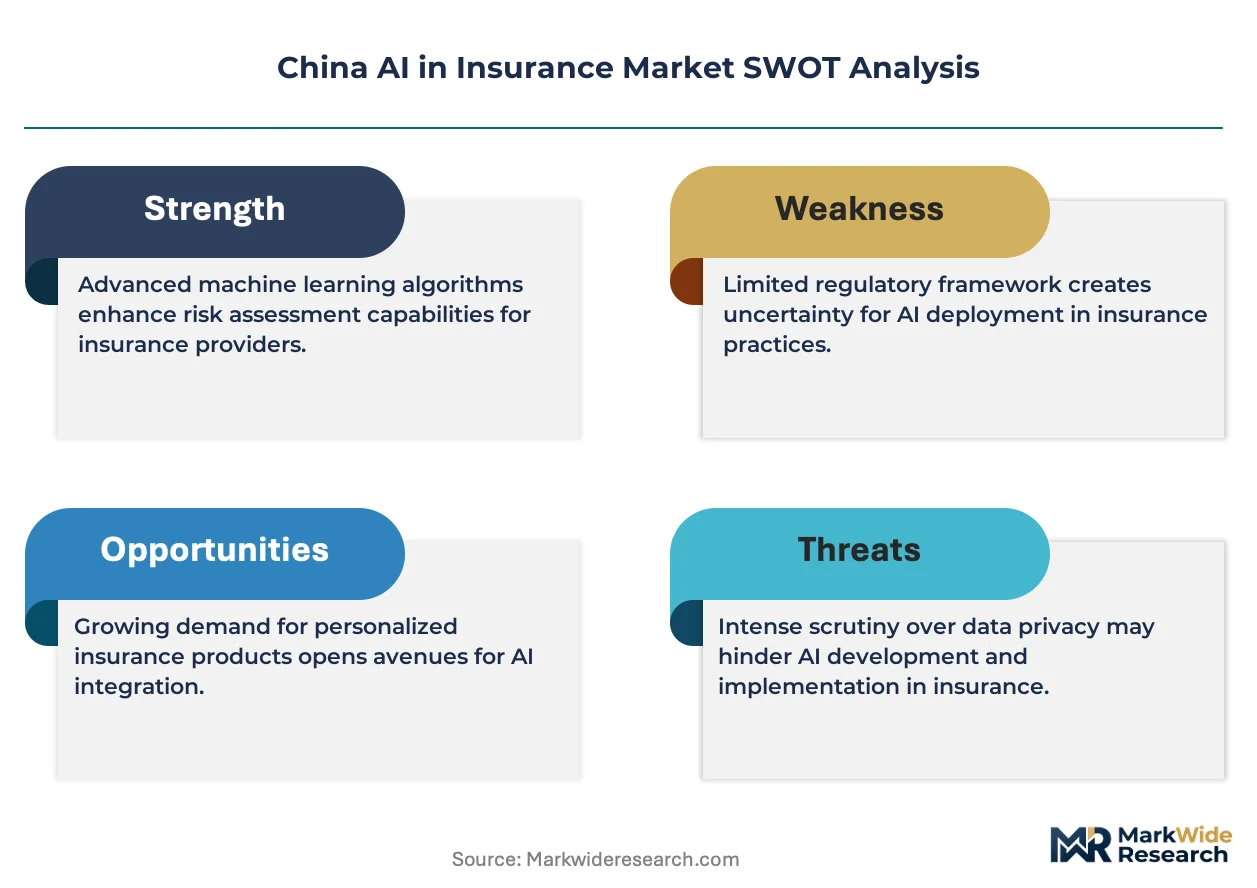
SAMR algorithm registration requirements and MIIT deep synthesis provisions are reshaping product standards for automated decision systems, forcing insurers to document training data provenance and model interpretability. The country's national insurance regulator mandates human-in-the-loop protocols for claims above specified thresholds, constraining full automation in high-value segments. Stakeholders must monitor evolving algorithm filing timelines and sandbox expansion criteria to time product rollouts against compliance readiness.
Market Dynamics
MIIT algorithm governance rules and SAMR registration mandates are forcing insurers to rebuild automated underwriting systems around documented training data provenance and human-in-the-loop protocols, compressing deployment timelines for high-value claims segments.
Growth Catalysts
- Synthetic Identity Detection:Fraud detection solutions attract disproportionate capital as digital channels proliferate synthetic identity schemes across property and casualty lines.
- Telematics Integration:Computer vision converging with vehicle telematics is accelerating underwriting automation for auto coverage in Shanghai and Shenzhen insurtech clusters.
- Dual Carbon Goals:China's national emissions targets are tightening compliance requirements for automated agricultural risk assessment systems tied to climate-linked policies.
Market Restraints
- Algorithm Registration Burden:SAMR filing timelines and MIIT deep synthesis provisions create documentation overhead that slows product rollouts for automated decision systems.
- Talent Concentration Risk:AI engineering expertise clusters disproportionately in Shanghai and Shenzhen, inflating compensation costs for insurers operating outside these hubs.
- Human-in-the-Loop Mandates:National insurance regulator protocols requiring manual review for claims above specified thresholds constrain full automation in high-value segments.
Strategic Opportunities
- Rural Agricultural Coverage:Satellite imagery combined with predictive analytics offers underpenetrated penetration for crop and livestock policies in inland provinces.
- Embedded Distribution:Transaction data ecosystems enable seamless policy origination at point-of-sale across e-commerce and mobility platforms.
- Multimodal Claim Intake:Voice transcription layered with image recognition creates differentiation in customer service workflows for health and accident lines.
Industry Challenges
- Interpretability Engineering:Documenting model decision pathways for regulatory filings demands specialized machine learning operations talent that insurers struggle to retain.
- Legacy Core Integration:Policy administration systems built on decades-old architectures resist API-based connectivity with cloud-native AI engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China AI in Insurance Market |
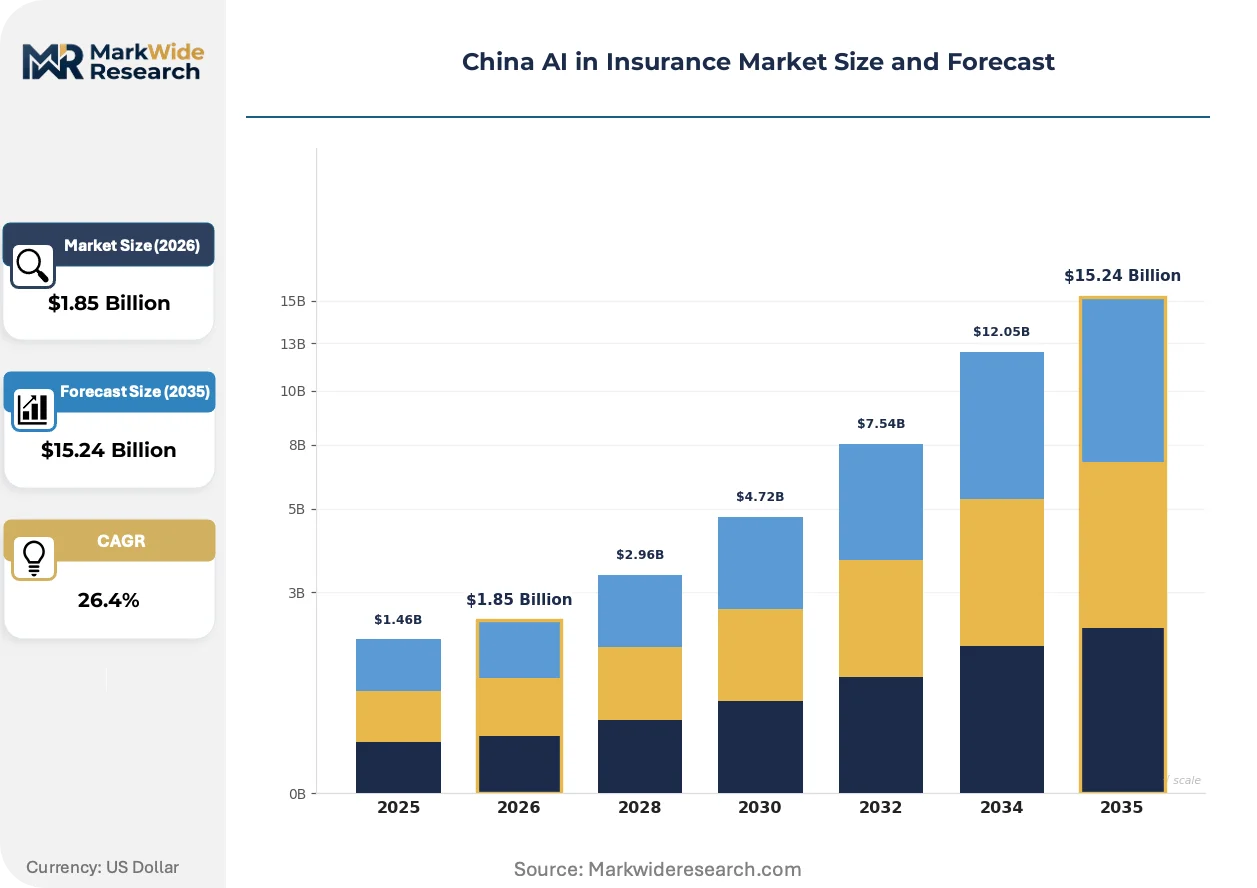
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Chatbots, Fraud Detection, Underwriting Automation, Risk Assessment End User: Insurance Agents, Brokers, Insurers, Underwriters Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Computer Vision Application: Claims Processing, Customer Service, Policy Management, Data Analytics |
| Companies Covered | Ping An Insurance, ZhongAn Online P&C Insurance, Ant Insurance Services, PICC, China Life, China Pacific, Sunshine Insurance, Tencent WeSure, Zhibao Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China AI in Insurance Market Trends and Innovations
Natural language processing capabilities are maturing fastest in customer-facing applications, while competitive differentiation shifts toward multimodal systems and regulatory-compliant model architectures.
Large language models fine-tuned on insurance documentation are absorbing underwriting workloads previously handled by human analysts. Life and health insurers deploy these systems to extract medical history from unstructured clinical notes. The technology is absorbing routine risk classification tasks, compressing actuarial staffing ratios at digital-native carriers.
MIIT deep synthesis provisions and SAMR algorithm registration requirements are reshaping product development standards for automated underwriting. Insurers must now maintain audit trails for training data sourcing and model versioning. Health and property lines face the steepest compliance recalibration as these rules expand beyond pilot sandbox approvals.
Buyer procurement of AI underwriting engines is consolidating around single-vendor relationships rather than fragmented point solutions. Mid-tier insurers abandon multi-source integrations in favor of unified platforms with embedded compliance tooling. This pattern concentrates most visibly in Shenzhen, where regulatory sandbox participants prioritize streamlined vendor management over best-of-breed component assembly.
China AI in Insurance Market Segmentation
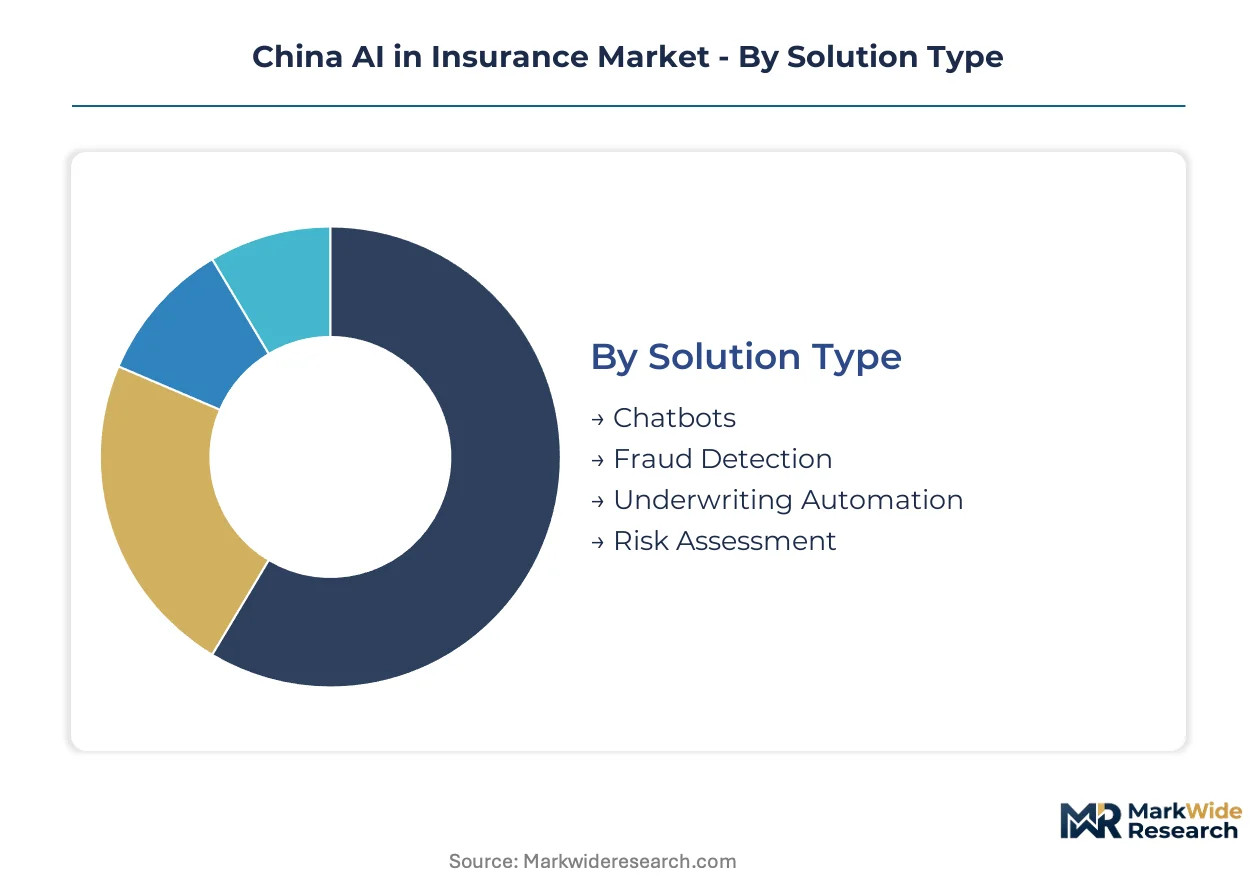
AI deployment patterns across China's insurance sector diverge sharply between high-volume, low-margin automation and premium-priced decision systems requiring regulatory-grade interpretability. Solution architecture, end-user workflow integration, and underlying technology stack each create distinct procurement criteria and vendor selection pressures.
Solution Type:
Volume concentration sits with fraud detection and customer-facing automation, while premium pricing attaches to underwriting engines requiring SAMR algorithm registration compliance.
- Fraud Detection:Pattern recognition systems analyze transaction anomalies and synthetic identity markers across digital distribution channels. P&C insurers in Shanghai deploy these most aggressively as digital-first distribution expands fraud exposure.
- Underwriting Automation:Risk classification engines process structured policy data and unstructured medical documentation to generate actuarial decisions within seconds. Computer vision integration with telematics is climbing the fastest for auto coverage in Shenzhen insurtech clusters.
- Chatbots:Natural language processing systems handle policy inquiries and claim status updates through WeChat and proprietary app interfaces.
- Risk Assessment:Predictive models evaluate climate-linked agricultural exposure and health policy mortality tables using satellite imagery and electronic health records.
Mature deployment sits with Fraud Detection. Newer deployment is concentrated in Underwriting Automation.
End User:
Procurement authority fragments across distribution intermediaries seeking workflow efficiency and carriers pursuing core system replacement.
- Insurers:Direct carriers commission proprietary model development and cloud-native policy administration platforms. Ping An Insurance anchors this segment through captive cloud infrastructure and vertical integration across life and health lines.
- Brokers:Independent intermediaries license third-party comparison tools and automated quote generation to compress placement timelines. ZhongAn Online P&C Insurance competes here through fully digital-native policy administration.
- Insurance Agents:Individual producers adopt mobile-first client onboarding and commission tracking applications.
- Underwriters:Technical risk specialists deploy augmented decision support for complex commercial and specialty lines requiring manual judgment.
Procurement maturity clusters with Insurers. Technology refresh cycles concentrate among Brokers.
Technology:
Stack selection determines regulatory filing burden and talent acquisition costs, with interpretability requirements favoring certain architectures over others.
- Machine Learning:Supervised and unsupervised algorithms power risk scoring, pricing optimization, and retention prediction. Gradient-boosted frameworks dominate structured data applications where decision trees satisfy SAMR explainability mandates.
- Natural Language Processing:Text extraction and sentiment analysis systems process clinical notes, accident reports, and customer correspondence. Large language models fine-tuned on insurance documentation are gaining share fastest for medical history extraction in life and health lines.
- Computer Vision:Image recognition systems assess vehicle damage, property conditions, and agricultural crop health from satellite and mobile capture.
- Predictive Analytics:Statistical forecasting models project claims frequency, severity, and reserve adequacy using historical loss triangles.
Regulatory-ready deployment concentrates in Machine Learning. Experimental adoption is expanding most quickly in Natural Language Processing.
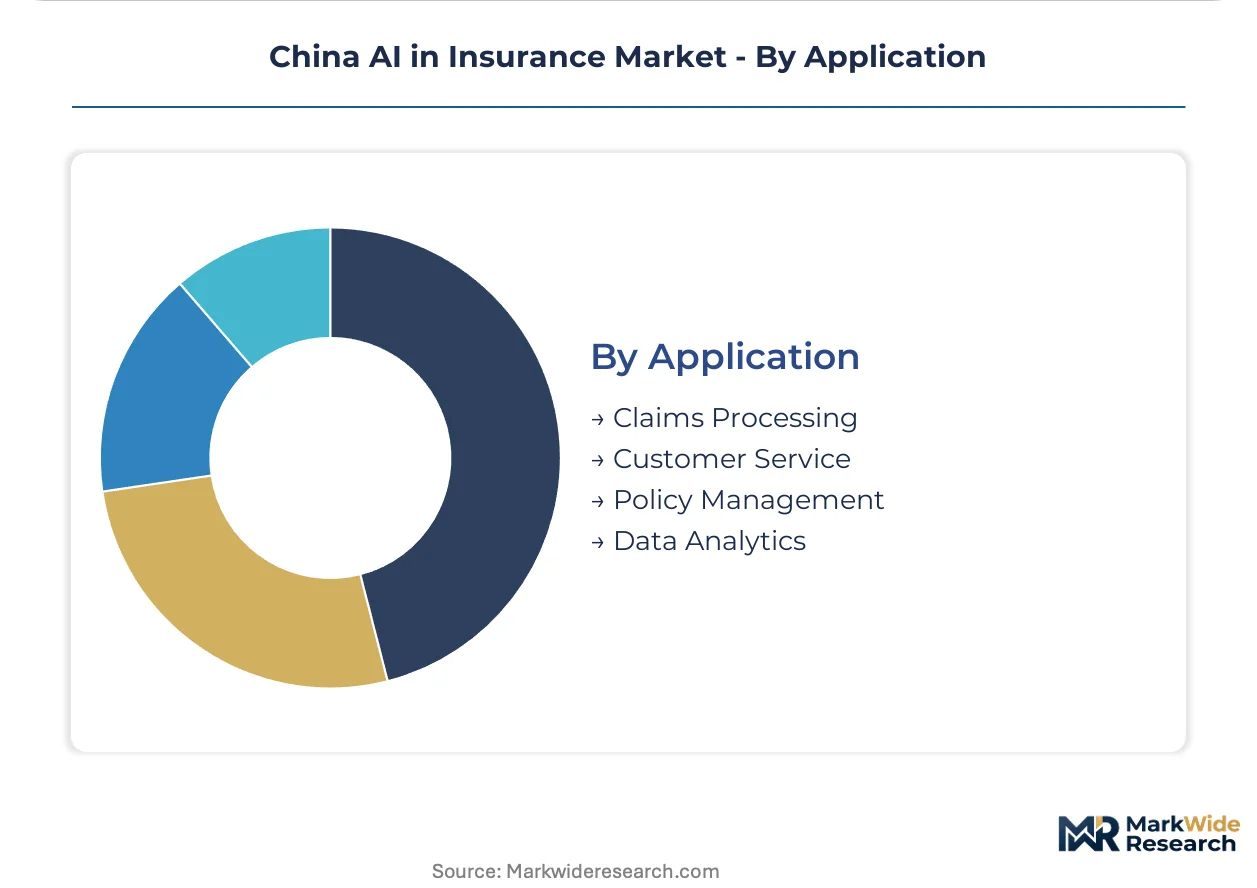
Application:
Workflow automation priority reflects margin pressure and customer experience investment cycles across policy lifecycle stages.
- Claims Processing:Intelligent intake, damage assessment, and payment authorization systems compress cycle times from days to hours. MIIT deep synthesis provisions force documentation of training data provenance for automated adjudication above regulatory thresholds.
- Customer Service:Omnichannel interaction platforms integrate voice transcription with image recognition for multimodal claim reporting. Ant Insurance Services extends embedded distribution through Alipay's transaction data ecosystem in this layer.
- Policy Management:Endorsement processing, renewal pricing, and lapse prediction automate administrative workflows.
- Data Analytics:Business intelligence dashboards aggregate portfolio performance and regulatory reporting for actuarial and compliance functions.
Operational scale sits with Claims Processing. Competitive differentiation is concentrating in Customer Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI engineering talent concentrates in coastal technology corridors where regulatory sandbox approvals and cloud infrastructure density enable rapid model deployment.
Yangtze River Delta
Shanghai anchors the nation's densest insurtech cluster, with MIIT algorithm governance rules driving compliance investment among property and casualty carriers. SAMR registration mandates force documented training data provenance for automated underwriting systems deployed across life and health lines. The city's Lujiazui financial district hosts concentrated engineering teams building multimodal claim intake platforms.
Pearl River Delta
Shenzhen's hardware-software convergence accelerates computer vision integration with vehicle telematics for auto coverage automation. Dual carbon goals tighten compliance requirements for climate-linked agricultural risk assessment systems trialed in adjacent Guangdong prefectures. Tencent WeSure leverages the city's embedded distribution ecosystem through transaction data partnerships.
Beijing-Tianjin-Hebei
The capital's regulatory proximity shapes national insurance regulator protocols requiring human-in-the-loop review for high-value claims. State-backed carriers commission proprietary model development through captive cloud infrastructure. Zhongguancun technology corridor attracts NLP engineering talent for medical history extraction systems.
Sichuan-Chongqing
Inland demand for rural agricultural coverage drives satellite imagery deployment for crop and livestock policies. Talent concentration risk inflates compensation costs as AI engineers remain scarce outside coastal hubs. Provincial regulators pilot streamlined algorithm filing timelines for automated underwriting in underpenetrated markets.
China AI in Insurance Market Competitive Landscape
Global technology platforms compete with domestic insurance conglomerates across distribution infrastructure and proprietary data assets. Market structure tilts toward vertical integration, with carriers building captive cloud capabilities rather than licensing third-party engines. Three archetypes dominate: state-backed incumbents with regulatory relationships, digital-native insurers with embedded distribution, and technology platforms extending financial services. Competitive moves concentrate on M&A for engineering talent and strategic partnerships for data access.
Among domestic insurance conglomerates, Ping An Insurance anchors the proprietary infrastructure tier through captive cloud development across life and health lines. ZhongAn Online P&C Insurance exemplifies the digital-native archetype with fully automated policy administration. Ant Insurance Services occupies the platform-extension position, leveraging transaction data ecosystems for embedded distribution at point-of-sale.
| Leading Market Players |
|---|
| Ping An Insurance |
| ZhongAn Online P&C Insurance |
| Ant Insurance Services |
| PICC |
| China Life |
| China Pacific |
| Sunshine Insurance |
| Tencent WeSure |
| Zhibao Technology |
| Others |
Pricing and Supply Chain Analysis
Cloud compute pricing indices from Alibaba Cloud and Huawei Cloud cascade through AI insurance procurement tiers, compressing margins for mid-tier insurers while concentrating premium pricing power among carriers with captive infrastructure. MIIT algorithm governance compliance costs feed directly into SaaS licensing structures, separating bundled regulatory-ready platforms from unbundled point solutions.
Pricing Analysis
Service-bundling separates compliance-ready underwriting engines with embedded SAMR registration tooling from stripped-down API offerings lacking audit trail documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with MIIT-registered platforms commanding substantial markups over unregistered alternatives. Pricing pressure stems from consolidation in procurement patterns as insurers abandon multi-vendor fragmentation. Tier-three domestic carriers exhibit highest price sensitivity, while state-backed incumbents absorb premium tiers for proprietary development.
Supply Chain Analysis
Direct-to-carrier channels handle hyperscale demand from Ping An and China Life, while broker-mediated distribution serves mid-tier insurers lacking internal engineering capacity. GPU and specialized AI accelerator supply concentrates in Taiwan, South Korea, and mainland China fabs. Training data sourcing draws from domestic electronic health record systems, satellite imagery providers, and vehicle telematics platforms. Single-source vulnerability sits with NVIDIA datacenter GPU allocation, where export restrictions tighten availability for model training clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large language models fine-tuned on insurance documentation are displacing rule-based underwriting systems, compressing actuarial staffing ratios and forcing legacy core replacement decisions across the sector.
For Market Incumbents: Lock in proprietary cloud infrastructure to anchor model development against Ant Insurance Services' data ecosystem expansion. Prioritize MIIT algorithm registration for core underwriting engines before sandbox approvals narrow. Consolidate vendor relationships around unified platforms with embedded compliance tooling to reduce fragmentation overhead.
For New Entrants and Emerging Players: Embedded distribution partnerships through Alipay and WeChat Pay channels offer lowest-friction customer acquisition for digital-native carriers. Target rural agricultural coverage in Sichuan and Chongqing, where satellite imagery deployment lags coastal sophistication. Lead with multimodal claim intake combining voice transcription with image recognition to differentiate customer experience.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier insurers with stranded legacy core systems but intact regulatory licenses in inland provinces. Long-term viability hinges on successful cloud migration and AI underwriting engine deployment within the next technology refresh cycle. Watch MIIT sandbox expansion criteria as inflection signal for compliance-ready product rollout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cloud Infrastructure Buildout | Ping An's captive development anchors model training capacity outside third-party GPU allocation constraints. |
| MIIT Algorithm Registration Completion | SAMR filing timelines determine product rollout sequencing for automated underwriting systems. |
| Embedded Distribution Partnership | Ant Insurance Services leverages Alipay transaction data for point-of-sale policy origination. |
| Multimodal Claim Intake Deployment | Voice transcription layered with image recognition differentiates customer service in health lines. |
| Rural Agricultural Coverage Expansion | Satellite imagery combined with predictive analytics penetrates underinsured crop and livestock markets. |
Research Methodology
MIIT regulatory filings, SAMR algorithm registration databases, and insurer technology procurement disclosures formed the secondary backbone, cross-referenced against primary interviews with chief technology officers at domestic carriers, MIIT sandbox program administrators, and AI engineering leads at Ping An Cloud and ZhongAn Online. Conversations with agricultural insurance underwriters in Sichuan and health line actuaries in Shanghai validated deployment patterns. Bottom-up model counts triangulated against top-down market sizing from regulatory capital disclosure filings.
Historical trendline analysis of algorithm registration volumes and cloud infrastructure capex informed projection frameworks across the modeling period. Segmentation dimensions modeled include solution type, end-user procurement authority, technology stack architecture, and application workflow stage. CAGRs derived from fitted growth curves adjusted for regulatory filing timeline constraints. Forecast inputs incorporated MIIT sandbox expansion criteria and dual carbon goal compliance deadlines for climate-linked agricultural systems.
The model holds under stable regulatory filing timelines; deviation in MIIT algorithm governance enforcement intensity or GPU export restriction expansion would shift deployment velocity assumptions. Forecasts reflect documented base conditions around talent concentration in Shanghai and Shenzhen. Periodic stress-testing of base assumptions is recommended against regulatory sandbox admission criteria evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
North America Insurtech Market
Insurance Technology
UK Insurtech Market