
 P and C Insurance Software Market | 2026-2036
P and C Insurance Software Market Size, Share, and Industry Trends Forecast 2026-2036
P and C Insurance Software Market Analysis
The capital-intensity divergence between legacy platform maintainers and cloud-native challengers is rotating competitive dynamics across the sector. Guidewire Software leverages its installed base of tier-one carriers to sustain renewal revenue. Duck Creek Technologies competes through modular architecture that accelerates deployment timelines for mid-market insurers.
Property and casualty insurance software encompasses integrated digital platforms that automate policy lifecycle management, claims adjudication, and premium billing through configurable rules engines and API-first architectures. These systems process underwriting decisions in milliseconds while maintaining statutory reserve calculations and reinsurance treaty compliance. Claims Management commands the largest share of current spending as carriers modernize legacy COBOL-based systems. Cloud-Based deployment is expanding fastest as insurers exit data center obligations. Artificial Intelligence integration within Underwriting Solutions represents the highest-margin growth pocket for vendors.
US state insurance departments enforce NAIC model laws on data security and producer licensing that elevate compliance module requirements. The EU AI Act and GDPR impose algorithmic transparency standards on automated underwriting engines sold into European markets. Stakeholders must evaluate whether their technology roadmaps accommodate divergent regulatory trajectories across jurisdictions.
Market Dynamics
Cloud migration mandates from US state insurance departments are forcing carriers to accelerate core system replacement timelines, compressing vendor selection cycles and elevating API-first architectures over monolithic legacy platforms.
Growth Catalysts
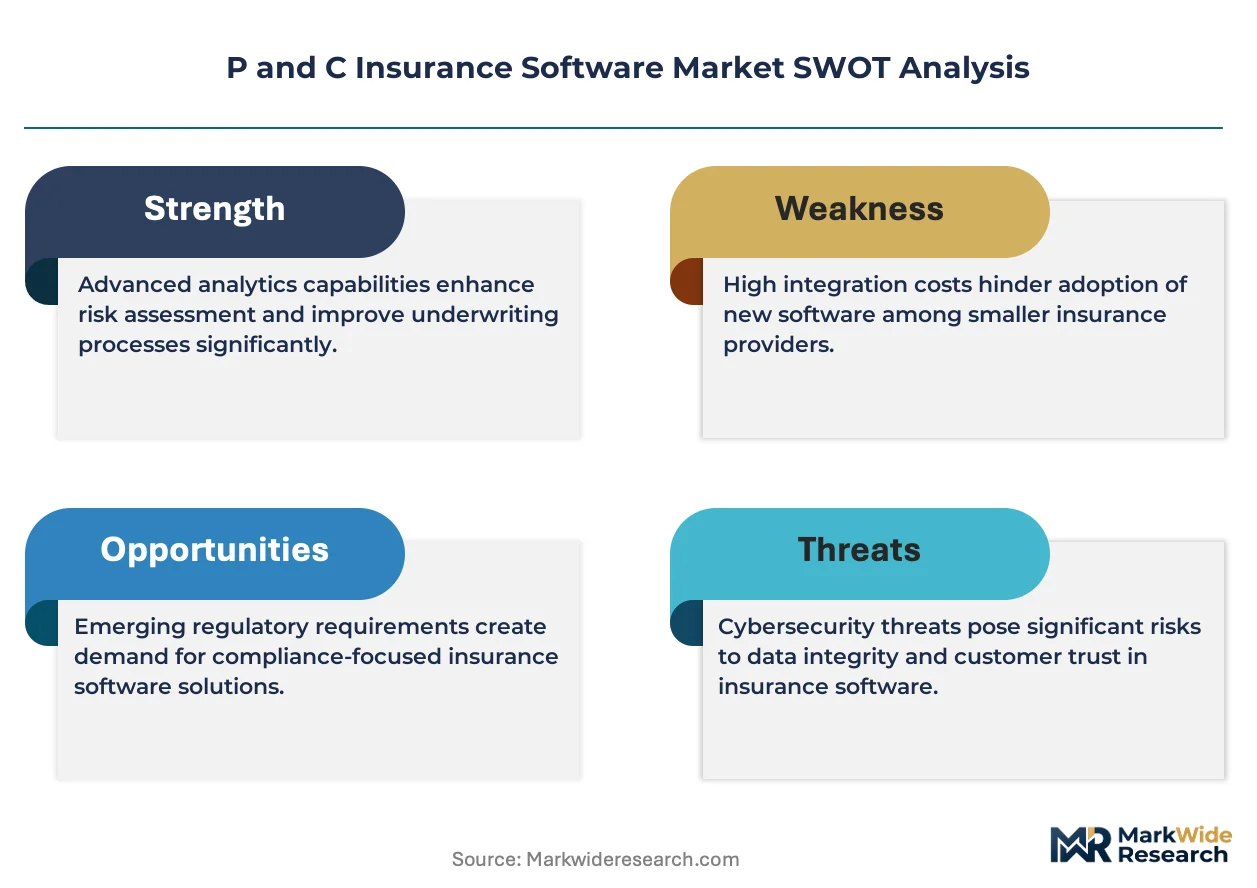
- NAIC Model Laws on Data Security:US state insurance departments enforce stringent cybersecurity frameworks that mandate modernized policy administration systems with embedded compliance modules.
- Claims Modernization:Carriers replace COBOL-based claims engines with real-time adjudication platforms to reduce loss adjustment expense ratios and improve customer retention.
- Mid-Market Insurer Expansion:Regional carriers in the United States invest in modular policy administration to compete against national tier-one carriers on speed-to-market.
Market Restraints
- Legacy Data Migration Complexity:Decades of policy and claims data trapped in proprietary formats create technical debt that extends implementation timelines.
- Specialized Talent Scarcity:Shortage of professionals fluent in both insurance domain knowledge and cloud-native architecture drives implementation costs upward.
- Reinsurance Treaty Integration:Complex multi-party cession calculations require custom development that resists standardization across vendor platforms.
Strategic Opportunities
- Artificial Intelligence in Underwriting:Machine learning models for risk scoring and pricing optimization represent high-margin expansion for vendors with proprietary data assets.
- Embedded Insurance Distribution:API-first platforms enable direct integration into automotive, real estate, and e-commerce transaction flows.
- EU AI Act Compliance Services:Algorithmic transparency requirements for automated underwriting create advisory and tooling revenue streams for vendors serving European markets.
Industry Challenges
- Core System Integration Friction:Carriers struggle to synchronize new cloud platforms with existing billing, reinsurance, and statutory reporting systems without operational disruption.
- Actuarial Model Validation:State regulators require extensive documentation of predictive model governance, extending deployment timelines for AI-enabled pricing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P and C Insurance Software Market |
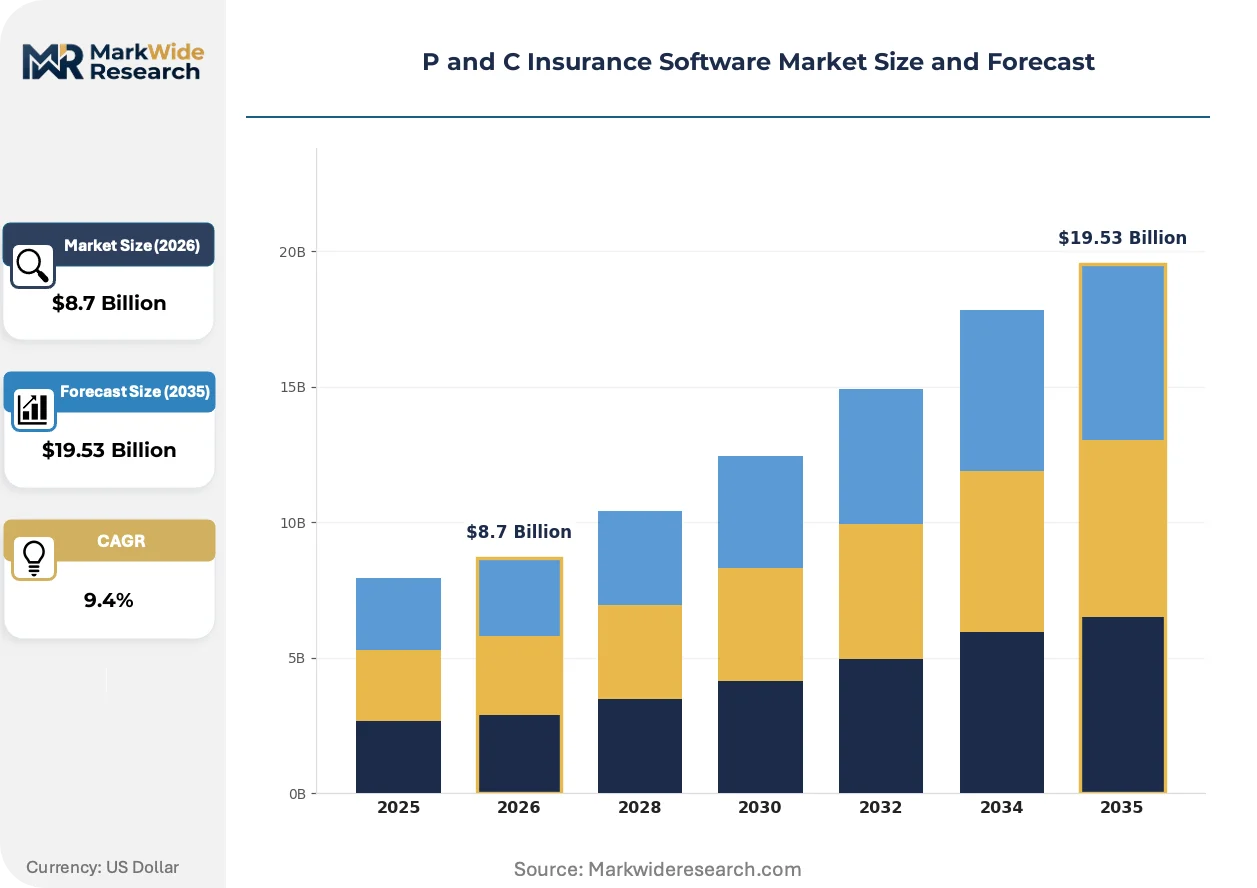
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Claims Management, Policy Administration, Underwriting Solutions, Billing Systems End User: Small Enterprises, Medium Enterprises, Large Corporations, Brokers Deployment: Cloud-Based, On-Premises, Hybrid Solutions, SaaS Technology: Artificial Intelligence, Machine Learning, Blockchain, IoT |
| Companies Covered | Guidewire Software, Duck Creek Technologies, Salesforce, Microsoft, Sapiens, Majesco, Insurity, Applied Systems, WTW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P and C Insurance Software Market Emerging Trajectories
Competitive dynamics in property and casualty insurance software are fragmenting along deployment-model lines, with cloud-native architectures gaining preference over on-premise installations among mid-market carriers seeking faster implementation.
Microservices-based policy administration platforms are bifurcating the vendor landscape between comprehensive suite providers and specialized point-solution vendors. Tier-one carriers favor end-to-end platforms with unified data models, while regional insurers adopt best-of-breed components for underwriting, claims, and billing. This architectural divergence is compressing pricing power for monolithic legacy vendors and expanding addressable market for API-first challengers.
The EU AI Act imposes algorithmic transparency standards on automated underwriting engines sold into European markets. Vendors must document model training data, decision logic, and human oversight protocols to maintain market access. Carriers operating across US and EU jurisdictions face divergent compliance roadmaps that complicate platform standardization strategies.
Subscription pricing for software-as-a-service platforms is displacing perpetual license models among mid-market insurers seeking to convert capital expenditure to operational expenditure. Vendors respond with tiered consumption-based contracts tied to policy volume or claims throughput. This shift is most pronounced among regional mutual insurers and managing general agents in the United States prioritizing cash flow flexibility over long-term cost optimization.
P and C Insurance Software Market Segmentation
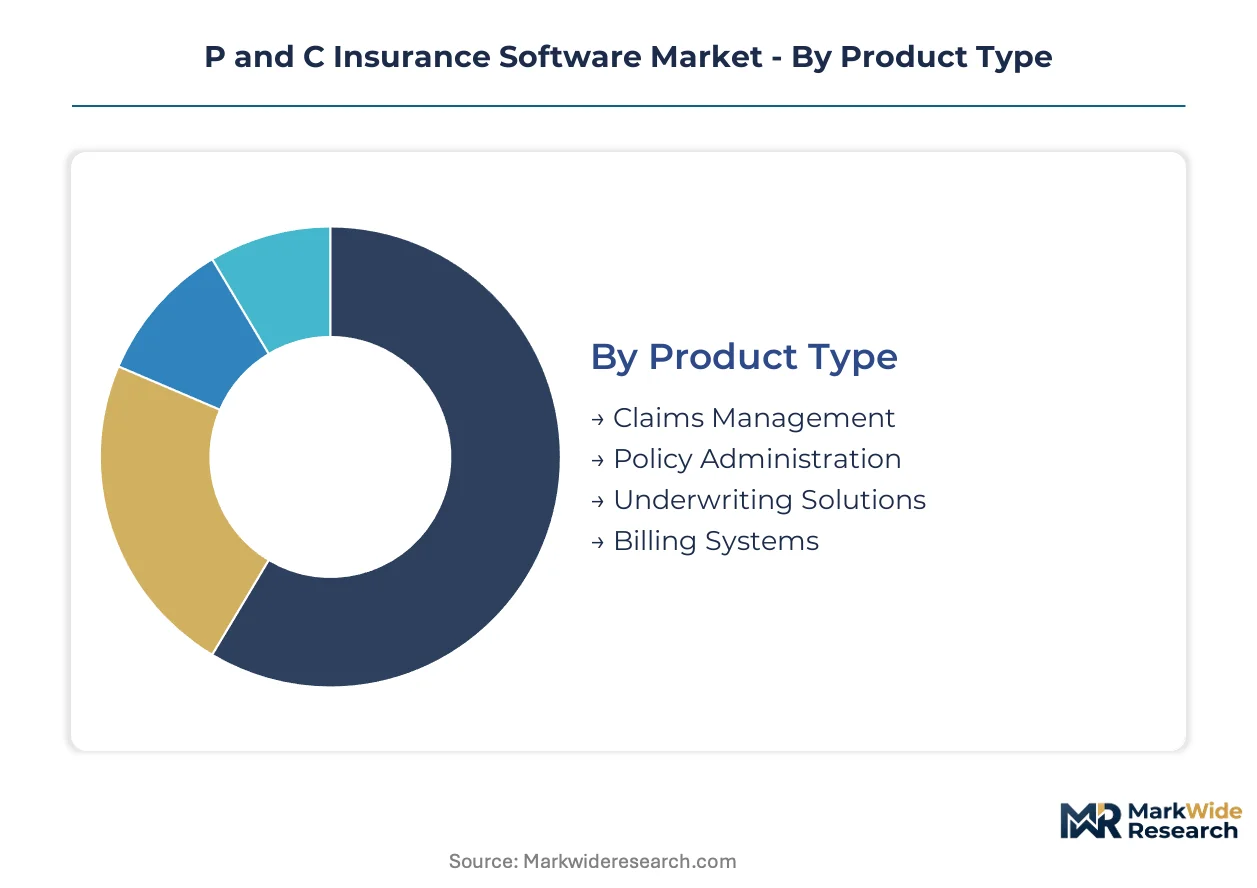
Segmentation in property and casualty insurance software reveals how regulatory mandates, carrier scale, and technology maturity create divergent purchasing patterns across the market. Understanding these divisions enables vendors to align product roadmaps with the specific compliance and operational pressures facing each buyer category.
Product Type:
NAIC model laws on data security and state-level cloud migration mandates are reshaping which modules carriers prioritize in replacement cycles, with compliance-heavy functions attracting investment ahead of ancillary tools.
- Claims Management:Real-time adjudication platforms process loss notifications through configurable rules engines that integrate with third-party data providers for fraud detection. Large corporations in the United States dominate procurement as they modernize COBOL-based legacy systems to reduce loss adjustment expense ratios and improve retention metrics. Established volume favors Claims Management; emerging adoption favors Underwriting Solutions.
- Policy Administration:Core systems managing policy lifecycle from quote through renewal, featuring product configurator tools and rating engines that adapt to state-specific filing requirements. Mid-market insurers in the United States are accelerating purchases to compete with national carriers on speed-to-market for new products.
- Underwriting Solutions:Risk scoring and pricing optimization platforms incorporating predictive models and external data ingestion for automated decisioning.
- Billing Systems:Premium collection and commission management modules with statutory reserve calculation capabilities and producer licensing compliance.
Carriers with legacy technical debt concentrate spending on Claims Management and Policy Administration, while digitally mature insurers prioritize Underwriting Solutions for competitive differentiation.
End User:
Organizational scale determines deployment complexity tolerance and integration requirements, with procurement patterns diverging sharply between capital-constrained regional players and national carriers with dedicated IT functions.
- Large Corporations:Tier-one national carriers and multi-line insurers requiring end-to-end platforms with unified data models, extensive customization, and dedicated vendor support structures. These buyers in the United States command the largest share of current spending as they execute multi-year core system replacement programs mandated by state insurance departments.
- Medium Enterprises:Regional carriers and mutual insurers seeking modular architectures that accelerate implementation timelines without requiring full-suite commitments. Procurement concentrates among United States-based insurers prioritizing cash flow flexibility through subscription pricing over perpetual license models.
- Small Enterprises:Managing general agents and niche program administrators with limited IT staff requiring pre-configured, rapid-deployment solutions.
- Brokers:Independent agents and brokerage networks needing connectivity tools for carrier submission and policy servicing rather than full administration platforms.
Vendor resources flow toward Large Corporations for revenue concentration; product innovation targets Medium Enterprises for expansion velocity.
Deployment:
Capital structure preferences and state regulatory timelines are rotating the competitive landscape away from perpetual license models toward consumption-based contracts.
- Cloud-Based:Fully managed infrastructure eliminating data center obligations, with automatic updates ensuring continuous compliance with evolving NAIC cybersecurity frameworks. United States state insurance departments are accelerating mandates that force carriers toward this model, compressing vendor selection cycles and elevating API-first architectures.
- SaaS:Software-as-a-service delivery with tiered consumption contracts tied to policy volume or claims throughput, converting capital expenditure to operational expenditure. Regional mutual insurers in the United States prioritize this option for cash flow flexibility.
- On-Premises:Legacy-installed systems maintained within carrier-owned data centers, still prevalent among insurers with specialized security requirements or complex reinsurance treaty integrations.
- Hybrid Solutions:Mixed deployments separating sensitive data on-premise while leveraging cloud scalability for compute-intensive functions like predictive modeling.
Established infrastructure commitments sustain On-Premises revenue; regulatory pressure and financial flexibility are driving Cloud-Based expansion most aggressively.
Technology:
Integration maturity and data asset availability determine which emerging technologies deliver measurable underwriting and claims outcomes versus experimental investment.
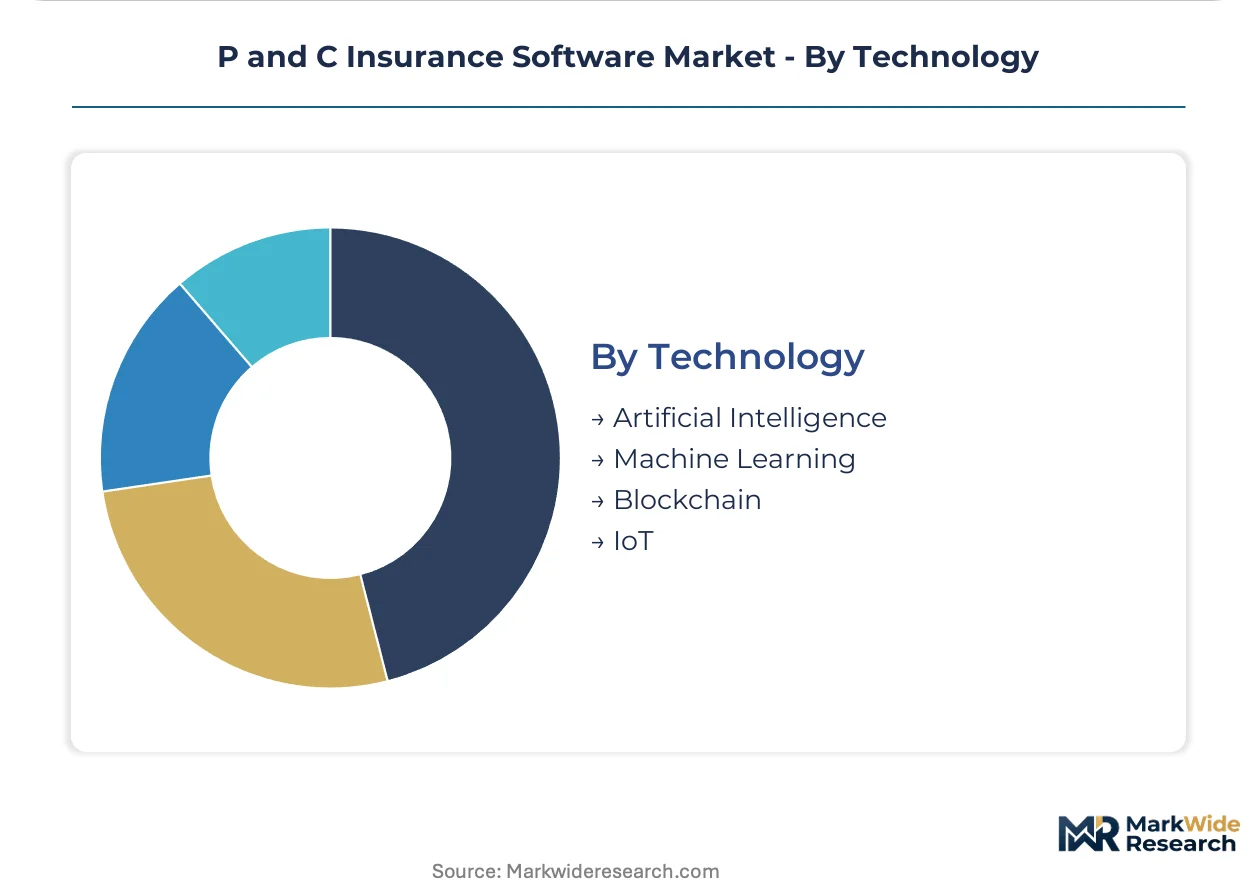
- Artificial Intelligence:Automated underwriting engines and claims triage systems requiring extensive documentation of model governance for state regulator validation. The EU AI Act imposes additional algorithmic transparency standards on vendors selling into European markets, creating compliance service opportunities. Large United States carriers concentrate demand as they seek high-margin pricing optimization capabilities.
- Machine Learning:Predictive models for risk scoring, fraud detection, and customer retention that improve with proprietary claims data accumulation.
- Blockchain:Distributed ledger applications for smart contract automation in parametric insurance and reinsurance settlement.
- IoT:Sensor data integration from connected vehicles, property monitoring devices, and industrial equipment enabling usage-based pricing and real-time risk intervention.
Proprietary data advantages favor Artificial Intelligence adoption among data-rich incumbents; sensor infrastructure buildout is accelerating IoT deployment in commercial auto and property lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers consume P and C insurance software as end-to-end policy administration platforms, while European buyers prioritize modular compliance solutions for algorithmic transparency mandates. This consumption-mix differential shapes vendor product roadmaps and deployment timelines across jurisdictions.
United States
State insurance departments in California, New York, and Texas enforce cloud migration mandates that compress vendor selection cycles. NAIC model laws on data security elevate compliance module requirements for policy administration systems. The Hartford insurance cluster and Boston-Washington corridor concentrate procurement among tier-one carriers executing multi-year core system replacements.
Germany
Munich Re and Allianz anchor demand for reinsurance treaty integration capabilities within vendor platforms. The EU AI Act imposes algorithmic transparency standards on automated underwriting engines sold into German markets. The Frankfurt-Rhine-Main financial center drives procurement concentration for predictive pricing optimization tools.
United Kingdom
Lloyd's of London and specialty carriers in the City prioritize real-time claims adjudication platforms with fraud detection integration. GDPR compliance requirements shape data architecture decisions for policy lifecycle management systems. The London insurance market cluster sustains demand for configurable rules engines serving complex commercial lines.
Japan
Tokio Marine and Sompo Holdings drive adoption of IoT-enabled usage-based pricing platforms for commercial auto and property lines. METI guidelines on digital transformation accelerate cloud migration timelines for regional insurers. The Tokyo-Osaka corridor concentrates implementation of microservices-based policy administration among mid-market mutual carriers.
India
IRDAI regulations on digital-first insurance distribution expand addressable market for API-first platforms among managing general agents. The PLI scheme for technology adoption subsidizes core system modernization for public sector insurers. Bengaluru and Mumbai financial technology clusters incubate indigenous policy administration vendors targeting regional carriers.
P and C Insurance Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the P and C insurance software market, with concentration highest among suite providers serving tier-one carriers. The integrated tier commands premium pricing through unified data models and dedicated support structures, while specialists compete on deployment velocity and modular flexibility. Two strategic archetypes dominate: comprehensive suite vendors with decades of installed-base relationships, and API-first challengers with cloud-native architectures. Competitive moves center on strategic partnerships for embedded insurance distribution and technology licensing arrangements for AI-enabled underwriting capabilities.
Within the integrated suite tier, Guidewire Software and Duck Creek Technologies exemplify divergent architectural approaches to carrier scale segmentation. Guidewire occupies a position serving national tier-one carriers with extensive customization requirements, while Duck Creek sits within the mid-market acceleration segment through modular deployment options. Salesforce represents the platform-extender archetype, leveraging horizontal cloud infrastructure to capture ancillary insurance workflows outside core policy administration. These three anchors illustrate how vendor positioning stratifies across carrier IT maturity and capital structure preferences.
| Leading Market Players |
|---|
| Guidewire Software |
| Duck Creek Technologies |
| Salesforce |
| Microsoft |
| Sapiens |
| Majesco |
| Insurity |
| Applied Systems |
| WTW |
| Others |
Supply Flow & Price Mechanics
Implementation timelines stretching 18-24 months for tier-one carriers concentrate pricing power with established suite vendors while compressing margins for challengers forced to absorb integration complexity. This lead-time band reinforces contract structures that favor long-term SaaS commitments over transactional models.
Pricing Analysis
Contract structures in P and C insurance software gravitate toward multi-year SaaS subscriptions with consumption-based tiers tied to policy volume or claims throughput. Price differentiation separates comprehensive suite providers commanding premium rates for unified data models from modular vendors competing on deployment velocity. Pricing pressure stems from mid-market insurers converting capital expenditure to operational expenditure, squeezing perpetual license revenue. Regional mutual carriers exhibit highest price sensitivity, while national tier-one carriers prioritize customization depth over unit cost.
Supply Chain Analysis
Inventory of implementation capacity—measured in certified consultant availability and cloud infrastructure provisioning—runs 90-120 days for specialized insurance-technology expertise. Supply concentrates in the United States, India, and Ireland, where vendor development centers and system integrator ecosystems cluster. Raw material dependencies include hyperscaler compute capacity, proprietary claims data repositories, and regulatory compliance documentation frameworks. Single-source vulnerability attaches to cloud infrastructure providers dominating carrier hosting obligations. Distribution runs through direct enterprise sales teams and certified implementation partners serving carrier IT procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in switching costs: decades of policy data locked in proprietary formats and multi-year implementation cycles erect barriers that protect incumbent positions against displacement.
For Market Incumbents: Secure renewal revenue through embedded AI modules that deepen platform stickiness, and extend vertical integration into data services that carriers cannot replicate internally. Cloud-native challengers with API-first architectures threaten mid-market share; respond by acquiring specialist underwriting analytics firms to fill capability gaps. Certification investment in NAIC compliance automation reinforces regulatory entrenchment against modular competitors. For New Entrants and Emerging Players: Fast-tracked SOC 2 Type II and state insurance department certification pathways open procurement doors to regional mutual insurers bypassed by tier-one vendors. White-space concentrates in embedded insurance distribution APIs for automotive and real estate transaction flows, and in EU AI Act compliance tooling for carriers with European exposure. Go-to-market through managing general agents with pre-configured rapid-deployment solutions circumvents lengthy carrier procurement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because policy administration platforms generate sticky, high-retention cash flows with limited competitive substitution. Acquisition targets should display vertical data assets—proprietary claims histories or underwriting model training sets—that resist replication. Signal to watch: state insurance department cloud migration mandate acceleration compressing vendor selection timelines and elevating implementation capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies policy administration with claims and billing modules, reducing carrier IT fragmentation and integration friction. |
| Strategic Partnership | Aligns with hyperscalers like AWS or Azure to meet state cloud migration mandates and accelerate provisioning timelines. |
| Acquisition of Specialist Firm | Adds AI-enabled underwriting capabilities or EU AI Act compliance tooling to fill product roadmap gaps. |
| Geographic Expansion | Establishes development centers in Bengaluru or Dublin to access insurance-technology talent pools and reduce implementation costs. |
| Product Launch | Introduces microservices-based modules targeting mid-market insurers seeking speed-to-market without full-suite commitments. |
Methodological Framework
Operator-level perspectives from chief information officers at tier-one carriers, mid-market IT directors, system integrator project leads, and state insurance department technology officers anchored the qualitative base for this study. Primary interview insights combined with secondary validation from SEC 10-K filings, NAIC regulatory bulletins, and hyperscaler cloud revenue disclosures. Bottom-up triangulation across vendor contract values and top-down reconciliation against carrier IT spending estimates ensured cross-verification of market sizing.
Sensitivity analysis tested forecast outputs against alternative scenarios for cloud migration mandate timing and AI adoption velocity across the projection horizon. Segmentation dimensions modeled include deployment model, carrier scale tier, product module type, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and projected cloud adoption S-curves. Industry-specific inputs incorporated NAIC cybersecurity framework compliance costs and EU AI Act implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued state regulatory pressure for cloud modernization and stable reinsurance treaty complexity; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
UK Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Insurance Software Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
China AI in Insurance Market