
 Europe Insurance Telematics Market | 2026-2036
Europe Insurance Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insurance Telematics Market Foresight
CE marking under the EU Cybersecurity Act for connected vehicle devices is collapsing the vendor landscape for aftermarket telematics hardware. Allianz leverages its captive IoT infrastructure to sustain pricing power in German motor portfolios. Octo Telematics anchors the southern European installed base through embedded OEM partnerships. Admiral competes on consumer-facing app design rather than hardware subsidies.
Europe insurance telematics denotes the integration of telecommunications, vehicular sensors, and data analytics to transmit real-time driving behavior and vehicle status to insurers for dynamic risk pricing and claims adjudication. Systems typically incorporate accelerometers sampling at 100 Hz, GPS modules with sub-5-meter accuracy, and cellular modems operating on LTE-M or NB-IoT protocols to capture braking intensity, cornering force, and mileage accumulation. Smartphone Apps within the Device Type dimension dominate new policy origination due to zero marginal hardware cost, while Black Box Devices retain preference among young-driver segments where court-admissible crash reconstruction carries premium value. Pay-How-You-Drive policies within the Insurance Type category are expanding fastest as behavioral scoring models mature beyond simple mileage proxies.
GDPR enforcement by national data protection authorities and the EU AI Act's risk classification framework for algorithmic insurance pricing are tightening consent architectures and model audit requirements across member states. EIOPA's supervisory convergence mandates on digital distribution are further standardizing disclosure protocols for telematics-enabled contracts. Insurers must now decide whether to build proprietary data lakes or subscribe to federated analytics platforms that preserve policyholder privacy under emerging regulatory interpretations.
Market Dynamics
GDPR enforcement and the EU AI Act are forcing insurers to rebuild consent architectures and algorithmic audit trails, collapsing legacy data collection models while opening paths for privacy-preserving federated analytics.
Growth Catalysts
- Pay-How-You-Drive Policy Maturation:Behavioral scoring models now integrate accelerometer and GPS data streams, enabling granular risk pricing that rewards safe driving with immediate premium reductions.
- EU AI Act Risk Classification:The regulation's high-risk system designation for algorithmic insurance pricing creates compliance-driven demand for auditable telematics platforms with embedded model explainability.
- Mediterranean Smartphone Density:Italy and Spain combine high motor insurance penetration with near-universal smartphone ownership, eliminating hardware friction for app-based policy origination.
Market Restraints
- CE Marking Concentration:The EU Cybersecurity Act's certification requirements for connected vehicle devices are eliminating aftermarket hardware vendors unable to absorb compliance costs, reducing supplier diversity.
- Silicon Supply Bottlenecks:LTE-M and NB-IoT modem chip production concentrates in East Asian foundries, exposing European telematics hardware assemblers to input volatility and extended lead times.
- GPS Accuracy Limitations:Sub-5-meter positioning precision remains insufficient for urban canyon crash reconstruction, constraining liability determination in dense metropolitan environments.
Strategic Opportunities
- Eastern European Underpenetration:Poland and Romania exhibit low telematics adoption despite rising motor insurance density, presenting first-mover advantages for localized app-based distribution.
- Federated Analytics Platforms:Privacy-enhancing computation enables cross-insurer risk pooling without raw data sharing, aligning with EDPB guidance on GDPR-compliant model training.
- OEM Embedded Integration:Factory-installed telematics modules in connected vehicles are displacing aftermarket installation, creating captive data streams for insurers with established automotive partnerships.
Industry Challenges
- Actuarial-AI Talent Scarcity:The intersection of traditional reserving expertise and machine learning engineering remains thinly staffed across European insurer headquarters.
- Legacy PAS Integration:Policy administration systems built for annual renewals require expensive middleware development to ingest real-time telematics data streams and execute dynamic pricing.
- Cross-Border Data Localization:Divergent national interpretations of GDPR's lawful basis for processing create compliance fragmentation for insurers operating across multiple member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insurance Telematics Market |
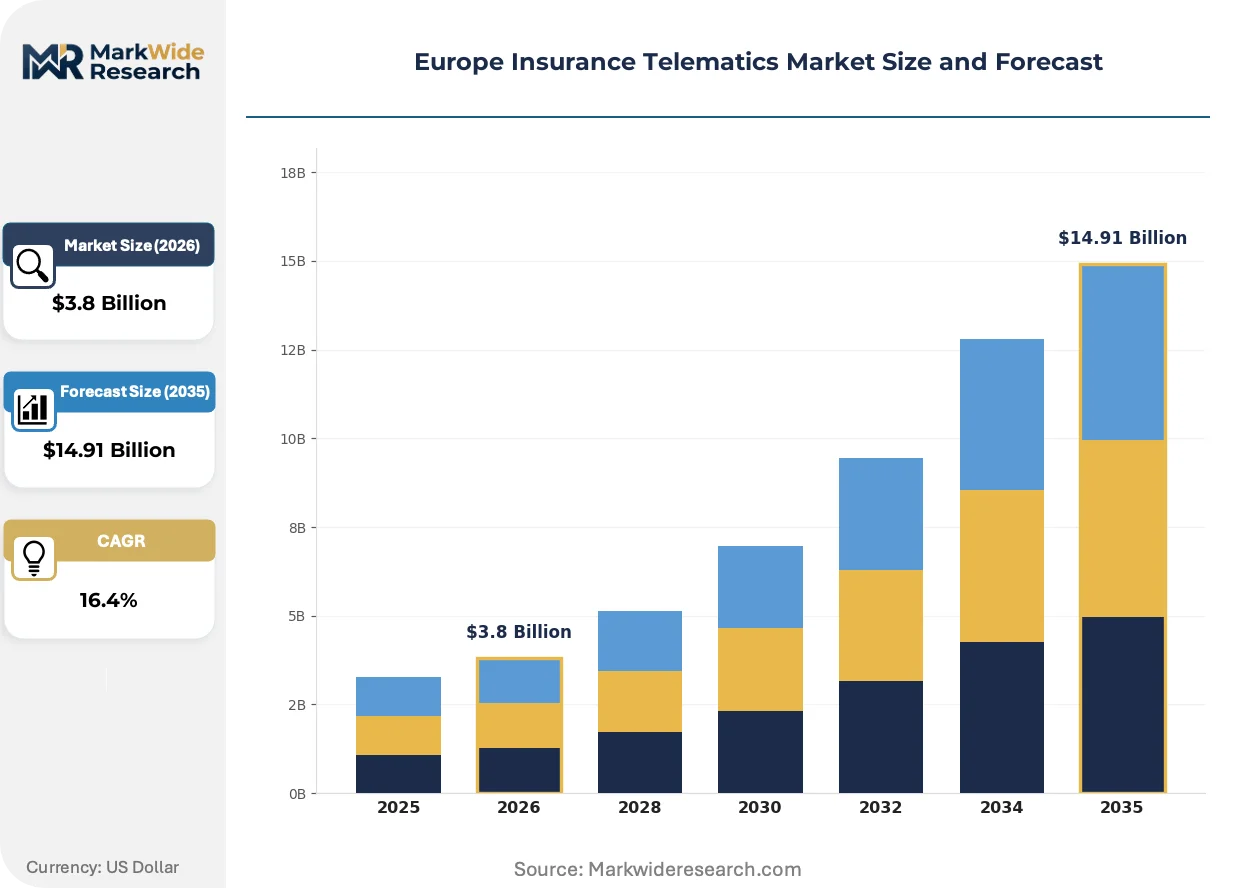
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: OBD Devices, Smartphone Apps, Embedded Systems, Black Box Devices Data Type: Driver Behavior, Vehicle Usage, Location Data, Event Data Insurance Type: Pay-As-You-Drive, Pay-How-You-Drive, Fleet Insurance, Usage-Based Insurance End User: Insurers, Brokers, Fleet Managers, Consumers |
| Companies Covered | Unipol, Generali, Allianz, AXA, Unipolsai Assicurazioni, LexisNexis Risk Solutions, Octo Telematics, Admiral, Direct Line Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insurance Telematics Market Shifts & Advancements
Smartphone-based data collection is compressing hardware economics while regulatory pressure on algorithmic transparency is reshaping competitive advantage toward privacy-preserving infrastructure.
Edge computing on vehicle-mounted devices is displacing cloud-dependent processing architectures for real-time crash detection. Commercial fleet operators in Germany now mandate on-device inference to minimize latency in emergency response protocols. This shift is displacing traditional black-box architectures that rely on cellular uplink for all analytical functions.
The EU AI Act's high-risk system requirements are mandating algorithmic impact assessments for behavioral scoring models. Insurers must now document training data provenance and model drift monitoring protocols before deployment. Mediterranean markets with established telematics penetration are experiencing the steepest compliance adaptation curves as national supervisors issue convergent guidance.
Young-driver segments are rejecting hardware installation mandates in favor of bring-your-own-device app models. Digital-native policyholders in Italy and Spain expect gamified feedback interfaces with immediate premium adjustments. This preference compression is most visible in urban centers where smartphone dependency intersects with high insurance costs for provisional license holders.
Europe Insurance Telematics Market Segmentation
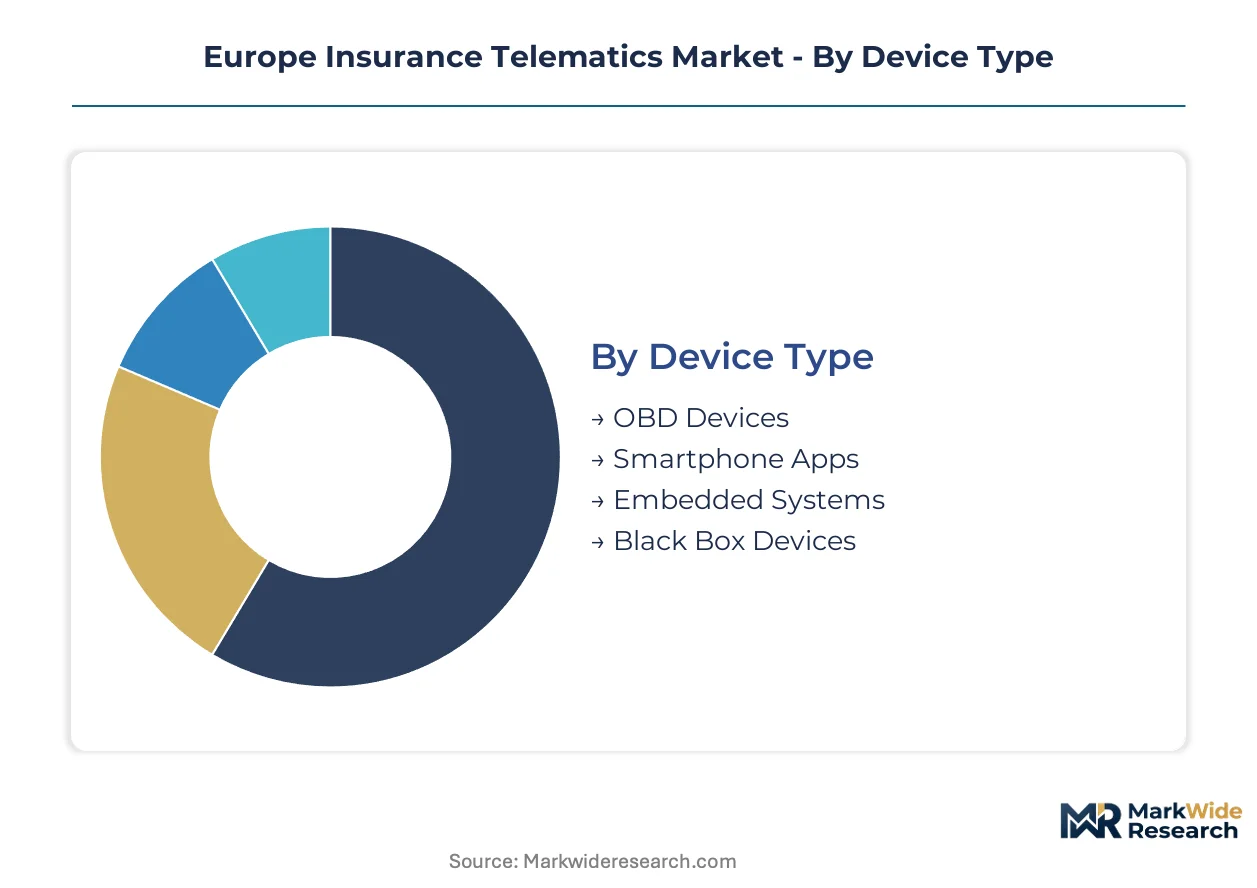
Europe insurance telematics segmentation reveals divergent margin architectures across hardware, data, and distribution layers. Device economics favor software-centric models while insurance product design determines customer lifetime value capture.
Device Type:
Margin pools concentrate in subscription software layers rather than hardware manufacturing, with CE marking compliance costs reshaping vendor profitability curves.
- Smartphone Apps:Zero marginal hardware cost enables rapid policy origination at scale. Italian and Spanish insurers leverage near-universal smartphone penetration to bypass installation friction entirely. Mediterranean markets exhibit the steepest adoption curves as young-driver segments reject physical device mandates.
- Black Box Devices:Court-admissible crash reconstruction capabilities command premium positioning in young-driver and high-risk segments. German and UK insurers absorb higher upfront hardware subsidies in exchange for multi-year policy lock-in and reduced claims litigation costs.
- OBD Devices:Plug-in diagnostics modules capture vehicle health data streams without professional installation.
- Embedded Systems:Factory-installed OEM telematics modules create captive data streams for partnered insurers.
The dominant share belongs to Smartphone Apps, while Embedded Systems is closing the gap fastest through automotive partnership consolidation.
Data Type:
Actuarial value escalates with data granularity, positioning behavioral telemetry above simple mileage verification in pricing sophistication tiers.
- Driver Behavior:Accelerometer and gyroscope streams sampled at 100 Hz enable granular risk scoring through braking intensity, cornering force, and acceleration patterns. GDPR consent architectures and EU AI Act audit requirements are forcing insurers to document provenance and model drift protocols for these high-risk algorithmic systems.
- Location Data:GPS modules with sub-5-meter accuracy enable territory-based risk pricing and theft recovery services. Urban canyon limitations in dense metropolitan environments constrain liability determination precision, creating demand for multi-constellation GNSS augmentation.
- Vehicle Usage:Mileage accumulation and trip frequency support basic Pay-As-You-Drive pricing models with minimal privacy intrusion.
- Event Data:Crash reconstruction telemetry serves forensic claims adjudication and fraud detection workflows.
Driver Behavior commands the dominant share, though Location Data is expanding most quickly through connected vehicle OEM integration.
Insurance Type:
Product maturity curves separate behavioral pricing sophistication from simple usage verification, with fleet applications scaling through enterprise procurement channels.
- Pay-How-You-Drive:Dynamic premium adjustments tied to real-time behavioral scoring reward safe driving with immediate cost reductions. German commercial fleet operators now mandate these policies for liability optimization, while Mediterranean consumer markets respond to gamified feedback interfaces.
- Fleet Insurance:Centralized telematics deployment across vehicle pools enables aggregate risk management for logistics and delivery operators. LTE-M and NB-IoT modem protocols support continuous connectivity without driver smartphone dependency.
- Pay-As-You-Drive:Mileage-based pricing appeals to low-usage vehicle owners seeking basic cost reduction.
- Usage-Based Insurance:Hybrid models combine mileage verification with limited behavioral elements for mid-market positioning.
Fleet Insurance holds the dominant share, yet Pay-How-You-Drive is gaining share fastest as behavioral scoring models mature beyond mileage proxies.
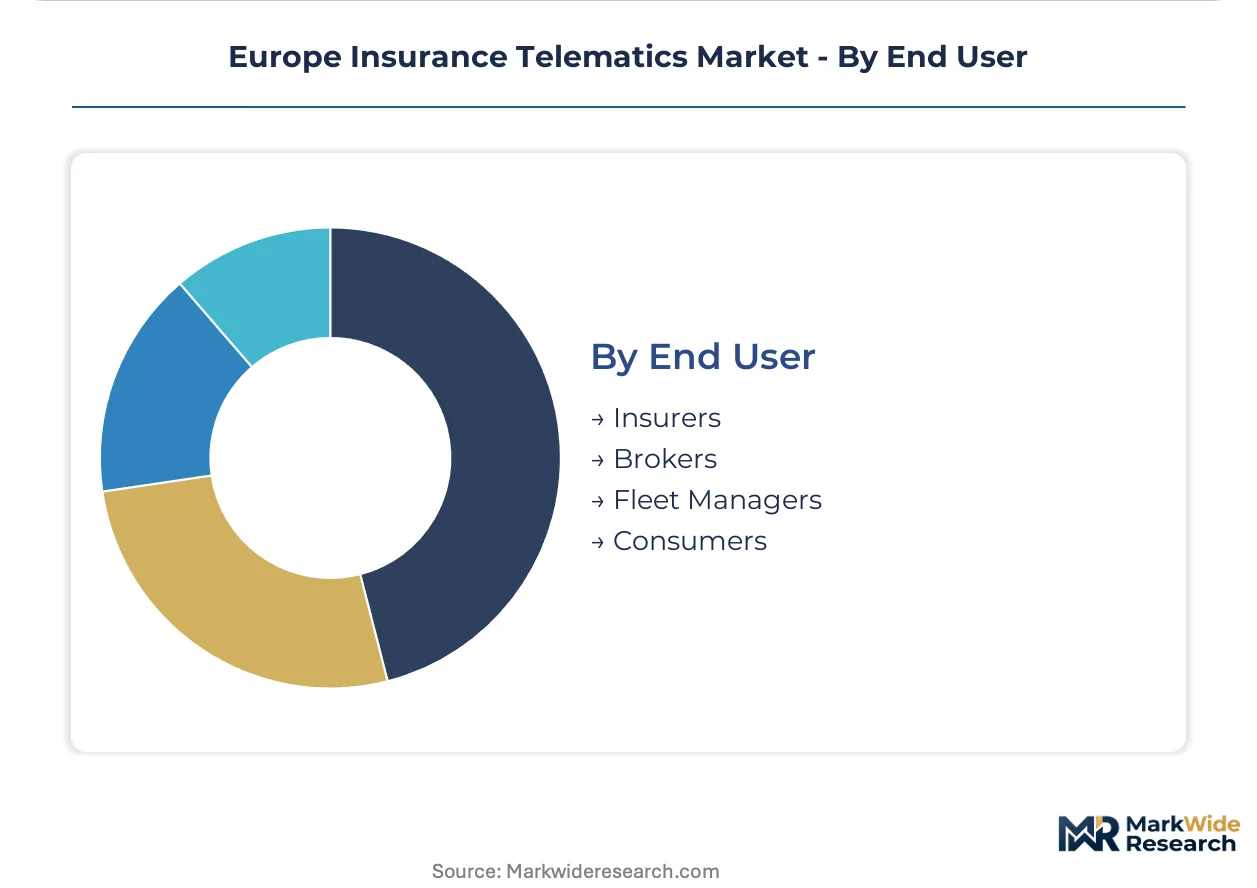
End User:
Customer acquisition economics vary sharply between direct consumer channels and intermediated distribution through brokers and fleet managers.
- Insurers:Direct policy origination through proprietary apps captures full margin stack and customer data ownership. Allianz and Admiral compete on platform design rather than hardware subsidies, with EIOPA supervisory convergence mandating standardized disclosure protocols for telematics-enabled contracts.
- Fleet Managers:Enterprise procurement of multi-vehicle telematics bundles concentrates volume and reduces per-unit acquisition costs. German logistics operators lead European adoption, mandating on-device edge computing for emergency response latency minimization.
- Brokers:Intermediated distribution requires API integration with insurer telematics platforms for policy comparison and placement.
- Consumers:Individual policyholders exhibit divergent preferences between app-based convenience and hardware-based crash reconstruction reliability.
Insurers command the dominant share, while Fleet Managers are expanding most quickly through enterprise telematics standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in Germany and Italy drive premium volume concentration, while Mediterranean consumer markets accelerate app-based policy origination through smartphone density. Regulatory enforcement by EIOPA and national data protection authorities is standardizing disclosure protocols across member states.
Germany
KBA regulations on connected vehicle data security shape telematics hardware certification requirements for commercial fleets. The EU AI Act's high-risk system designation mandates algorithmic audit trails for behavioral scoring models deployed by insurers. Munich and Stuttgart anchor the automotive insurance cluster where Allianz leverages captive IoT infrastructure for motor portfolio pricing power.
Italy
Near-universal smartphone penetration eliminates hardware friction for Pay-How-You-Drive policy origination among young-driver segments. GDPR enforcement by the Garante per la Protezione dei Dati Personali tightens consent architectures for telematics data collection. Turin and Milan host the southern European installed base where Octo Telematics maintains embedded OEM partnerships for data stream capture.
United Kingdom
FCA conduct rules on digital distribution mandate clear disclosure of telematics-enabled contract terms to consumer policyholders. The UK Information Commissioner's Office applies GDPR-derived standards to algorithmic insurance pricing transparency requirements. London concentrates broker-intermediated telematics platform development, with Admiral competing on consumer-facing app design rather than hardware subsidies.
Spain
Mediterranean motor insurance density intersects with high smartphone adoption to compress customer acquisition costs for app-based insurers. Spanish data protection authority guidance on GDPR lawful basis for processing creates compliance templates adopted across Iberian telematics deployments. Barcelona and Madrid emerge as testing grounds for gamified feedback interfaces targeting digital-native provisional license holders.
France
ANSM and CNIL oversight of health-adjacent vehicle data creates specialized compliance pathways for telematics platforms processing biometric proxies. The EU Green Deal's mobility transition incentives accelerate fleet telematics adoption for emissions monitoring and route optimization. Paris anchors continental R&D concentration for privacy-preserving federated analytics platforms that enable cross-insurer risk pooling.
Europe Insurance Telematics Market Competitive Landscape
Player mix skews toward integrated insurers with captive IoT infrastructure and specialized telematics platform providers serving multi-carrier deployments. Market structure exhibits tiered consolidation around proprietary data lake architectures versus federated analytics subscriptions. Three archetypes dominate: vertically integrated insurers controlling full technology stacks, independent telematics platform vendors supplying algorithmic scoring engines, and automotive OEMs embedding factory-installed data collection modules. Competitive dynamics center on M&A activity targeting middleware capabilities and strategic partnerships bridging insurer policy administration systems with real-time data ingestion protocols.
Within the integrated insurer tier, Allianz and Generali represent archetypes of proprietary infrastructure deployment, each sustaining pricing power through captive data ownership rather than third-party platform dependency. Among specialized platform providers, Octo Telematics occupies a position exemplifying the independent vendor model that supplies behavioral scoring capabilities across multiple carrier relationships. Admiral anchors the consumer-facing digital distribution vector, competing through application interface design rather than hardware subsidy economics. AXA and Unipol sit within the mid-tier convergence zone, balancing proprietary development with selective platform partnerships to address multi-market regulatory fragmentation.
| Leading Market Players |
|---|
| Unipol |
| Generali |
| Allianz |
| AXA |
| Unipolsai Assicurazioni |
| LexisNexis Risk Solutions |
| Octo Telematics |
| Admiral |
| Direct Line Group |
| Others |
Supply & Pricing Matrix
CE marking under the EU Cybersecurity Act gates both hardware vendor qualification and price differentiation across aftermarket telematics devices, compressing margins for uncertified assemblers while enabling premium positioning for compliant suppliers serving German commercial fleet operators.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate modem procurement for LTE-M and NB-IoT chipsets, exposing European hardware assemblers to East Asian foundry pricing volatility. Three-tier pricing structure across premium-certified, standard-compliant, and economy-tier devices separates court-admissible crash reconstruction capabilities from basic mileage verification. Pricing pressure stems from zero-marginal-cost smartphone apps displacing subsidized black-box installations among young-driver segments. Fleet managers exhibit lowest price sensitivity due to liability optimization mandates, while individual consumers in Mediterranean markets prioritize app-based convenience over hardware reliability premiums.
Supply Chain Analysis
Taiwan and South Korea anchor LTE-M and NB-IoT modem fabrication, with European telematics hardware assemblers drawing from concentrated East Asian foundry capacity for cellular connectivity modules. German and Italian device integrators rest on GPS module supplies from multi-constellation GNSS providers, accelerometer MEMS from specialized semiconductor houses, and CE marking certification services from notified bodies. Single-source vulnerability concentrates in advanced node modem production, exposing lead time volatility for European assemblers. Distribution runs through tiered channels: direct OEM embedded partnerships for factory-installed systems, insurer-procured bulk contracts for fleet deployments, and retail aftermarket for consumer black-box segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of actuarial science and machine learning engineering remains critically understaffed across European insurer headquarters, constraining proprietary model development and amplifying acquisition premiums for teams possessing both reserving expertise and algorithmic deployment capabilities.
For Market Incumbents: Fortify proprietary data lake architectures against federated analytics platforms by deepening in-house production of behavioral scoring engines and securing exclusive OEM embedded data partnerships. The EU AI Act's high-risk system audit requirements threaten carriers dependent on third-party algorithmic vendors, making captive model explainability infrastructure the priority lever for pricing power defense in German motor portfolios. For New Entrants and Emerging Players: Anchor in Poland and Romania's underpenetrated telematics markets where rising motor insurance density meets minimal incumbent app-based distribution. Localized smartphone-first policy origination targeting young-driver segments in Warsaw and Bucharest offers the most penetrable white space, with gamified feedback interfaces providing immediate differentiation against hardware-mandated legacy offerings. For Investors and Strategic Acquirers: The EU AI Act's full enforcement reshapes the acquisition landscape toward privacy-preserving federated analytics platforms that enable cross-insurer risk pooling without raw data sharing. Long-term viability over the coming decade hinges on GDPR-compliant infrastructure that satisfies convergent EDPB guidance across member states. Target acquisition archetypes include middleware specialists bridging legacy policy administration systems to real-time telematics ingestion, with EIOPA supervisory convergence announcements serving as the signal to watch for regulatory inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | EU Cybersecurity Act compliance collapses vendor landscape, concentrating share among certified German and Italian hardware suppliers. |
| Federated Analytics Platform Development | Privacy-enhancing computation aligns with EDPB guidance, enabling cross-carrier model training without GDPR-prohibited data pooling. |
| OEM Embedded Partnership Expansion | Factory-installed telematics modules in connected vehicles displace aftermarket installation, creating captive data streams for partnered insurers. |
| Edge Computing Infrastructure Deployment | On-device inference minimizes emergency response latency, meeting German commercial fleet operator mandates for real-time crash detection. |
| Actuarial-AI Talent Acquisition | Combined reserving and machine learning expertise scarcity drives competitive positioning for proprietary behavioral scoring model development. |
Research Methodology
Desk research of EIOPA supervisory convergence mandates, national data protection authority guidance, and connected vehicle regulatory filings preceded structured interviews with telematics platform CTOs, motor insurance pricing actuaries, fleet procurement managers, and OEM partnership directors. Primary fieldwork combined with secondary validation against CE marking databases, cellular module customs records, and insurer digital distribution disclosures. Bottom-up policy origination volume estimates triangulated against top-down motor insurance penetration benchmarks across member states.
Variance decomposition across device type, data granularity tier, and insurance product maturity enabled robust growth trajectory estimation throughout the forecast period. Segmentation dimensions modeled encompass hardware deployment mode, behavioral telemetry sophistication, pricing mechanism architecture, and end-user procurement channel. CAGRs derived from logistic adoption curve fitting against smartphone penetration saturation levels and regulatory compliance deadline clustering. Industry-specific inputs include EU AI Act implementation timelines and EDPB guidance evolution on lawful basis for telematics processing.
Underlying assumptions cover GDPR consent architecture stability, CE marking capacity expansion, and modem chipset supply continuity, with deviation risk concentrated in divergent national supervisory interpretations of algorithmic pricing transparency. Forecasts reflect these conditions with explicit sensitivity to regulatory guidance materialization. Recalibration cycles align with EIOPA convergence mandate updates and EDPB opinion releases on telematics data processing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Europe Insurtech Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
China AI in Insurance Market