
 Middle East AI in Insurance Market | 2026-2036
Middle East AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East AI in Insurance Market Analytics
Commercial property and casualty insurers is reorganizing technology procurement priorities ahead of retail life insurers across the Middle East. AXA Gulf leverages proprietary machine learning models for Gulf-specific risk profiling. Qatar Insurance Company (QIC) anchors its competitive stance through deep investments in Arabic-language natural language processing. Allianz Saudi Fransi dominates the Saudi market with Shariah-compliant algorithmic underwriting systems.
Artificial intelligence in Middle East insurance encompasses software systems that apply machine learning, natural language processing, and predictive analytics to automate core insurance functions including risk selection, claims adjudication, and customer interaction, typically operating through cloud-based architectures integrated with legacy core policy administration systems. The primary commercial purpose centers on reducing loss ratios and operational expense loads while accelerating quote-to-bind cycle times. Fraud detection and claims processing command the largest current revenue pools within product type segments, while underwriting automation represents the fastest-expanding category as carriers seek to compress manual review timelines. Machine learning leads technology adoption by a wide margin, though natural language processing is gaining ground fastest as Arabic dialect processing capabilities mature.
The UAE Central Bank's digital operational resilience framework and Saudi Arabian Monetary Authority's sandbox licensing for insurtech entities together establish the region's most consequential regulatory architecture for AI deployment. SAMR-equivalent standards in the Gulf Cooperation Council jurisdictions increasingly require explainable AI documentation for algorithmic pricing decisions. Stakeholders must monitor evolving data localization requirements and model governance standards as Gulf regulators harmonize cross-border insurance technology supervision.
Market Dynamics
Algorithmic underwriting automation is fragmenting traditional actuarial workflows across Middle East insurance carriers as cloud-native architectures displace on-premise legacy systems. The UAE Central Bank's digital operational resilience framework and Saudi Arabian Monetary Authority's sandbox licensing together mandate explainable AI documentation for pricing decisions, forcing carriers to restructure technology procurement priorities ahead of supervisory deadlines.
Growth Catalysts
- Machine Learning Adoption:Predictive analytics engines automate risk selection and claims adjudication, compressing quote-to-bind cycle times for property and casualty lines.
- Saudi Vision 2030:Financial sector reforms accelerate insurtech licensing and algorithmic decision-making standards across the Kingdom's insurance supervisory framework.
- Arabic NLP Maturation:Natural language processing capabilities for Gulf dialects enable automated customer interaction and document processing at scale.
Market Restraints
- Data Localization Mandates:Cross-border data transfer restrictions in GCC jurisdictions fragment cloud infrastructure deployment and increase compliance overhead.
- Legacy System Integration:Core policy administration systems from the 1990s resist API connectivity, delaying AI module deployment timelines.
- Actuarial Talent Scarcity:Shortage of professionals combining traditional underwriting expertise with machine learning implementation skills constrains carrier transformation velocity.
Strategic Opportunities
- Takaful Segment Automation:Shariah-compliant algorithmic underwriting systems address underserved Islamic insurance demand across Saudi Arabia and the UAE.
- Fraud Detection Expansion:Claims processing AI identifies anomalous patterns in motor and health portfolios where manual review misses coordinated schemes.
- SAMR Sandbox Pathways:Regulatory licensing for insurtech entities enables algorithmic pricing experimentation outside traditional capital requirements.
Industry Challenges
- Explainable AI Documentation:Gulf regulators require transparent model governance for algorithmic decisions, demanding specialized compliance infrastructure.
- Cloud Migration Capex:Shifting from on-premise core systems to cloud-native architectures requires substantial capital allocation amid compressed investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East AI in Insurance Market |
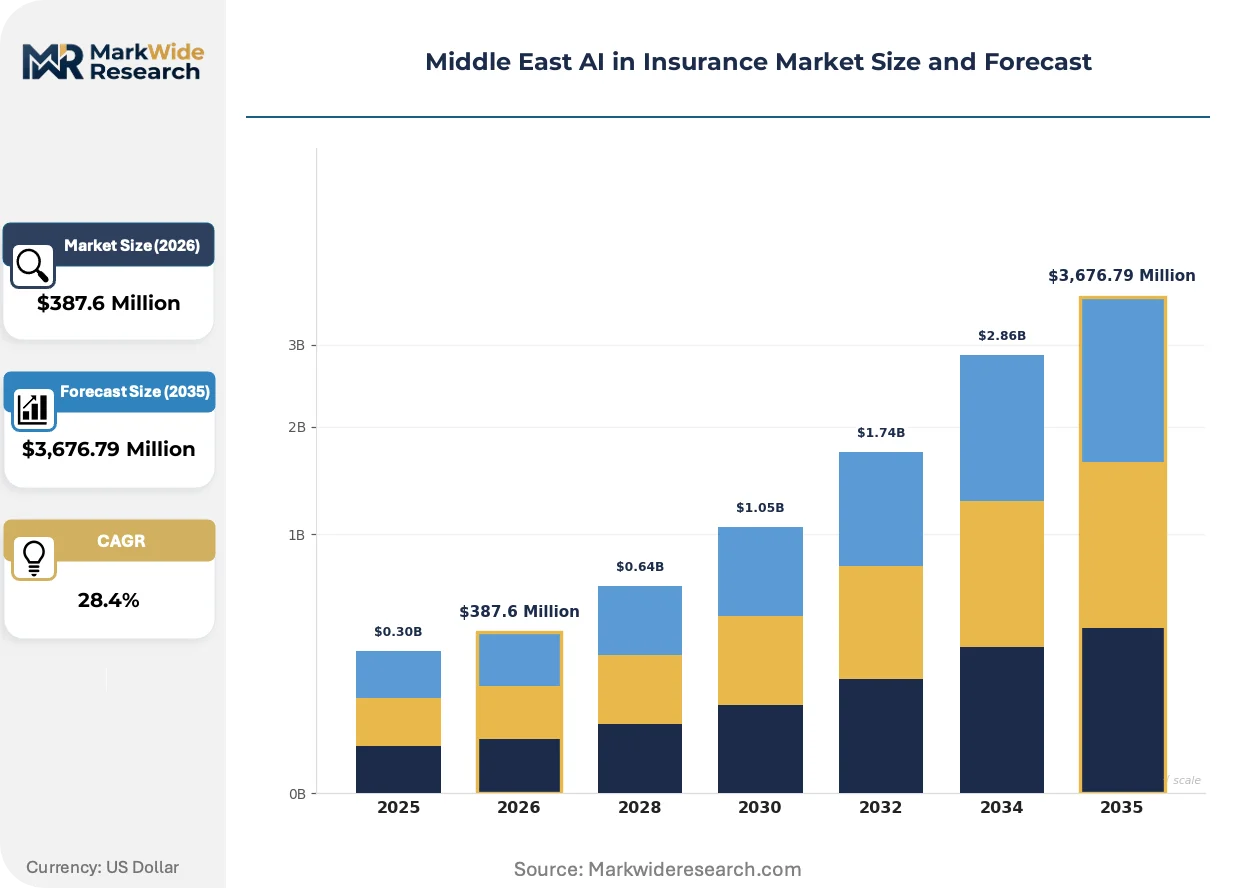
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $3,676.79 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fraud Detection, Underwriting Automation, Claims Processing, Customer Service Technology: Machine Learning, Natural Language Processing, Data Analytics, Computer Vision End User: Insurance Companies, Brokers, Reinsurers, Policyholders Application: Policy Management, Risk Assessment, Customer Insights, Market Forecasting |
| Companies Covered | AXA Gulf, Allianz Saudi Fransi, Qatar Insurance Company (QIC), Dubai Insurance Company, Abu Dhabi National Insurance Company (ADNIC), Oman Insurance Company, Gulf Insurance Group (GIG), National General Insurance Company (NGI), Emirates Insurance Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East AI in Insurance Market Evolving Landscape
Machine learning deployment patterns across Middle East insurance are fragmenting established underwriting hierarchies as carriers race to automate risk selection ahead of regulatory deadlines. Three developments dominate technology procurement priorities.
Cloud-native underwriting engines are fragmenting traditional actuarial department structures. These systems apply ensemble machine learning to Gulf-specific risk factors including construction quality indices and regional weather pattern databases. Large commercial property carriers in Dubai and Riyadh deploy these tools within eighteen-month implementation windows. The technology is fragmenting centralized underwriting authority into distributed algorithmic decision nodes.
The UAE Central Bank's digital operational resilience framework mandates algorithmic impact assessments for insurers deploying automated pricing. This regulation requires documented model governance, stress testing protocols, and human oversight mechanisms. Carriers must submit explainability documentation before deploying machine learning in customer-facing decisions. Saudi Arabian Monetary Authority sandbox participants adapt these standards for cross-border product approvals.
Corporate risk managers now demand API-embedded insurance quotes within enterprise resource planning workflows. Traditional broker-mediated placement cycles face compression as direct platform integration enables real-time coverage binding. Large construction and logistics operators in the UAE lead this procurement evolution, selecting carriers based on integration speed rather than historical relationships.
Middle East AI in Insurance Market Segmentation
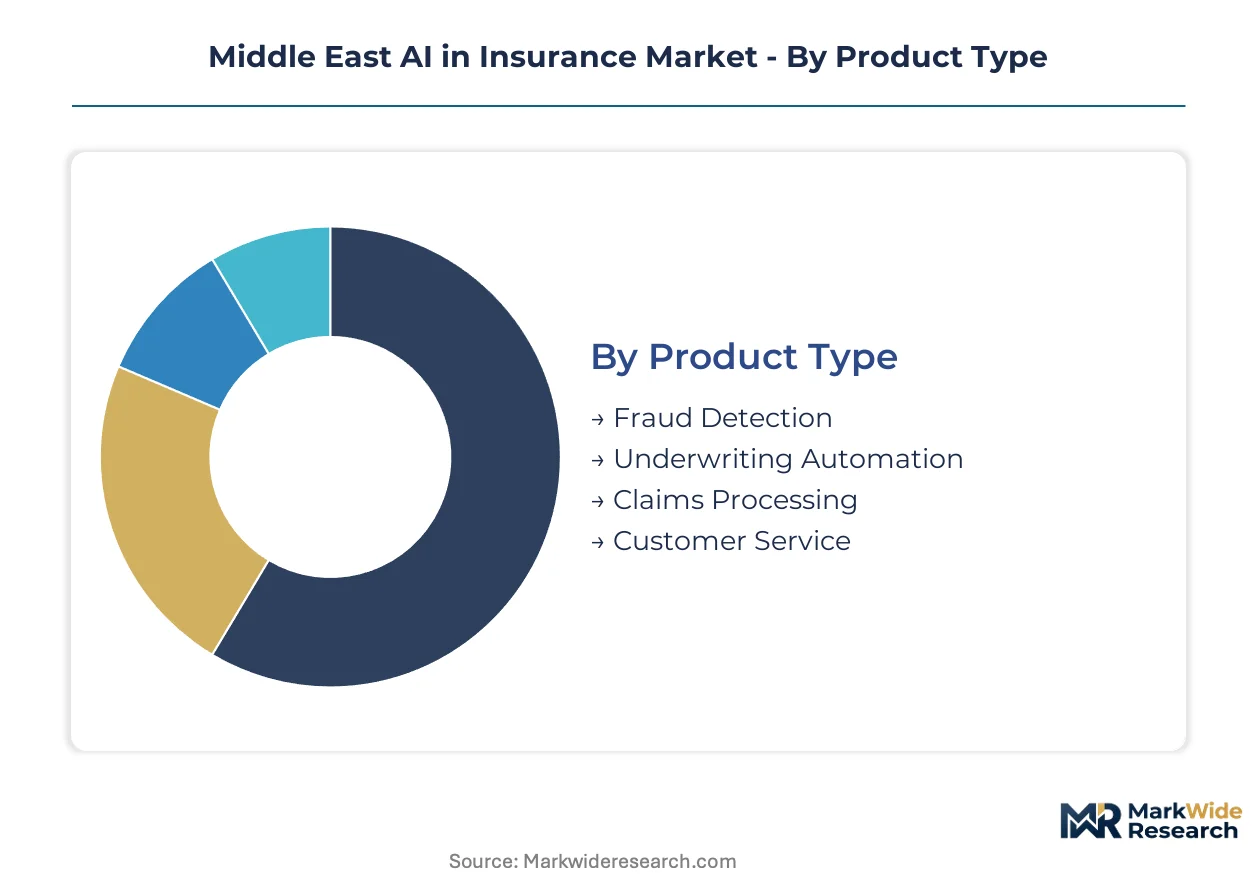
Segmentation of Middle East AI in Insurance reveals concentrated margin pools in fraud detection and machine learning deployment, with Saudi Arabian and UAE carriers driving differential technology procurement across product categories.
Product Type:
Fraud detection and underwriting automation command the widest deployment spreads across Gulf carrier portfolios, absorbing disproportionate technology budgets relative to operational scale.
- Fraud Detection:Anomaly identification systems analyze motor and health claims patterns to flag coordinated schemes invisible to manual review. UAE commercial property carriers deploy these tools most aggressively, pressured by SAMR-equivalent documentation requirements for algorithmic decision transparency. The segment absorbs substantial compliance overhead alongside core technology investment.
- Underwriting Automation:Cloud-native engines apply ensemble machine learning to Gulf-specific risk factors including construction quality indices and regional weather databases. Saudi Vision 2030 financial reforms compress implementation timelines across Riyadh-headquartered carriers. This category fragments traditional actuarial hierarchies into distributed algorithmic nodes.
- Claims Processing:Automated adjudication workflows accelerate settlement cycles for property and casualty lines.
- Customer Service:Arabic-language chatbots and voice interfaces handle policy inquiries across dialect variants.
The dominant share belongs to fraud detection, while underwriting automation is closing the gap fastest.
Technology:
Carrier procurement prioritizes mature machine learning stacks over emerging modalities, though natural language processing gains ground as Arabic dialect capabilities mature.
- Machine Learning:Predictive analytics engines dominate risk selection and pricing automation across UAE and Saudi deployments. Ensemble methods processing Gulf-specific construction and weather data have achieved production reliability ahead of regulatory deadlines. The technology anchors virtually every carrier's digital transformation roadmap.
- Natural Language Processing:Arabic dialect processing enables automated document analysis and customer interaction at scale. Qatar Insurance Company anchors competitive positioning through deep investments in Gulf Arabic language models. Regulatory sandboxes in Saudi Arabia accelerate experimentation with customer-facing NLP applications.
- Data Analytics:Descriptive and diagnostic tools support actuarial reserving and portfolio monitoring.
- Computer Vision:Image-based damage assessment for property and motor claims remains nascent but expanding.
Machine learning maintains the deepest carrier penetration, though natural language processing expands most quickly as language barriers fall.
End User:
Insurance companies internalize the bulk of AI development costs, while broker and policyholder adoption follows integration maturity curves.
- Insurance Companies:Primary developers and deployers of algorithmic underwriting, claims automation, and fraud detection systems. UAE and Saudi carriers restructure technology procurement priorities ahead of central bank digital resilience mandates. Capital allocation concentrates in cloud-native architectures displacing 1990s-era core systems.
- Brokers:API-embedded quote integration within enterprise resource planning workflows compresses traditional placement cycles. Large UAE construction and logistics operators now select carriers based on integration speed rather than historical relationships. This segment demands real-time coverage binding capabilities.
- Reinsurers:Algorithmic risk transfer pricing and portfolio optimization applications.
- Policyholders:Self-service claims filing and policy management through mobile interfaces.
Insurance companies retain the dominant deployment share, while broker-facing solutions gain share fastest as API integration becomes a procurement differentiator.
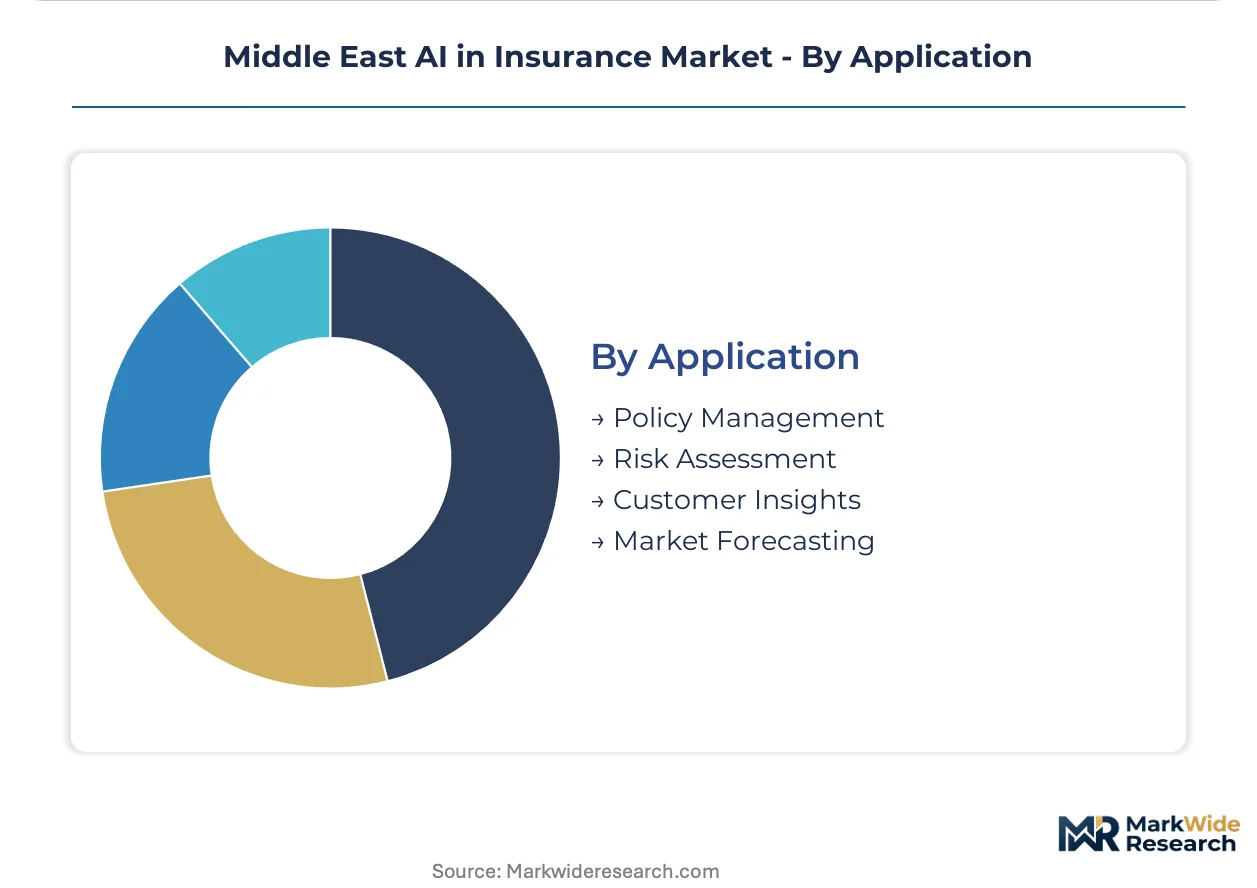
Application:
Risk assessment applications absorb the steepest investment trajectories as carriers automate core underwriting functions ahead of regulatory deadlines.
- Risk Assessment:Algorithmic evaluation of property construction quality, motor driver behavior, and health portfolio morbidity patterns. Saudi Arabian Monetary Authority sandbox licensing enables pricing experimentation outside traditional capital requirements. The application commands priority in carrier technology roadmaps.
- Policy Management:Automated endorsement processing, renewal pricing, and coverage modifications. UAE Central Bank operational resilience frameworks mandate explainable documentation for these customer-facing algorithmic decisions. Systems must demonstrate human oversight mechanisms and stress testing protocols.
- Customer Insights:Behavioral segmentation and lifetime value prediction for retention campaigns.
- Market Forecasting:Predictive models for premium volume and loss ratio projection.
Risk assessment holds the dominant deployment position, while policy management climbs fastest as regulatory documentation requirements force system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based insurers export AI-enabled underwriting platforms to Saudi Arabian carriers seeking rapid digital transformation. This technology corridor concentrates vendor relationships and regulatory knowledge transfer between the two largest Gulf markets. Cross-border data flows follow this axis despite emerging localization requirements.
United Arab Emirates
Dubai's insurtech cluster attracts machine learning vendors serving commercial property underwriters. The UAE Central Bank's digital operational resilience framework mandates algorithmic impact assessments before customer-facing deployment. Abu Dhabi hosts ADNIC and Emirates Insurance Company as anchor carriers modernizing core systems.
Saudi Arabia
Riyadh-headquartered carriers accelerate underwriting automation ahead of SAMR sandbox licensing deadlines. The Saudi Arabian Monetary Authority's insurtech regulatory sandbox enables algorithmic pricing experimentation outside traditional capital requirements. Allianz Saudi Fransi anchors algorithmic Shariah-compliant product development in the Eastern Province.
Qatar
Doha-based carriers leverage Arabic natural language processing for customer-facing automation. Qatar Insurance Company anchors Gulf Arabic language model investments. The Qatar Central Bank's digital banking framework extends to insurance algorithmic governance requirements.
Kuwait
Gulf Insurance Group concentrates regional AI procurement from its Kuwait City headquarters. The country's insurance regulator aligns with SAMR-equivalent explainable AI documentation standards. Local carriers face legacy system integration constraints delaying cloud-native deployment timelines.
Oman
Muscat-based Oman Insurance Company participates in cross-border technology partnerships with UAE vendors. The Central Bank of Oman's gradual digital transformation timeline lags neighboring jurisdictions. Local carriers prioritize fraud detection over full underwriting automation given capital constraints.
Middle East AI in Insurance Market Competitive Landscape
Player mix skews toward diversified multinational carriers with Gulf-specific digital operations. Market structure concentrates around three to five large insurers controlling disproportionate technology procurement budgets. Strategic archetypes include global carriers with regional Gulf subsidiaries, domestic champions with sovereign backing, and Takaful specialists with Shariah-compliant automation requirements. Competitive moves center on regulatory sandbox participation and Arabic-language NLP capability acquisition.
Among global carriers with Gulf operations, AXA Gulf and Allianz Saudi Fransi exemplify the multinational archetype adapting proprietary machine learning models to regional risk factors. Qatar Insurance Company represents the domestic specialist path, anchoring competitive positioning through deep investments in Arabic dialect processing. These three carriers occupy distinct strategic positions: AXA Gulf leads commercial property automation, Allianz Saudi Fransi dominates Shariah-compliant algorithmic underwriting, and QIC anchors natural language processing differentiation.
| Leading Market Players |
|---|
| AXA Gulf |
| Allianz Saudi Fransi |
| Qatar Insurance Company (QIC) |
| Dubai Insurance Company |
| Abu Dhabi National Insurance Company (ADNIC) |
| Oman Insurance Company |
| Gulf Insurance Group (GIG) |
| National General Insurance Company (NGI) |
| Emirates Insurance Company |
| Others |
Value Network & Pricing Analysis
Cloud-native underwriting platforms are displacing on-premise legacy systems across UAE and Saudi carrier procurement, simultaneously concentrating vendor relationships in Dubai and Riyadh technology clusters while compressing implementation pricing through competitive SaaS bundling. This substitution dynamic fragments traditional software licensing economics as carriers negotiate consumption-based contracts against fixed perpetual licenses.
Pricing Analysis
Next-generation machine learning underwriting engines command premium SaaS tiers against discounted legacy system maintenance contracts and experimental sandbox pricing for emerging NLP capabilities. Three-tier pricing structure across enterprise, mid-market, and pilot deployment levels differentiates by API call volume, model customization depth, and regulatory documentation support. Cost compression in mid-market tiers is intensifying because Saudi Vision 2030 deadlines compress procurement timelines. Broker-facing API integration packages show highest price sensitivity; carriers with sovereign backing demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of Arabic-language training data and Gulf-specific risk factor databases dominates carrier procurement strategy over just-in-time cloud resource provisioning. Technology supply concentrates in the United States, United Kingdom, and India for core machine learning infrastructure, with UAE and Saudi Arabia emerging as regional deployment hubs. Component dependencies include cloud compute instances, proprietary insurance core system APIs, and regulatory compliance documentation frameworks. Single-source vulnerability in legacy system API connectivity creates integration bottlenecks. Distribution runs through direct carrier-vendor relationships and Dubai-based insurtech intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as regulatory sandbox licensing accelerates algorithmic pricing experimentation ahead of supervisory deadlines across the Gulf Cooperation Council.
For Market Incumbents: Shield core underwriting margins by accelerating cloud-native architecture deployment ahead of SAMR-equivalent documentation mandates. Prioritize vertical integration into proprietary Gulf risk factor databases to defend against emerging NLP specialists. Lock in Arabic-language model training partnerships before talent scarcity intensifies.
For New Entrants and Emerging Players: SAMR sandbox certification fast-tracks enable algorithmic pricing experimentation without traditional capital requirements. Target Oman and Kuwait carrier modernization backlogs where legacy system constraints delay incumbent transformation. Lead with API-first fraud detection modules requiring minimal core system integration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed insurtech vendors holding UAE Central Bank operational resilience framework compliance documentation. Five-to-ten year viability hinges on regulatory harmonization across GCC jurisdictions. Watch Saudi Arabian Monetary Authority sandbox graduation rates as inflection indicator for scalable deployment readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | Enables algorithmic pricing experimentation outside traditional SAMR capital requirements. |
| Arabic NLP Capability Acquisition | Qatar Insurance Company anchors competitive positioning through Gulf dialect investments. |
| Cloud-Native Core Migration | Replaces 1990s-era policy administration systems resisting API connectivity. |
| API-Embedded Broker Integration | UAE construction operators select carriers based on ERP integration speed. |
| Shariah-Compliant Algorithm Development | Allianz Saudi Fransi dominates Takaful segment automation in Eastern Province. |
Research Methodology
The analysis maps fraud detection systems, underwriting automation engines, claims processing workflows, and customer service AI, each validated through chief technology officers, insurance regulatory affairs leads, core system procurement managers, and insurtech partnership directors. Primary interviews with UAE Central Bank supervisory staff and SAMR sandbox administrators combined with secondary validation against regulatory filing databases, carrier annual technology disclosure reports, and cloud vendor hyperscaler capex disclosures. Bottom-up deployment estimates triangulate against top-down premium automation penetration rates.
Consistency checks validated model outputs against external benchmarks for machine learning adoption curves in regulated financial services. Segmentation dimensions include product type, technology modality, end-user category, and application function across the modeling period. CAGRs derive from carrier technology budget trajectories, regulatory deadline compression effects, and vendor implementation pipeline data. Forecast inputs incorporate SAMR-equivalent documentation requirement rollout schedules and Arabic NLP capability maturation timelines.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions across GCC jurisdictions; material deviation in data localization mandates or cross-border supervision frameworks would warrant model refresh. Forecasts reflect assumptions about sandbox licensing continuity and legacy system API accessibility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Insurance Software Market
Insurance Technology
North America Insurance Telematics Market