
 Insurance Automation Market | 2026-2036
Insurance Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Automation Market Foresight
The United States is narrowing its technology gap with dedicated automation infrastructure for insurance carriers migrating from on-premise legacy stacks. UiPath leverages robotic process automation to dominate policy administration workflows for mid-market insurers. Guidewire anchors its position through deep integration with cloud-based claims orchestration layers. Shift Technology competes on AI-native fraud detection modules that reduce manual review queues.
Insurance automation encompasses software systems that execute underwriting, claims adjudication, policy servicing, and customer interactions with minimal human intervention, typically operating through API-connected workflows and rules engines processing structured and unstructured data. Claims Processing leads product-type revenue as carriers prioritize loss-cost containment, while Underwriting Automation registers the fastest expansion as machine learning models refine risk scoring precision. Robotic Process Automation remains the most deployed technology segment due to its plug-and-play retrofit capability for legacy core systems, whereas AI Tools capture the highest margin pools through subscription-based predictive analytics.
FDA guidelines on software-as-medical-device intersect with health insurance automation where wellness algorithms trigger coverage decisions, while HIPAA mandates shape data architecture requirements for all U.S. insurance automation platforms. The EU AI Act imposes conformity assessments on automated underwriting systems deployed in European markets, forcing vendors to build explainability layers into black-box models. Stakeholders must monitor emerging state-level algorithmic accountability statutes that could fragment compliance obligations across multiple jurisdictions.
Market Dynamics
Property and casualty carriers are compressing claims cycle times through API-orchestrated workflows that bypass manual handoffs between legacy core systems and cloud-native modules. This infrastructure migration is redistributing vendor power toward platforms offering retrofit compatibility with existing policy administration databases.
Growth Catalysts
- EU AI Act compliance mandates:European carriers must deploy explainable underwriting algorithms, creating immediate demand for audit-trail software and model documentation tools.
- Cloud-native core replacement:United States insurers are retiring on-premise policy administration systems, opening procurement windows for automation vendors with microservices architecture.
- Fraud detection automation:Machine learning modules processing unstructured claims data are reducing manual review queues for mid-market carriers with limited investigative staff.
Market Restraints
- Legacy system integration costs:Custom API development for 1990s-era COBOL-based policy databases consumes 40-60% of automation project budgets.
- Specialized talent scarcity:Actuarial data scientists capable of validating algorithmic underwriting models command premium compensation in London and New York financial centers.
- Regulatory fragmentation risk:Emerging state-level algorithmic accountability statutes in the United States threaten to multiply compliance obligations across 50 jurisdictions.
Strategic Opportunities
- Small commercial underwriting:Automated risk scoring for Main Street businesses remains underpenetrated relative to personal auto and homeowners segments.
- India's digitization push:IRDAI's sandbox framework permits pilot deployments of automated claims systems without full licensing, lowering market entry barriers.
- Embedded insurance distribution:API-first automation platforms enable real-time policy issuance through e-commerce checkout flows and IoT device purchase paths.
Industry Challenges
- Model explainability requirements:Black-box machine learning systems face rejection from internal compliance committees and external regulators demanding decision traceability.
- Data architecture fragmentation:Decades of mergers have left carriers with incompatible policy databases that resist unified automation layer deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Automation Market |
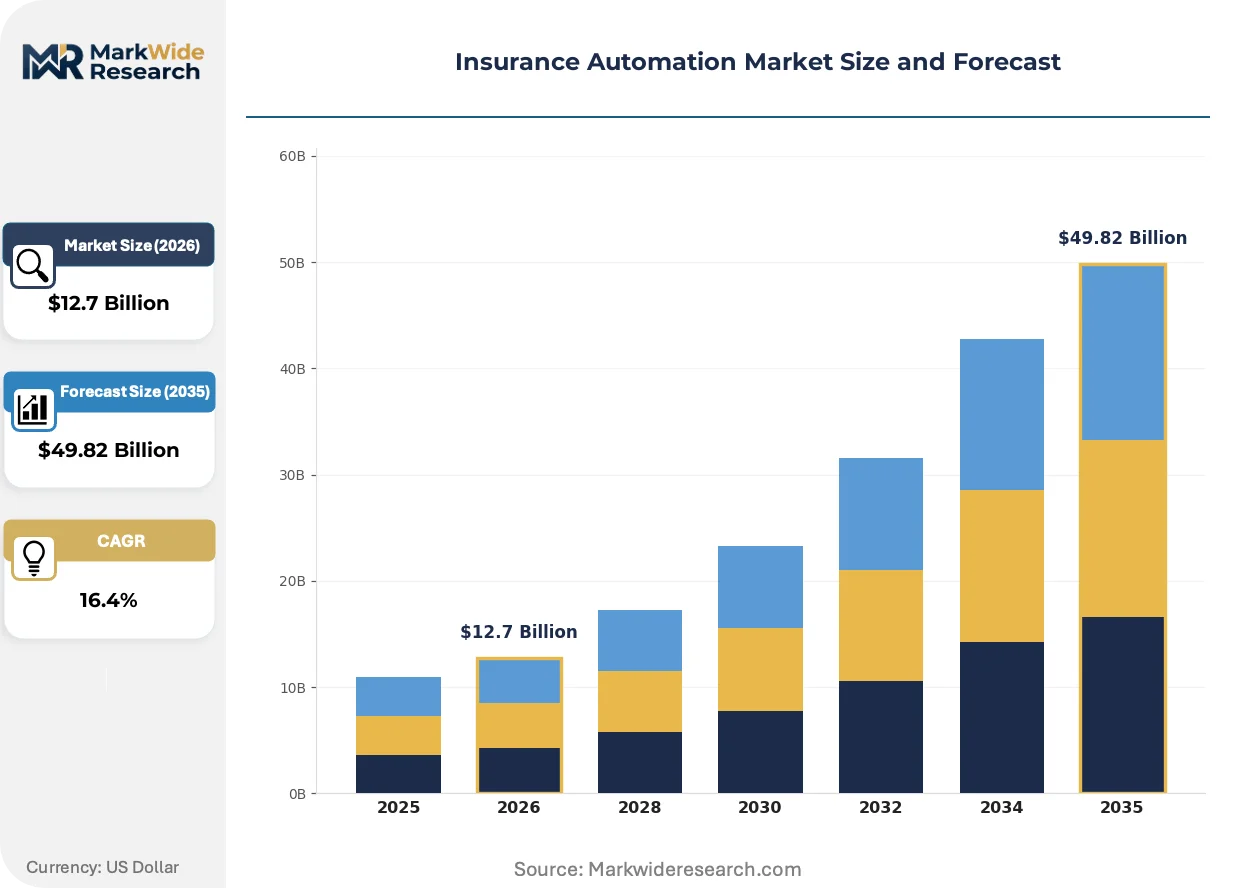
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Claims Processing, Underwriting Automation, Policy Management, Customer Engagement Technology: AI Tools, Machine Learning, Robotic Process Automation, Cloud Computing End User: Insurance Providers, Brokers, Financial Advisors, Risk Managers Service Type: Consulting, Implementation, Support Services, Managed Services |
| Companies Covered | UiPath, Formstack, Superblocks, Ushur, NowCerts, Creatio, Camunda, Guidewire, Shift Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Automation Market Shifts & Advancements
Distributed ledger protocols and generative AI are converging to reshape how carriers verify coverage, adjudicate claims, and interact with policyholders. These technologies are compressing the gap between data capture and actionable underwriting insight.
Intelligent document processing is virtualizing the extraction of loss details from unstructured medical records, police reports, and contractor estimates. Mid-market carriers in the United States are deploying these tools within six-month implementation windows. The technology is virtualizing claims intake workflows that previously required dedicated data entry teams.
The EU AI Act imposes conformity assessments on automated underwriting systems deployed in European markets, forcing vendors to rebuild neural network architectures with built-in audit trails. High-risk insurance algorithms now require human-in-the-loop overrides for adverse coverage decisions. French and German carriers are front-loading compliance investments ahead of enforcement deadlines.
Usage-based insurance models are displacing traditional annual rating cycles with real-time premium adjustments driven by telematics and IoT sensor feeds. Commercial fleet operators are demanding per-mile or per-hour coverage structures that legacy rating engines cannot accommodate. This shift is most visible in United States commercial auto and European pay-as-you-drive personal lines.
Insurance Automation Market Segmentation
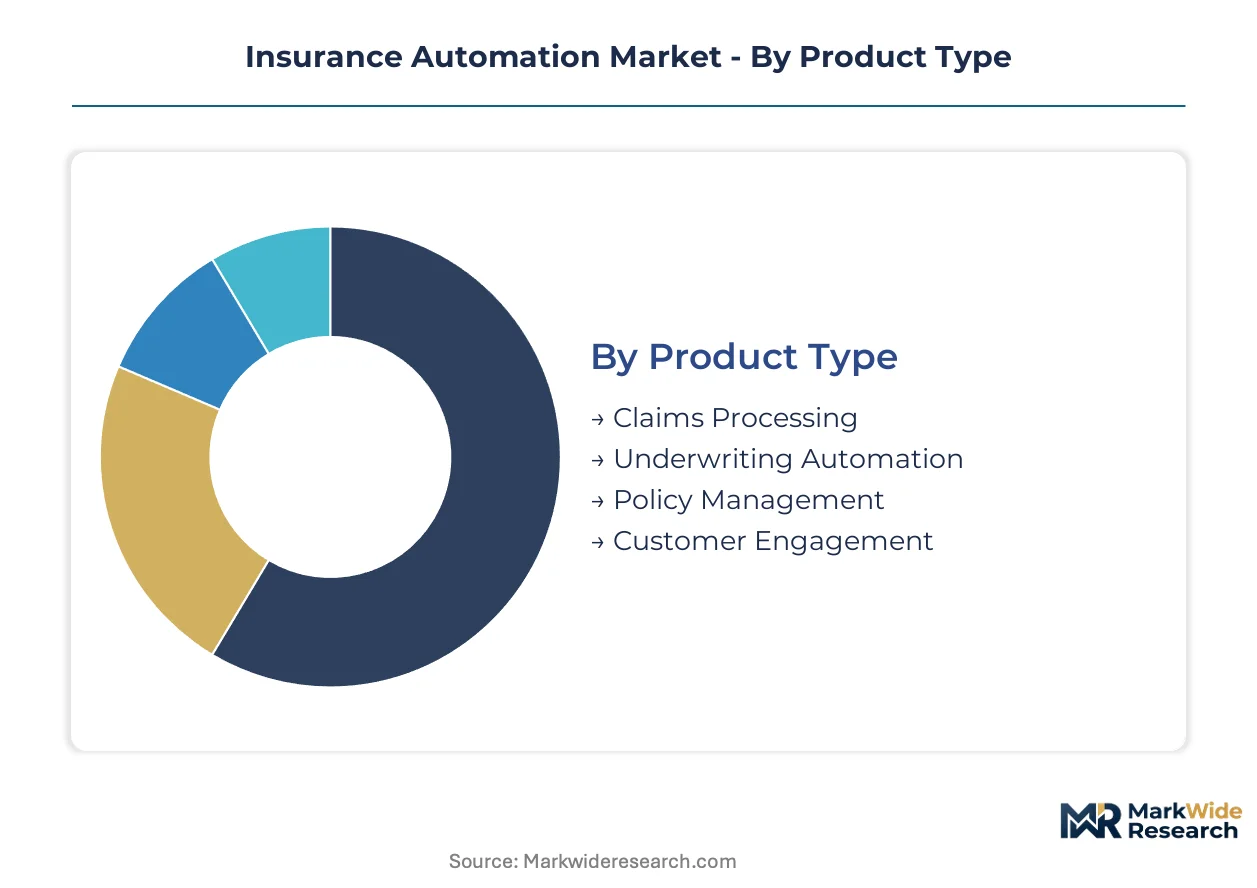
Insurance automation vendors configure their offerings across four intersecting dimensions that determine deployment complexity and revenue capture. Product type defines functional scope, technology stack dictates integration requirements, end user shapes user interface design, and service type governs ongoing revenue streams.
Product Type:
Carriers deploy automation across a spectrum from back-office adjudication to front-line policyholder interaction, with each use case demanding distinct data architectures and workflow logic.
- Claims Processing:API-orchestrated modules execute first-notice-of-loss intake, reserve setting, and payment authorization with minimal human intervention. United States property and casualty carriers prioritize this segment to compress cycle times and reduce loss adjustment expense.
- Underwriting Automation:Machine learning models ingest structured risk data and unstructured documents to generate binding authority decisions in sub-second timeframes. European carriers facing EU AI Act explainability mandates are front-loading investment in model documentation layers alongside core scoring engines.
- Policy Management:Rules engines automate endorsements, renewals, and cancellations across multi-line books of business.
- Customer Engagement:Conversational AI and self-service portals handle routine policy inquiries and certificate requests.
The dominant share belongs to Claims Processing, while Underwriting Automation is closing the gap fastest.
Technology:
Technology selection determines retrofit feasibility against legacy core systems and governs margin profiles through licensing models.
- AI Tools:Predictive analytics platforms deliver subscription-based fraud detection, pricing optimization, and churn forecasting with recurring revenue structures. United States mid-market carriers favor these tools for their ability to demonstrate ROI within single fiscal years.
- Robotic Process Automation:Software bots replicate human keystrokes across green-screen policy administration systems without requiring database rearchitecture. This technology commands the largest installed base due to its plug-and-play deployment against 1990s-era COBOL infrastructure.
- Machine Learning:Supervised and unsupervised algorithms refine risk segmentation and anomaly detection through continuous feedback loops.
- Cloud Computing:Microservices architectures enable elastic scaling of compute resources during catastrophe surge events.
Robotic Process Automation retains the broadest deployment footprint, though AI Tools are expanding most quickly through predictive analytics subscriptions.
End User:
Automation interfaces must adapt to distinct regulatory responsibilities and data access permissions across the insurance value chain.
- Insurance Providers:Carriers and mutual insurers require end-to-end platforms spanning underwriting through claims with full data sovereignty and audit trail compliance.
- Brokers:Independent and captive distribution channels need quote-comparison engines and policy issuance portals with multi-carrier connectivity.
- Financial Advisors:Wealth management hybrids demand integrated life insurance illustrations embedded within comprehensive financial planning software.
- Risk Managers:Corporate purchasers seek analytics dashboards aggregating exposure data across global property and casualty programs.
Insurance Providers consume the majority of platform licensing revenue, while Brokers are gaining share fastest through embedded distribution partnerships.
Service Type:
Vendor revenue models bifurcate between project-based professional services and recurring managed service arrangements.
- Consulting:Advisory engagements assess automation readiness, design target operating models, and map legacy system dependencies prior to procurement decisions.
- Implementation:Systems integrators configure rule engines, train machine learning models, and execute data migration cutovers with defined acceptance criteria.
- Support Services:Tiered help desks resolve production incidents and deliver periodic release updates under annual maintenance contracts.
- Managed Services:Outsourced operations teams assume responsibility for ongoing bot monitoring, model retraining, and exception queue management.
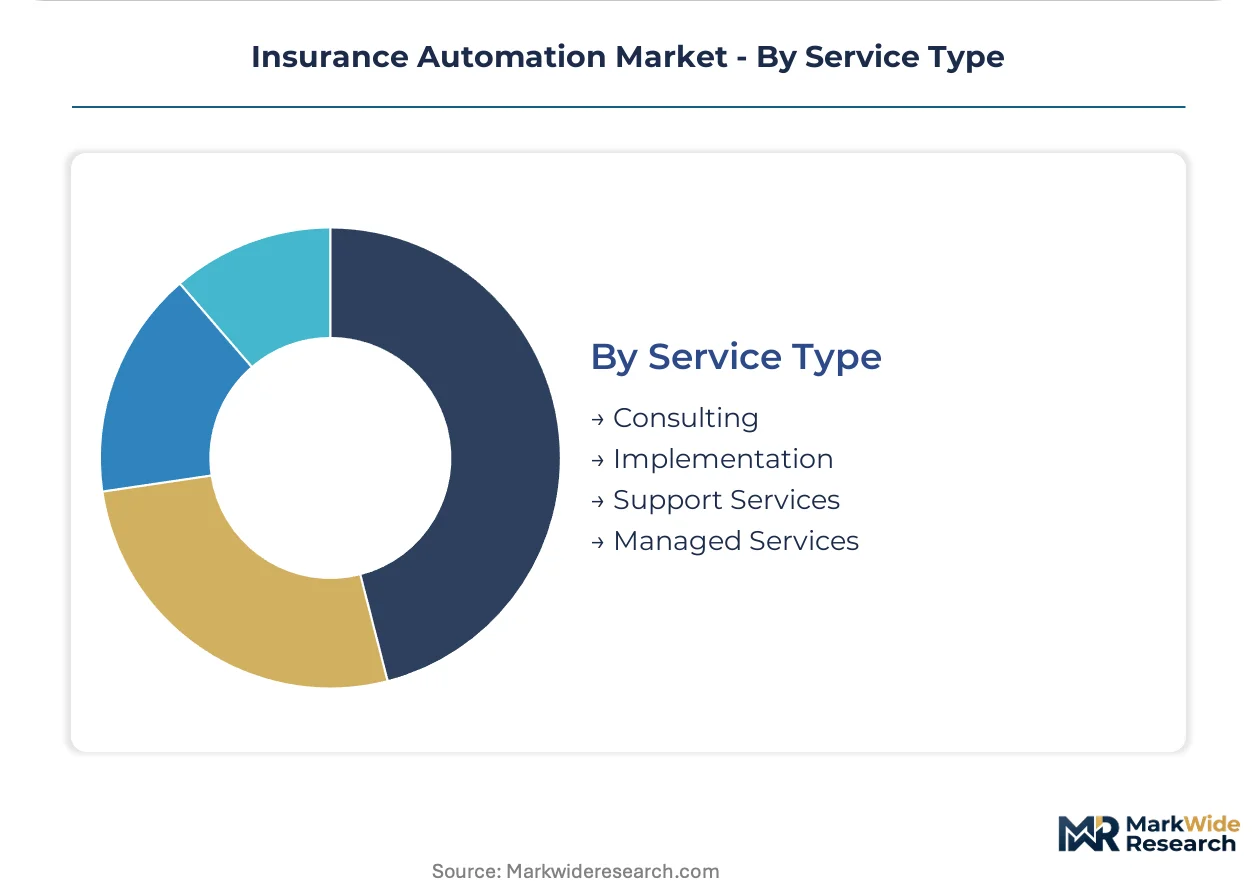
Implementation services generate the largest immediate revenue pools, while Managed Services are climbing the fastest as carriers seek to convert capital expenditures to operational budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automation software development clusters in the United States, Germany, United Kingdom, France, and India. Each concentration reflects distinct regulatory pressures and carrier modernization cycles that shape vendor deployment strategies.
United States
HIPAA mandates govern data architecture for all health insurance automation platforms, forcing vendors to build encryption layers into underwriting workflows. The FDA's software-as-medical-device guidelines intersect with wellness algorithms that trigger coverage decisions. Boston and New York financial centers host dense concentrations of actuarial data scientists validating algorithmic models for commercial carriers.
Germany
The KBA regulates telematics data used in usage-based auto insurance models that demand real-time automation infrastructure. Munich and Frankfurt insurance clusters drive procurement of explainable AI systems ahead of EU AI Act enforcement deadlines. German carriers front-load compliance investments for automated underwriting audit trails.
United Kingdom
Lloyd's of London syndicates compress claims cycle times through API-orchestrated workflows connecting legacy core systems to cloud modules. The Financial Conduct Authority scrutinizes algorithmic pricing fairness in personal lines automation. London's InsurTech corridor anchors development of fraud detection machine learning for global reinsurance programs.
France
The ANSM and CNIL impose layered compliance on health insurance automation processing medical device data and personal information. Paris-based carriers deploy human-in-the-loop overrides for adverse coverage decisions mandated by EU AI Act high-risk system classifications. French vendors specialize in model documentation tools for neural network explainability.
India
IRDAI's sandbox framework permits pilot deployments of automated claims systems without full licensing, lowering market entry barriers for foreign vendors. SEBI regulations shape data governance for insurers with bancassurance distribution. Mumbai and Bangalore technology clusters host development centers for RPA tools retrofitting 1990s-era policy administration systems.
Insurance Automation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying fraud detection modules and document extraction engines. The vendor base organizes around three strategic archetypes: end-to-end core system replacers, RPA retrofit specialists for legacy COBOL infrastructure, and AI-native point solution providers. Consolidation pressure intensifies as carriers demand unified automation layers rather than fragmented toolchains. Dominant competitive moves include strategic partnerships between RPA vendors and cloud infrastructure providers, plus vertical integration into managed services offerings.
Among the platform integrators named in raw data, Guidewire and UiPath occupy distinct positions within the automation stack. Guidewire anchors the core system replacement tier with cloud-native claims orchestration. UiPath exemplifies the RPA retrofit archetype, dominating policy administration workflows for mid-market insurers migrating from on-premise stacks. Shift Technology represents the AI-native specialist tier, competing on fraud detection modules that reduce manual review queues for carriers with limited investigative staff.
| Leading Market Players |
|---|
| UiPath |
| Formstack |
| Superblocks |
| Ushur |
| NowCerts |
| Creatio |
| Camunda |
| Guidewire |
| Shift Technology |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States and Western Europe anchors margin capture downstream, with hyperscaler compute costs determining SaaS pricing floors for automation vendors serving mid-market carriers. This upstream concentration forces pricing discipline across the vendor base as infrastructure passthrough costs dominate operational expenditure structures.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated underwriting platforms, with explainability-certified modules commanding premium positioning against basic scoring engines. Pricing stratifies across enterprise-grade compliance bundles, standard API-accessible tools, and economy RPA retrofit licenses. Cost compression in the economy tier is intensifying because Indian development centers are flooding the market with low-code automation alternatives. Mid-market United States carriers exhibit the highest price sensitivity, while Lloyd's of London syndicates prioritize audit-trail completeness over license cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent telematics modules that feed usage-based insurance automation. Component sourcing draws from Taiwan for semiconductor fabrication, India for software engineering talent, and Ireland for European data residency compliance. Single-source vulnerability concentrates in NVIDIA GPU supply for machine learning training workloads. Distribution runs through direct enterprise sales teams for carrier core systems, with systems integrators handling mid-market RPA deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial data scientists capable of validating algorithmic underwriting models represent the critical capability gap constraining vendor expansion and carrier adoption timelines. This scarcity elevates compensation costs and extends implementation cycles across the ecosystem.
For Market Incumbents: Harden explainability architectures ahead of EU AI Act enforcement deadlines to preempt compliance-driven displacement by AI-native challengers. Invest in backward integration into model documentation tooling to capture recurring revenue streams from audit-trail software mandates. Channel control through exclusive partnerships with Guidewire and Duck Creek implementation ecosystems defends against RPA vendor encroachment. For New Entrants and Emerging Players: Establish a beachhead in small commercial underwriting automation for Main Street businesses, where carrier penetration lags personal auto and homeowners segments. Target India's IRDAI sandbox environment for pilot deployments without full licensing barriers. Lead with API-first embedded insurance distribution partnerships that enable real-time policy issuance through e-commerce checkout flows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RPA retrofit specialists holding sticky mid-market carrier relationships but lacking AI-native roadmaps. Five-to-ten year viability hinges on successful cloud-native platform migration and recurring revenue conversion from project-based professional services. Monitor EU AI Act conformity assessment deadlines as inflection indicators for explainability-tooling acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UiPath's partnership with AWS Redshift accelerates claims data lake connectivity for mid-market carriers. |
| Acquisition of Specialist Firm | Consolidation of fraud detection point solutions addresses carrier demand for unified automation layers. |
| Product Launch | Guidewire's cloud-native claims orchestration release targets on-premise legacy system replacement cycles. |
| Strategic Partnership | Shift Technology's integration with Salesforce Service Cloud expands distribution through broker channels. |
| Geographic Expansion | Ushur's Mumbai development center captures IRDAI sandbox opportunities in automated claims processing. |
Research Methodology
The analysis maps claims processing automation, underwriting scoring engines, policy administration RPA, and customer engagement AI, each validated through carrier CIOs, vendor product managers, systems integration partners, and regulatory compliance officers. Primary interviews combined with secondary validation against SEC 10-K filings, IRDAI sandbox disclosures, EU AI Act implementation guidance, and carrier earnings call transcripts enabled bottom-up and top-down triangulation.
Assumptions held carrier modernization budgets and EU AI Act enforcement timelines fixed while varying cloud migration velocity and embedded insurance adoption curves across the projection horizon. Segmentation dimensions modeled include product type, technology stack, end-user archetype, and service delivery model, with CAGRs derived from vendor booking growth rates and carrier procurement pipeline analysis. Machine learning model retraining frequency and API transaction volume served as industry-specific forecast inputs.
Sensitivities concentrate around state-level algorithmic accountability statute proliferation and hyperscaler compute cost inflation. Forecasts reflect documented assumptions with explicit revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Latin America AI in Insurance Market