
 Global Digital Insurance Platform Market | 2026-2036
Global Digital Insurance Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Insurance Platform Market Foresight
North American cloud infrastructure providers is broadening the addressable base for digital insurance platforms. Guidewire Software leverages its installed base in property and casualty to sustain renewal momentum across tier-one carriers. Duck Creek Technologies anchors its competitive position through specialized configurability for mid-market insurers. Salesforce competes by extending its CRM-native architecture into policy lifecycle workflows.
A digital insurance platform constitutes an integrated software environment that automates policy origination, claims adjudication, underwriting decisioning, and customer interaction through configurable rules engines and API-orchestrated data flows. These systems typically process structured risk data against actuarial models in real time to determine pricing, reserving, and capital allocation across insurance product lines. Claims Processing platforms currently occupy the largest margin pool due to operational cost intensity and fraud detection value. Customer Engagement solutions represent the fastest-growing segment as insurers shift from transactional servicing to continuous digital relationships. Cloud-Based deployment dominates new implementations, though Hybrid architectures persist among carriers with regulatory data residency constraints.
The EU AI Act, GDPR, and state-level US regulations such as HIPAA and the NAIC model laws collectively shape platform requirements around explainable algorithms, consent management, and cross-border data governance. EIOPA's digital operational resilience framework in Europe and the SEC's cybersecurity disclosure rules for US-listed carriers are forcing vendors to embed compliance-by-design into core architectures. Stakeholders must monitor how divergent jurisdictional requirements for algorithmic accountability reshape platform standardization versus localization trade-offs.
Market Dynamics
Property and casualty carriers face intensifying pressure from the EU AI Act and GDPR compliance deadlines, forcing wholesale reconstruction of policy administration systems with embedded algorithmic auditability rather than retrofitted compliance layers.
Growth Catalysts
- Embedded AI Governance Mandates:The EU AI Act compels insurers to deploy explainable underwriting models, accelerating procurement of platforms with native compliance architectures.
- Mid-Market Digital Maturity Gaps:Regional carriers in Germany, France, and Japan lack in-house development capacity, creating concentrated demand for configurable SaaS deployments.
- Real-Time Data Orchestration:API-first platforms enable instant risk scoring against external telemetry sources, compressing quote-to-bind cycles from days to minutes.
Market Restraints
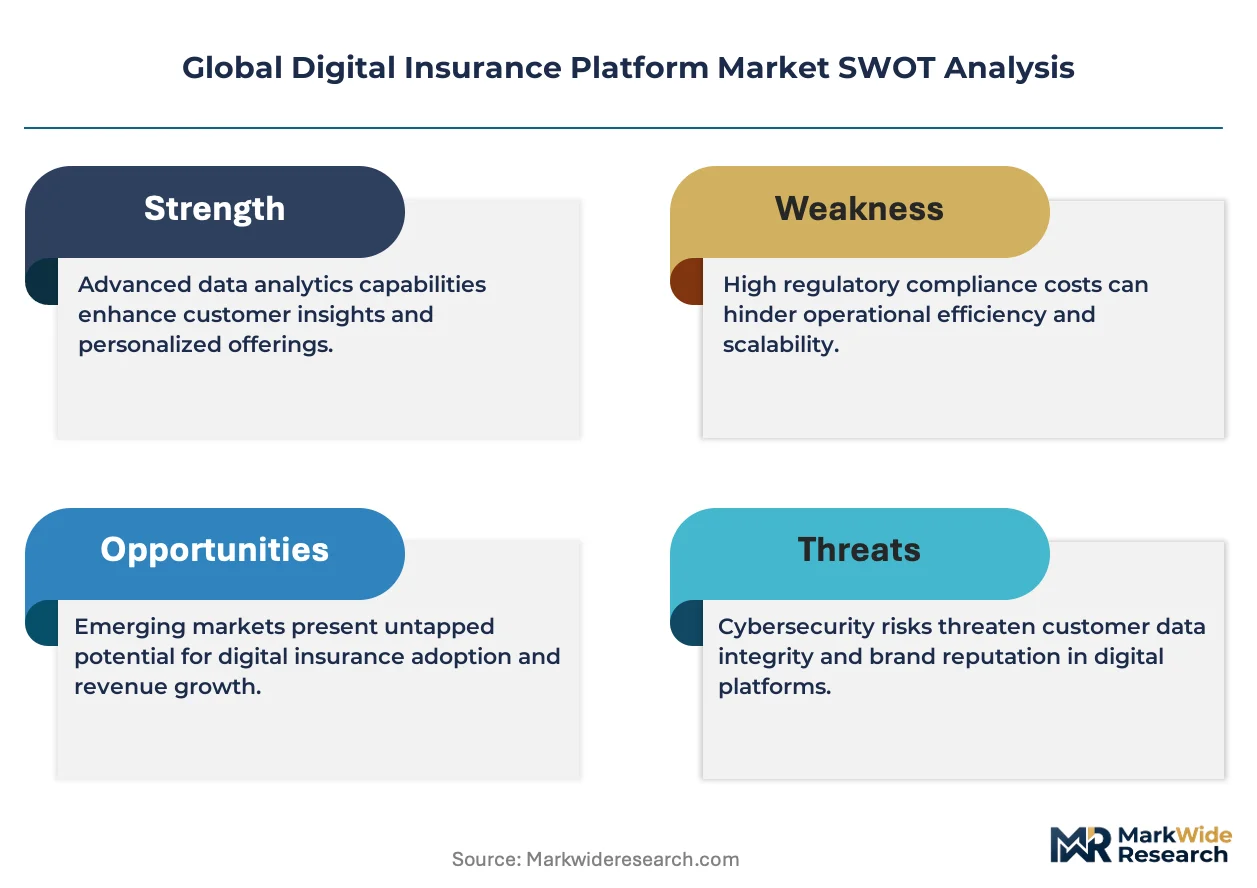
- Cloud Concentration Risk:Hyperscaler dependency for compute and storage creates single-point-of-failure exposure for tier-one carriers with systemic importance.
- Legacy System Entrenchment:COBOL-based policy cores in US and UK markets impose prohibitive migration costs and multi-year transition timelines.
- Cross-Border Data Friction:China's data localization requirements and GDPR's extraterritorial reach generate conflicting compliance obligations for multinational insurers.
Strategic Opportunities
- Parametric Insurance Expansion:Climate-linked triggers for crop and property coverage require platforms with IoT sensor integration and automated payout engines.
- Embedded Distribution Channels:Automotive OEMs and fintech wallets in South Korea and Brazil seek white-labeled insurance APIs for point-of-sale integration.
- SEC Cybersecurity Disclosures:US-listed carriers must upgrade incident response capabilities, creating demand for platforms with real-time breach detection modules.
Industry Challenges
- Actuarial-Engineering Talent Scarcity:Shortage of professionals fluent in both traditional reserving methods and machine learning model governance constrains implementation velocity.
- Interoperability Tax:Custom API bridges between modern platforms and 1980s-era claims databases consume 30-40% of implementation budgets.
- Algorithmic Bias Certification:EIOPA's emerging fairness standards require documented testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Insurance Platform Market |
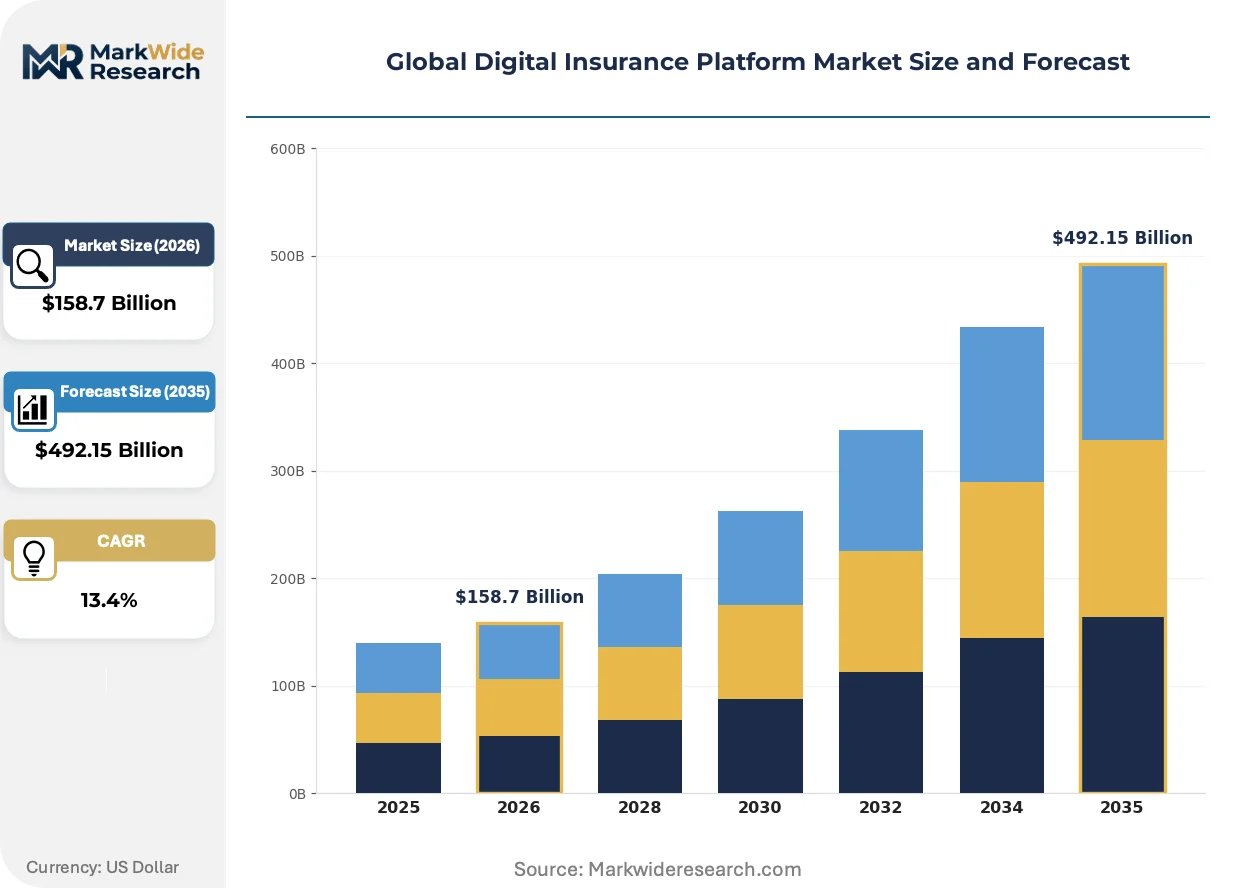
| Market Size in 2026 | $158.7 Billion |
| Market Size in 2035 | $492.15 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Policy Management, Claims Processing, Underwriting, Customer Engagement, Analytics, Risk Assessment Application: Life Insurance, Property & Casualty, Health Coverage, Commercial Insurance, Specialty Lines, Microinsurance Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, API-Driven, Edge Computing End User: Insurers, Reinsurers, Brokers, Agents, Third-Party Administrators, Risk Managers |
| Companies Covered | Guidewire Software, Duck Creek Technologies, Salesforce, Oracle, Microsoft, SAP, IBM, Pegasystems, Majesco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Insurance Platform Market Shifts & Advancements
Distributed ledger architectures and ambient computing interfaces are compressing the latency between risk event detection and capital deployment, reshaping how carriers structure products and reserve capital.
Telematics fusion with computer vision is electrifying usage-based auto and property underwriting. German and Japanese carriers now ingest continuous vehicle sensor streams and drone imagery for dynamic premium adjustment. This convergence collapses the distinction between risk assessment and loss prevention, shifting carrier value propositions from post-event reimbursement to real-time hazard mitigation.
The EU AI Act's risk-based classification system imposes mandatory human oversight on high-stakes underwriting algorithms. European carriers must reconstruct decision trees with auditable intervention points. This regulatory architecture is accelerating adoption of "glass-box" machine learning frameworks in life and health segments, displacing opaque neural network approaches that dominated prior investment cycles.
Carriers in the United States and United Kingdom are unbundling monolithic platform contracts into componentized microservices procurement. Risk teams now license claims modules, policy engines, and customer portals from distinct vendors, integrating via open API standards. This fragmentation shifts vendor relationships from decade-long lock-in to annual renewal cycles based on feature velocity and interoperability performance.
Global Digital Insurance Platform Market Segmentation
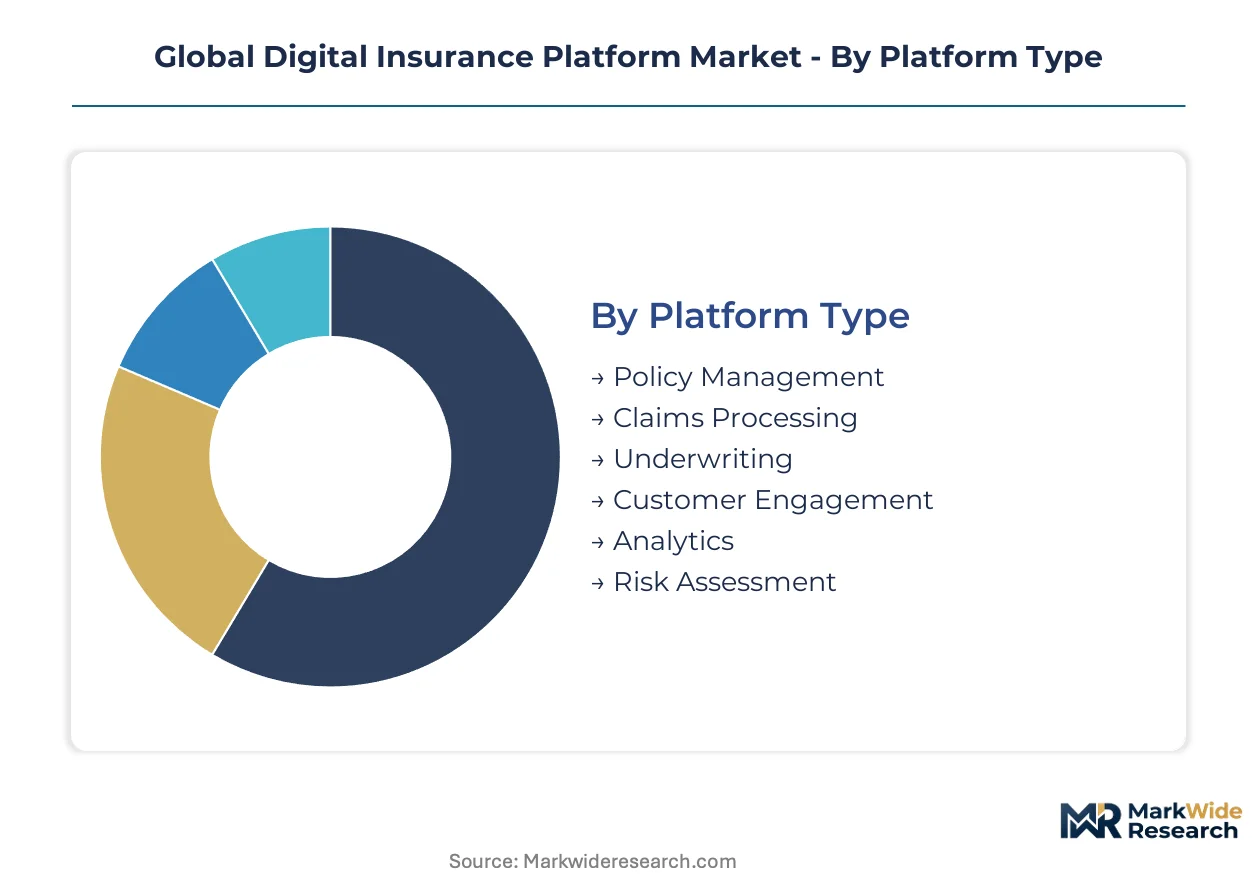
Segmentation reveals how procurement patterns diverge across platform architectures and user maturity levels. Carriers prioritize deployment models that reconcile regulatory data residency with API flexibility, while end-user type determines whether implementations target core system replacement or peripheral workflow automation.
Platform Type:
EIOPA's digital operational resilience framework and the SEC's cybersecurity disclosure rules impose distinct certification burdens: Claims Processing and Underwriting modules require algorithmic auditability documentation, while Customer Engagement platforms face lighter consent-management scrutiny.
- Claims Processing:Automated adjudication engines ingest structured loss data against fraud detection models and reserve allocation algorithms. Demand concentrates among US property and casualty carriers modernizing legacy COBOL cores to meet NAIC model law requirements for real-time breach detection.
- Customer Engagement:Continuous digital relationship platforms deploy personalized interaction workflows across policy lifecycle touchpoints. German and French regional insurers lacking in-house development capacity drive SaaS procurement for configurable portal architectures.
- Policy Management:Core administration systems automating issuance, endorsements, and renewals through rules-based engines.
- Underwriting:Real-time risk scoring platforms integrating external telemetry for dynamic pricing decisions.
- Analytics:Capital allocation and reserving optimization tools processing actuarial datasets against regulatory capital frameworks.
- Risk Assessment:Exposure quantification modules linking IoT sensor streams to parametric trigger mechanisms.
Leading the category by volume: Claims Processing. Growing fastest: Customer Engagement.
Application:
Cost tier structures diverge sharply: Property and Casualty implementations command premium pricing due to multi-line complexity and catastrophe modeling requirements, while Microinsurance deployments prioritize stripped-down mobile-first architectures at economy tier points.
- Property & Casualty:Multi-peril coverage platforms integrating catastrophe models, reinsurance treaties, and IoT telemetry for dynamic premium adjustment. US tier-one carriers dominate procurement volume as systemic importance designations drive integrated platform investments.
- Health Coverage:Patient data exchange platforms embedding HIPAA consent management and pre-authorization automation. Demand clusters around US integrated delivery networks and German sickness funds modernizing legacy claims corridors.
- Life Insurance:Mortality risk assessment platforms with accelerated underwriting and digital policy issuance capabilities.
- Commercial Insurance:Mid-market and large-account platforms supporting complex multi-national coverage structures.
- Specialty Lines:Niche coverage platforms for marine, aviation, and cyber risks requiring bespoke rating algorithms.
- Microinsurance:Low-touch mobile distribution platforms targeting emerging market informal sector penetration.
Highest implementation spend: Property & Casualty. Steepest expansion trajectory: Microinsurance via embedded distribution partnerships.
Deployment Model:
Volume concentration favors Cloud-Based architectures among digitally native carriers, while Hybrid deployments persist where GDPR Article 44 cross-border transfer mechanisms or China's data localization requirements constrain pure SaaS adoption.
- Cloud-Based:Hyperscaler-hosted environments delivering elastic compute for actuarial batch processing and real-time API orchestration. Japanese and South Korean carriers lead new implementation volume, leveraging domestic cloud availability zones for latency-sensitive underwriting.
- Hybrid:Split architectures retaining sensitive policy data on-premises while exposing customer-facing services via cloud edge nodes. EU carriers with UK legacy operations deploy this model to reconcile divergent post-Brexit data governance regimes.
- On-Premises:Captive data center deployments for carriers with systemic importance designations and regulatory capital constraints.
- SaaS:Multi-tenant configurable platforms targeting mid-market insurers without dedicated infrastructure teams.
- API-Driven:Headless architectures enabling componentized procurement from multiple vendors via open standards.
- Edge Computing:Distributed processing nodes for telematics-intensive usage-based auto and parametric property applications.
Dominant deployment mode: Cloud-Based. Gaining share fastest: API-Driven microservices procurement.
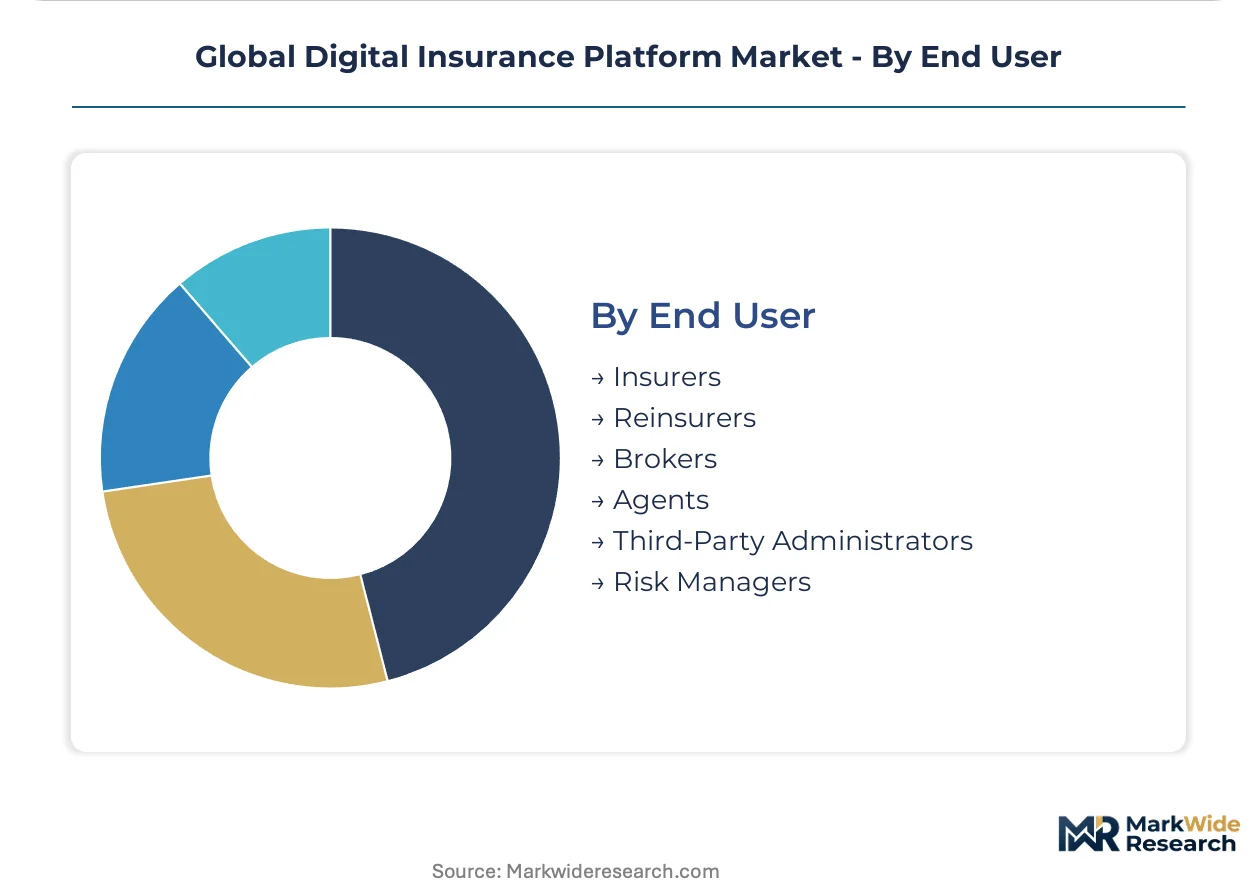
End User:
Customer type determines platform complexity tiers: Insurers procure full-stack core replacements, while Brokers and Agents license lightweight quote-bind portals with reduced configuration overhead.
- Insurers:Primary carriers acquiring end-to-end policy lifecycle platforms with embedded regulatory compliance modules. US and UK tier-one carriers anchor demand through decade-long modernization programs replacing 1980s-era administration systems.
- Brokers:Intermediary platforms aggregating multi-carrier quoting and placement workflows. Lloyd's coverholders and US wholesale brokers drive procurement for submission automation and market connectivity tools.
- Reinsurers:Treaty and facultative platforms with catastrophe exposure aggregation and retrocession management capabilities.
- Agents:Captive and independent agent portals with streamlined application intake and commission tracking features.
- Third-Party Administrators:Claims servicing platforms for self-insured employers and captives outsourcing operational functions.
- Risk Managers:Enterprise insurance buyers deploying analytics dashboards for coverage optimization and loss forecasting.
Largest procurement volume: Insurers. Expanding most quickly: Brokers through embedded distribution API partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density in Northern Virginia anchors North American platform deployment capacity, while regulatory divergence between Washington and Brussels fragments data governance architectures.
United States
Tier-one property and casualty carriers drive procurement volume through systemic importance designations and NAIC model law compliance deadlines. The SEC's cybersecurity disclosure rules for listed carriers mandate real-time breach detection modules. Hartford and Boston insurance technology clusters concentrate vendor implementation teams serving legacy modernization programs.
Germany
Regional insurers lacking in-house development capacity create concentrated demand for configurable SaaS deployments. The EU AI Act's risk-based classification system imposes mandatory human oversight on high-stakes underwriting algorithms. Munich and Frankfurt financial centers host implementation hubs for glass-box machine learning frameworks displacing opaque neural network approaches.
United Kingdom
Lloyd's coverholders and wholesale brokers accelerate procurement for submission automation and market connectivity tools. Post-Brexit divergence from EU data governance regimes forces hybrid deployment architectures reconciling UK legacy operations with continental requirements. London's insurance market cluster drives API-first platform unbundling into componentized microservices procurement.
Japan
Domestic cloud availability zones enable latency-sensitive underwriting implementations for telematics-intensive usage-based auto coverage. METI's operational resilience guidelines shape platform certification requirements for systemic carriers. Tokyo and Osaka insurance technology corridors concentrate vendor partnerships for legacy policy administration replacement.
South Korea
Automotive OEMs and fintech wallets seek white-labeled insurance APIs for point-of-sale embedded distribution integration. The country's data localization framework constrains pure SaaS adoption, favoring hybrid architectures with domestic edge nodes. Seoul's digital finance cluster anchors platform development partnerships targeting parametric insurance expansion.
Global Digital Insurance Platform Market Competitive Landscape
Global majors compete with regional champions across compliance architecture depth and API configurability. The vendor base stratifies into three tiers: hyperscaler-backed platforms with native cloud infrastructure, specialized insurance software houses with decades of policy domain expertise, and CRM-native entrants extending customer relationship architectures into core underwriting workflows. Dominant competitive moves include vertical integration into telematics data streams and strategic partnerships with automotive OEMs for embedded distribution channels.
Within the specialized insurance software tier, Guidewire Software and Duck Creek Technologies exemplify contrasting scale-positioning strategies, while Salesforce occupies a position bridging CRM-native engagement layers with policy lifecycle automation. These three anchors represent divergent bets on whether carriers prioritize end-to-end platform consolidation or componentized best-of-breed procurement.
| Leading Market Players |
|---|
| Guidewire Software |
| Duck Creek Technologies |
| Salesforce |
| Oracle |
| Microsoft |
| SAP |
| IBM |
| Pegasystems |
| Majesco |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU AI Act-compliant platforms and legacy configurations manifests in both pricing power and supply chain sourcing strategies. Premium-tier vendors command sustained margins through embedded auditability architectures, while economy-tier providers face cost compression from interoperability tax burdens and talent scarcity.
Pricing Analysis
Implementation-support bundling separates full-service deployment contracts from unbundled software licenses with third-party integration costs. Three-tier pricing structure across premium, standard, and economy levels reflects algorithmic auditability certification depth and geographic data residency compliance. Pricing pressure stems from mid-market carriers consolidating vendor relationships amid renewal cycle compression. Regional insurers in Germany and France exhibit highest price sensitivity due to in-house development capacity gaps, while US tier-one carriers prioritize compliance architecture over unit cost.
Supply Chain Analysis
Cross-border data transfer costs concentrate platform development capacity in the United States, Germany, and Japan, with hyperscaler availability zones anchoring cloud infrastructure deployment. Core supply draws from specialized actuarial-engineering talent pools, API middleware providers, and regulatory compliance consulting networks. Single-source vulnerability runs through concentrated hyperscaler dependencies for compute and storage. Distribution runs through direct enterprise sales teams serving tier-one carriers, supplemented by systems integrator partnerships for mid-market SaaS deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where the EU AI Act creates a substantial barrier-to-entry moat for platforms with native algorithmic auditability, marginalizing retrofitted competitors.
For Market Incumbents: Cement renewal momentum through glass-box machine learning framework investments that preempt EIOPA fairness certification requirements. Lock in tier-one carrier relationships with embedded IoT telemetry integration for parametric insurance expansion. Defensive positioning against API-first microservices fragmentation demands demonstrating superior interoperability performance against best-of-breed component stacks. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized compliance-native architectures targeting regional carriers lacking legacy system entanglement. White-labeled insurance APIs for automotive OEM embedded distribution channels in South Korea and Brazil represent the most penetrable white-space. Go-to-market execution should prioritize configurable SaaS deployments with rapid implementation timelines against mid-market digital maturity gaps. For Investors and Strategic Acquirers: Re-rating potential sits with specialized insurance software houses given accelerating procurement from property and casualty carriers facing NAIC model law deadlines. Long-term viability favors vendors with demonstrated glass-box machine learning deployments and established hyperscaler partnerships. Monitor EIOPA algorithmic bias certification timeline acceleration as the critical inflection signal for platform standardization versus localization trade-offs.| Strategic Initiative | Industry Significance |
|---|---|
| Glass-Box ML Framework Deployment | EU AI Act compliance architecture displaces opaque neural network approaches in life and health underwriting segments. |
| IoT Telemetry Integration | Parametric insurance expansion requires automated payout engines linking sensor streams to climate-linked triggers. |
| API-First Microservices Unbundling | Lloyd's coverholders and US wholesale brokers drive procurement for submission automation and market connectivity tools. |
| Hybrid Cloud Architecture Investment | GDPR Article 44 cross-border transfer mechanisms and China's data localization requirements constrain pure SaaS adoption. |
| Embedded Distribution Partnership | Automotive OEMs and fintech wallets in South Korea and Brazil seek white-labeled insurance APIs for point-of-sale integration. |
Research Methodology
Multi-period observation of platform procurement cycles, regulatory compliance deadlines, and vendor implementation timelines anchored the trend analysis, supplemented by interviews with insurance technology executives, actuarial officers, regulatory affairs leads, and systems integration specialists. Secondary validation drew from SEC cybersecurity disclosure filings, EIOPA digital operational resilience frameworks, NAIC model law updates, and hyperscaler capex disclosures. Bottom-up carrier spending patterns and top-down market sizing were triangulated to establish volume and value estimates.
Input-output matrices modeled deployment model adoption, platform type procurement velocity, end-user digital maturity, and regional regulatory divergence across the projection horizon. CAGRs were derived from carrier modernization program announcements, vendor booking disclosures, and compliance-driven replacement cycle acceleration. Industry-specific forecast inputs included EU AI Act implementation phase transitions and NAIC model law state adoption trajectories.
The model assumes a particular technology adoption path; alternative pathways for glass-box machine learning or distributed ledger architectures would alter the outlook. Forecasts reflect assumptions around regulatory deadline adherence, hyperscaler infrastructure availability, and actuarial-engineering talent supply elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Insurance Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Japan AI in Insurance Market