
 UK Insurtech Market | 2026-2036
UK Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
UK Insurtech Market Analytics
Actuarial data science talent scarcity is reorganizing competitive dynamics across the UK Insurtech Market. Ki Insurance leverages Lloyd's syndicate infrastructure to sustain delegated authority platforms. ManyPets anchors pet health subscription models that compete against legacy annual policies. Tractable differentiates through computer vision claims automation that reduces loss-adjustment cycle times.
UK Insurtech encompasses technology-enabled insurance distribution, underwriting, and claims management platforms operating under Financial Conduct Authority authorization, typically integrating application programming interfaces with legacy core systems to enable real-time risk pricing and policy issuance. The sector's primary commercial purpose centers on reducing acquisition costs and improving loss ratios through algorithmic decisioning. Health Insurance product lines command premium pricing power due to chronic condition management integrations, while Claims Processing services capture recurring software revenue streams. AI Analytics technology layers are attracting disproportionate venture allocation relative to blockchain infrastructure.
The Financial Conduct Authority's consumer duty regime and Prudential Regulation Authority solvency standards jointly determine capital requirements and product governance obligations for UK insurtech authorizations. The Information Commissioner's Office GDPR enforcement shapes data architecture investments across customer onboarding and claims evidence handling. Stakeholders must monitor how the Bank of England's digital pound consultations could reshape premium collection rails and smart contract settlement mechanics.
Market Dynamics
The Financial Conduct Authority's consumer duty regime is forcing a fundamental reorganization of product governance across UK insurtech distribution channels. This regulatory pressure is compressing legacy commission structures while elevating algorithmic transparency requirements for real-time pricing engines.
Growth Catalysts
- Telematics penetration in commercial motor fleets:Usage-based insurance models are capturing risk data from connected vehicle sensors, enabling dynamic premium adjustments based on actual driving behavior rather than static demographic proxies.
- Open Banking APIs:The UK's regulatory framework for financial data sharing is streamlining customer onboarding and enabling automated underwriting decisions through real-time income and transaction verification.
- GDPR-compliant data architectures:Investments in privacy-preserving analytics are unlocking granular risk segmentation while maintaining Information Commissioner's Office enforcement alignment.
Market Restraints
- Actuarial data science talent scarcity:The intersection of statistical modeling and machine learning expertise commands premium compensation, compressing margins for mid-scale insurtech authorizations.
- Lloyd's syndicate infrastructure dependency:Delegated authority platforms require costly capital backing arrangements, concentrating market access among well-capitalized participants.
- Legacy core system integration friction:Policy administration system modernization demands substantial technical debt remediation before API-layer connectivity achieves operational stability.
Strategic Opportunities
- Pet health subscription models:Recurring revenue structures are displacing traditional annual policy renewal cycles in companion animal coverage, capturing lifetime customer value through preventive care integrations.
- Computer vision claims automation:Damage assessment algorithms are reducing loss-adjustment cycle times in motor and property lines, creating software-as-a-service revenue streams beyond underwriting.
- Manchester tech corridor expansion:Lower operational costs relative to London's underwriting cluster are attracting venture-stage insurtech infrastructure investments and engineering talent migration.
Industry Challenges
- Prudential Regulation Authority solvency calibration:Capital requirement modeling for algorithmic underwriting portfolios lacks established actuarial standards, creating authorization timeline uncertainty.
- Smart contract settlement mechanics:Blockchain-based policy execution faces interoperability gaps with traditional payment rails, delaying parametric insurance product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Insurtech Market |
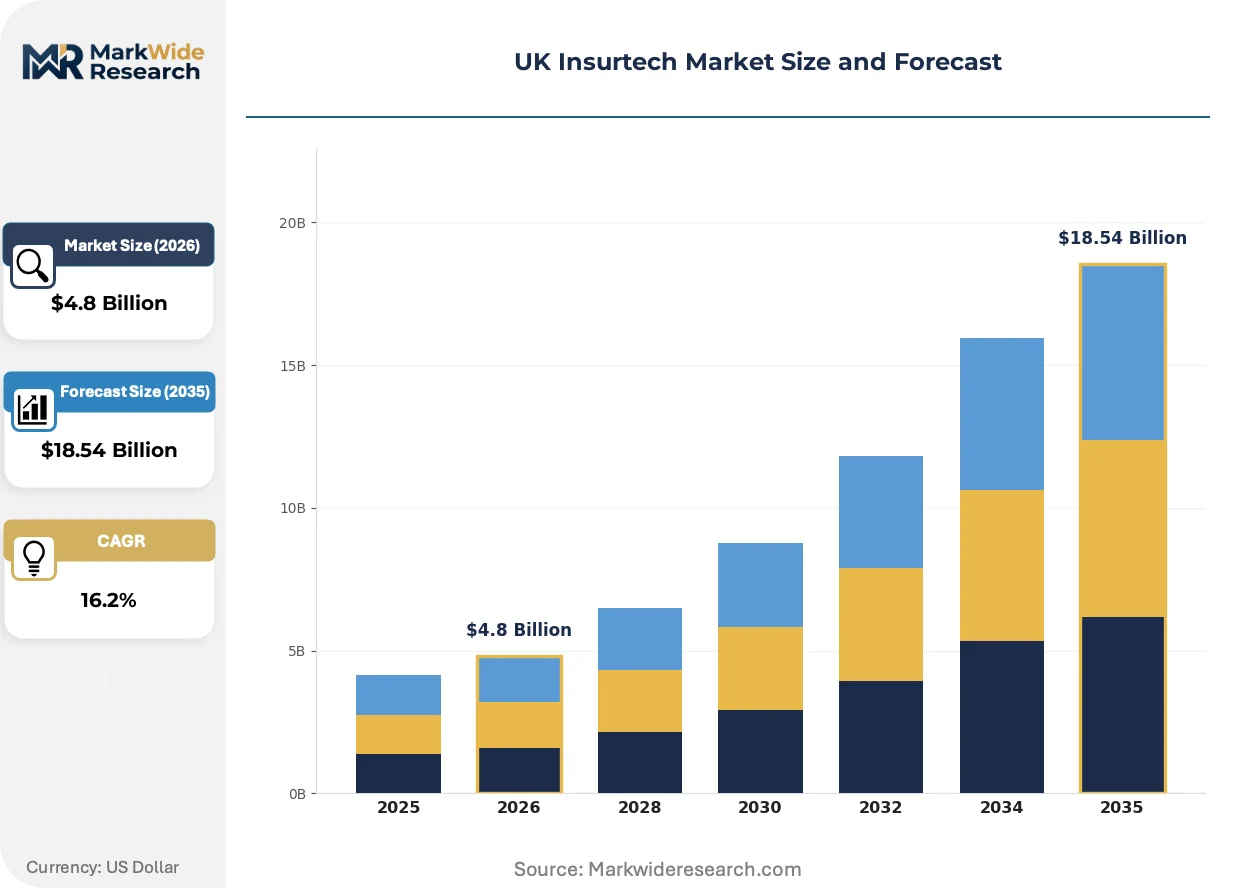
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Auto Insurance, Property Insurance, Travel Insurance Service Type: Policy Management, Claims Processing, Risk Assessment, Underwriting Technology: Blockchain, AI Analytics, Machine Learning, IoT Solutions Customer Type: Individuals, Small Businesses, Corporations, Startups |
| Companies Covered | Ki Insurance, ManyPets, Zego, Marshmallow, YuLife, Tractable, Superscript, BIMA, Cytora, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Insurtech Market Evolving Landscape
Algorithmic decisioning architectures are fragmenting traditional value chains across UK insurance distribution. Three developments are compressing incumbent competitive advantages while elevating platform-based business models.
Embedded insurance distribution through API-native partnerships is fragmenting the customer acquisition landscape. Retail banking applications and automotive point-of-sale platforms are integrating policy issuance workflows directly into transaction journeys. This disintermediation is compressing aggregator commission pools while shifting premium volume toward technology-enabled managing general agents.
The Financial Conduct Authority's consumer duty rules are mandating outcome-focused product design across all retail insurance lines. Firms must demonstrate fair value assessment through explicit price-to-benefit ratios and vulnerability detection protocols. Digital-first insurers are responding by deploying natural language processing for policy documentation simplification, while legacy carriers face substantial marketing material overhaul costs.
Commercial fleet operators are consolidating procurement authority into centralized risk management functions, bypassing traditional broker relationships. Direct platform access to usage-based coverage is displacing annual policy negotiations in logistics and passenger transport verticals. This concentration is most visible among last-mile delivery networks operating across Greater London and the West Midlands, where telematics-enabled premium reductions are driving carrier switching behavior.
UK Insurtech Market Segmentation
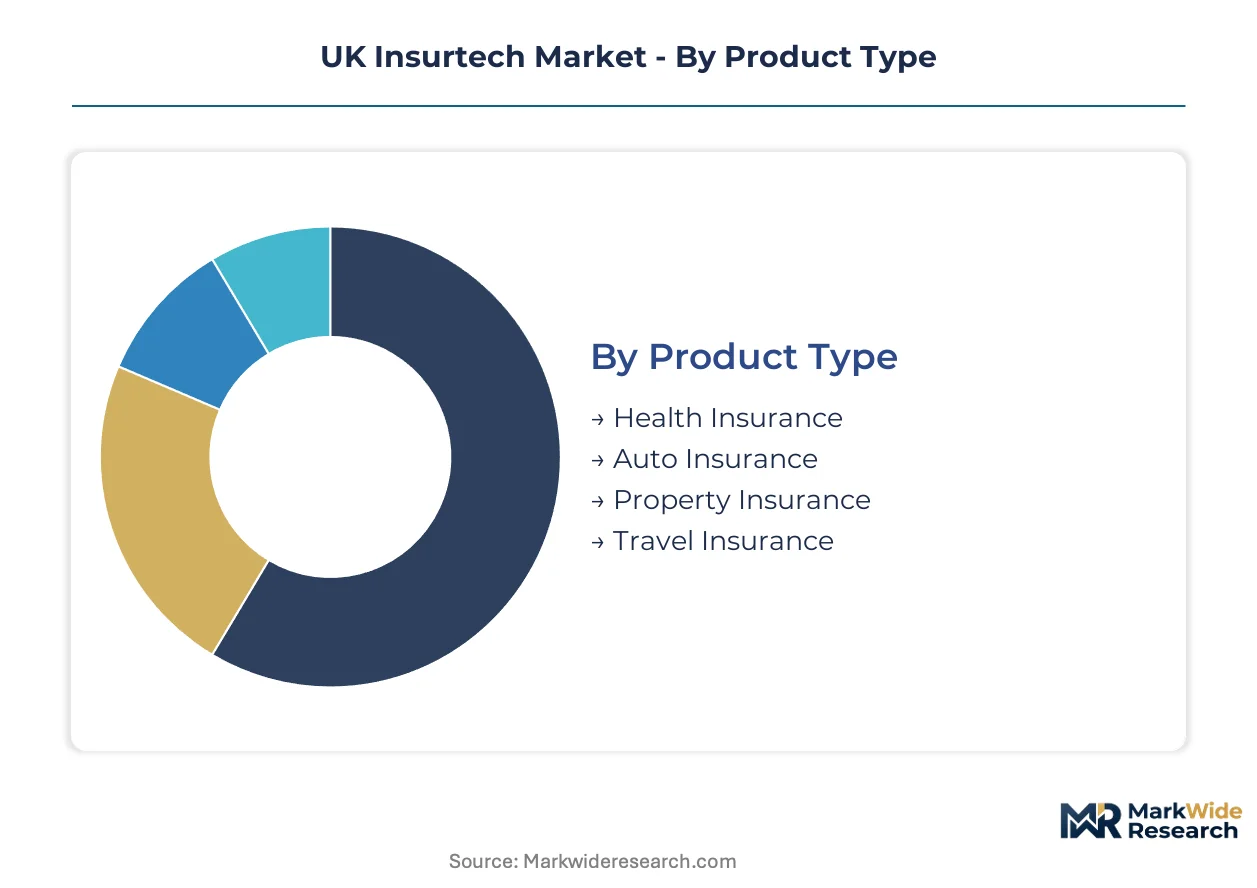
Segmentation reveals how UK Insurtech value pools concentrate across product architectures and technology layers. Distribution channel strategies and capital efficiency requirements vary substantially across these divides, reshaping authorization pathways and partnership priorities.
Product Type:
Health Insurance faces acute substitution pressure from NHS digital-first services and employer-sponsored wellness platforms, compressing standalone policy margins.
- Health Insurance:Chronic condition management integrations and preventive care data feeds command premium pricing power. Demand concentrates among London's financial services workforce and Manchester's tech corridor employees seeking supplemental coverage beyond NHS wait times.
- Auto Insurance:Telematics-enabled usage-based models are displacing traditional annual policies in commercial fleets. Risk data from connected vehicle sensors enables dynamic premium adjustments based on actual driving behavior rather than static demographic proxies.
- Property Insurance:Smart home sensor integrations enable real-time risk monitoring and parametric trigger designs.
- Travel Insurance:Embedded distribution through airline and booking platform APIs fragments traditional aggregator channels.
Health Insurance retains volume leadership; Auto Insurance holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates capital-intensive underwriting infrastructure from software-margin claims services.
- Claims Processing:Computer vision automation reduces loss-adjustment cycle times in motor and property lines. Recurring software revenue streams attract venture allocation disproportionate to underwriting capital requirements.
- Underwriting:Algorithmic decisioning platforms require substantial actuarial data science investment and Lloyd's syndicate capital backing. The Financial Conduct Authority's consumer duty rules mandate explicit price-to-benefit transparency for real-time pricing engines.
- Policy Management:API-native policy administration systems demand legacy core system integration investment before operational stability.
- Risk Assessment:Open Banking data feeds and IoT sensor streams enable granular segmentation beyond traditional credit scoring.
Claims Processing captures the highest margin expansion; Underwriting demands the heaviest capital deployment.
Technology:
Application maturity separates production-grade AI deployments from experimental blockchain infrastructure.
- AI Analytics:Natural language processing simplifies policy documentation for consumer duty compliance. Privacy-preserving architectures maintain Information Commissioner's Office alignment while unlocking granular risk segmentation.
- Machine Learning:Predictive models for fraud detection and pricing optimization command premium talent compensation. Demand concentrates among delegated authority platforms seeking algorithmic transparency for Lloyd's syndicate relationships.
- IoT Solutions:Connected vehicle and property sensor networks feed real-time underwriting data streams.
- Blockchain:Smart contract settlement mechanics face interoperability gaps with traditional payment rails, delaying parametric product launches.
AI Analytics dominates current investment flows; Machine Learning is gaining share fastest among authorized insurers.
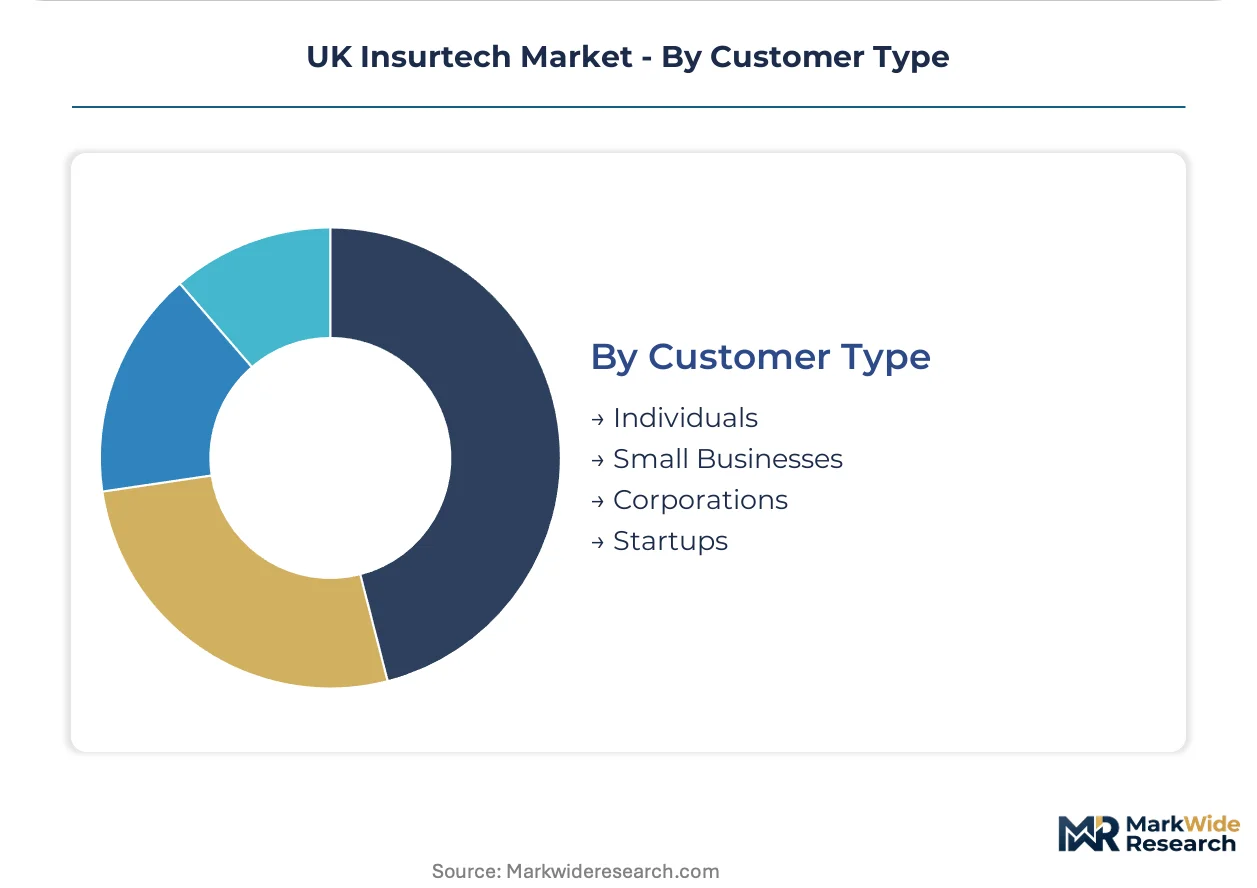
Customer Type:
Volume concentration tracks procurement centralization trends across risk management functions.
- Corporations:Centralized risk management functions bypass traditional broker relationships for direct platform access. Commercial fleet operators in Greater London and the West Midlands consolidate procurement authority into usage-based coverage negotiations.
- Small Businesses:Embedded insurance through retail banking APIs streamlines onboarding with automated underwriting decisions. Lower operational costs in Manchester's tech corridor attract venture-stage infrastructure targeting this segment.
- Individuals:Pet health subscription models and travel micro-policies displace traditional annual renewal cycles.
- Startups:Early-stage ventures face actuarial data scarcity and limited loss history for algorithmic pricing.
Corporations anchor premium volume; Small Businesses are expanding most quickly through embedded distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's underwriting cluster consumes insurtech infrastructure differently from Manchester's emerging tech corridor, with the former prioritizing delegated authority platforms and the latter favoring embedded distribution APIs for small business segments.
Greater London
Commercial fleet operators and Lloyd's syndicate partnerships drive concentrated demand for usage-based motor coverage and algorithmic underwriting platforms. The Financial Conduct Authority's consumer duty rules mandate explicit price-to-benefit transparency for real-time pricing engines deployed across the capital. The City of London and Canary Wharf financial districts anchor Ki Insurance's delegated authority infrastructure and Tractable's computer vision claims operations.
Manchester Tech Corridor
Lower operational costs attract venture-stage insurtech infrastructure targeting small business embedded distribution through retail banking APIs. The Information Commissioner's Office GDPR enforcement shapes privacy-preserving analytics investments across customer onboarding workflows. Spinningfields and MediaCityUK concentrate engineering talent migration from London, with ManyPets anchoring pet health subscription model development.
West Midlands
Last-mile delivery networks and logistics operators consolidate procurement authority into centralized risk management functions bypassing traditional brokers. Telematics-enabled premium reductions drive carrier switching behavior among commercial fleet operators. Birmingham's enterprise zone supports Zego's usage-based commercial motor platform expansion.
Scotland
Edinburgh's financial services heritage sustains demand for policy management and risk assessment software serving institutional insurance clients. The Prudential Regulation Authority's solvency standards influence capital requirement modeling for algorithmic underwriting portfolios seeking authorization. The Edinburgh-Glasgow corridor attracts actuarial data science talent for predictive modeling development.
South East England
Affluent commuter belts outside London generate demand for supplemental health insurance beyond NHS wait times. YuLife's employer-sponsored wellness platforms capture corporate benefit budgets across Thames Valley technology employers. Reading and Oxford concentrate health-tech integration partnerships linking wearable data to preventive care coverage pricing.
UK Insurtech Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding Lloyd's syndicate capital backing and the latter capturing niche segments through API-native distribution. The market structure reflects pronounced tiering between delegated authority platforms requiring substantial regulatory authorization and embedded insurance specialists operating through partnership layers. Two strategic archetypes dominate: managing general agents leveraging algorithmic underwriting transparency and subscription-model insurers capturing lifetime customer value through preventive care integrations. Competitive dynamics center on M&A activity consolidating mid-scale authorizations and strategic partnerships embedding policy issuance into retail banking and automotive point-of-sale workflows.
Within the delegated authority tier, Ki Insurance and Tractable exemplify divergent infrastructure plays, with the former representing syndicate-backed underwriting platforms and the latter occupying a position in computer vision claims automation. ManyPets anchors the subscription-model archetype, sitting within the pet health segment where recurring revenue structures displace traditional annual policy renewals. These three companies collectively illustrate how capital efficiency requirements and regulatory authorization timelines stratify competitive positioning across the UK market.
| Leading Market Players |
|---|
| Ki Insurance |
| ManyPets |
| Zego |
| Marshmallow |
| YuLife |
| Tractable |
| Superscript |
| BIMA |
| Cytora |
| Others |
Value Network & Pricing Analysis
The Financial Conduct Authority's consumer duty regime gates both supply qualification and price differentiation across UK insurtech distribution channels. Firms must demonstrate fair value assessment through transparent price-to-benefit ratios before accessing Lloyd's syndicate capital backing or retail banking API partnerships.
Pricing Analysis
Subscription-based recurring revenue models dominate pricing structures across pet health and embedded insurance segments. Price differentiation stems from algorithmic transparency tiering and preventive care integration depth. Cost compression in mid-scale underwriting operations intensifies because actuarial data science talent scarcity commands premium compensation. Small business segments exhibit highest price sensitivity through embedded distribution channels, while corporate fleet operators prioritize usage-based premium reductions over absolute cost.
Supply Chain Analysis
The United Kingdom and Ireland anchor Lloyd's syndicate capital infrastructure and delegated authority platform development. The supply chain draws from cloud computing infrastructure providers, connected vehicle sensor manufacturers, and Open Banking API aggregators. Single-source vulnerability concentrates in legacy core system integration partnerships, where policy administration modernization demands substantial technical debt remediation. Distribution runs through managing general agent networks, retail banking partnerships, and direct platform access for commercial fleet procurement centralization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHS digital-first service expansion threatens standalone health insurance margins, forcing incumbents to defend subscription-model customer lifetime value against preventive care platform substitution.
For Market Incumbents: Consolidate algorithmic underwriting capabilities through Lloyd's syndicate capital backing arrangements. Deepen vertical integration into computer vision claims automation to capture software-as-a-service revenue streams beyond traditional underwriting margins. Acquire delegated authority platforms in Manchester's tech corridor to offset London operational cost premiums. For New Entrants and Emerging Players: Lead with embedded insurance distribution through retail banking APIs targeting small business segments in Manchester and the West Midlands. Capture white-space opportunity in pet health subscription models where ManyPets has validated recurring revenue structures. Deploy Open Banking-enabled automated underwriting to compress customer onboarding cycle times against legacy annual policy renewal friction. For Investors and Strategic Acquirers: The Financial Conduct Authority's consumer duty implementation reshapes the acquisition landscape toward algorithmic transparency and fair value demonstration. Target managing general agents with production-grade AI analytics and established Lloyd's relationships over experimental blockchain infrastructure plays. Monitor Prudential Regulation Authority solvency calibration guidance as the critical signal for authorization timeline certainty and capital deployment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Platform Development | Enables real-time pricing transparency required by Financial Conduct Authority consumer duty rules. |
| Delegated Authority Syndicate Partnership | Secures Lloyd's capital backing for mid-scale insurtech authorization pathways. |
| Computer Vision Claims Automation Deployment | Reduces loss-adjustment cycle times for Tractable-style SaaS revenue capture. |
| Embedded Banking API Integration | Streamlines small business onboarding through Open Banking transaction verification. |
| Pet Health Subscription Model Expansion | Displaces annual policy renewals with lifetime customer value through preventive care. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the UK insurtech authorization landscape. Primary interviews captured perspectives from delegated authority platform executives, Lloyd's syndicate capital providers, retail banking API integration specialists, and commercial fleet risk managers. Secondary validation drew from Financial Conduct Authority authorization filings, Prudential Regulation Authority solvency disclosures, Information Commissioner's Office GDPR enforcement records, and Open Banking implementation entity reports. Bottom-up policy volume estimates triangulated against top-down premium pool assessments.
Across the analysis window, forecasts model product type segmentation across health, auto, property, and travel lines alongside service type differentiation in claims processing, underwriting, policy management, and risk assessment. Technology layer splits capture AI analytics, machine learning, IoT solutions, and blockchain infrastructure maturity gaps. CAGRs derive from algorithmic adoption curve modeling and regulatory authorization timeline probability weighting. Forecast inputs incorporate telematics penetration rates in commercial fleets and pet health subscription conversion metrics.
The analysis sits within stated boundaries; outcomes outside sustained Financial Conduct Authority consumer duty enforcement or Prudential Regulation Authority solvency stability would require recalibration. Forecasts reflect assumptions on Open Banking API standardization continuity and Lloyd's syndicate capital availability for delegated authority platforms. Recalibration cycles align with material shifts in regulatory authorization timelines and algorithmic underwriting portfolio performance data accumulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Europe Insurtech Market