
 Insurtech Market | 2026-2036
Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Insurtech Market Intelligence
Embedded API architectures is tilting the distribution model away from traditional agent channels toward point-of-sale integration. Lemonade leverages behavioral economics and AI-driven claims automation to differentiate its homeowner and renter products. Root Insurance anchors its growth in telematics-based auto underwriting, using smartphone sensor data to price risk dynamically. Coalition specializes in cyber insurance bundled with active risk monitoring, extending protection beyond pure indemnity into prevention services.
Insurtech encompasses technology-enabled platforms that automate insurance functions through machine learning, distributed ledgers, and cloud-native infrastructure, reducing loss-adjustment expenses while accelerating policy lifecycle management. The technology dimension spans blockchain for immutable claims records, AI for fraud detection, big data for predictive modeling, and cloud computing for elastic capacity scaling. Claims management and underwriting automation command the deepest margin pools, while policy administration remains a mature, cost-pressured segment where incumbents dominate legacy system migration.
The National Association of Insurance Commissioners coordinates state-level regulatory standards across the United States, while the SEC oversees insurtech entities with hybrid financial service offerings. GDPR and the EU AI Act impose algorithmic transparency requirements that reshape product development cycles for carriers operating across European jurisdictions. Stakeholders must monitor how divergent state-by-state approval timelines in the United States interact with federal proposals for a unified digital insurance framework.
Market Dynamics
Embedded API distribution architectures are systematically displacing traditional agent channels, forcing incumbent carriers to rebuild their technology stacks around real-time data exchange at the point of sale rather than policy-centric legacy systems.
Growth Catalysts
- Telematics sensor proliferation:Smartphone and IoT device penetration enables dynamic risk pricing in auto and property lines, expanding addressable premium pools beyond static actuarial tables.
- GDPR algorithmic transparency mandates:European regulatory clarity around automated decision-making accelerates carrier investment in explainable AI underwriting systems.
- Small and medium enterprise embedded models:Point-of-sale insurance integration within e-commerce and SaaS platforms captures previously uninsured commercial exposures at transaction origin.
Market Restraints
- Legacy system migration costs:Core policy administration modernization requires substantial capital allocation, compressing near-term profitability for established carriers.
- State-by-state regulatory fragmentation:Divergent approval timelines across United States jurisdictions delay product launches and increase compliance overhead.
- Data sovereignty constraints:Cross-border cloud infrastructure restrictions limit centralized AI model training and claims processing efficiency.
Strategic Opportunities
- Cyber insurance bundled prevention:Active risk monitoring services extend carrier value propositions beyond indemnity into continuous security posture management.
- Behavioral economics product design:Gamification and instant claims settlement architectures differentiate customer experience in commoditized personal lines.
- United States regulatory sandboxes:State-level innovation frameworks permit controlled testing of novel coverage structures and pricing methodologies.
Industry Challenges
- Actuarial-technical talent scarcity:Shortage of professionals combining statistical modeling expertise with cloud-native engineering capabilities constrains product development velocity.
- Blockchain claims record integration:Immutable ledger adoption creates friction with existing loss-adjustment workflows and regulatory reporting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurtech Market |
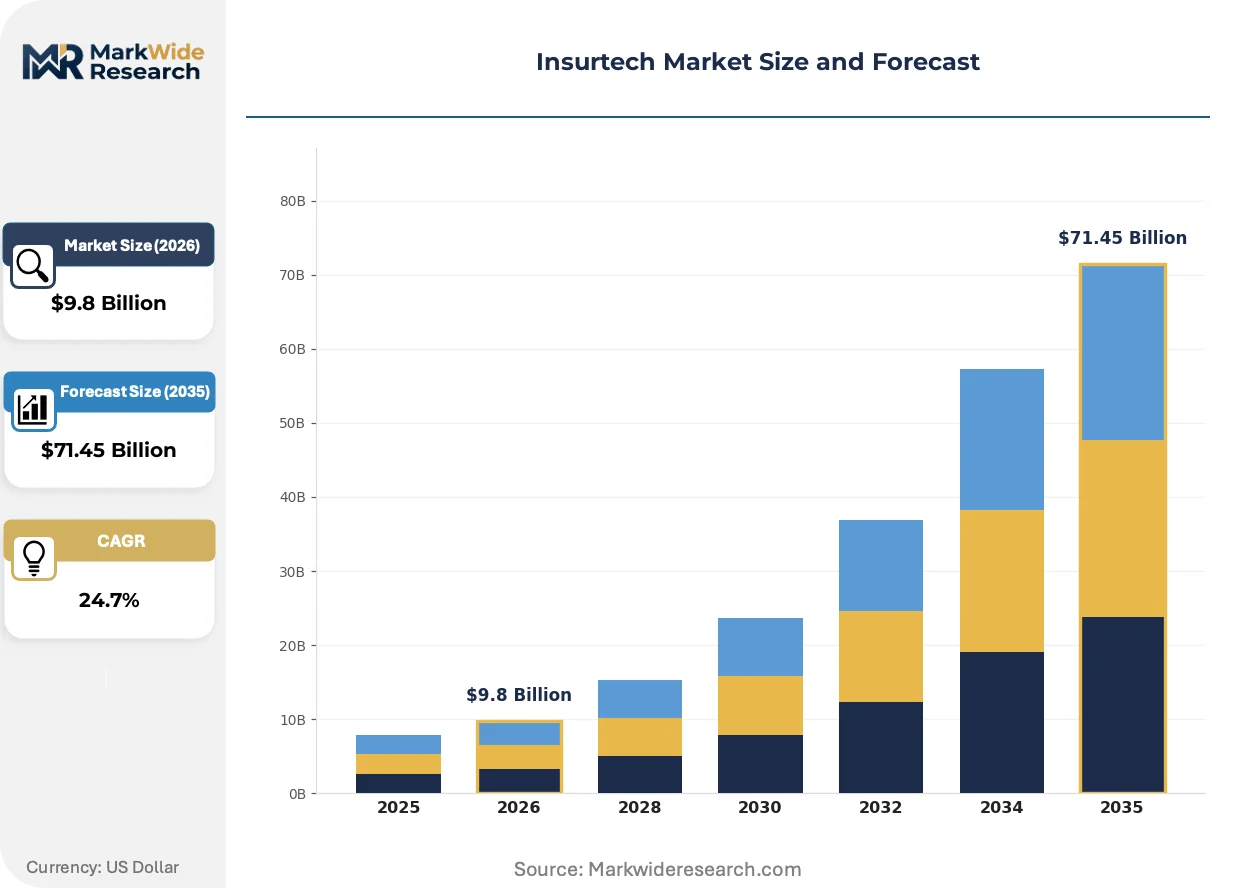
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $71.45 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, AI, Big Data, Cloud Computing Service Type: Claims Management, Policy Administration, Risk Assessment, Underwriting Automation End User: Insurance Companies, Brokers, Agents, Insured Individuals Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Lemonade, Next Insurance, Root Insurance, Shift Technology, Kin Insurance, Coalition, Oscar Health, Devoted Health, Policygenius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurtech Market Strategic Shifts & Innovations
Machine learning underwriting and distributed ledger infrastructure are converging to compress policy lifecycle timelines from weeks to minutes, redefining customer expectations across personal and commercial lines.
Parametric insurance structures are hybridizing traditional indemnity models with predefined trigger mechanisms. Agricultural and catastrophe carriers deploy satellite and sensor data to automate payouts without loss adjustment. Small commercial buyers in climate-exposed regions adopt these instruments fastest. The technology is hybridizing risk transfer with instant liquidity provision, eliminating claims dispute costs.
The EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions across European jurisdictions. Carriers must document model training data and decision logic for regulatory audit. Product development cycles lengthen as compliance teams validate explainability frameworks. German and French regulators lead enforcement, with cross-border carriers consolidating AI governance functions in Dublin and Luxembourg.
Small and medium enterprises now procure commercial coverage through embedded APIs within accounting and payroll platforms rather than broker intermediaries. This channel shift concentrates distribution power with vertical SaaS providers. United States technology platforms capture commission streams previously allocated to independent agents. The transformation is most advanced in workers compensation and cyber lines where transaction data enables real-time exposure assessment.
Insurtech Market Segmentation
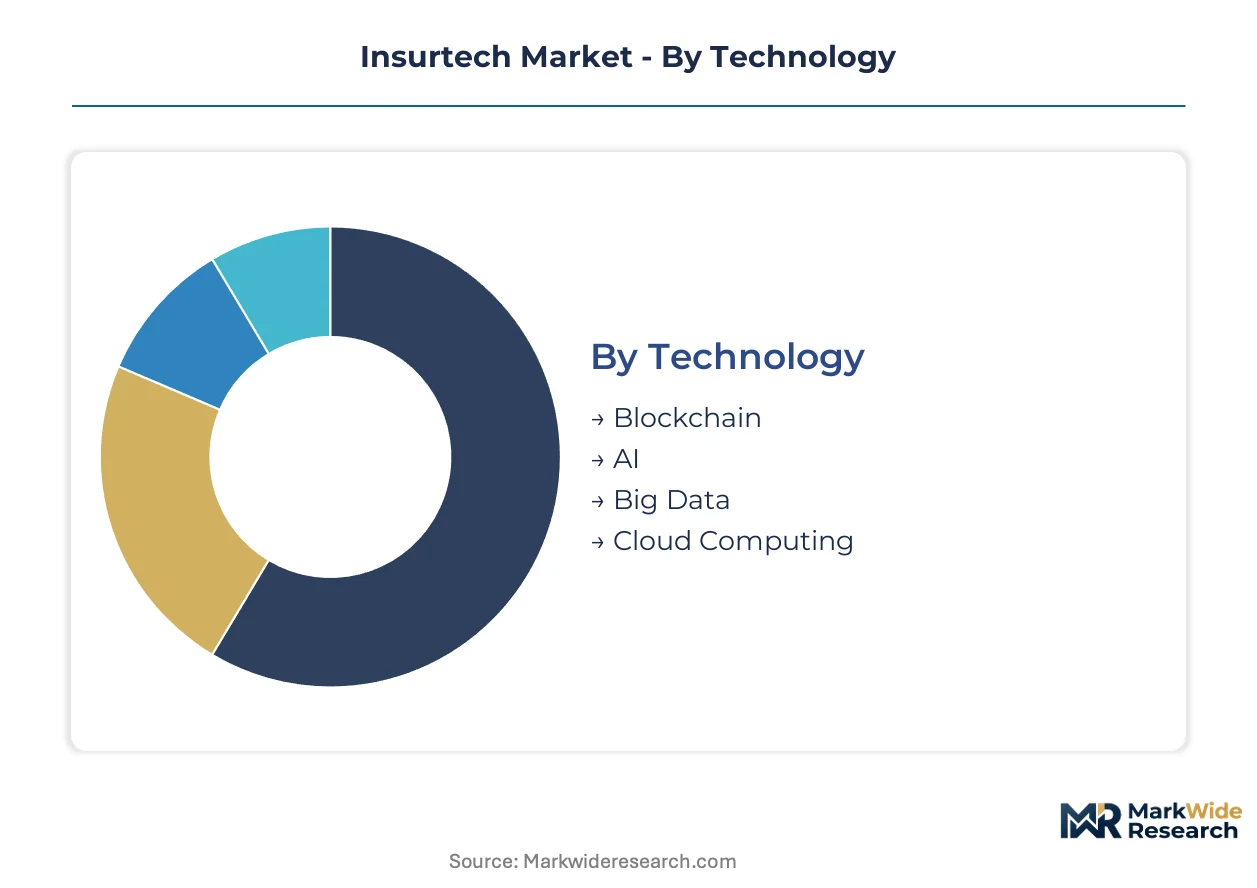
Technology architecture determines capital intensity and margin capture in insurtech. Deployment choices reshape distribution economics. End-user concentration dictates product complexity requirements.
Technology:
Technology stack selection governs underwriting speed, fraud detection accuracy, and infrastructure scalability across carrier operations.
- AI:Machine learning models process behavioral data streams for dynamic pricing and automated claims triage. Demand concentrates in United States auto and property lines where Lemonade and Root deploy real-time decision engines. GDPR algorithmic transparency mandates in Europe lengthen model validation cycles.
- Big Data:Predictive analytics platforms aggregate telematics, satellite imagery, and credit signals for risk stratification. German and French carriers lead integration of external data lakes into core underwriting systems. Cloud sovereignty constraints complicate cross-border model training.
- Blockchain:Distributed ledger infrastructure creates immutable claims records and smart contract automation.
- Cloud Computing:Elastic infrastructure enables rapid capacity scaling during catastrophe events and policy surges.
AI commands the established base. The steepest expansion runs through Big Data.
Service Type:
Service specialization aligns with margin pools and carrier transformation priorities across the policy lifecycle.
- Underwriting Automation:Algorithmic risk assessment compresses quote-to-bind timelines from days to minutes. United States insurtechs deploy smartphone sensor data for dynamic auto pricing. EU AI Act documentation requirements extend product development cycles.
- Claims Management:Automated triage and fraud detection reduce loss-adjustment expenses. Embedded API architectures enable instant settlement for low-complexity personal lines. Coalition bundles active monitoring with cyber claims processing.
- Risk Assessment:Continuous exposure monitoring extends beyond point-in-time underwriting.
- Policy Administration:Core system modernization remains cost-pressured as incumbents migrate legacy infrastructure.
Claims Management commands the established base. Underwriting Automation is gaining share fastest.
End User:
End-user structure determines interface complexity, regulatory exposure, and distribution channel requirements.
- Insurance Companies:Tier-one carriers invest in full-stack modernization of policy administration and claims systems. United States state-level regulatory sandboxes accelerate pilot deployments. Legacy migration costs compress near-term profitability.
- Brokers:Intermediaries adopt white-label digital platforms to defend against embedded API displacement. Small commercial lines in the United States shift fastest toward vertical SaaS integration.
- Agents:Independent distribution networks face channel compression from point-of-sale insurance.
- Insured Individuals:Direct-to-consumer platforms demand instant quotes and mobile-first claims experiences.
Insurance Companies command the established base. Brokers show the steepest expansion trajectory.
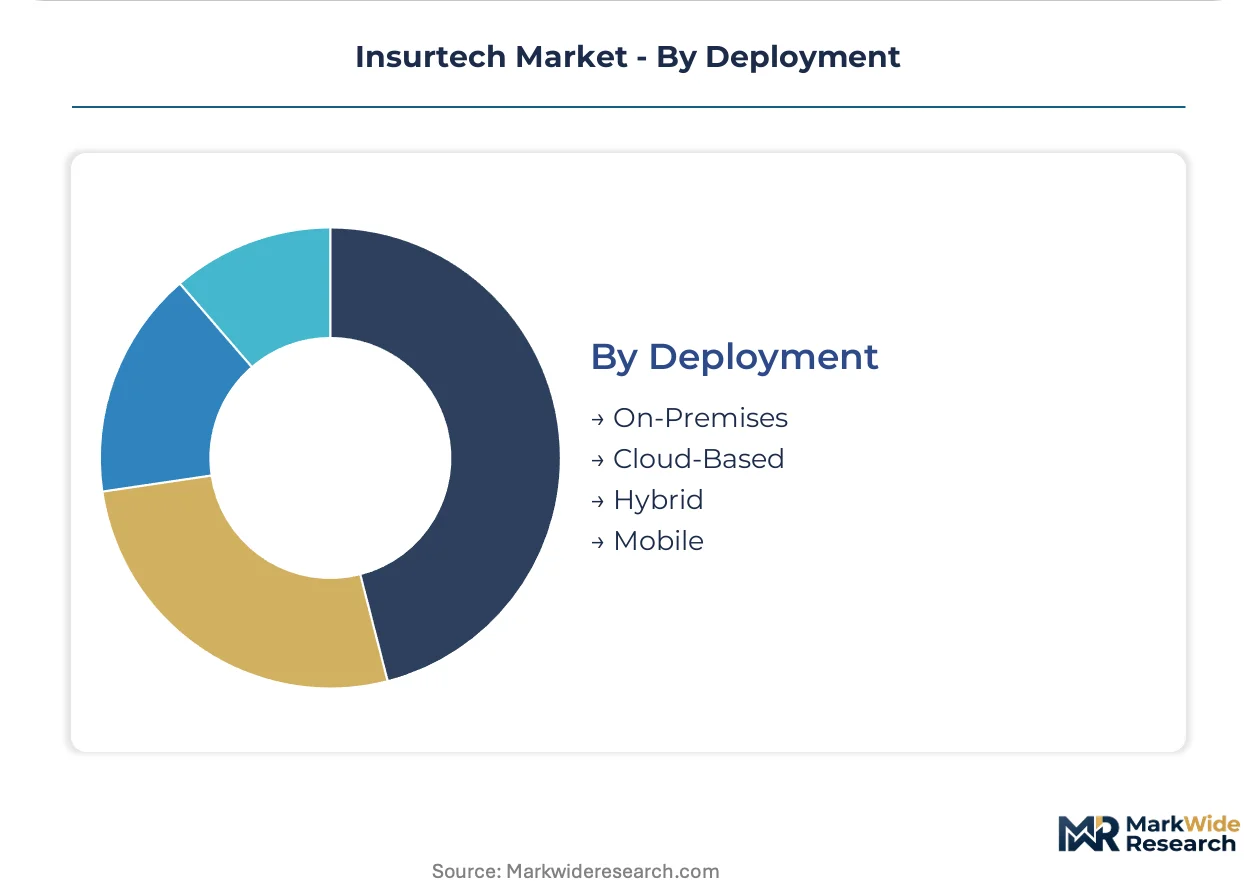
Deployment:
Deployment architecture shapes data sovereignty compliance, latency requirements, and capital expenditure profiles.
- Cloud-Based:Multi-tenant SaaS platforms enable rapid scaling without infrastructure ownership. United States carriers dominate adoption due to mature vendor ecosystems. European GDPR data localization rules fragment centralized AI training.
- Hybrid:Split architectures balance sensitive data on-premises with compute-intensive workloads in cloud. German and French regulators favor this model for algorithmic underwriting auditability.
- On-Premises:Legacy infrastructure persists among tier-one carriers with complex system interdependencies.
- Mobile:Smartphone-native distribution captures point-of-sale insurance within e-commerce and travel platforms.
Cloud-Based commands the established base. Hybrid architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based insurtech platforms export embedded insurance APIs to United Kingdom and German e-commerce markets, establishing transatlantic technology corridors that reshape European distribution economics.
United States
Venture capital deployment in Silicon Valley and New York Metro accelerates carrier digitization, while state-level regulatory sandboxes in Arizona and Wyoming permit controlled testing of novel coverage structures. The SEC oversees hybrid financial service offerings. San Francisco anchors telematics-based auto underwriting development where smartphone sensor data drives dynamic pricing models.
Germany
Industrial Mittelstand demand for cyber insurance bundles drives SME-focused platform adoption, particularly in manufacturing-heavy Baden-Württemberg and Bavaria. The KBA and BaFin enforce algorithmic transparency requirements that extend product development cycles. Munich's insurtech cluster concentrates on explainable AI underwriting systems compliant with EU AI Act documentation mandates.
United Kingdom
London's Lloyd's syndicates integrate blockchain claims records to compress settlement timelines, while embedded API architectures displace traditional broker channels in fintech-heavy East London clusters. The Financial Conduct Authority coordinates sandbox frameworks with Prudential Regulation Authority oversight. Insurtech development concentrates around the City and Shoreditch tech corridor.
France
Paris-based carriers invest in parametric agricultural insurance using satellite data for automated payouts in climate-exposed regions. The ANSM and CNIL enforce GDPR algorithmic decision-making transparency. Lyon and Toulouse emerge as secondary clusters where insurtechs partner with regional mutual insurers on SME embedded coverage.
India
Mumbai and Bangalore drive demand for mobile-first microinsurance distribution through UPI-integrated platforms reaching previously uninsured populations. The IRDAI regulates sandbox frameworks while RBI oversight applies to payment-embedded products. Hyderabad's technology corridor hosts cloud-native infrastructure development for claims automation serving South Asian markets.
Insurtech Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands dominant share. Venture-backed insurtechs anchor the growth tier, incumbent carriers occupy the transformation tier, and vertical SaaS platforms capture embedded distribution economics. Strategic moves concentrate on API partnership expansion and M&A consolidation of underwriting automation capabilities.
Within the venture-backed digital-native tier, Lemonade, Root Insurance, and Coalition occupy positions exemplifying distinct archetypes—behavioral economics-driven claims automation, telematics-based dynamic pricing, and cyber insurance bundled with active risk monitoring respectively. These entities represent the embedded distribution and AI underwriting specialization vectors that incumbent carriers must counter through technology acquisition or partnership restructuring.
| Leading Market Players |
|---|
| Lemonade |
| Next Insurance |
| Root Insurance |
| Shift Technology |
| Kin Insurance |
| Coalition |
| Oscar Health |
| Devoted Health |
| Policygenius |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure concentration in the United States creates margin capture asymmetry between hyperscaler-dependent insurtechs and carriers retaining on-premises core systems. Embedded API distribution channels extract commission premiums from SaaS platforms while compressing agent-mediated policy economics.
Pricing Analysis
Legacy policy administration systems trade at substantial discounts to cloud-native underwriting platforms, while next-generation AI-driven claims automation commands premium SaaS-tiered pricing. Three-tier pricing structure across enterprise, mid-market, and SME levels reflects deployment complexity and integration depth. Cost compression in commoditized personal lines intensifies as embedded distribution disintermediates traditional broker networks. Small commercial buyers exhibit highest price sensitivity, whereas tier-one carriers prioritize capability over cost in core system procurement.
Supply Chain Analysis
Extended payment terms from United States venture-backed insurtechs strain vendor cash cycles, while supply-chain finance facilities from cloud hyperscalers stabilize infrastructure procurement. Technology sourcing concentrates in the United States, Ireland, and Germany where GDPR-compliant data centers anchor European operations. Proprietary AI model training, telematics sensor hardware, and blockchain validation nodes constitute critical input dependencies. Single-source vulnerability around hyperscaler cloud platforms threatens operational continuity. Distribution runs through API marketplaces and direct carrier-vendor relationships rather than traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurtech penetration remains below saturation across commercial lines and emerging markets, with embedded insurance APIs representing an early-cycle expansion vector. Small and medium enterprise adoption through vertical SaaS platforms accelerates addressable market expansion.
For Market Incumbents: Entrench core policy administration dominance through accelerated cloud migration timelines, countering venture-backed entrants' speed-to-market advantage. Acquire underwriting automation specialists to close AI capability gaps rather than building organically. Prioritize API partnership architectures that preserve distribution relationships against embedded disintermediation.
For New Entrants and Emerging Players: Pursue white-space concentration in cyber insurance bundled with active risk monitoring, where incumbent prevention-service capabilities remain underdeveloped. Target mid-market commercial lines in German and French manufacturing clusters where Mittelstand demand outpaces carrier digitization. Deploy vertical SaaS integration as primary go-to-market mechanism, capturing transaction-origin data for real-time exposure assessment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed underwriting automation specialists possessing proven carrier deployments but limited platform scale. Five-to-ten year viability hinges on successful transition from point solutions to full-stack infrastructure. Monitor EU AI Act enforcement patterns as inflection indicator for explainable AI compliance costs and product development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership Expansion | Embedded distribution through vertical SaaS platforms captures SME commission pools from traditional brokers. |
| Acquisition of AI Underwriting Specialist | Explainable AI capabilities satisfy EU AI Act documentation mandates while compressing quote-to-bind timelines. |
| Cloud-Native Core Migration | Elastic infrastructure enables catastrophe surge capacity without legacy system capital intensity. |
| Cyber Prevention Service Launch | Active risk monitoring extends carrier value proposition beyond indemnity into continuous security posture management. |
| Regulatory Sandbox Entry | State-level innovation frameworks in Arizona and Wyoming permit controlled testing of novel coverage structures. |
Research Approach
A standing panel of chief technology officers at tier-one carriers, venture capital partners with insurtech portfolios, regulatory affairs specialists at NAIC and BaFin, and embedded API platform executives provided ongoing calibration. Primary interviews combined with secondary validation from SEC filings, IRDAI sandbox disclosures, EU AI Act implementation guidance, and venture funding databases. Bottom-up policy volume estimates triangulated against top-down premium pool analysis.
Scenario bracketing anchored projections across technology adoption curves, regulatory enforcement intensity, and embedded distribution penetration rates. Segmentation dimensions modeled include technology stack, service type specialization, end-user category, and deployment architecture across the projection horizon. CAGRs derived from S-curve technology diffusion patterns and carrier transformation budget elasticity. Forecast inputs incorporated telematics sensor penetration rates and SME platform integration velocity.
Sensitivities concentrate around GDPR data localization enforcement, state-by-state regulatory sandbox expansion, and hyperscaler cloud pricing volatility. Forecasts embody assumptions regarding venture capital deployment continuity and carrier legacy migration prioritization. Macroeconomic contraction, federal digital insurance framework preemption, or generative AI underwriting breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
UK Insurtech Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Insurance Software Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Insurance Fraud Detection Market