
 Germany AI in Insurance Market | 2026-2036
Germany AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany AI in Insurance Market Insights
German InsurTech infrastructure is repositioning around cloud-native AI stacks. Allianz SE leverages proprietary machine learning models for dynamic pricing across motor portfolios. Munich Re anchors the reinsurance segment with predictive analytics platforms that cedants integrate into treaty negotiations. ERGO Group AG competes through robotic process automation deployments in back-office claims operations.
AI in insurance denotes the application of computational algorithms—encompassing supervised learning architectures, transformer-based natural language models, and robotic automation frameworks—to risk selection, loss prediction, and policy administration workflows. These systems process structured actuarial data and unstructured customer communications to generate probabilistic outputs that inform underwriting decisions and reserve calculations. Claims management applications dominate current deployment value, as German carriers prioritize loss-ratio compression through automated damage assessment and fraud pattern recognition. Machine learning solutions command the technology tier, while predictive analytics capabilities are deepening fastest among reinsurers seeking real-time catastrophe exposure monitoring. Risk assessment tools within the solution category capture concentrated margin pools due to their integration complexity and regulatory validation requirements.
BaFin's supervisory guidance on algorithmic decision-making intersects with EU AI Act conformity obligations to mandate explainability standards for high-risk insurance applications. The German Insurance Association (GDV) coordinates industry responses to these layered compliance demands, particularly regarding customer-facing chatbot disclosures. Stakeholders must monitor how BaFin interprets the AI Act's insurance-specific risk classifications against existing Solvency II governance frameworks.
Market Dynamics
The German AI in insurance sector is compressing around BaFin's algorithmic governance deadlines, forcing carriers to revalidate underwriting models before EU AI Act enforcement windows close. This regulatory compression is accelerating procurement cycles for explainable AI platforms while freezing experimental deployments pending conformity assessments.
Growth Catalysts
- EU AI Act insurance classification:High-risk system designations for credit scoring and life underwriting are mandating documented risk management protocols, creating structured demand for compliance-integrated AI tooling.
- Automated claims triage:Property and casualty carriers are deploying computer vision for damage assessment, compressing loss adjustment expense ratios across motor and property lines.
- Munich-Frankfurt cluster concentration:Reinsurance analytics demand in Frankfurt and InsurTech development in Munich are generating specialized vendor ecosystems and talent pipelines.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for large language models depend on constrained NVIDIA H100 supply, inflating cloud service expenditures for mid-tier carriers.
- Actuarial data siloing:Historical claims datasets remain fragmented across legacy policy administration systems, limiting training data availability for predictive models.
- Solvency II model governance:Existing internal model validation requirements create friction against rapid AI model deployment in capital-sensitive applications.
Strategic Opportunities
- Baden-Württemberg manufacturing insurance:Industrial IoT sensor networks in automotive and machinery sectors enable parametric coverage products with real-time risk monitoring.
- Telematics-ML convergence:Connected vehicle data streams combined with gradient-boosted pricing models allow dynamic premium adjustments at policy renewal.
- BaFin sandbox participation:Supervisory innovation frameworks permit limited-scale AI deployments under modified compliance requirements, reducing market entry barriers.
Industry Challenges
- Explainable AI engineering scarcity:German carriers face acute shortages of technical staff capable of implementing SHAP and LIME interpretability methods within production pipelines.
- Legacy system API limitations:Core policy administration platforms from the 1990s lack real-time data exchange capabilities, forcing expensive middleware development for AI integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany AI in Insurance Market |
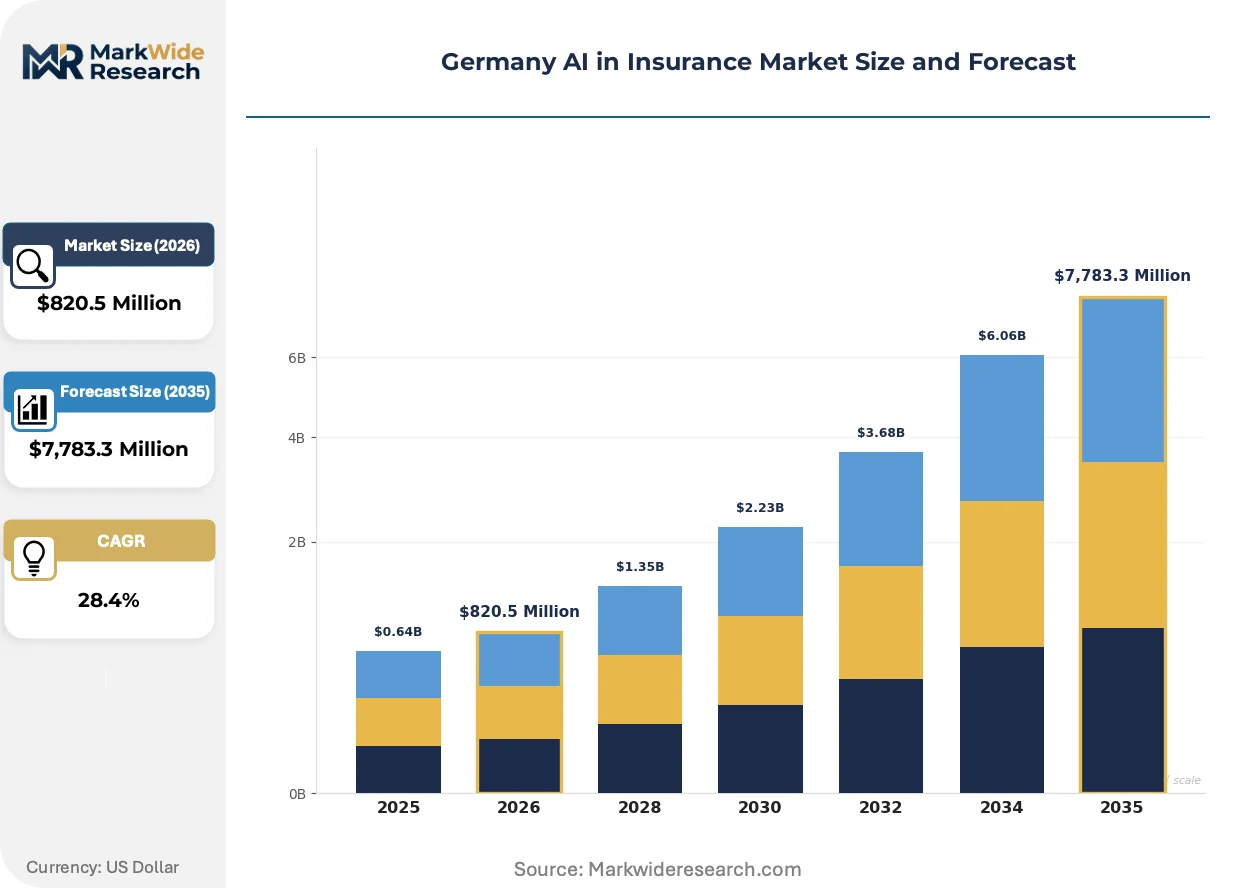
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $7,783.3 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Underwriting, Claims Management, Fraud Detection, Customer Service Technology: Machine Learning, Natural Language Processing, Robotics, Predictive Analytics End User: Insurance Providers, Brokers, Consulting Firms, Reinsurers Solution: Chatbots, Data Analytics Platforms, Risk Assessment Tools, Automation Solutions |
| Companies Covered | Allianz SE, Munich Re, AXA Germany, ERGO Group AG, Generali Deutschland AG, Zurich Insurance Group, Talanx AG, HDI Global SE, Wüstenrot & Württembergische AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany AI in Insurance Market Trends and Innovations
Transformer-based natural language models are penetrating German insurance workflows, reshaping document processing and customer interaction architectures. These capabilities are migrating from pilot programs to operational deployments across underwriting and claims functions.
Foundation models fine-tuned on German insurance corpora are rewriting document classification and extraction workflows. Commercial lines underwriters at mid-sized carriers are adopting these tools for submission intake processing, compressing quote turnaround from days to hours. The technology is rewriting competitive positioning in SME commercial insurance, where speed-to-quote determines placement success.
BaFin's interpretability guidance intersects with EU AI Act Article 13 requirements to mandate technical documentation standards for automated decision systems. German carriers must now maintain model cards and data provenance records for high-risk applications. Life and health insurers face the steepest compliance burden, as medical underwriting algorithms fall under strictest scrutiny.
Corporate risk managers are unbundling traditional broker relationships to procure AI-enabled analytics directly from reinsurers and specialty platforms. This disintermediation is most visible among DAX-listed industrial groups with captive insurance structures, who demand real-time exposure visualization tools. Munich-based risk analytics providers are capturing this demand through direct platform licensing arrangements.
Germany AI in Insurance Market Segmentation
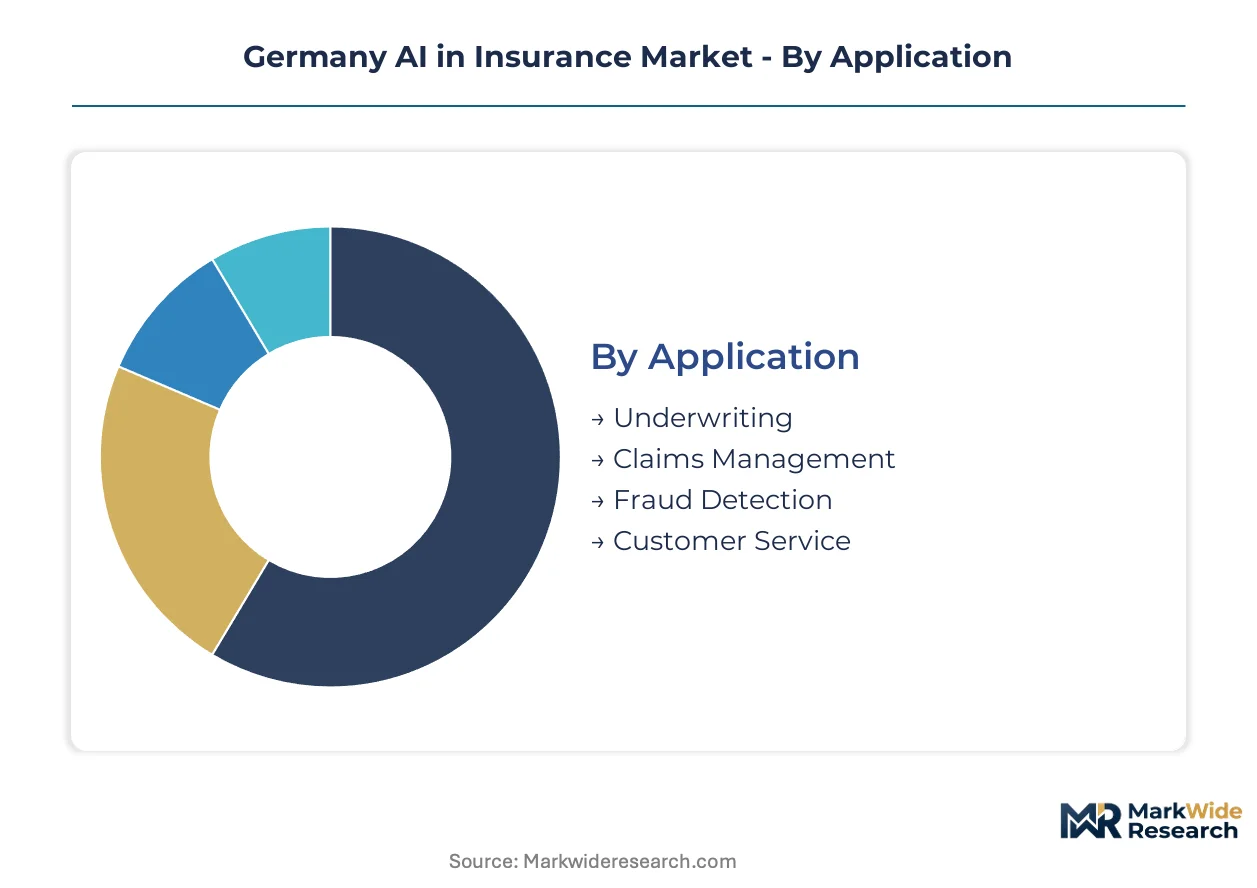
Segmentation in the German AI insurance market reveals how procurement priorities diverge across functional workflows and organizational archetypes. Carriers allocate budgets differentially based on regulatory exposure, legacy system constraints, and Solvency II capital sensitivity.
Application:
Carriers prioritize applications based on loss-ratio compression potential and BaFin interpretability requirements.
- Claims Management:Computer vision systems automate damage assessment for motor and property lines, reducing loss adjustment expenses. Munich-based P&C carriers deploy these tools most aggressively, driven by pressure on combined ratios and adjuster workforce shortages.
- Fraud Detection:Anomaly detection algorithms flag suspicious claims patterns using historical actuarial data and behavioral signals. Frankfurt reinsurers integrate these capabilities into treaty pricing, as cedants demand real-time fraud scoring in parametric structures.
- Underwriting:Gradient-boosted models accelerate risk selection across commercial and personal lines.
- Customer Service:Conversational AI handles policy inquiries and claims status updates.
Volume sits with Claims Management; growth tilts toward Fraud Detection.
Technology:
Technology choices reflect infrastructure maturity and talent availability within carrier IT departments.
- Machine Learning:Supervised learning architectures dominate pricing and reserving applications, with German carriers favoring interpretable models over black-box alternatives. Allianz and ERGO maintain proprietary training pipelines for motor telematics and property risk scoring.
- Predictive Analytics:Statistical forecasting platforms enable real-time catastrophe exposure monitoring and dynamic capital allocation. Munich Re's analytics licensing to industrial captives drives specialized demand in this tier.
- Natural Language Processing:Transformer-based models extract information from submission documents and correspondence.
- Robotics:RPA frameworks automate back-office policy administration and data entry workflows.
Machine Learning captures the largest deployment budgets; Predictive Analytics is climbing the fastest among reinsurance applications.
End User:
End-user categories diverge sharply in procurement sophistication and integration complexity tolerance.
- Insurance Providers:Primary carriers demand end-to-end platforms spanning underwriting through claims, with strict BaFin compliance documentation. Mid-tier German P&C insurers currently lead procurement volume as they modernize legacy core systems.
- Reinsurers:Treaty and facultative underwriters require granular exposure analytics and cedant data integration. Munich's reinsurance cluster generates concentrated demand for catastrophe modeling and retrocession pricing tools.
- Brokers:Intermediaries seek client-facing analytics dashboards and placement optimization tools.
- Consulting Firms:Advisory practices procure AI tooling for carrier transformation programs and due diligence support.
Insurance Providers dominate current spending; Reinsurers are gaining share fastest through direct platform licensing to corporate risk managers.
Solution:
Solution procurement correlates with carrier digital maturity and middleware investment capacity.
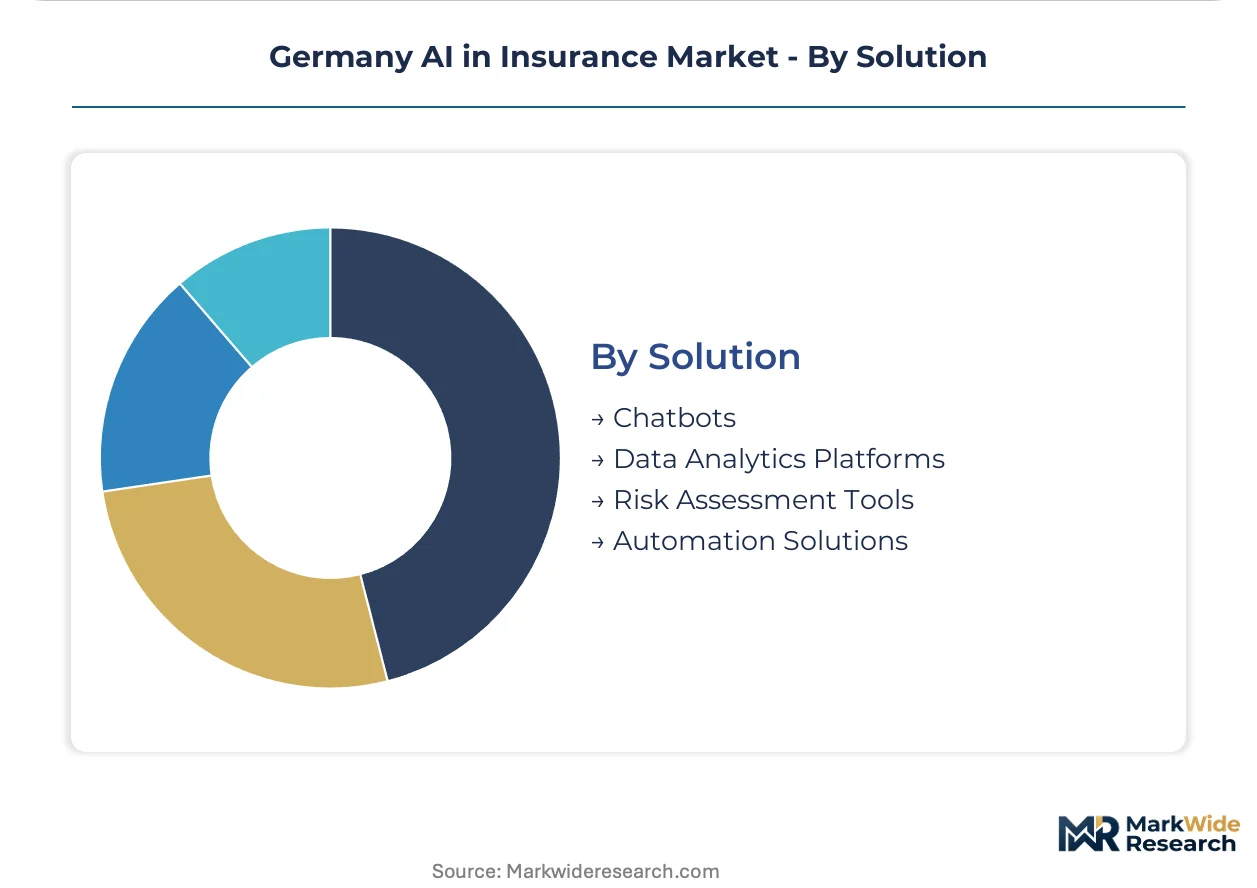
- Risk Assessment Tools:Integrated underwriting workbenches combine external data ingestion, model scoring, and documentation workflows. These solutions command premium pricing due to regulatory validation requirements and Solvency II governance integration.
- Data Analytics Platforms:Enterprise-grade visualization and modeling environments support actuarial and risk management functions. Frankfurt's reinsurance hub drives specialized demand for exposure aggregation and treaty optimization capabilities.
- Chatbots:Customer-facing conversational interfaces handle routine inquiries with mandatory disclosure protocols under EU AI Act Article 13.
- Automation Solutions:RPA and intelligent document processing tools streamline back-office operations.
Risk Assessment Tools anchor solution revenue; Data Analytics Platforms show the steepest expansion trajectory as reinsurers unbundle traditional broker relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's AI in insurance market concentrates in metropolitan clusters where actuarial talent pools and regulatory proximity intersect. The country's federal structure distributes InsurTech development across state-level financial centers, each shaped by distinct industrial specializations and supervisory interpretations.
Bavaria
Munich anchors Germany's InsurTech ecosystem with the densest concentration of venture-backed AI startups serving property and casualty carriers. BaFin's regional office maintains close supervisory relationships with digital-first insurers headquartered here. The cluster specializes in computer vision for automated damage assessment and natural language processing for commercial underwriting workflows.
Hesse
Frankfurt's reinsurance hub drives demand for predictive analytics platforms and catastrophe exposure modeling tools. The European Insurance and Occupational Pensions Authority's proximity shapes compliance-integrated product development cycles. Local vendors concentrate on treaty pricing algorithms and real-time capital allocation dashboards for global reinsurance buyers.
Baden-Württemberg
Stuttgart and Karlsruhe host industrial insurance specialists leveraging IoT sensor networks for manufacturing risk monitoring. The state's automotive supply chain density creates parametric coverage opportunities tied to production line telemetry. Local AI deployments focus on supply chain disruption prediction and cyber-physical risk quantification.
North Rhine-Westphalia
Düsseldorf and Cologne house legacy carrier back-office operations undergoing robotic process automation transformation. The region's insurance employment base supports talent pipelines for explainable AI engineering roles. Mid-tier P&C insurers here prioritize claims triage automation to offset adjuster workforce shortages.
Berlin-Brandenburg
Berlin's startup ecosystem produces niche AI vendors targeting customer-facing applications and fraud detection algorithms. The city's lower cost base attracts technical talent from Munich and Frankfurt for remote development teams. BaFin's innovation sandbox programs enable limited-scale deployments of experimental underwriting models.
Germany AI in Insurance Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive development strategies. The vendor base organizes into three tiers: proprietary platform developers, compliance-integrated solution providers, and specialized analytics boutiques. Strategic moves concentrate on M&A for talent acquisition and partnerships for cloud infrastructure access. Vertical integration into data pipelines distinguishes carriers with scale from those dependent on third-party aggregators.
Within the proprietary platform tier, Allianz SE and Munich Re exemplify divergent approaches to AI capability development. Allianz anchors the primary carrier segment with in-house machine learning pipelines for dynamic pricing across motor portfolios. Munich Re occupies a position in reinsurance analytics through predictive platforms that cedants license for treaty negotiations. ERGO Group AG represents the automation-focused archetype, deploying robotic process automation at scale across back-office claims operations.
| Leading Market Players |
|---|
| Allianz SE |
| Munich Re |
| AXA Germany |
| ERGO Group AG |
| Generali Deutschland AG |
| Zurich Insurance Group |
| Talanx AG |
| HDI Global SE |
| Wüstenrot & Württembergische AG |
| Others |
Pricing and Supply Chain Analysis
Compliance-integrated AI tooling bifurcation separates BaFin-validated platforms from experimental deployments, with premium pricing attaching to explainability documentation and Solvency II governance integration while mid-tier carriers absorb GPU compute volatility through SaaS-tiered consumption models. This divergence concentrates procurement power among Munich and Frankfurt clusters where reinsurance analytics demand sustains higher licensing fees, while legacy system API limitations force price-insensitive middleware investments elsewhere.
Pricing Analysis
Service-bundling unbundles across the German AI insurance vendor landscape, with implementation support and ongoing BaFin compliance documentation increasingly separated from base platform licensing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—premium tiers incorporate EU AI Act conformity pre-validation and dedicated explainability engineering, while economy tiers offer black-box models with limited documentation. Pricing pressure stems from NVIDIA H100 supply constraints inflating cloud inference costs for transformer-based deployments. Mid-tier P&C insurers exhibit highest price sensitivity due to combined ratio pressures, whereas Munich Re and Allianz SE absorb premium pricing for proprietary pipeline control.
Supply Chain Analysis
Dual-sourcing requirements mandate multi-cloud qualification among German carriers, with BaFin's operational resilience guidelines pressuring redundancy across AWS, Azure, and Google Cloud Platform deployments. GPU silicon concentrates in Taiwan and South Korea, with NVIDIA H100 and AMD MI300X supply chains drawing from TSMC foundry capacity. Cloud service dependencies rest on hyperscaler data center footprints in Frankfurt and Amsterdam. Single-source vulnerability concentrates in NVIDIA's datacenter GPU monopoly, intensifying procurement risk. Distribution runs through direct enterprise licensing with Munich and Frankfurt-based carriers, supplemented by systems integrator channels for mid-tier implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU compute scarcity props pricing power for cloud-native AI stacks, with NVIDIA allocation priority favoring carriers with committed multi-year infrastructure contracts over experimental deployments.
For Market Incumbents: Extend proprietary model pipeline development to capture gradient-boosted pricing advantages before EU AI Act enforcement windows compress vendor qualification cycles. Allianz and Munich Re should deepen backward integration into training data pipelines, securing exclusive access to industrial IoT sensor networks in Baden-Württemberg manufacturing corridors. Defensive positioning requires pre-emptive BaFin sandbox participation to lock in modified compliance pathways for high-risk underwriting applications. For New Entrants and Emerging Players: The €50K-€200K annual subscription gap between premium explainability-integrated platforms and economy RPA tools creates white-space opportunity for mid-market carriers in North Rhine-Westphalia. Target claims triage automation for mid-tier P&C insurers with adjuster workforce shortages, leveraging computer vision APIs without full core system replacement. Go-to-market angle: BaFin-compliant model cards as a service, reducing documentation burden for carriers lacking internal SHAP/LIME engineering capacity. For Investors and Strategic Acquirers: Re-rating potential sits with specialized analytics boutiques possessing EU AI Act pre-validated toolkits given regulatory compression accelerating procurement cycles. Long-term viability centers on vendors with captive data pipeline access—industrial IoT aggregators in Stuttgart-Karlsruhe corridors or telematics platforms with OEM integration. Signal to watch: BaFin's interpretation of high-risk system designations for life underwriting algorithms, which would trigger immediate compliance-integrated tooling demand.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Pipeline Development | Allianz's in-house machine learning for motor telematics captures pricing precision unavailable through third-party APIs. |
| BaFin Sandbox Participation | ERGO Group's limited-scale RPA deployments under modified compliance reduce market entry barriers for experimental underwriting tools. |
| Industrial IoT Data Partnership | Munich Re's sensor network integration in Baden-Württemberg enables parametric coverage with real-time production line telemetry. |
| Multi-Cloud Infrastructure Redundancy | Dual-sourcing across AWS and Azure aligns with BaFin operational resilience guidelines for high-risk AI system deployments. |
| Explainability Engineering Talent Acquisition | SHAP and LIME implementation capacity scarcity in Berlin-Brandenburg creates acquisition targets for carriers accelerating EU AI Act compliance. |
Research Methodology
Multi-period observation of BaFin supervisory guidance evolution and EU AI Act implementation milestones anchored the trend analysis, supplemented by interviews with chief data officers at Munich and Frankfurt-based carriers, actuarial science leads at reinsurance analytics platforms, compliance officers navigating Solvency II governance integration, and InsurTech founders in Bavaria's venture ecosystem. Secondary validation drew from BaFin circulars on algorithmic decision-making, EIOPA technical standards on AI in insurance, GDV industry position papers, and hyperscaler capex disclosures for European cloud infrastructure expansion. Bottom-up carrier spending estimates triangulated against top-down market sizing from technology procurement patterns.
Input-output matrices modeled deployment volumes across claims management, fraud detection, underwriting, and customer service applications, segmented by machine learning, predictive analytics, natural language processing, and robotics technologies. End-user disaggregation spanned insurance providers, reinsurers, brokers, and consulting firms with solution-type splits across risk assessment tools, data analytics platforms, chatbots, and automation solutions. CAGRs derived from regression analysis of historical technology procurement and regulatory enforcement timeline acceleration. Industry-specific forecast inputs incorporated GPU supply chain constraints and BaFin interpretability guidance implementation schedules.
Inputs from carrier IT procurement databases and reinsurance treaty pricing platform vendors were available through the study window; gaps in experimental AI deployment failure rates introduce uncertainty bands around adoption curve assumptions. Forecasts reflect documented assumptions regarding EU AI Act enforcement consistency and cloud infrastructure cost trajectories. Deviation in NVIDIA H100 supply allocation or BaFin's high-risk system classification breadth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
UK Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Insurtech Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Japan AI in Insurance Market