
 Singapore Insurtech Market | 2026-2036
Singapore Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Insurtech Market Analytics
API-first infrastructure is narrowing the gap between traditional carriers and digital-native distributors in Singapore's insurance sector. bolttech leverages its embedded insurance marketplace to connect insurers with non-insurance distribution partners across Southeast Asia. CoverGo anchors its position through no-code policy administration tools that reduce carrier deployment cycles. Singlife competes as a digitally licensed life insurer with direct-to-consumer term products.
Singapore insurtech encompasses technology-enabled platforms that automate insurance distribution, underwriting, claims processing, and policy management through cloud-native architectures and real-time data pipelines. These systems integrate with core banking APIs and regulatory reporting frameworks to enable seamless policy issuance and embedded coverage within third-party transactions. Health insurance platforms currently lead segment momentum as chronic disease management programs integrate wearable data streams for dynamic pricing. AI-driven underwriting engines represent the fastest-growing technology segment, with natural language processing reducing medical record review time from days to minutes. Cloud computing infrastructure sustains backend scalability for insurers managing seasonal premium spikes and catastrophe exposure modeling.
The Monetary Authority of Singapore governs digital insurer licensing through its FinTech Regulatory Sandbox, while the Personal Data Protection Commission enforces consent frameworks for biometric and behavioral data used in pricing algorithms. MAS sandbox guidelines shape product innovation velocity by permitting controlled live testing of parametric and on-demand coverage models before full licensing. Stakeholders must monitor how MAS updates to risk-based capital requirements for digital insurers affect competitive capital efficiency versus traditional incumbents.
Market Dynamics
API-first infrastructure is compressing distribution timelines between Singapore carriers and digital-native platforms, while MAS sandbox licensing accelerates the entry of cloud-native underwriters into previously protected product lines.
Growth Catalysts
- MAS FinTech Regulatory Sandbox:Controlled live testing permissions reduce time-to-market for parametric and on-demand coverage models, enabling digital insurers to validate products before full licensing.
- SME embedded insurance adoption:Small and medium enterprises across Singapore are integrating coverage into payment workflows and e-commerce transactions, expanding addressable premium pools beyond traditional broker channels.
- AI underwriting engines:Natural language processing systems compress medical record review from days to minutes, lowering acquisition costs for health and life products targeting corporate employee benefits.
Market Restraints
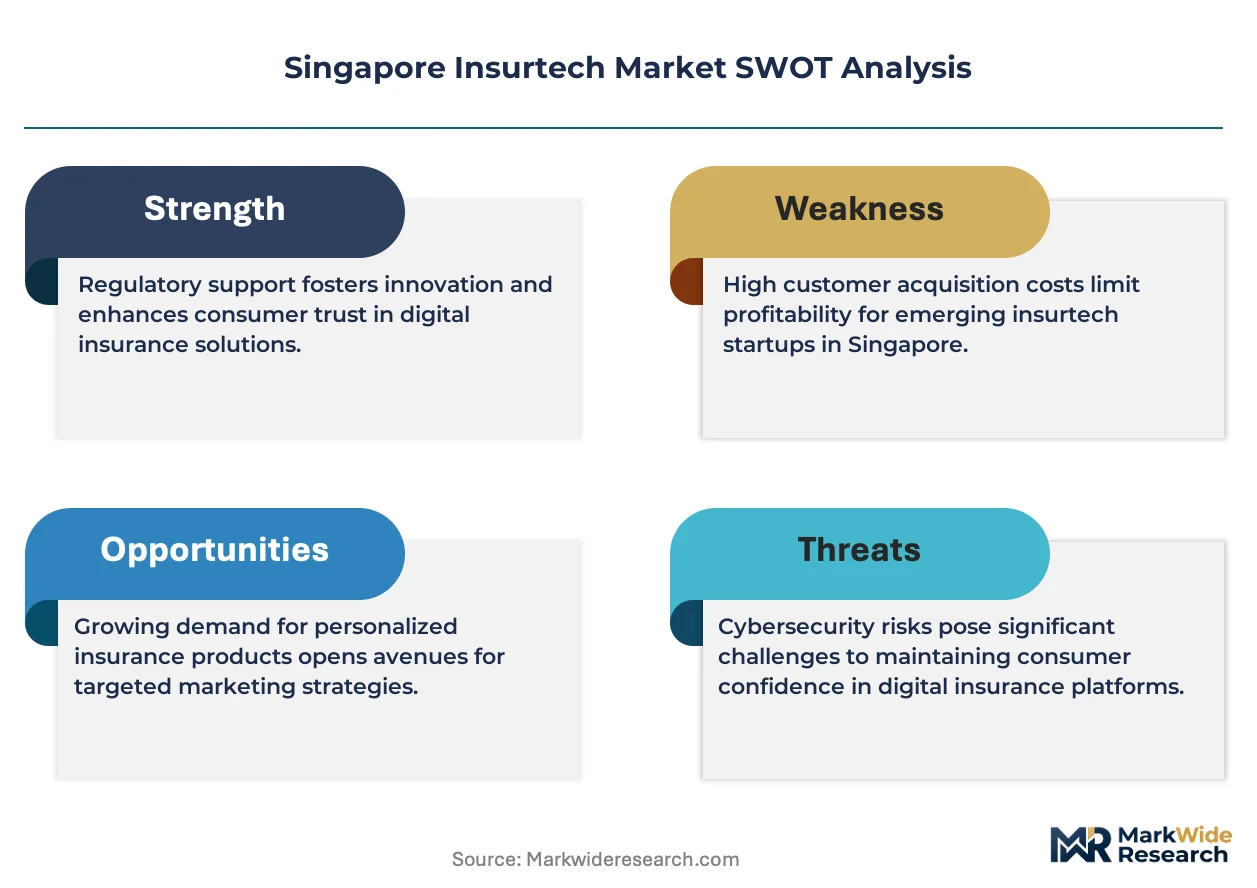
- Cloud infrastructure concentration:Reliance on hyperscale providers for core policy administration creates systemic operational risk during regional outages or data sovereignty disputes.
- PDPC biometric consent friction:Strict behavioral and biometric data consent requirements under Singapore's Personal Data Protection Commission slow deployment of dynamic pricing models using wearable health streams.
- Legacy core system integration costs:Traditional carriers face prohibitive capital requirements to replatform decades-old policy administration systems onto cloud-native architectures.
Strategic Opportunities
- Chronic disease management integration:Health platforms embedding wearable data streams into dynamic pricing models can capture employer-sponsored wellness program budgets.
- Cross-border Southeast Asia distribution:Singapore-licensed digital insurers can leverage regulatory recognition frameworks to distribute embedded products into Malaysia and Indonesia via API partnerships.
- Parametric catastrophe coverage:Climate risk models using satellite and IoT sensor data enable instant-trigger policies for property and business interruption exposure.
Industry Challenges
- Actuarial data science talent scarcity:Shortage of professionals combining insurance domain expertise with machine learning engineering delays model deployment cycles.
- MAS risk-based capital recalibration:Evolving solvency requirements for digital insurers create uncertainty in capital planning and product pricing assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Insurtech Market |
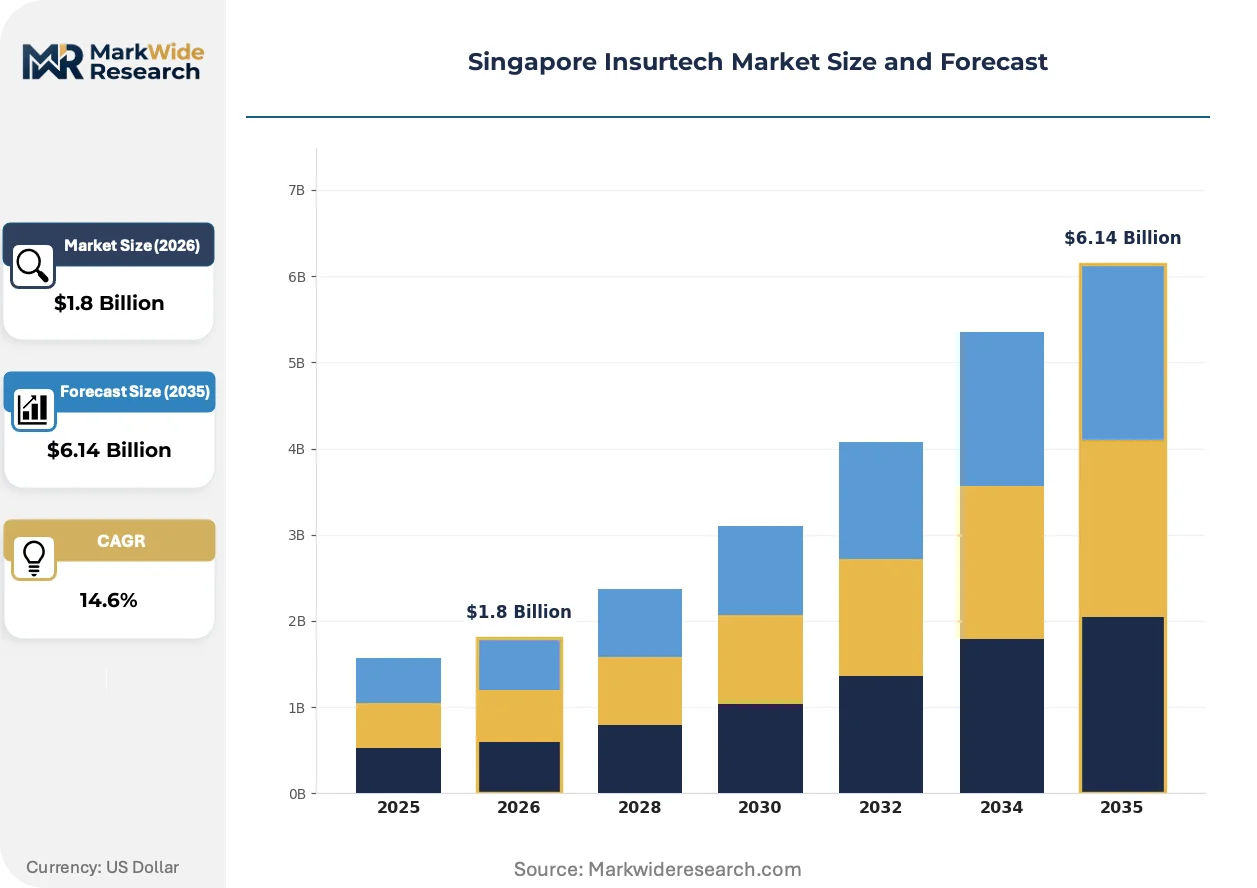
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Life Insurance, Property Insurance, Auto Insurance Customer Type: Individuals, SMEs, Corporates, Startups Distribution Channel: Online Platforms, Agents, Brokers, B2B Partnerships Technology: Blockchain, AI, Big Data, Cloud Computing |
| Companies Covered | bolttech, Igloo, CoverGo, Singapore Life, CXA Group, Income Insurance, Singlife, Great Eastern, Prudential Assurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Insurtech Market Evolving Landscape
Convergence between embedded distribution channels and real-time underwriting engines is restructuring how Singapore insurers acquire and retain policyholders across health and property lines.
Computer vision damage assessment is hybridizing claims processing workflows by enabling policyholders to submit photos for instant repair estimates. Property insurers and motor underwriters are deploying these tools to eliminate adjuster dispatch for routine claims. The technology is compressing indemnity payment cycles from weeks to hours while reducing fraud through automated consistency checks.
MAS updates to risk-based capital requirements for digital insurers are reshaping competitive capital efficiency benchmarks. The framework introduces differentiated solvency treatment for parametric and traditional indemnity products. Singapore's digitally licensed life and general insurers must now optimize product mix to minimize capital drag against return targets.
Corporate benefits managers are consolidating vendor relationships by demanding unified platforms combining health insurance, wellness programs, and claims analytics. Single-point solutions from standalone insurtechs face displacement by integrated offerings from banks and telecom distributors. This consolidation pressure is most visible among Singapore's financial services and technology sector employers with above-average employee benefits sophistication.
Singapore Insurtech Market Segmentation
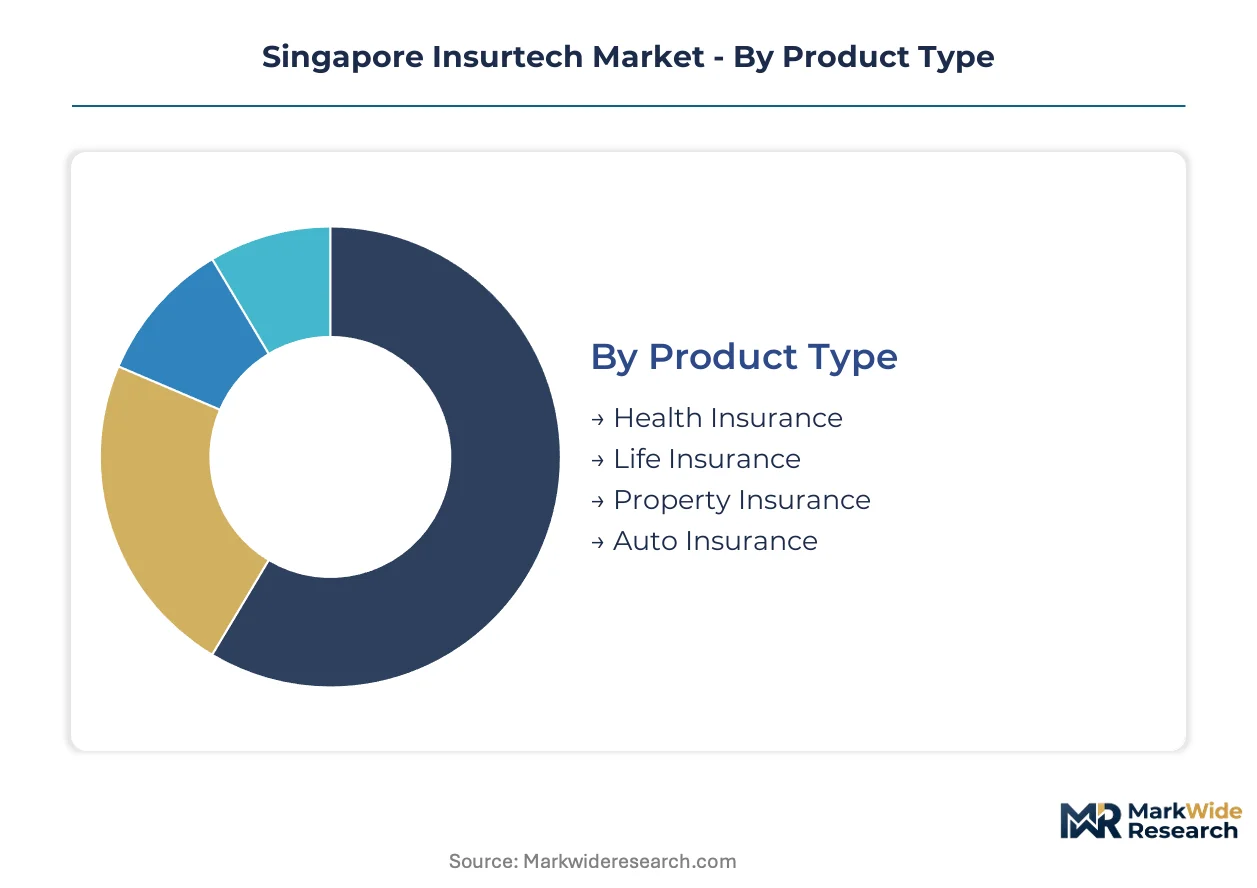
Segmentation in Singapore's insurtech market reveals how capital deployment and regulatory velocity concentrate across product lines and customer cohorts. Understanding these divides helps stakeholders prioritize platform investments and partnership strategies.
Product Type:
Health insurance platforms turn over fastest with annual policy renewals and dynamic pricing adjustments, while life insurance products lock in capital for multi-year durations with slower feature iteration cycles.
- Health Insurance:Platforms integrate wearable biometric streams and chronic disease management protocols into employer-sponsored wellness programs. Demand concentrates among Singapore's financial services and technology sector employers seeking unified benefits administration with real-time claims analytics.
- Life Insurance:Digitally licensed carriers deploy direct-to-consumer term products with streamlined medical underwriting via natural language processing. Singapore's corporate employee benefits managers drive volume through group policies with accelerated issuance timelines.
- Property Insurance:Computer vision damage assessment tools compress claims cycles from weeks to hours for routine residential and commercial exposures.
- Auto Insurance:Usage-based models leverage telematics data for dynamic premium adjustments, though adoption remains constrained by PDPC consent requirements for behavioral data collection.
Health insurance dominates installed base through employer channel penetration. Life insurance is where expansion concentrates as MAS sandbox licensing accelerates digital-first carrier entry.
Customer Type:
Cost tier stratification separates high-touch corporate mandates from low-margin individual acquisitions, with SMEs occupying the middle ground where embedded distribution economics prove most compelling.
- Individuals:Direct-to-consumer platforms target digitally native segments with instant-quote term life and micro-health products. Acquisition costs remain elevated due to PDPC biometric consent friction and marketing spend competition.
- SMEs:Embedded insurance adoption expands as payment processors and e-commerce platforms integrate coverage into transaction workflows. Singapore's SME sector drives parametric and on-demand product validation through MAS sandbox testing.
- Corporates:Benefits consolidation demands unified platforms combining health coverage, wellness programs, and claims analytics. Single-point insurtech solutions face displacement from bank and telecom distributors.
- Startups:Venture-backed firms prioritize flexible, month-to-month coverage with API-first issuance and minimal medical underwriting requirements.
Corporates dominate installed base through multi-year group policy commitments. SMEs represent the steepest expansion trajectory as embedded distribution bypasses traditional broker economics.
Distribution Channel:
Volume concentration shifts toward API-enabled partnerships as customer acquisition costs through traditional intermediaries compress margins below sustainable thresholds for digital-native carriers.
- Online Platforms:Direct digital distribution leverages real-time underwriting engines and instant policy issuance for standardized products. Singapore's mobile-first consumer base drives platform engagement metrics.
- Agents:Human intermediaries retain relevance for complex commercial lines and high-net-worth individual advisory, though their share erodes in commoditized personal lines.
- Brokers:Traditional intermediaries face margin compression as API-first platforms enable carriers to bypass wholesale channels for SME and individual segments.
- B2B Partnerships:Embedded distribution through banks, telecoms, and e-commerce marketplaces expands addressable premium pools beyond insurance-native touchpoints.
B2B partnerships dominate installed base through existing customer relationship leverage. Online platforms are where expansion concentrates as MAS sandbox approvals validate direct digital licensing models.
Technology:
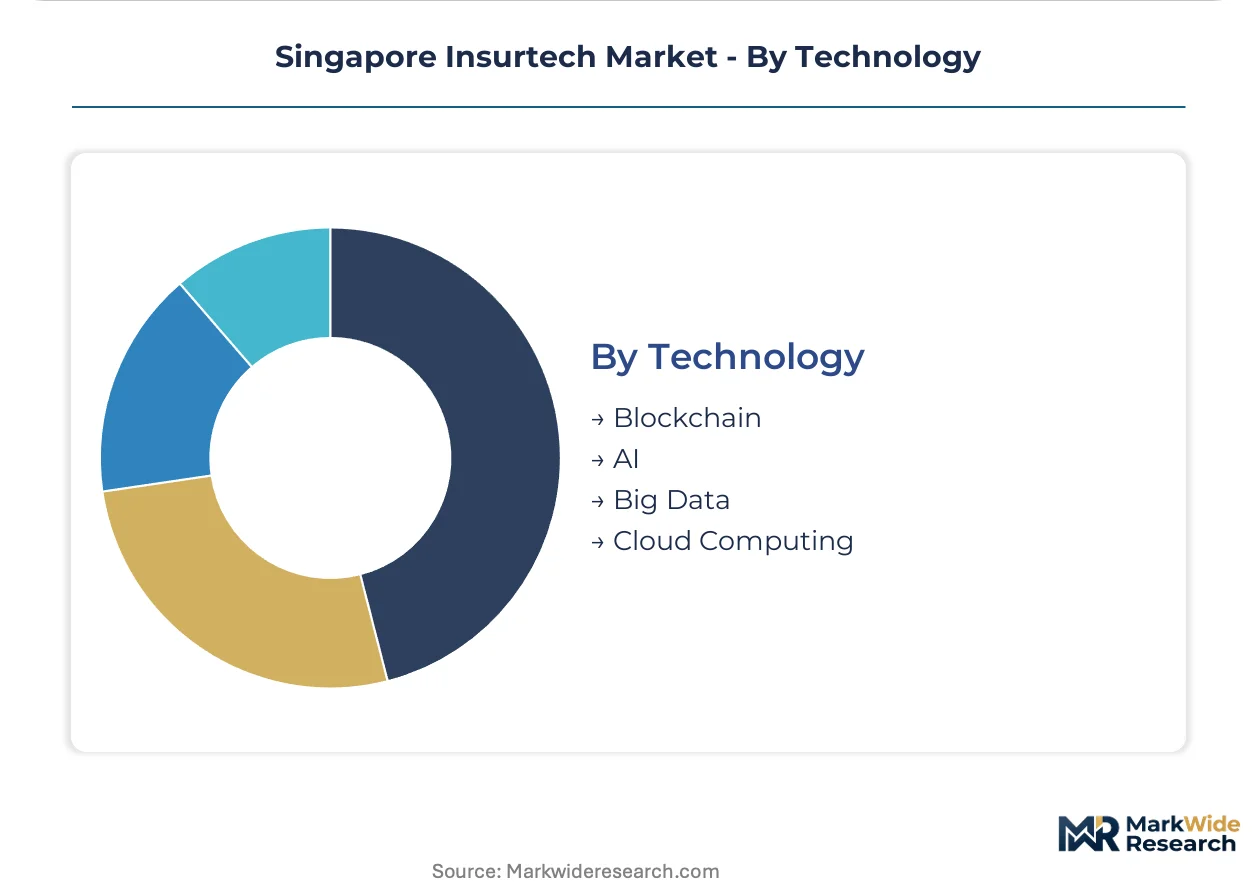
Supply concentration in cloud infrastructure creates systemic dependencies, while AI underwriting engines differentiate fastest on compressed cycle times and capital efficiency metrics.
- AI:Natural language processing systems reduce medical record review from days to minutes, lowering acquisition costs for health and life products. Singapore's talent scarcity in actuarial data science delays model deployment cycles.
- Cloud Computing:Hyperscale backend infrastructure sustains scalability for seasonal premium spikes and catastrophe exposure modeling, though concentration risk emerges during regional outages.
- Big Data:Behavioral and biometric data streams enable dynamic pricing models, constrained by PDPC consent frameworks and data sovereignty considerations.
- Blockchain:Smart contract applications target parametric catastrophe coverage with instant-trigger indemnity payments, though production deployment remains limited.
Cloud computing dominates installed base as foundational infrastructure for policy administration. AI is where expansion concentrates as underwriting automation becomes the primary competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports embedded insurance infrastructure and API-first distribution platforms to Southeast Asian markets seeking digital underwriting capabilities. Malaysian and Indonesian carriers license Singapore-developed policy administration systems to bypass legacy modernization costs. The city-state's regulatory sandbox approvals serve as de facto certification for cross-border technology deployment.
Malaysia
Malaysian insurers adopt Singapore-sourced embedded distribution APIs for e-commerce and digital wallet integrations. Bank Negara Malaysia's Financial Technology Enabler Group permits sandbox testing of parametric micro-insurance products. Kuala Lumpur's financial district hosts regional headquarters of Singapore-licensed insurtechs distributing SME coverage into Selangor and Johor manufacturing corridors.
Indonesia
Indonesian digital banks integrate Singapore-developed insurance marketplaces into mobile lending workflows. Otoritas Jasa Keuangan regulations on digital financial innovation create licensing pathways for Singapore-origin underwriting engines. Jakarta's fintech cluster attracts Singapore insurtechs establishing joint ventures with local e-commerce platforms for on-demand coverage.
Thailand
Thai insurers license Singapore cloud-native policy administration systems to replace decades-old core platforms. Bank of Thailand's regulatory sandbox framework accommodates foreign-developed parametric insurance models for agricultural and property lines. Bangkok's insurance broker district increasingly sources real-time underwriting capabilities from Singapore API providers.
Vietnam
Vietnamese digital payment platforms embed Singapore-originated micro-insurance products into ride-hailing and delivery transactions. State Bank of Vietnam guidelines on digital financial services enable pilot programs for foreign-insurtech partnerships. Ho Chi Minh City's emerging fintech hub serves as testing ground for Singapore-developed dynamic pricing algorithms in motor and health lines.
Philippines
Philippine mobile wallet operators deploy Singapore-sourced embedded insurance infrastructure for catastrophe and health micro-coverage. Bangko Sentral ng Pilipinas' digital bank licensing creates distribution channels for Singapore-origin underwriting platforms. Manila's business process outsourcing sector adopts Singapore-developed AI claims processing tools for international carrier clients.
Singapore Insurtech Market Competitive Landscape
Channel-controlling players compete with product-specialist players for distribution leverage in Singapore's insurance sector. The market structure concentrates around three strategic archetypes: embedded distribution platforms, no-code policy administration providers, and digitally licensed direct carriers. Consolidation pressure favors scale players with existing customer relationship networks. Competitive moves center on API partnership expansion and regulatory sandbox pre-emption.
Among embedded distribution specialists, bolttech anchors the marketplace infrastructure tier connecting insurers with non-insurance partners. CoverGo occupies the no-code policy administration segment reducing carrier deployment cycles. Singlife exemplifies the digitally licensed carrier archetype with direct-to-consumer term products. These three represent distinct competitive vectors rather than direct substitutes, with each archetype capturing value at different points in the insurance value chain.
| Leading Market Players |
|---|
| bolttech |
| Igloo |
| CoverGo |
| Singapore Life |
| CXA Group |
| Income Insurance |
| Singlife |
| Great Eastern |
| Prudential Assurance Company |
| Others |
Value Network & Pricing Analysis
Singapore-Johor freight corridors transmit cloud infrastructure costs from Malaysian data centers into domestic insurtech pricing tiers, concentrating margin pressure on carriers dependent on hyperscale backend services while enabling price differentiation between API-native distributors and legacy-dependent underwriters.
Pricing Analysis
Cost-plus contracts with hyperscale cloud providers indexed to regional electricity tariffs dominate infrastructure economics for Singapore's digital insurers. Three-tier pricing structure across enterprise-grade, mid-market, and SME API tiers separates carriers by integration complexity and policy volume commitments. Pricing pressure stems from MAS risk-based capital recalibration uncertainty compressing product margin assumptions. SME embedded distribution partners exhibit highest price sensitivity due to transaction-margin constraints, while corporate benefits managers prioritize platform consolidation over unit cost.
Supply Chain Analysis
Tariff exposure between Singapore and Malaysia dominates supply chain risk for cloud infrastructure and cross-border data pipeline dependencies. Policy administration software draws from development centers in Singapore, India, and Vietnam, with AI underwriting engines sourcing GPU compute from Taiwan and South Korea. Single-source vulnerability concentrates in hyperscale cloud concentration for core systems. Distribution runs through API-first B2B partnerships with banks and e-commerce platforms, bypassing traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's insurtech sector sits in early-cycle expansion as MAS sandbox licensing accelerates digital-first carrier penetration beyond legacy incumbent strongholds.
For Market Incumbents: Entrench defensible positions by accelerating legacy core system migration to cloud-native architectures before digital-native competitors achieve scale economies. Prioritize API partnership control with Singapore's banking and telecom distributors to lock out embedded distribution challengers. MAS capital requirement uncertainty demands proactive product mix optimization toward parametric structures with favorable solvency treatment.
For New Entrants and Emerging Players: Pursue white-space opportunities in SME embedded insurance through payment processor and e-commerce platform integrations where traditional broker economics fail. Target Malaysia and Indonesia cross-border distribution via regulatory recognition frameworks, leveraging Singapore sandbox approvals as de facto certification. Lead with chronic disease management platforms integrating wearable data streams to capture employer wellness program budgets.
For Investors and Strategic Acquirers: No-code policy administration specialists with established carrier deployment track records represent the most defensible acquisition archetype in this market. Long-term viability hinges on regulatory sandbox velocity sustaining digital licensing momentum against incumbent lobbying pressure. Monitor MAS risk-based capital framework updates as the critical inflection signal for digital insurer competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership Expansion | Embedded distribution through DBS and Grab Financial bypasses traditional broker channels for SME acquisition. |
| Regulatory Sandbox Pre-emption | MAS FinTech Regulatory Sandbox approvals validate parametric product structures before full licensing requirements. |
| No-Code Platform Deployment | CoverGo's policy administration tools reduce carrier implementation cycles from months to weeks. |
| Cross-Border Distribution Licensing | Singapore-origin platforms leverage Bank Negara Malaysia recognition frameworks for Selangor market entry. |
| AI Underwriting Engine Development | Natural language processing systems compress Singlife medical record review timelines from days to minutes. |
Research Methodology
Operator-level perspectives from digital insurer CTOs, MAS regulatory affairs leads, corporate benefits managers at financial services firms, and API platform engineering heads anchored the qualitative base. Secondary validation drew from MAS sandbox approval disclosures, PDPC consent framework guidance, carrier annual reports, and Southeast Asian fintech venture funding databases. Bottom-up policy volume estimates triangulated against top-down premium pool assessments across the Singapore insurance sector.
Scenario-bracketing framed projections across conservative, baseline, and accelerated MAS licensing velocity assumptions. Segmentation dimensions modeled include product type, customer tier, distribution channel architecture, and technology stack maturity. CAGRs derived from policy issuance volume trajectories and premium per policy trends, with cross-border expansion rates and AI underwriting adoption curves as key forecast inputs.
Sensitivities concentrate around MAS capital requirement recalibration timing and PDPC biometric consent enforcement intensity. Forecasts reflect assumptions on sandbox graduation rates and SME embedded insurance penetration trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
United States Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Insurance Software Market
Insurance Technology
Global Insurance Telematics Market