
 Asia-Pacific P&C Insurance Software Market | 2026-2036
Asia-Pacific P&C Insurance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific P&C Insurance Software Market Insights
Buyer concentration among mid-tier insurers across Southeast Asia is rebalancing as regional carriers consolidate while independent brokerages fragment into specialized niches. Guidewire Software Inc. sustains technology leadership in cloud-native core platforms across Australian and Japanese carriers. Sapiens International Corporation dominates policy administration modernization for tier-two insurers in India and Israel. Duck Creek Technologies positions its configurable SaaS stack to compete for greenfield deployments among digital-first entrants in Singapore and Hong Kong.
Asia-Pacific P&C insurance software encompasses core systems, claims management, policy administration, and analytics modules engineered on microservices architectures with API-first interoperability standards, serving carriers' actuarial automation, fraud detection, and regulatory reporting workflows. Cloud-based deployment leads absolute spending as APRA, IRDAI, and Japan's FSA mandate operational resilience and data sovereignty controls. Analytics segments capture disproportionate margin pools where real-time catastrophe modeling and telematics-driven pricing engines differentiate vendor offerings. On-premises legacy estates persist among Japan's mutual insurers and China's state-owned carriers, creating hybrid integration demand.
IRDAI mandates digital public infrastructure compatibility and sandbox licensing for insurtech partnerships, while APRA CPS 234 imposes prudential cybersecurity standards that shape vendor qualification criteria across Australian insurers. Japan's FSA and METI coordinate on fintech licensing frameworks that govern cross-border data flows for regional software deployments. Stakeholders must monitor how divergent data localization requirements between India, China, and ASEAN jurisdictions constrain single-tenant cloud architectures and force multi-region infrastructure investments.
Market Dynamics
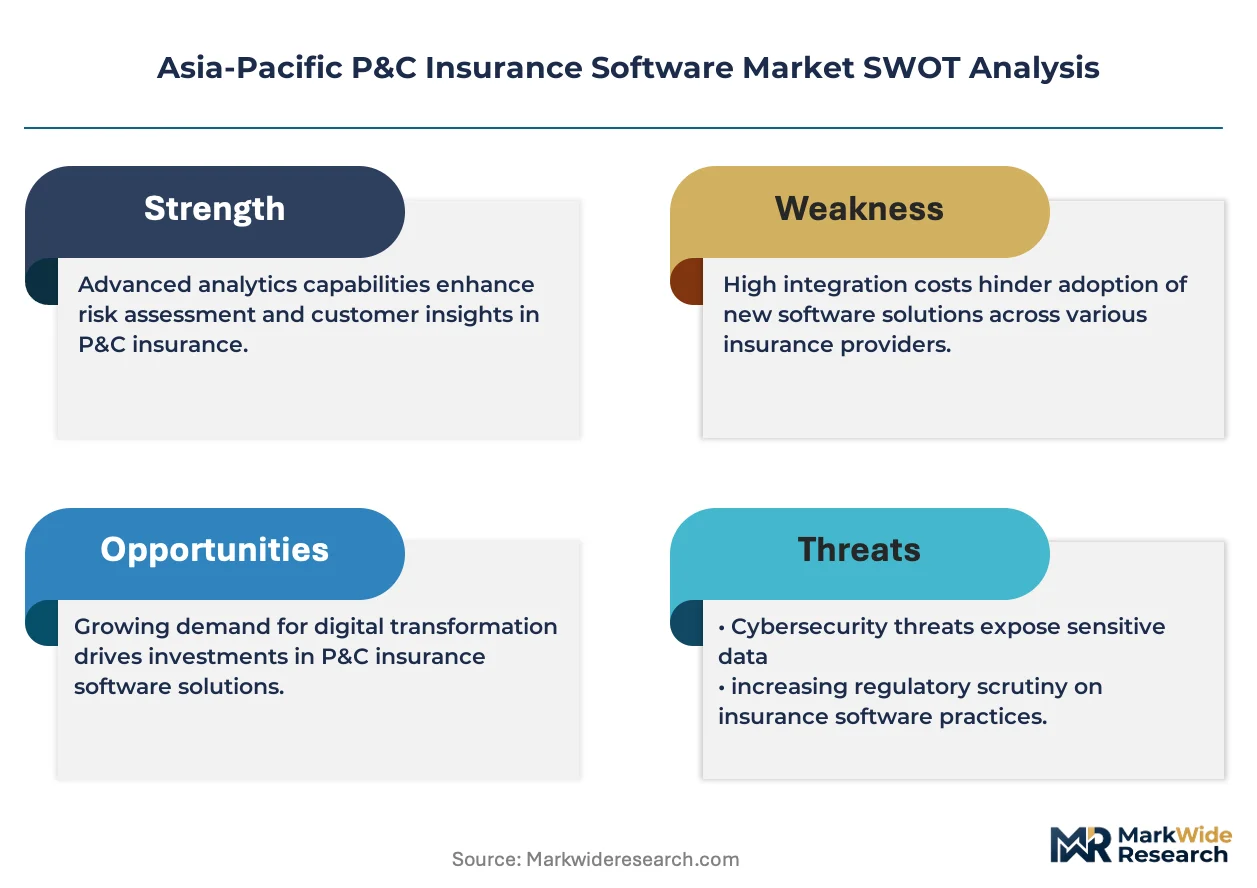
APRA CPS 234 cybersecurity mandates and IRDAI's cloud-first directives are compressing procurement cycles across Asia-Pacific carriers, forcing simultaneous core system replacement and compliance architecture rebuilds.
Growth Catalysts
- APRA CPS 234 Compliance:Australian prudential cybersecurity standards mandate operational resilience controls that accelerate SaaS procurement among tier-one and tier-two insurers.
- Telematics Integration:Usage-based auto insurance platforms embed real-time driving data into pricing engines, expanding addressable premium pools for motor carriers.
- India:IRDAI's digital public infrastructure compatibility requirements push domestic insurers toward API-first core system architectures.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscaler dominance in Singapore and Sydney data centers creates single-point-of-failure risks for multi-tenant insurance platforms.
- Legacy Integration Costs:COBOL-based policy administration systems at Japan's mutual insurers require expensive middleware layers for API connectivity.
- Data Localization Friction:Divergent sovereignty requirements between India, China, and ASEAN jurisdictions fragment single-tenant architectures into multi-region deployments.
Strategic Opportunities
- Vietnam and Philippines:Underpenetrated general insurance markets with low software penetration rates offer greenfield SaaS deployment potential.
- Parametric Insurance:Climate-risk products linked to satellite weather data create demand for automated claims triggers and instant payout engines.
- Embedded Insurance:B2B2C distribution through e-commerce platforms and ride-hailing apps opens alternative customer acquisition channels outside traditional agency networks.
Industry Challenges
- Actuarial-Engineering Talent Gap:Scarce professionals who bridge statistical modeling and cloud-native system architecture delay implementation timelines.
- Multi-Generational System Integration:Hybrid estates combining 1980s mainframe cores with microservices layers multiply testing and failure-mode complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific P&C Insurance Software Market |
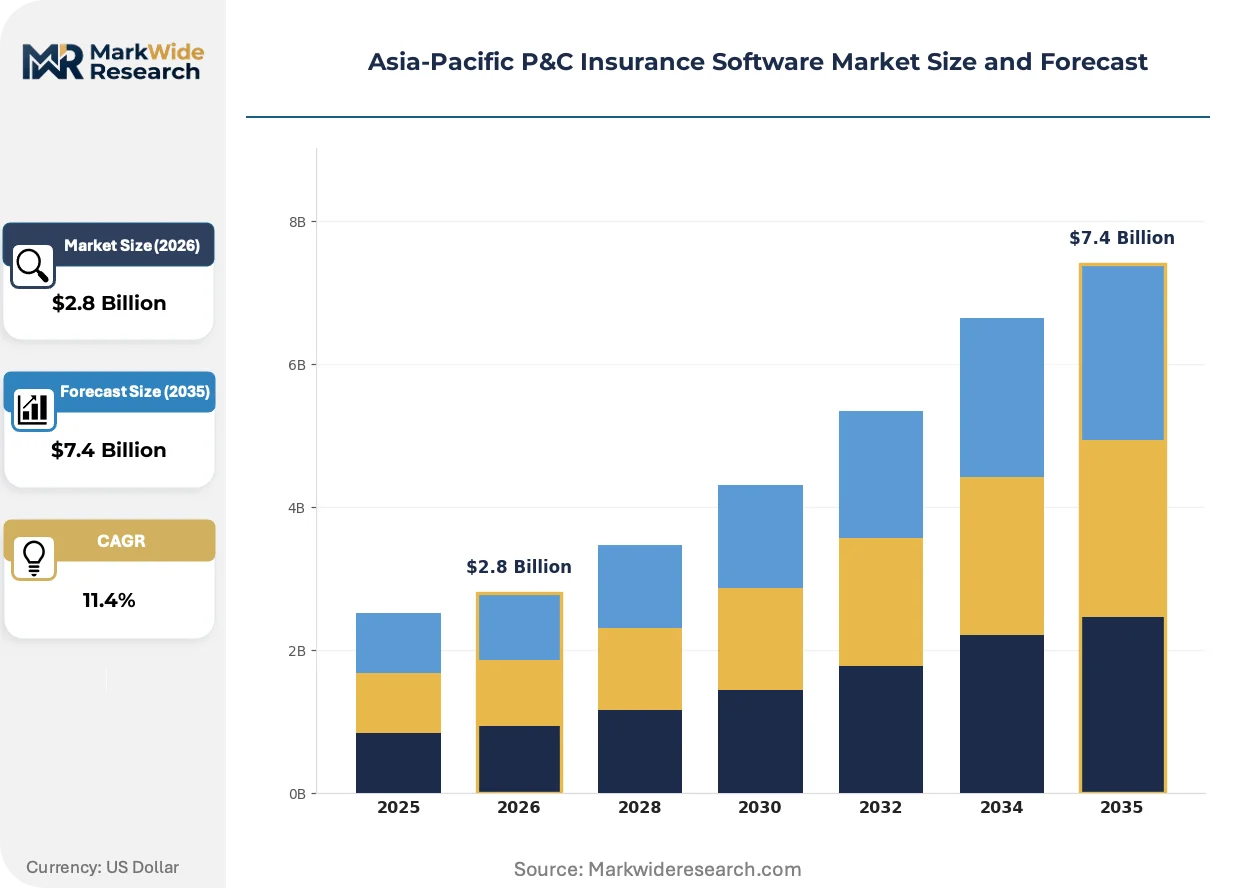
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Systems, Claims Management, Policy Administration, Analytics Deployment: On-Premises, Cloud-Based, SaaS, Hybrid End User: Insurance Companies, Brokers, Agents, Reinsurers Service Type: Integration, Consulting, Support, Training |
| Companies Covered | Sapiens International Corporation, Pegasystems Inc., Guidewire Software Inc., FINEOS Corporation Limited, Ebix Inc., Duck Creek Technologies, DXC Technology Company, Insuresoft Inc., Majesco Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific P&C Insurance Software Market Trends and Innovations
Microservices-based core platforms are displacing monolithic legacy suites as carriers prioritize API interoperability and continuous deployment pipelines over single-vendor lock-in.
Artificial intelligence-powered fraud detection engines analyze claims patterns across unstructured documents and image metadata. Mid-tier Australian and Japanese carriers deploy these tools within six-month implementation windows. Predictive analytics is converging with real-time catastrophe modeling to compress reinsurance placement cycles from weeks to hours.
IRDAI's sandbox licensing framework for insurtech partnerships creates structured pathways for carriers to pilot algorithmic underwriting models. The framework mandates data escrow and audit trails that shape vendor qualification criteria. Indian tier-two insurers respond by establishing dedicated digital innovation units with direct board reporting lines.
Subscription-based pricing for core system modules displaces perpetual license models that dominated procurement through the 2010s. Brokerages and managing general agents in Hong Kong and Singapore now demand usage-aligned fees tied to policy volumes processed. This shift concentrates vendor risk on retention metrics rather than upfront implementation revenue.
Asia-Pacific P&C Insurance Software Market Segmentation
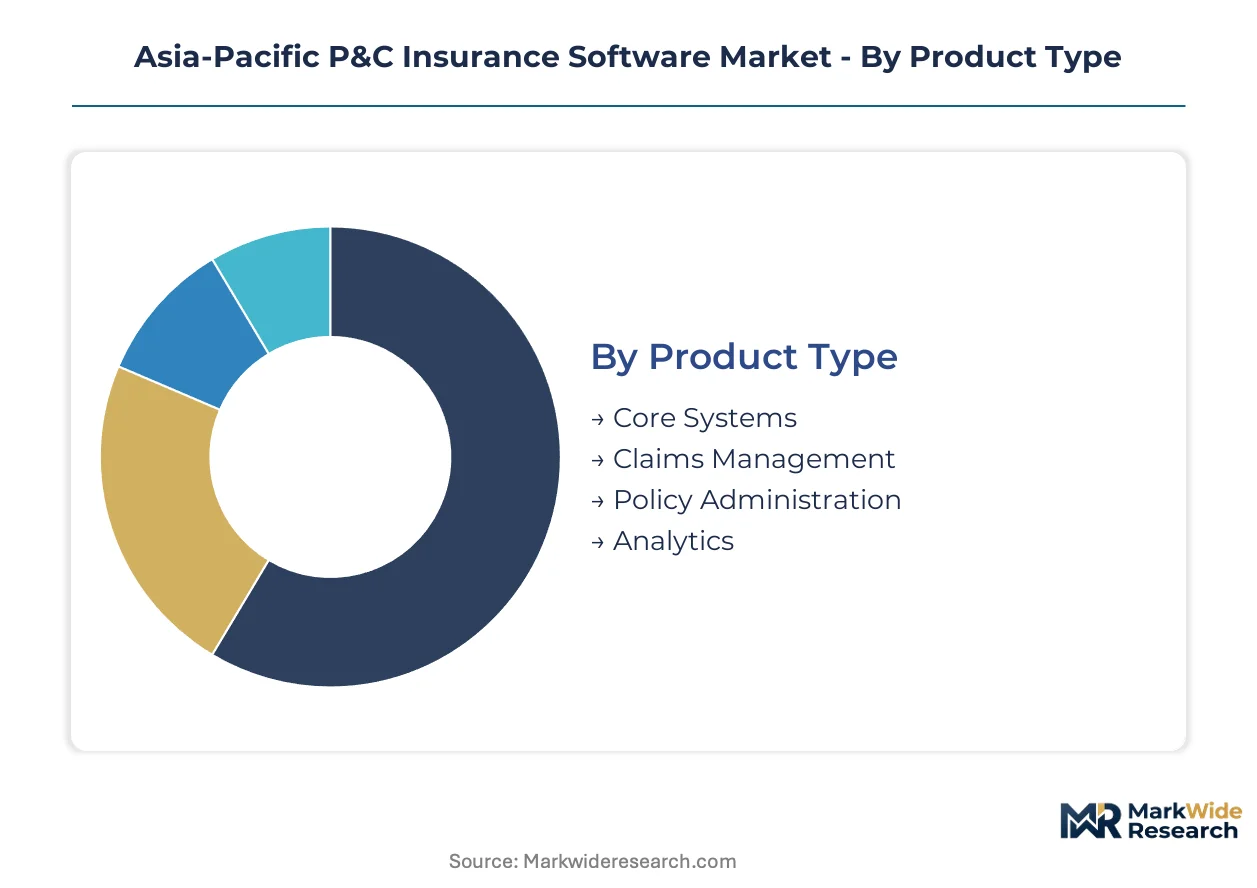
Segmentation reveals how procurement priorities diverge across Asia-Pacific carriers. Regulatory mandates from APRA, IRDAI, and Japan's FSA reshape spending patterns by deployment model and product type. Understanding these splits exposes where vendor margins concentrate versus where price competition erodes profitability.
Product Type:
Supply concentrates in platforms that combine policy lifecycle management with embedded compliance controls.
- Core Systems:Policy administration engines built on microservices architectures handle underwriting, billing, and reinsurance cessions through unified data models. Australian tier-one carriers prioritize these platforms to satisfy APRA CPS 234 operational resilience mandates. Core Systems absorb the bulk of installed capacity; Analytics is expanding most quickly.
- Claims Management:Automated workflows route first-notice-of-loss through fraud detection engines and reserve estimation algorithms. Japanese motor insurers deploy these modules to compress claims cycle times from weeks to days.
- Policy Administration:Rating engines and document generation tools configurable through low-code interfaces. Indian tier-two insurers favor these for IRDAI-mandated product filing agility.
- Analytics:Catastrophe modeling, telematics pricing, and predictive risk scoring delivered via API. Singaporean carriers embed these capabilities into usage-based auto and parametric weather products.
Core Systems commands the largest share of carrier IT budgets; Analytics platforms are climbing the fastest as pricing sophistication becomes a competitive differentiator.
Deployment:
Cost tier structures segment procurement between capital-intensive legacy estates and operational-expense SaaS models.
- Cloud-Based:Single-tenant or multi-tenant infrastructure hosted in Sydney, Singapore, or Mumbai data centers. APRA and IRDAI data sovereignty rules mandate in-region processing for Australian and Indian carriers. Cloud-Based deployments dominate new procurement; SaaS is gaining share fastest.
- SaaS:Subscription-priced modules with vendor-managed updates and elastic capacity scaling. Hong Kong digital insurers and Southeast Asian greenfield entrants favor this model to preserve capital.
- On-Premises:Licensed software running on carrier-owned hardware in Tokyo, Osaka, or Beijing facilities. Japan's mutual insurers and China's state-owned carriers maintain these estates due to governance constraints.
- Hybrid:Core policy data remaining on-premises while customer-facing portals and analytics migrate to cloud. Australian regional carriers adopt this architecture during phased modernization programs.
Cloud-Based deployments capture the majority of new spending; SaaS represents the steepest expansion trajectory among digital-first entrants.
End User:
Customer type determines contract structure, with direct carriers demanding deep customization and intermediaries prioritizing speed-to-market.
- Insurance Companies:Direct writers and mutuals procuring enterprise-wide platform replacements. These buyers negotiate multi-year contracts with implementation services bundled.
- Brokers:Independent and tied intermediaries in Australia and Hong Kong seeking comparative rating and policy placement tools. They drive demand for usage-aligned pricing models.
- Agents:Captive and independent sales forces across Southeast Asia requiring mobile-first quoting applications with offline synchronization.
- Reinsurers:Treaty and facultative carriers in Singapore and Tokyo deploying exposure management and ceded reinsurance accounting modules.
Insurance Companies account for the largest deployment base; Brokers are expanding most quickly as intermediary digitization accelerates.
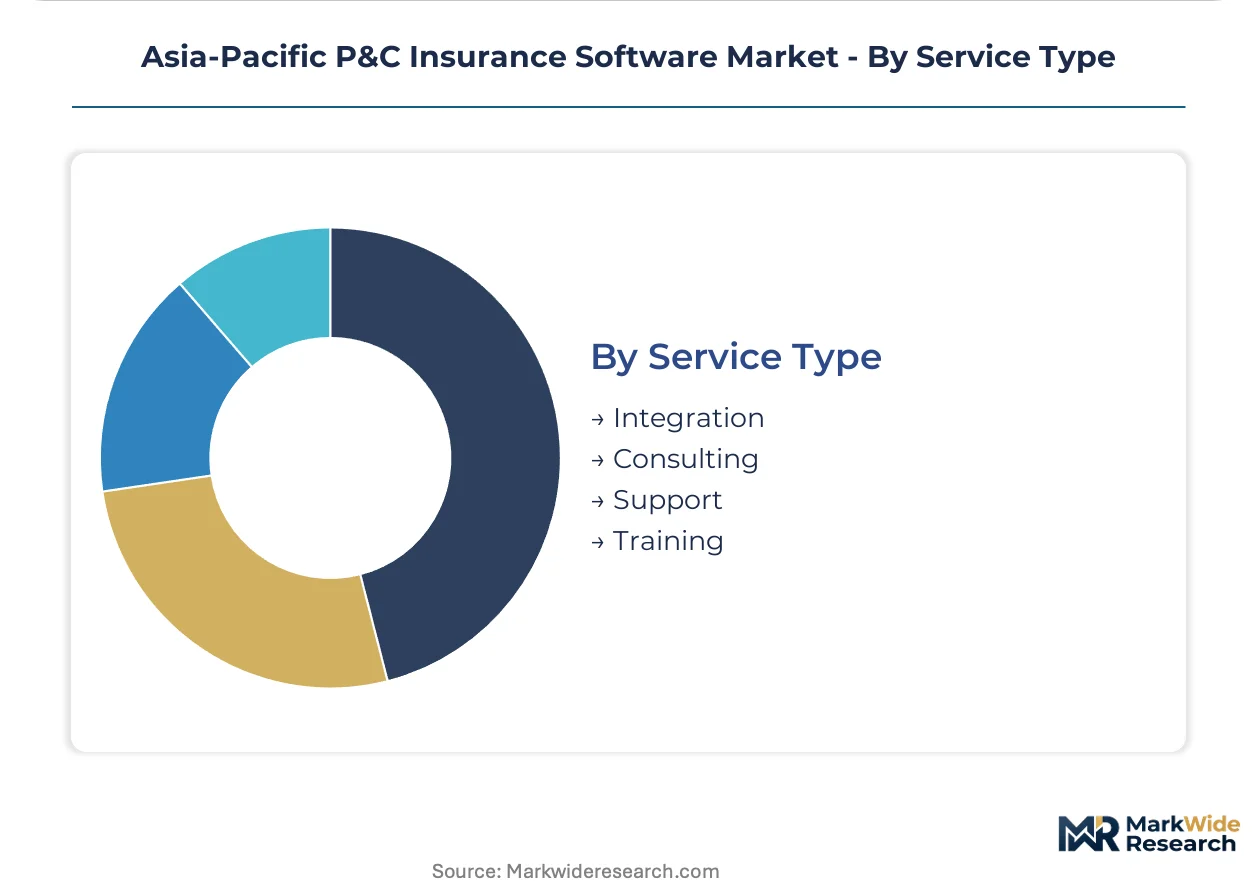
Service Type:
Margin concentration follows complexity, with integration services commanding premium pricing while support contracts commoditize.
- Integration:Middleware development connecting legacy COBOL cores to modern API layers. Japanese carriers pay substantial premiums for these skills given scarce mainframe-to-cloud expertise.
- Consulting:Business process redesign and change management for core system replacements. Indian insurers engage these services to align IRDAI compliance with operational workflows.
- Support:Tiered helpdesk and maintenance contracts with response-time SLAs. These services face pricing pressure as carriers push toward self-service knowledge bases.
- Training:Certification programs for carrier IT staff and business users on vendor-specific platforms. Australian insurers mandate these investments to reduce long-term dependency on external resources.
Integration services absorb the bulk of professional services spending; Consulting is climbing the fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments in Sydney and Singapore anchor Asia-Pacific software deployment capacity. Mumbai data centers process Indian carrier workloads under IRDAI sovereignty mandates. Tokyo and Osaka facilities retain on-premises estates for mutual insurers.
Australia
Tier-one carriers accelerate SaaS procurement to satisfy APRA CPS 234 operational resilience deadlines. The prudential regulator mandates cybersecurity controls that compress vendor qualification timelines. Sydney-based regional carriers adopt hybrid architectures during phased modernization programs.
India
Domestic insurers modernize legacy core systems amid IRDAI pressure for digital public infrastructure compatibility. The insurance regulator's sandbox licensing framework structures insurtech partnership pathways. Mumbai and Bangalore clusters concentrate tier-two carrier procurement for policy administration engines.
Japan
Mutual insurers maintain COBOL-based estates requiring expensive middleware for API connectivity. METI and FSA coordinate fintech licensing frameworks governing cross-border data flows. Tokyo carriers deploy automated claims workflows to compress cycle times from weeks to days.
Singapore
Digital-first entrants favor subscription-priced SaaS modules to preserve capital for greenfield operations. The Monetary Authority of Singapore supervises data localization requirements for regional headquarters. Marina Bay financial district hosts reinsurance exposure management platform deployments.
Vietnam
Underpenetrated general insurance markets offer greenfield SaaS deployment potential with minimal legacy friction. The Ministry of Finance regulates foreign software vendor licensing for domestic carriers. Ho Chi Minh City brokerages digitize comparative rating tools for emerging middle-class segments.
Asia-Pacific P&C Insurance Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue configurable microservices architectures for greenfield deployments. Market structure consolidates around cloud-native core platforms while fragmenting across specialized analytics modules. Three archetypes dominate: legacy-suite modernizers, API-first specialists, and vertical SaaS configurators. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into embedded insurance distribution channels.
Within the cloud-native tier, Guidewire Software Inc. and Duck Creek Technologies exemplify platform consolidation strategies. Sapiens International Corporation anchors policy administration modernization for tier-two carriers. These three entities represent distinct geographic positioning—Guidewire penetrating Australian and Japanese markets, Duck Creek targeting Singapore and Hong Kong digital entrants, and Sapiens dominating Indian domestic procurement.
| Leading Market Players |
|---|
| Sapiens International Corporation |
| Pegasystems Inc. |
| Guidewire Software Inc. |
| FINEOS Corporation Limited |
| Ebix Inc. |
| Duck Creek Technologies |
| DXC Technology Company |
| Insuresoft Inc. |
| Majesco Limited |
| Others |
Pricing and Supply Chain Analysis
Microservices-based platform delivery is compressing implementation timelines from years to months while simultaneously fragmenting vendor margins across subscription tiers. This architectural shift concentrates procurement power among Australian and Singaporean carriers with APRA and MAS cloud mandates, forcing price transparency into previously opaque enterprise licensing negotiations.
Pricing Analysis
Implementation services bundled versus unbundled from core platform subscriptions creates the primary pricing fault line across Asia-Pacific carrier procurement. Three-tier pricing structure across premium, standard, and economy levels separates Guidewire-tier enterprise deployments from Sapiens mid-market offerings and Duck Creek digital-native configurations. Price differentiation hinges on customization depth and IRDAI compliance certification tier. Cost compression in the standard tier is intensifying because Indian tier-two carriers demand fixed-fee implementations. Brokers and managing general agents exhibit highest price sensitivity; tier-one Australian mutuals show lowest sensitivity due to APRA-mandated resilience requirements.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler concentration in Sydney and Singapore data centers hosting multi-tenant insurance platforms. Software development capacity concentrates in India, Israel, and the United States; cloud infrastructure draws from AWS, Azure, and Google Cloud regional facilities. Supply chain risk centers on regulatory fragmentation forcing multi-region deployment architectures. Distribution runs through direct enterprise sales teams for tier-one carriers, systems integrators for mid-market modernization, and digital marketplaces for insurtech partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary data layers and captive cloud infrastructure is accelerating as vendors seek margin defense against hyperscaler commoditization. This race shapes competitive positioning across the forecast window.
For Market Incumbents: Deploy compliance certification moats around APRA CPS 234 and IRDAI sandbox frameworks to lock out unqualified competitors. Acquire specialized analytics boutiques in Singapore and Bangalore to close capability gaps in real-time catastrophe modeling. Threat substitution from low-code insurtech configurators demands pre-emptive API ecosystem control. For New Entrants and Emerging Players: The price-point gap between premium Guidewire deployments and economy-tier legacy modernization creates entry space for configurable microservices stacks. Vietnam and Philippines greenfield carriers represent the most penetrable geography with minimal COBOL integration burden. Lead with usage-based pricing aligned to policy volume growth rather than upfront license commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler strategic acquisitions and private equity roll-ups of regional specialists. Long-term viability favors vendors with demonstrated IRDAI sandbox approvals and APRA operational resilience certifications. Watch IRDAI digital public infrastructure mandate acceleration as the inflection signal for Indian market consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures satisfy APRA CPS 234 interoperability mandates for Australian tier-one carriers. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure anchor data sovereignty compliance across Singapore and Sydney regions. |
| Acquisition of Specialist Firm | Telematics analytics boutiques in Bangalore accelerate usage-based auto insurance product launches. |
| Geographic Expansion | Vietnam and Philippines presence captures greenfield SaaS demand with minimal legacy integration friction. |
| Product Launch | Parametric weather modules with satellite data triggers open climate-risk product categories for Southeast Asian carriers. |
Research Methodology
Document review covered vendor SEC filings, IRDAI regulatory circulars, and APRA prudential standards, complemented by interviews with chief technology officers at Australian tier-one carriers, IRDAI compliance officers at Indian domestic insurers, and platform engineers at Singaporean digital entrants. Secondary sources included carrier annual reports, hyperscaler regional capex disclosures, and insurtech partnership announcements. Bottom-up policy administration deployment estimates triangulated against top-down regional IT spending forecasts.
Market sizing outputs segmented across deployment models, product types, and end-user categories throughout the forecast period. CAGRs derived from regression analysis against carrier premium growth trajectories and regulatory mandate implementation timelines. Key inputs included IRDAI digital public infrastructure compatibility deadlines, APRA CPS 234 compliance phase-in schedules, and telematics penetration rates across motor insurance portfolios.
Inputs from regulatory filings and vendor financial disclosures were available through the study window; gaps in private carrier IT budget allocations introduce uncertainty bands around tier-two insurer modernization forecasts. Deviation in IRDAI sandbox licensing velocity or APRA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
P and C Insurance Software Market