
 Japan AI in Insurance Market | 2026-2036
Japan AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan AI in Insurance Market Insights
Generative AI integration into core insurance platforms is reshaping policy lifecycle management across Japan. MS&AD Insurance Group Holdings leverages extensive proprietary claims databases to train specialized underwriting models. Tokio Marine Holdings anchors its competitive stance through sustained R&D investment in natural language processing for customer service automation. SOMPO Holdings differentiates via predictive analytics capabilities spanning risk assessment and fraud detection workflows.
Japan AI in Insurance encompasses the deployment of machine learning algorithms, natural language processing engines, and computer vision systems to automate underwriting decisions, detect anomalous claims patterns, and personalize policyholder interactions through predictive customer insights. These technologies process structured and unstructured data streams including medical records, driving telemetry, and satellite imagery to reduce loss ratios and accelerate settlement cycles. Claims Processing currently dominates product type revenue as legacy paper-based workflows convert to automated triage systems, while Fraud Detection registers the fastest expansion due to rising sophistication in staged accident schemes and medical billing irregularities. Machine Learning leads technology deployment by volume, though Predictive Analytics commands premium pricing for actuarial-grade risk quantification.
METI's AI governance guidelines and Japan's Act on Protection of Personal Information establish compliance baselines for algorithmic transparency and data minimization in insurance applications. PMDA oversight intersects where AI-enabled health insurance products incorporate diagnostic predictions, requiring clinical validation standards. Financial Services Agency prudential rules further shape capital allocation for carriers deploying black-box models in core underwriting. Stakeholders must monitor evolving regulatory expectations around explainable AI as supervisory frameworks mature beyond voluntary principles toward enforceable audit requirements.
Market Dynamics
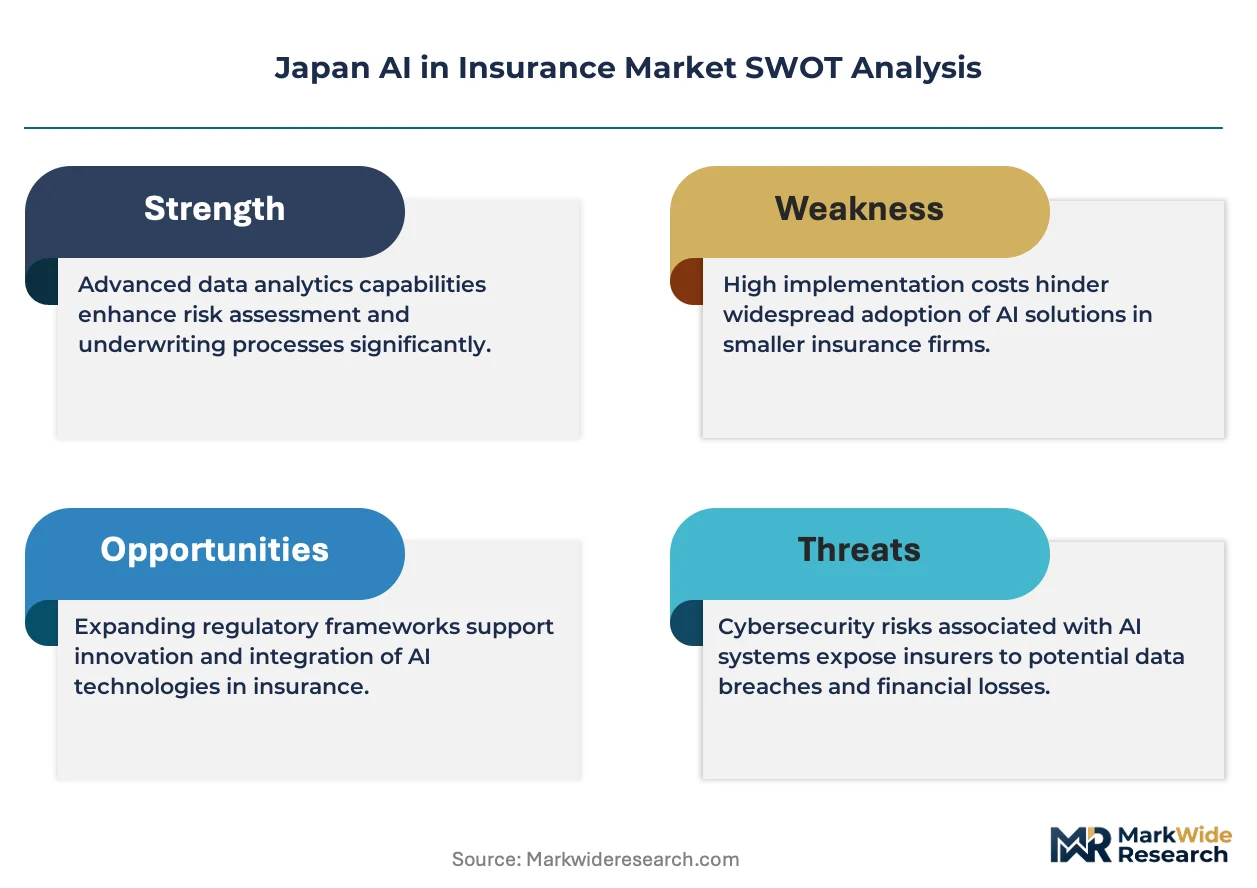
Japan's Act on Protection of Personal Information revisions are compelling carriers to abandon legacy data architectures and adopt privacy-preserving AI infrastructures, fundamentally restructuring how insurers collect, process, and monetize policyholder information.
Growth Catalysts
- Regulatory Pressure:METI's AI governance guidelines mandate algorithmic transparency standards that accelerate carrier investment in explainable underwriting models.
- Claims Automation:Property and casualty insurers deploy machine learning triage systems to compress settlement cycles from weeks to hours.
- Tokyo Cluster Concentration:Major carriers maintain centralized digital transformation offices in Tokyo's insurance district, creating knowledge spillovers and vendor ecosystem density.
Market Restraints
- Data Localization Costs:Japan's strict data residency requirements force carriers to maintain expensive domestic cloud infrastructure rather than leverage global hyperscale providers.
- Actuarial Talent Scarcity:The intersection of traditional insurance expertise and machine learning engineering skills remains severely underdeveloped in domestic labor markets.
- Black-Box Model Risk:Financial Services Agency prudential rules impose capital penalties on carriers deploying non-explainable algorithms in core underwriting functions.
Strategic Opportunities
- Rural Agency Networks:Underpenetrated prefectures outside Tokyo-Osaka corridors present first-mover advantages for AI-enabled remote underwriting and claims assessment.
- Health-Insurance Convergence:PMDA oversight pathways for diagnostic AI create openings for carriers to integrate predictive health analytics into policy pricing.
- Federated Learning Architectures:Privacy-preserving techniques allow competitors to collaboratively train fraud detection models without sharing sensitive claims data.
Industry Challenges
- Core System Integration:Decades-old policy administration platforms resist API connectivity, forcing expensive middleware layers for AI deployment.
- Model Validation Timelines:Actuarial certification processes for AI-driven pricing engines extend 18-24 months, delaying revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan AI in Insurance Market |
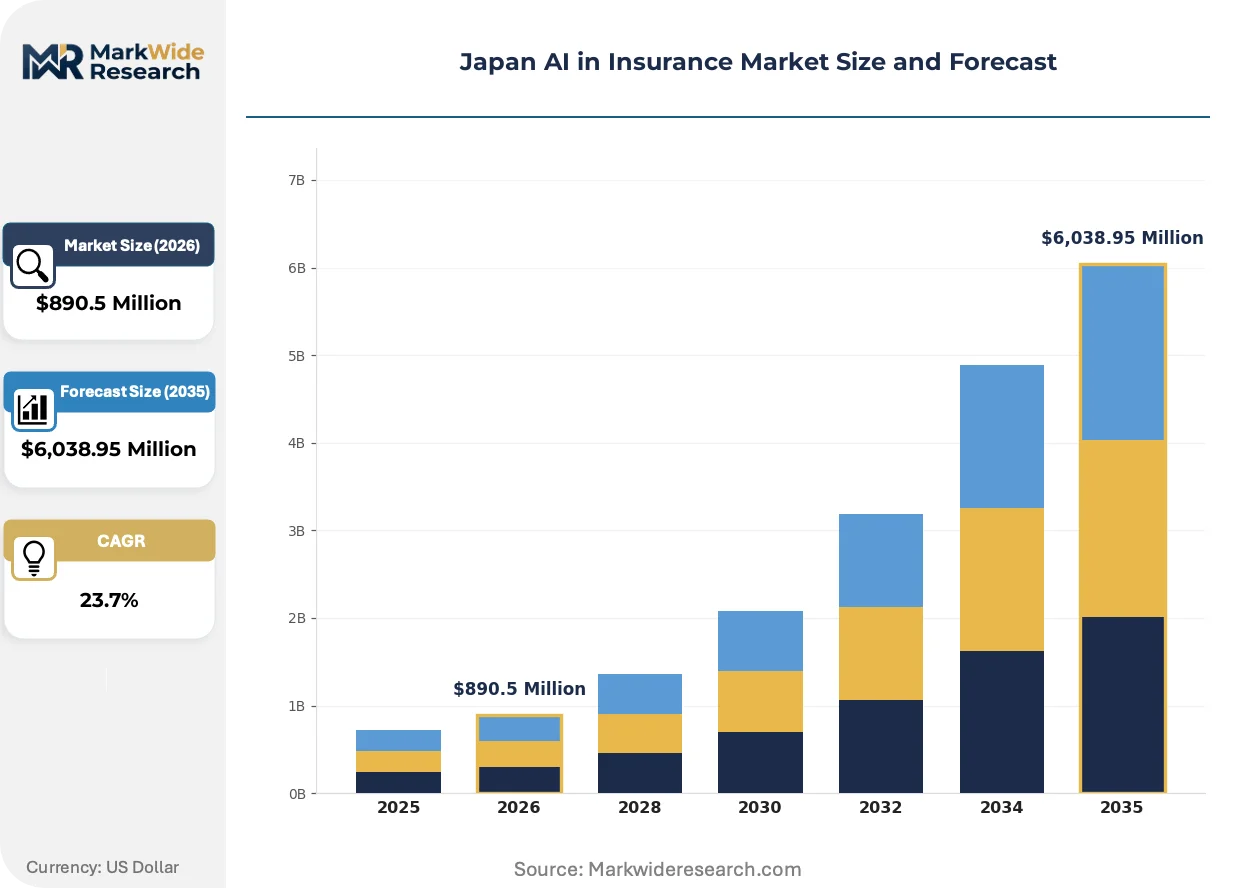
| Market Size in 2026 | $890.5 Million |
| Market Size in 2035 | $6,038.95 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Claims Processing, Fraud Detection, Underwriting Automation, Customer Service End User: Insurance Companies, Brokers, Agents, Financial Institutions Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Computer Vision Application: Risk Assessment, Policy Management, Customer Insights, Marketing Optimization |
| Companies Covered | MS&AD Insurance Group Holdings, Tokio Marine Holdings, SOMPO Holdings, Nippon Life Insurance Co., Mitsui Sumitomo Insurance, Mitsubishi UFJ Financial Group Inc., Mizuho Bank Ltd., Entrust, Onfido, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan AI in Insurance Market Trends and Innovations
Generative AI integration is compressing the policy lifecycle from quote to bind, while regulatory pressure on algorithmic accountability forces architectural redesigns across carrier technology stacks.
Large language models trained on proprietary claims corpora are rendering obsolete manual documentation review in underwriting workflows. Mid-tier carriers lacking extensive historical datasets adopt these capabilities through vendor partnerships rather than internal development. The technology is rendering obsolete traditional actuarial junior analyst roles focused on data extraction and preliminary risk classification.
METI's evolving AI governance framework now requires documented human oversight protocols for automated claims decisions above defined thresholds. Carriers must maintain audit trails demonstrating meaningful human intervention in algorithmic outputs. The property and casualty segment responds by embedding compliance checkpoints directly into machine learning pipelines rather than retrofitting post-deployment.
Corporate risk managers increasingly demand usage-based pricing transparency and granular coverage modularization rather than bundled annual policies. Digital-native intermediaries capture this demand through API-first distribution platforms that unbundle traditional agent relationships. This behavioral shift concentrates most visibly among technology sector policyholders in Tokyo and Osaka metropolitan areas.
Japan AI in Insurance Market Segmentation
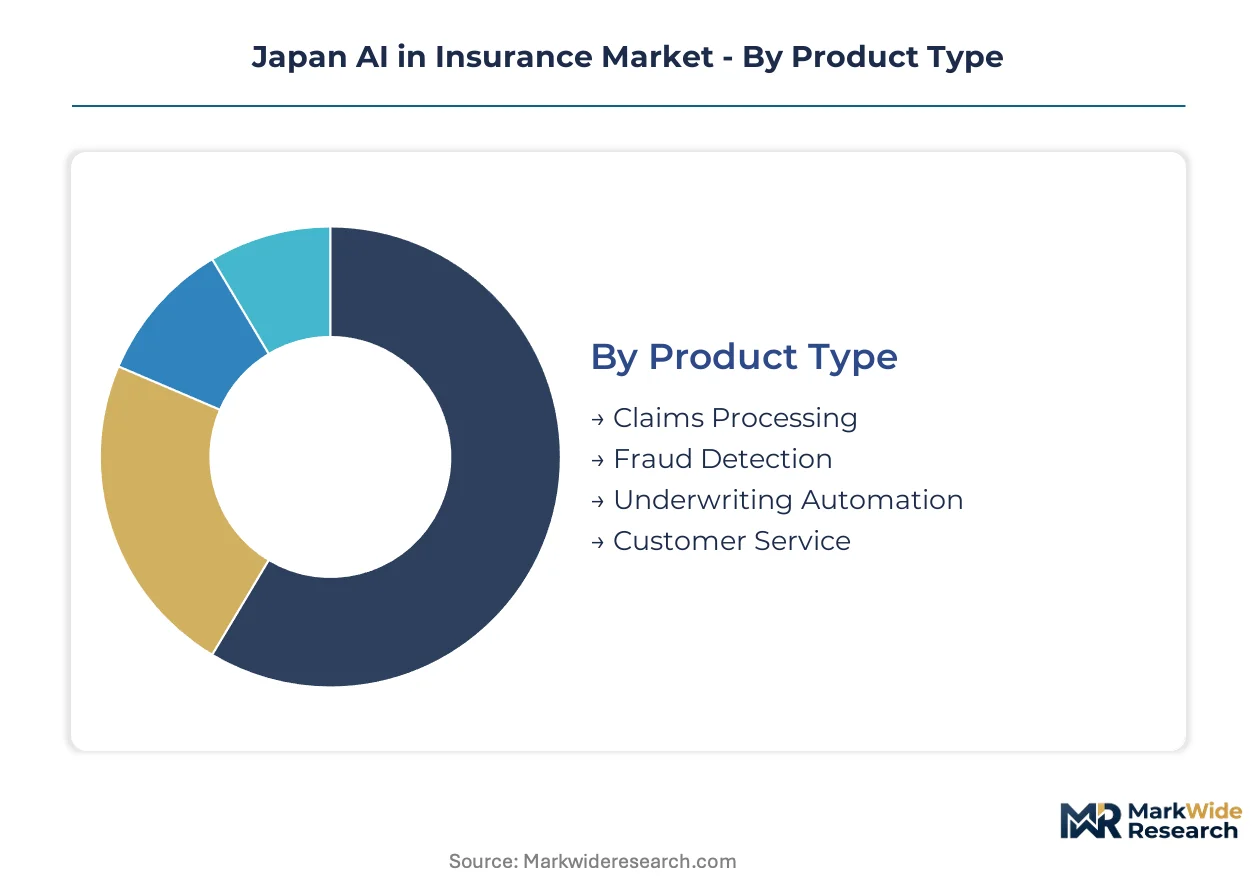
Segmentation in Japan's AI insurance market reveals how technology deployment varies by operational function, institutional buyer, and underlying technical architecture. Each dimension carries distinct procurement patterns and regulatory considerations.
Product Type:
Carriers deploy AI solutions across a spectrum from back-office automation to front-end customer engagement, with each product category commanding different integration timelines and compliance scrutiny.
- Claims Processing:Automated triage systems ingest structured and unstructured damage documentation to route claims through appropriate settlement pathways. Tokyo-based property and casualty carriers concentrate demand here as legacy paper workflows convert to digital pipelines.
- Fraud Detection:Anomaly detection models flag staged accidents and medical billing irregularities through pattern recognition across historical claims corpora. Rising sophistication in organized fraud rings across Kanto and Kansai regions accelerates carrier investment in these capabilities.
- Underwriting Automation:Machine learning models evaluate risk profiles from telemetry, medical records, and satellite imagery to compress quote-to-bind cycles.
- Customer Service:Conversational AI handles policy inquiries and claims status updates through chat and voice interfaces.
The dominant share belongs to Claims Processing, while Fraud Detection is closing the gap fastest.
End User:
Procurement authority varies significantly across the distribution chain, with each buyer type presenting distinct technical requirements and budget cycles.
- Insurance Companies:Direct carriers maintain the largest AI deployment budgets, funding proprietary model development and core system modernization. Major groups in Tokyo's insurance district anchor demand through centralized digital transformation offices.
- Brokers:Intermediaries adopt AI-powered comparison and advisory tools to differentiate advisory services. These firms concentrate procurement spend on client-facing analytics rather than back-office automation.
- Agents:Individual agency networks, particularly in underpenetrated prefectures, access AI capabilities through carrier-provided platforms rather than independent investment.
- Financial Institutions:Banks and securities firms with insurance subsidiaries deploy cross-selling algorithms to identify policy opportunities within existing customer bases.
Insurance Companies retain the largest deployment footprint, though Brokers are expanding AI investment most aggressively.
Technology:
The technical stack spans statistical learning, linguistic processing, and visual recognition, with each technology presenting distinct implementation barriers and performance characteristics.
- Machine Learning:Supervised and unsupervised algorithms power the majority of production deployments, from pricing engines to fraud scoring. These systems dominate by deployment volume across all major carrier groups.
- Natural Language Processing:Text and speech understanding engines automate document review and customer interaction workflows. Tokio Marine Holdings anchors competitive positioning through sustained R&D investment in Japanese-language customer service automation.
- Predictive Analytics:Actuarial-grade risk quantification commands premium pricing due to validation requirements and regulatory scrutiny. PMDA oversight intersects where health predictions inform policy pricing.
- Computer Vision:Image recognition systems assess property damage and medical imaging for claims validation, with adoption concentrated in property and casualty lines.
Machine Learning accounts for the broadest deployment base, while Predictive Analytics delivers the highest revenue per implementation.
Application:
Functional use cases determine how AI investments map to measurable business outcomes across the policy lifecycle.
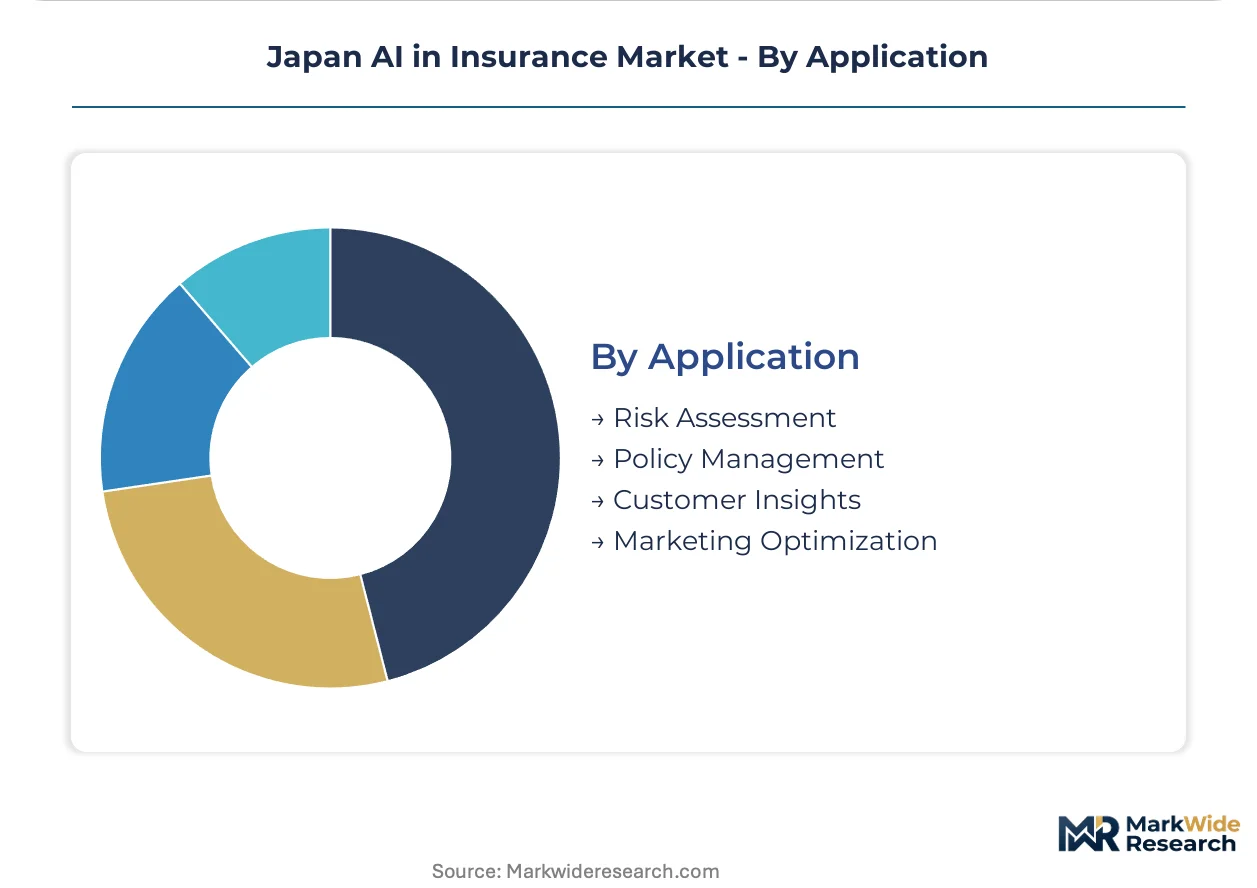
- Risk Assessment:AI models quantify underwriting risk from diverse data streams including driving behavior, health indicators, and environmental factors. METI governance guidelines mandate algorithmic transparency for these high-stakes decisions.
- Policy Management:Automated systems handle endorsements, renewals, and coverage modifications with minimal human intervention. These applications face lighter regulatory scrutiny than pricing or claims functions.
- Customer Insights:Predictive analytics segment policyholders for retention campaigns and cross-selling initiatives. Demand concentrates among digital-native intermediaries in Tokyo and Osaka metropolitan areas.
- Marketing Optimization:AI-driven targeting and channel allocation improve acquisition efficiency for direct and agency distribution.
Risk Assessment captures the deepest carrier investment, while Customer Insights is gaining traction fastest among intermediary channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports AI-enabled insurance solutions through technology licensing arrangements to Southeast Asian carriers seeking digital transformation capabilities. Cross-border data flows from Tokyo-based innovation hubs supply underwriting algorithms and fraud detection models to regional insurers in Singapore and Thailand. METI promotes these technology transfers through bilateral digital economy partnerships.
Kanto/Tokyo
Tokyo's insurance district concentrates carrier headquarters and digital transformation offices driving AI procurement spend. METI's AI governance guidelines mandate algorithmic transparency standards that reshape vendor selection criteria for carriers based here. The Marunouchi and Otemachi corridors host centralized R&D facilities where MS&AD and Tokio Marine develop proprietary machine learning models.
Kansai/Osaka
Osaka-based property and casualty carriers deploy computer vision systems for automated damage assessment in manufacturing and logistics insurance lines. The Act on Protection of Personal Information revisions compel these insurers to rebuild data architectures around privacy-preserving computation. The Umeda commercial district anchors a growing vendor ecosystem serving mid-tier regional carriers.
Chubu/Nagoya
Automotive insurance specialists in Nagoya integrate telematics data from Toyota and Honda supply chain partners into predictive underwriting models. PMDA oversight intersects where health predictions inform policy pricing for manufacturing sector group coverage. The Nagoya Station district hosts carrier digital hubs focused on usage-based insurance products.
Kyushu
Fukuoka's emerging fintech corridor attracts insurtech startups developing natural language processing for customer service automation. The national government's regional revitalization subsidies support AI talent recruitment outside Tokyo-Osaka corridors. Local carriers partner with Kyushu University research centers to access machine learning engineering capabilities.
Hokkaido
Agricultural and weather risk insurers in Sapporo deploy satellite imagery analysis for crop and livestock coverage pricing. Data localization requirements under Japan's strict residency rules force maintenance of domestic cloud infrastructure rather than global hyperscale alternatives. The Sapporo financial district hosts specialized actuarial firms serving northern Japan's distinct risk profiles.
Japan AI in Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure dominated by integrated financial conglomerates with captive insurance operations. The competitive landscape exhibits tiered concentration with three major insurance groups commanding proprietary technology development budgets while mid-tier carriers rely on vendor partnerships. Strategic archetypes include full-stack developers maintaining in-house AI labs, platform integrators licensing third-party engines, and niche specialists targeting fraud detection or claims automation. Dominant competitive moves encompass strategic partnerships with domestic cloud providers to satisfy data residency requirements and portfolio diversification into health-insurance convergence products.
Within the full-stack developer tier, MS&AD Insurance Group Holdings, Tokio Marine Holdings, and SOMPO Holdings occupy positions defined by sustained R&D investment in specialized underwriting models and natural language processing capabilities. These Tokyo-based insurance groups exemplify the archetype of carriers leveraging extensive proprietary claims databases to train production-grade machine learning systems. Their competitive positioning reflects decades of accumulated data assets and centralized digital transformation offices in the capital's insurance district.
| Leading Market Players |
|---|
| MS&AD Insurance Group Holdings |
| Tokio Marine Holdings |
| SOMPO Holdings |
| Nippon Life Insurance Co. |
| Mitsui Sumitomo Insurance |
| Mitsubishi UFJ Financial Group Inc. |
| Mizuho Bank Ltd. |
| Entrust |
| Onfido |
| Others |
Pricing and Supply Chain Analysis
Domestic cloud infrastructure providers in Japan command premium positioning as carriers abandon global hyperscale alternatives to satisfy data residency mandates under the Act on Protection of Personal Information, concentrating margin pools with vendors offering compliant localization rather than algorithmic innovation.
Pricing Analysis
Current-generation machine learning deployment commands substantial premiums over legacy rules-based systems, while next-generation generative AI integrations remain in pilot pricing phases. SaaS-tiered subscription models dominate procurement, with cost differentiation driven by validation grade for actuarial certification and customization depth for carrier-specific workflows. Pricing pressure stems from mid-tier carriers pooling procurement through broker consortiums to extract volume discounts. Regional carriers in underpenetrated prefectures exhibit highest price sensitivity, whereas Tokyo-based major groups prioritize compliance-grade solutions over cost optimization.
Supply Chain Analysis
Tariff exposure between Japan and China for semiconductor components creates supply vulnerability for GPU-dependent training infrastructure. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced processors, while specialized optical character recognition sensors draw from German and Japanese component manufacturers. Single-source vulnerability pervades the domestic cloud layer, where regulatory restrictions prevent diversification to global providers. Distribution runs through carrier procurement committees in Tokyo's insurance district, with implementation managed by systems integrators possessing METI-recognized AI governance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's AI insurance market sits in early-cycle expansion, with regulatory compulsion rather than competitive pressure driving the majority of current investment, creating sustained adoption tailwinds as compliance deadlines harden into enforceable audit requirements.
For Market Incumbents: Entrench proprietary data advantages through federated learning partnerships that expand model training corpora without triggering data sharing restrictions. Accelerate vertical integration into privacy-preserving computation hardware to reduce dependency on domestic cloud providers. The emerging threat of specialized insurtech challengers with pure-play AI architectures demands defensive patent filing in explainable underwriting methodologies.
For New Entrants and Emerging Players: Rural prefecture agency networks in Tohoku and Shikoku represent the most penetrable entry point, where incumbent carriers underinvest in AI-enabled remote claims assessment. Health-insurance convergence products requiring PMDA-aligned diagnostic validation offer regulatory moats against generalist competitors. A go-to-market angle anchored to METI governance guideline pre-certification accelerates carrier procurement committee approval timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist vendors possessing production-grade fraud detection models with existing Tokio Marine or MS&AD reference deployments. Long-term viability across a five-to-ten-year window hinges on regulatory technology capabilities as supervisory frameworks mature beyond voluntary principles. The signal to watch is Financial Services Agency issuance of enforceable capital penalties for non-explainable algorithmic underwriting, which would trigger replacement demand cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Deployment | Positions carriers ahead of Act on Protection of Personal Information enforcement milestones. |
| Federated Learning Consortium Formation | Enables MS&AD and competitors to collaboratively train fraud models without data sharing. |
| Natural Language Processing Talent Acquisition | Addresses acute scarcity of Japanese-language AI engineering capabilities in domestic labor markets. |
| Core System API Modernization | Reduces middleware costs for AI deployment against decades-old policy administration platforms. |
| PMDA Pre-Certification Pathway Investment | Opens health-insurance convergence revenue streams through diagnostic AI integration. |
Research Methodology
Two parallel data streams informed the analysis: structured intelligence from primary interviews with insurance carrier CTOs, AI governance officers, actuarial certification leads, and domestic cloud procurement managers; and secondary validation through Financial Services Agency prudential filings, METI AI governance guideline documentation, carrier annual securities reports, and PMDA diagnostic AI oversight memoranda. Bottom-up triangulation against top-down regulatory impact modeling ensured segmentation integrity.
Forecast inputs incorporated technology deployment velocity across machine learning, natural language processing, predictive analytics, and computer vision, segmented by product type, end user archetype, and application function. Modeled dimensions included carrier size tier, regulatory compliance maturity, and geographic concentration within Kanto, Kansai, Chubu, Kyushu, and Hokkaido clusters. CAGRs derived from adoption curve analysis against compliance deadline schedules, with algorithmic transparency mandates and data localization requirements as primary demand accelerators.
Practitioners should monitor METI guideline evolution toward enforceable audit standards and Financial Services Agency capital penalty implementation for early signals of demand inflection. Forecasts reflect assumptions around sustained regulatory pressure and domestic talent scarcity persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Insurtech Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
Insurance Software Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Global Blockchain in Insurance Market
Insurance Technology
UK Insurtech Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
China AI in Insurance Market