
 Usage-Based Insurance (UBI) Market | 2026-2036
Usage-Based Insurance (UBI) Market Size, Share, and Industry Trends Forecast 2026-2036
Usage-Based Insurance (UBI) Market Intelligence
Market Context
The gap between premium behavioral analytics tiers and commodity mileage-tracking offerings is recalibrating competitive economics across the UBI landscape. Progressive Corporation leverages its longitudinally accumulated driving data to sustain pricing precision in personal auto lines. Allstate Corporation anchors its market position through proprietary telematics infrastructure that controls customer touchpoints end-to-end.
Technical Definition and Segment Structure
Usage-based insurance denotes a pricing model where premiums adjust according to actual driving behavior captured through onboard sensors, GPS trajectory logging, and accelerometer-derived risk scoring rather than static demographic proxies. The architecture serves commercial purpose by aligning risk transfer costs with empirical exposure, reducing adverse selection in auto underwriting. Pay-How-You-Drive programs concentrate margin pools where granular behavioral data enables dynamic tariff refinement, while telematics infrastructure dominates technology investment flows as insurers replace aftermarket OBD-II dongles with embedded OEM connectivity. Manage-How-You-Drive segments attract fleet operators seeking driver coaching overlays that reduce loss frequency.
Regulatory Framework and Outlook
The European Insurance and Occupational Pensions Authority, alongside the EU AI Act and GDPR, imposes algorithmic transparency requirements that shape product design and data retention protocols for cross-border UBI deployment. In the United States, state departments of insurance and the National Association of Insurance Commissioners govern telematics disclosure standards that determine market access conditions. Stakeholders must monitor the divergence between permissive state-level regulatory sandboxes and emerging federal privacy frameworks that could unify compliance burdens.
Market Dynamics
Embedded OEM telematics is displacing aftermarket OBD-II hardware across personal and commercial auto lines, compressing insurer technology stacks and redistributing data ownership toward vehicle manufacturers.
Growth Catalysts
- EU embedded connectivity mandates:Regulatory requirements for standardized vehicle data interfaces are accelerating OEM-insurer partnership formation across Germany, France, and Italy.
- Commercial fleet loss-frequency reduction:Logistics operators in North America are adopting driver coaching overlays to compress incident rates and lower total cost of risk.
- Edge computing architectures:In-vehicle processing capabilities enable real-time risk scoring without persistent cloud transmission, reducing latency and data costs.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for telematics control units remains concentrated in Taiwan and South Korea, exposing hardware procurement to geopolitical friction.
- GDPR algorithmic transparency requirements:Cross-border data retention and explainability standards impose compliance architecture costs that disadvantage smaller regional insurers.
- Static demographic pricing persistence:Traditional underwriting proxies retain regulatory acceptance in multiple US states, slowing behavioral model penetration.
Strategic Opportunities
- Usage-based microinsurance for gig economy drivers:Hourly and per-trip coverage models address protection gaps among delivery and ride-hail contractors in urban India and Brazil.
- Vehicle-to-grid integration:EV battery state monitoring converges with driving behavior data to create unified risk and asset health products.
- California Consumer Privacy Act expansion:Data portability requirements are creating openings for consumer-owned telematics data marketplaces.
Industry Challenges
- Telematics data science talent scarcity:Insurers face acute shortages of actuaries capable of integrating sensor-derived behavioral signals into pricing models.
- Legacy policy administration integration:Core systems built for annual renewal cycles require expensive reconfiguration to support dynamic premium adjustment.
- Cross-carrier data standardization delays:Fragmented event taxonomy across OEM platforms complicates portfolio-level risk comparison.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Usage-Based Insurance (UBI) Market |
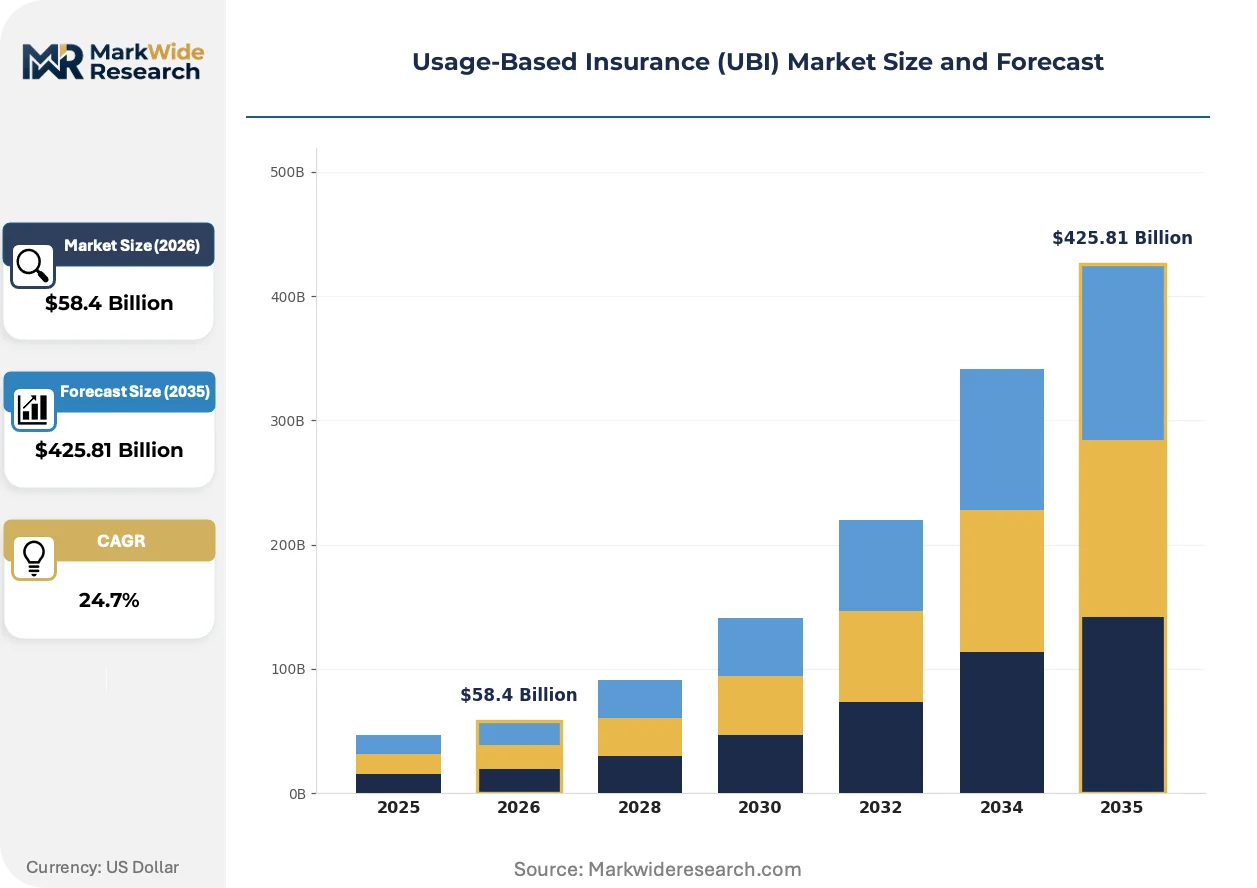
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $425.81 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pay-As-You-Drive, Pay-How-You-Drive, Manage-How-You-Drive, Behavior-Based, Mileage-Based, Time-Based Technology: Telematics, GPS, OBD-II Devices, Blockchain, Machine Learning, Mobile Applications Application: Personal Vehicles, Commercial Fleets, Ridesharing Services, Delivery Trucks, Rental Cars, Corporate Transport End User: Insurers, Fleet Operators, Ride-Hailing Companies, Car Rental Agencies, Corporate Clients, Insurance Brokers |
| Companies Covered | Progressive Corporation, Allstate Corporation, AXA, Liberty Mutual Insurance, State Farm Mutual Automobile Insurance Company, Octo Group S.p.A, Cambridge Mobile Telematics, Allianz SE, UNIPOLSAI Assicurazioni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Usage-Based Insurance (UBI) Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is compressing latency between driving events and risk recalculation, enabling real-time premium adjustment that static annual policies cannot match.
Edge-based computer vision is electrifying cabin and road monitoring by processing driver attention and traffic conditions locally without cloud dependency. Commercial fleet operators in Germany and the Netherlands are deploying these systems fastest. This compression of data transmission is electrifying insurer willingness to underwrite dynamic per-mile contracts that were previously uneconomical.
The EU AI Act's risk classification framework for automated decision-making is forcing UBI providers to document algorithmic logic and maintain human oversight protocols. Product teams are restructuring scoring engines to generate auditable explanation trails. German and French insurers are responding by segregating EU-specific model architectures from global deployments.
Buyer preference is rotating toward subscription-style insurance contracts that bundle maintenance, roadside assistance, and coverage into unified mobility services. Traditional agent distribution channels are losing ground to OEM-owned digital marketplaces. This channel displacement is most pronounced in Scandinavian markets where vehicle-as-a-service adoption runs highest.
Usage-Based Insurance (UBI) Market Segmentation
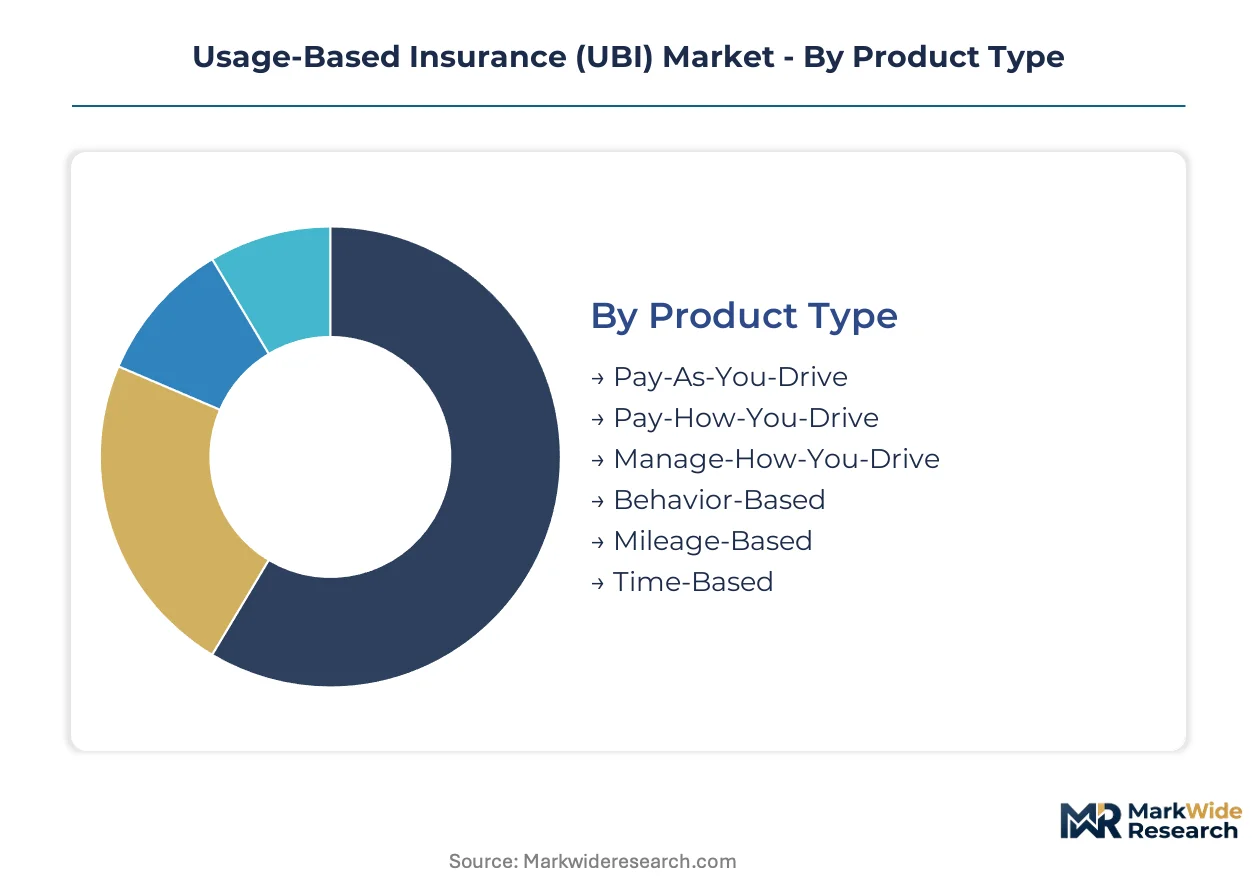
UBI product architectures diverge sharply in their data infrastructure requirements and underwriting sophistication. Telematics deployment costs and algorithmic complexity create tiered investment barriers that reshape competitive entry conditions across segments.
Product Type:
Capital intensity escalates with behavioral granularity, from simple mileage logging to real-time driver coaching systems requiring edge computing infrastructure.
- Pay-As-You-Drive:Premiums scale linearly with distance traveled using GPS or OBD-II mileage capture. German logistics fleets favor this model for predictable cost allocation across interstate routes.
- Pay-How-You-Drive:Accelerometer and gyroscope data feed dynamic risk scoring that rewards smooth braking and cornering. California insurers deploy this most aggressively to displace static demographic pricing.
- Manage-How-You-Drive:Real-time driver feedback loops reduce incident frequency for commercial operators. Dutch fleet managers pair these systems with gamified coaching portals.
- Behavior-Based:Composite scoring integrates phone use, speed variance, and time-of-day exposure. Insurers in Brazil apply this to ride-hail contractor pools.
- Mileage-Based:Simple odometer verification supports low-cost entry products. Indian two-wheeler insurers use this to penetrate price-sensitive urban markets.
- Time-Based:Coverage activates during specific windows for seasonal or occasional drivers. Scandinavian markets apply this to recreational vehicle fleets.
Pay-How-You-Drive absorbs the bulk of installed capacity; Manage-How-You-Drive is expanding most quickly.
Technology:
Hardware-software integration depth separates commodity tracking from differentiated risk intelligence platforms.
- Telematics:Embedded OEM connectivity modules transmit vehicle diagnostics and location data through cellular networks. BMW and Mercedes-Benz integrate these systems at factory level for German insurer partnerships.
- GPS:Satellite positioning enables geofencing and route verification for mileage-based contracts. Brazilian insurers rely on GPS for rural coverage validation where cellular density is sparse.
- OBD-II Devices:Aftermarket dongles plug into diagnostic ports for legacy vehicle compatibility. US personal auto lines still deploy these for older fleet vehicles lacking embedded connectivity.
- Blockchain:Distributed ledgers record immutable driving records for cross-carrier portability. Singapore regulators pilot this for data marketplace governance.
- Machine Learning:Neural networks identify predictive risk patterns from multi-sensor fusion. French insurers deploy these models under EU AI Act documentation requirements.
- Mobile Applications:Smartphone-based trip logging reduces hardware costs for price-sensitive segments. Indian gig economy platforms distribute these to delivery contractors.
Telematics commands the largest share of technology investment; Machine Learning is climbing the fastest as explainability frameworks mature.
Application:
Loss severity and data monetization potential vary dramatically across vehicle use cases and operator types.
- Personal Vehicles:Individual policyholders opt into behavior-based discounts through insurer mobile apps. Progressive and Allstate dominate this channel in the United States.
- Commercial Fleets:Multi-vehicle operators achieve loss ratio compression through centralized driver monitoring. German logistics firms DHL and DB Schenker mandate telematics across tractor-trailer units.
- Ridesharing Services:Platform-mediated coverage fills gaps between personal and commercial auto policies. Uber and Lyft drivers in California access per-trip microinsurance through embedded partnerships.
- Delivery Trucks:Last-mile operators face stop-and-go exposure patterns distinct from highway driving. Amazon DSP contractors in the Netherlands adopt usage-based coverage for urban van fleets.
- Rental Cars:Short-term lessors apply mileage-based surcharges to align customer costs with asset utilization. Enterprise and Sixt deploy this across European airport locations.
- Corporate Transport:Employee shuttle and executive car services integrate duty-of-care monitoring. Swiss pharmaceutical firms deploy these systems for sales force vehicle pools.
Commercial Fleets generate the highest premium density per vehicle; Ridesharing Services are gaining share fastest as platform economics mature.
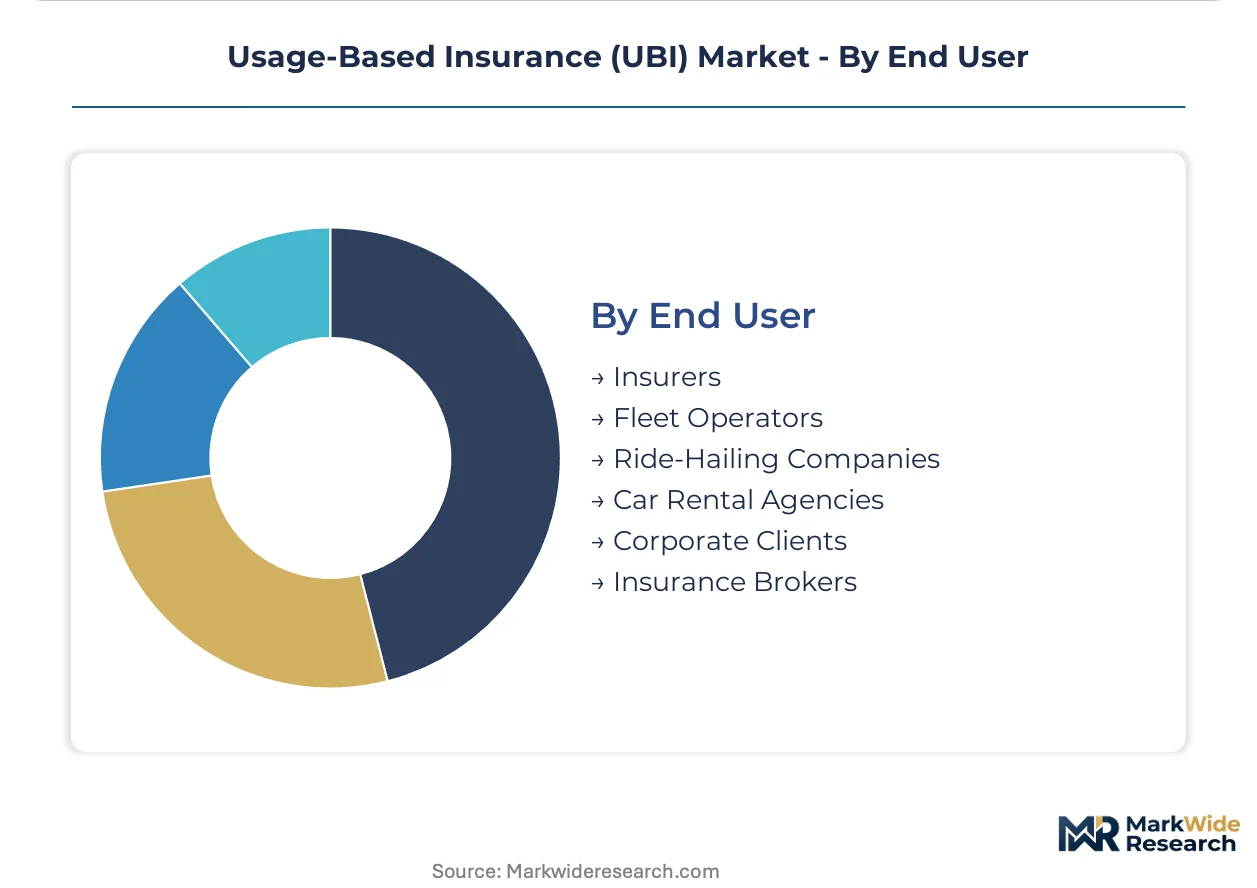
End User:
Data ownership preferences and integration capabilities segment buyer sophistication across the value chain.
- Insurers:Full-stack carriers invest in proprietary telematics infrastructure to control pricing precision. Allstate maintains end-to-end data pipelines for personal auto lines.
- Fleet Operators:Logistics firms prioritize loss frequency reduction over premium optimization. J.B. Hunt and Schneider National deploy driver coaching overlays in North America.
- Ride-Hailing Companies:Platform operators seek seamless coverage activation for contractor populations. Grab integrates UBI APIs for Southeast Asian driver pools.
- Car Rental Agencies:Asset-light lessors apply usage data to residual value forecasting. Hertz pilots this for electric fleet depreciation modeling.
- Corporate Clients:Risk managers bundle telematics with duty-of-care compliance. Siemens mandates connected vehicle policies for German employee transport.
- Insurance Brokers:Intermediaries aggregate multi-carrier telematics offerings for SME fleets. Marsh and Aon build proprietary comparison platforms.
Insurers deploy the most capital-intensive technology stacks; Fleet Operators are expanding data integration fastest as ROI measurement improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European UBI ecosystem density through BMW and Mercedes-Benz factory-embedded telematics partnerships with German insurers. The metropolitan corridor concentrates OEM-insurer data integration platforms that rival Silicon Valley's aftermarket innovation clusters.
United States
Progressive and Allstate leverage proprietary telematics infrastructure to dominate personal auto lines. State insurance departments and the National Association of Insurance Commissioners govern telematics disclosure standards. San Francisco and Austin host the densest concentrations of smartphone-based UBI startups targeting gig economy drivers.
Germany
DHL and DB Schenker mandate connected vehicle policies across commercial tractor-trailer fleets. The EU AI Act and GDPR impose algorithmic transparency requirements that reshape product architectures. Stuttgart and Munich form the core corridor where BMW, Mercedes-Benz, and Volkswagen integrate factory-level telematics for insurer partnerships.
United Kingdom
Commercial fleet operators adopt driver coaching overlays to compress loss frequency in logistics corridors. The Financial Conduct Authority and Information Commissioner's Office govern data retention and automated decision-making protocols. London's insurance technology cluster hosts telematics data science talent pipelines serving Lloyd's syndicates.
Netherlands
Amazon DSP contractors and last-mile operators deploy usage-based coverage for urban van fleets. Dutch regulators align with EU embedded connectivity mandates accelerating OEM-insurer partnerships. Rotterdam and Amsterdam concentrate telematics platform providers serving European commercial fleet markets.
India
Delivery platforms distribute smartphone-based trip logging to price-sensitive gig economy contractors. The Insurance Regulatory and Development Authority governs telematics product approvals and data localization requirements. Bangalore and Mumbai host insurtech clusters developing hourly microinsurance for two-wheeler delivery fleets.
Usage-Based Insurance (UBI) Market Key Industry Players
Premium-margin players sit above commodity-margin players across data infrastructure depth and algorithmic sophistication. The market structures around three tiers: full-stack carriers with proprietary telematics pipelines, OEM-integrated platform providers controlling vehicle data gateways, and hardware-agnostic software vendors serving price-sensitive segments. Strategic moves concentrate on OEM partnership formation for embedded connectivity access and edge computing capability acquisition for real-time risk scoring latency reduction.
Among North American full-stack carriers, Progressive Corporation and Allstate Corporation represent the proprietary data infrastructure archetype with end-to-end customer touchpoint control. Octo Group S.p.A occupies a position within the telematics platform provider tier serving multiple carrier clients across European markets. These three entities exemplify divergent strategic postures: captive data ownership versus multi-tenant platform scale versus specialized technology licensing.
| Leading Market Players |
|---|
| Progressive Corporation |
| Allstate Corporation |
| AXA |
| Liberty Mutual Insurance |
| State Farm Mutual Automobile Insurance Company |
| Octo Group S.p.A |
| Cambridge Mobile Telematics |
| Allianz SE |
| UNIPOLSAI Assicurazioni |
| Others |
Cost & Logistics Intelligence
Semiconductor fabrication costs for telematics control units cascade through three pricing tiers as raw silicon wafers from Taiwan and South Korea feed embedded OEM modules, aftermarket OBD-II dongles, and smartphone-based logging apps. German insurers absorb premium pricing for factory-integrated BMW and Mercedes-Benz connectivity while Indian gig platforms distribute low-cost mobile solutions to price-sensitive delivery contractors.
Pricing Analysis
Value-based pricing anchors UBI contracts to empirical risk reduction rather than static demographic proxies. Three-tier pricing structure across premium, standard, and economy levels separates embedded OEM partnerships from aftermarket hardware deployments from smartphone-only trip logging. Price differentiation rests on data granularity depth and algorithmic sophistication, with behavioral scoring commanding premium positioning over simple mileage verification. Pricing pressure stems from GDPR compliance architecture costs that disadvantage smaller regional carriers against full-stack incumbents. Fleet operators exhibit lowest price sensitivity due to loss-frequency reduction ROI, while individual gig economy drivers in emerging markets resist hardware procurement fees.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for telematics hardware deployment across European and Asian fleet markets. Manufacturing concentrates in Taiwan, South Korea, and Germany for semiconductor control units, GPS modules, and automotive-grade sensors. Component dependencies include cellular modems, accelerometer chips, and lithium-ion power cells. Single-source vulnerability in Taiwan semiconductor fabrication exposes procurement to geopolitical friction. Distribution runs through OEM-integrated channels for factory-installed systems and insurance broker networks for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic documentation requirements erect compliance moats that favor carriers with existing data science infrastructure over capital-constrained entrants. This regulatory barrier rewards early investment in explainable scoring engines and human oversight protocols.
For Market Incumbents: Anchor market position through exclusive OEM partnership lockups with BMW, Mercedes-Benz, and Volkswagen for embedded connectivity access. Acquire edge computing capability to compress real-time risk scoring latency below competitor thresholds. Defend against smartphone-based entrants by bundling maintenance and roadside assistance into subscription-style mobility contracts that increase switching costs.
For New Entrants and Emerging Players: Launch via API-first distribution targeting gig economy platforms in urban India and Brazil where hardware-free mobile logging penetrates price-sensitive contractor pools. Exploit white-space in hourly microinsurance for two-wheeler delivery fleets where traditional annual policies create protection gaps. Target California's data portability requirements under CCPA expansion to build consumer-owned telematics data marketplaces.
For Investors and Strategic Acquirers: OEM-insurer partnership announcements in Stuttgart and Munich are the leading indicator that embedded connectivity access is consolidating toward platform-scale players. Long-term viability favors technology licensing specialists with EU AI Act-compliant scoring architectures over hardware-dependent device manufacturers. Acquisition targets should demonstrate explainable model documentation and cross-border data governance capabilities. Watch for regulatory sandbox approvals in permissive US states as signal of behavioral pricing model expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Partnership Formation | BMW and Mercedes-Benz factory integration secures embedded data gateway control. |
| Edge Computing Acquisition | In-vehicle processing reduces latency for real-time premium adjustment. |
| API Platform Launch | Grab and Uber integration enables seamless contractor coverage activation. |
| GDPR Compliance Investment | Algorithmic transparency documentation satisfies EU AI Act requirements. |
| Microinsurance Product Development | Hourly two-wheeler coverage penetrates Indian delivery fleet markets. |
Research Approach
Document review covered SEC insurer filings, EU regulatory submissions to EIOPA, and vehicle production databases, complemented by interviews with telematics platform engineers, fleet operations directors at DHL and DB Schenker, insurance product development leads, and data science directors at full-stack carriers. Secondary validation drew from GDPR implementation guidance, EU AI Act risk classification frameworks, and state insurance department telematics disclosure standards. Bottom-up triangulation across installed base estimates and top-down reconciliation against premium volume aggregates anchored market sizing.
Cross-referencing historical adoption curves against panel input from OEM platform engineers and insurer actuaries shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type granularity, technology deployment mode, vehicle application class, and end-user integration sophistication. CAGRs were derived from regression against telematics penetration rates and behavioral data monetization progression. Forecast inputs incorporated embedded connectivity mandate timelines and commercial fleet loss-frequency reduction benchmarks.
Regulatory enforcement delays, semiconductor supply disruptions, and static pricing regime persistence in key US states are the dominant revision risks that could alter trajectory. Forecasts reflect documented assumptions about OEM partnership formation velocity and cross-carrier data standardization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Online Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Global Flood Insurance Market
Insurance
India Health Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Bancassurance Market
Insurance
China Group Health Insurance Market
Insurance
Digital Insurance Market
Insurance
India Travel Insurance Market
Insurance
India Online Insurance Market
Insurance
Global SME Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
GCC Health Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
India Liability Insurance Market