
 Ovum Egg Banking Market | 2026-2036
Ovum Egg Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Ovum Egg Banking Market Insights
The gap between boutique concierge banking and high-volume clinic networks is repositioning how patients access and pay for egg preservation. Cryos International leverages its pan-European cryologistics infrastructure to sustain donor access across multiple jurisdictions. Kindbody anchors its model with employer-sponsored fertility benefits, while RMA Network competes through standardized laboratory protocols that reduce cycle-to-cycle variability.
Ovum egg banking encompasses the cryogenic preservation of oocytes through slow-freeze or vitrification methods, typically maintaining tissues at minus 196 degrees Celsius in liquid nitrogen to suspend metabolic activity for future fertilization. The practice serves fertility preservation for oncology patients, elective social postponement of parenthood, and donor egg programs for third-party reproduction. Frozen eggs command structural preference in North American and European clinic networks due to scheduling flexibility and reduced synchronization burdens, while vitrified eggs capture margin pools through superior post-thaw survival rates. Research applications remain comparatively nascent, constrained by institutional review board complexity and fragmented funding.
The FDA mandates infectious disease screening and donor eligibility determination under 21 CFR Part 1271, while EMA oversight through the EU Tissues and Cells Directive harmonizes traceability and quality standards across member states. Compliance with these frameworks shapes market access, as non-conforming banks face exclusion from insurance reimbursement networks and cross-border referral pathways. Stakeholders must monitor evolving donor anonymity regulations and storage duration limits, as policy shifts in major jurisdictions could redirect patient flows and capital allocation toward more permissive regulatory environments.
Market Dynamics
Vitrification protocols are compressing cycle variability and enabling high-volume clinic networks to standardize outcomes across dispersed laboratory footprints. This technical consolidation is redrawing competitive boundaries between boutique fertility practices and scaled banking operations.
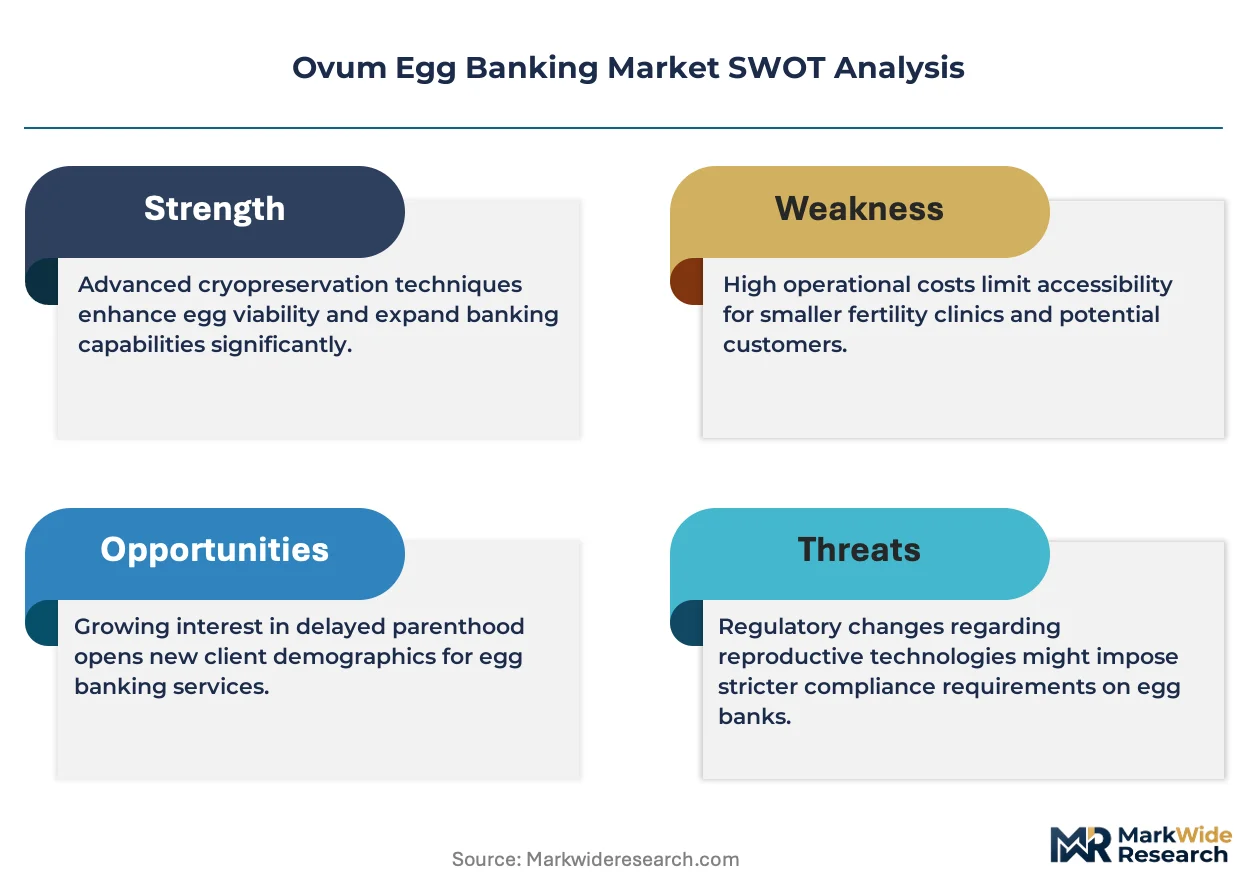
Growth Catalysts
- Employer-sponsored fertility benefits:Large technology and professional services firms now cover elective egg preservation in benefits packages, normalizing access for career-focused professionals in their early thirties.
- 21 CFR Part 1271 harmonization:FDA donor screening standardization has reduced cross-clinic compliance friction, enabling referral networks to route patients toward specialized banking facilities without redundant testing.
- Oncofertility protocols:Accelerated fertility preservation timelines for chemotherapy patients are expanding same-day stimulation-and-retrieval services at academic medical centers.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic infrastructure depends on regional industrial gas suppliers, with shortages in the United Kingdom and Germany disrupting storage continuity at satellite clinic locations.
- Donor anonymity sunset clauses:EMA-aligned jurisdictions are mandating identity-release provisions for donor-conceived children, reducing donor recruitment pools in Spain and Denmark.
- Extended storage cost compounding:Annual maintenance fees accumulate unpredictably over decades, creating affordability cliffs for patients who banked eggs in their twenties.
Strategic Opportunities
- Telemedicine-enabled cross-border banking:Remote monitoring of ovarian stimulation allows patients in restrictive jurisdictions to complete retrieval cycles in Spain or Cyprus without prolonged absence from employment.
- AI-assisted oocyte grading:Machine vision systems are converging with time-lapse imaging to predict blastocyst formation potential, reducing embryologist labor intensity in high-throughput laboratories.
- Indian domestic market formation:FSSAI draft guidelines for assisted reproductive technology are creating a regulatory pathway for domestic egg banking outside the current medical tourism corridor.
Industry Challenges
- Embryologist certification bottlenecks:Vitrification competency requires supervised case volumes that exceed training pipeline capacity at accredited reproductive medicine fellowships.
- Legacy inventory migration:Slow-freeze oocytes from the 2000s require specialized thaw protocols that few contemporary laboratories maintain, stranding patient assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovum Egg Banking Market |
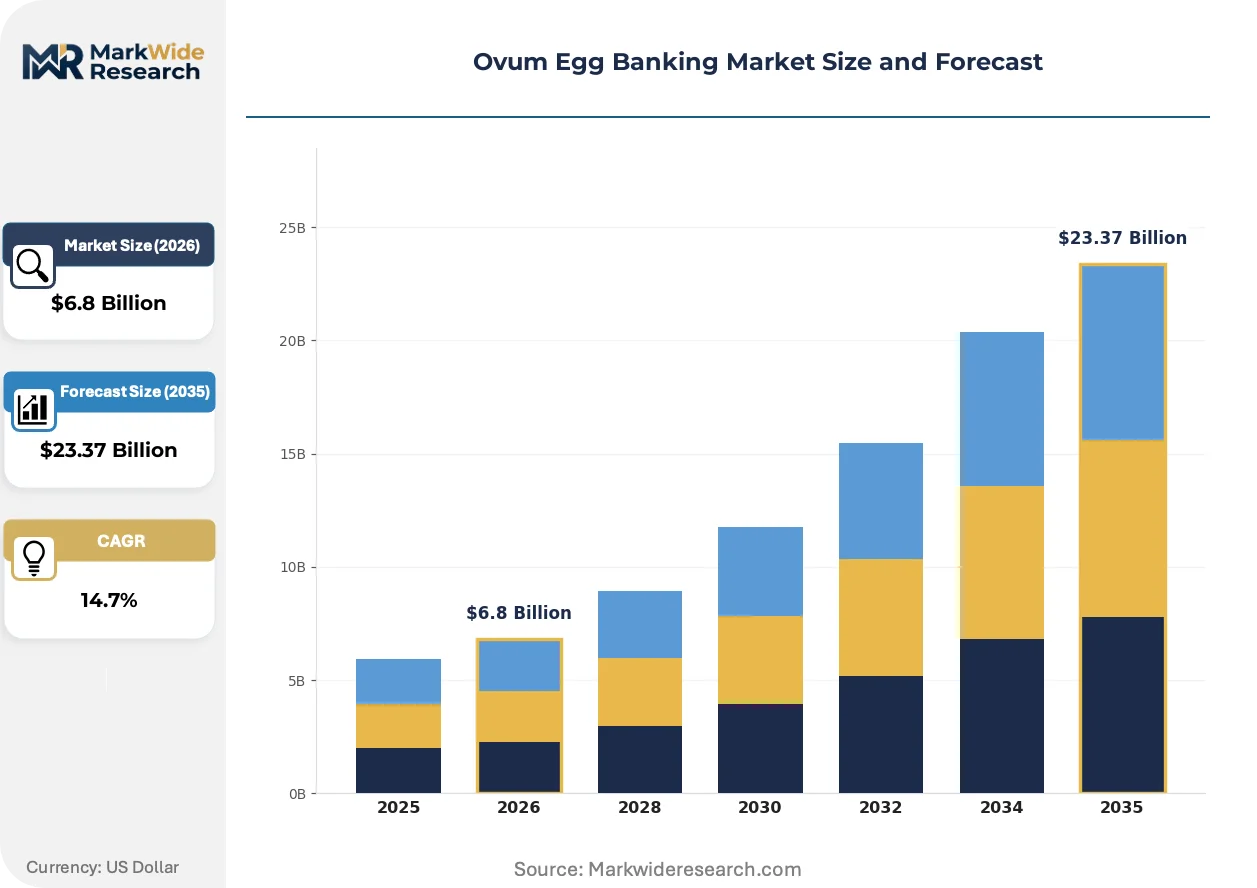
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.37 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Eggs, Frozen Eggs, Vitrified Eggs, Donor Eggs Application: Fertility Treatments, Research, IVF Procedures, Egg Donation End User: Fertility Clinics, Hospitals, Research Centers, Egg Banks Technology: Cryopreservation, Hormonal Stimulation, Embryo Culture, Genetic Screening |
| Companies Covered | CCRM Fertility, Cryos International, ReproTech LLC, Shady Grove Fertility, RMA Network, Carrot Fertility, CooperSurgical, Vitrolife AB, Kindbody, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovum Egg Banking Market Trends and Innovations
Automation is penetrating laboratory workflows that remained artisanal for decades, compressing skilled labor dependence while raising capital intensity thresholds for market entry.
Vitrification is integrating closed-system carrier devices that eliminate direct liquid nitrogen contact during cooling and warming phases. High-volume clinic networks in the United States and Spain are adopting these systems to reduce contamination risk and enable standardized shipping protocols. This integration is compressing the viability gap between fresh and frozen oocytes, eroding the historical premium commanded by fresh donor cycles.
EMA's EU Tissues and Cells Directive revision is mandating electronic traceability systems for donor gametes across member states. Fertility banks must implement interoperable chain-of-custody databases by enforcement deadlines. Spanish and Danish facilities with existing digital infrastructure are absorbing compliance costs more readily than smaller operators in Eastern European accession states.
Patients are compressing decision timelines between initial consultation and cycle initiation, driven by employer benefit enrollment windows and oncology treatment urgency. This acceleration is displacing the traditional multi-visit counseling model with streamlined telehealth onboarding. The United States exhibits the most pronounced compression, where same-week stimulation starts are becoming standard at employer-contracted fertility networks.
Ovum Egg Banking Market Segmentation
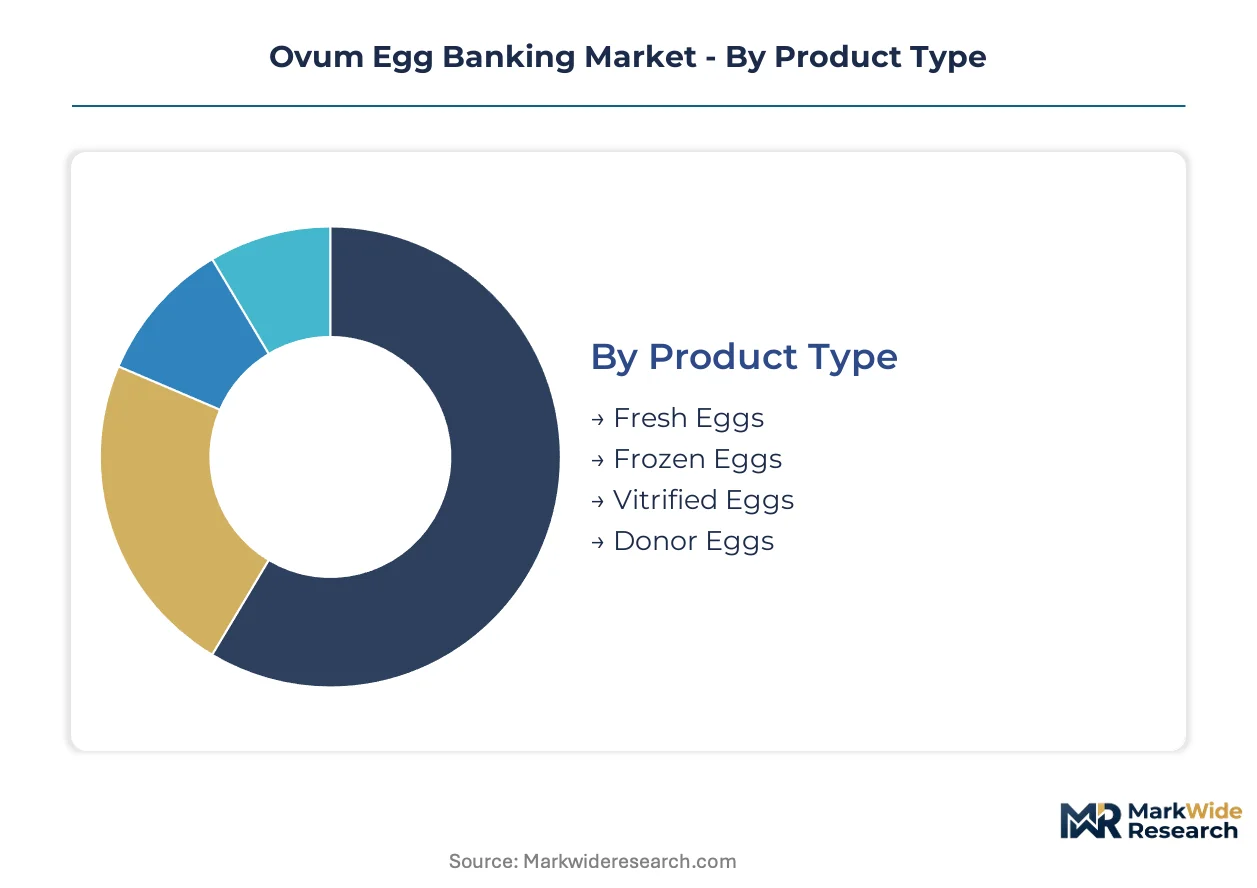
Segmentation in ovum egg banking reveals how technical specifications, clinical workflows, and regulatory pathways fragment purchasing decisions across patient populations. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Supply concentration in cryogenic infrastructure and laboratory certification creates tiered access patterns across preservation formats.
- Fresh Eggs:Unfrozen oocytes retrieved for immediate fertilization within hours of collection. Demand clusters at high-volume IVF centers in Spain and Denmark where donor recruitment networks sustain just-in-time availability for synchronous transfer cycles.
- Vitrified Eggs:Flash-frozen oocytes using ultra-rapid cooling that eliminates ice crystal formation. Post-thaw survival rates exceed 90% at accredited laboratories, capturing preference among United States fertility networks where scheduling flexibility commands premium positioning.
- Frozen Eggs:Slow-freeze preserved oocytes from earlier protocol generations. Legacy inventory requires specialized thaw expertise that few contemporary laboratories maintain, stranding patient assets at satellite clinic locations.
- Donor Eggs:Third-party oocytes screened under FDA 21 CFR Part 1271 or EMA Tissues and Cells Directive standards. Cross-border flows concentrate in Cyprus and Spain where anonymity provisions and compensation frameworks attract international patients.
Vitrified eggs absorb the bulk of installed capacity; donor eggs are expanding most quickly.
Application:
Cost tier differentiation separates reimbursable clinical procedures from self-pay research access, with IVF workflows commanding capital investment priority.
- Fertility Treatments:Elective preservation for career-focused professionals and medical preservation for oncology patients. Employer-sponsored benefits in United States technology and professional services sectors normalize access for women in their early thirties.
- IVF Procedures:Controlled ovarian stimulation, retrieval, and laboratory fertilization workflows. Standardized protocols at RMA Network and Kindbody facilities reduce cycle-to-cycle variability across dispersed geographic footprints.
- Egg Donation:Third-party reproduction matching donors with intended parents. EMA-aligned jurisdictions mandate identity-release provisions that reduce donor recruitment pools in historically permissive markets.
- Research:Oocyte biology, cryobiology, and early embryonic development studies. Institutional review board complexity and fragmented funding constrain volume relative to clinical applications.
IVF procedures absorb the bulk of installed capacity; fertility treatments are climbing the fastest.
End User:
Customer type fragmentation splits procurement between integrated health systems and specialized standalone facilities with distinct capital intensity thresholds.
- Fertility Clinics:Dedicated reproductive medicine practices with in-house laboratories. Cryos International leverages pan-European cryologistics to sustain donor access across multiple jurisdictions.
- Hospitals:Academic medical centers with oncofertility protocols. Same-day stimulation-and-retrieval services compress decision timelines for chemotherapy patients at United States tertiary care institutions.
- Egg Banks:Specialized cryostorage facilities with chain-of-custody infrastructure. EMA electronic traceability mandates favor Spanish and Danish operators with existing digital systems.
- Research Centers:University and institutional laboratories conducting oocyte biology studies. Funding discontinuity limits sustained procurement relative to clinical end users.
Fertility clinics absorb the bulk of installed capacity; egg banks are gaining share fastest.
Technology:
Margin concentration in vitrification protocols and genetic screening separates high-throughput laboratories from artisanal practices dependent on skilled embryologist labor.
- Cryopreservation:Vitrification and slow-freeze methods maintaining oocytes at minus 196 degrees Celsius. Closed-system carrier devices eliminate direct liquid nitrogen contact, enabling standardized shipping protocols.
- Genetic Screening:Preimplantation genetic testing for aneuploidy and monogenic disorders. Machine vision systems converge with time-lapse imaging to predict blastocyst formation potential.
- Hormonal Stimulation:Ovarian stimulation protocols using gonadotropins and antagonists. Telemedicine-enabled remote monitoring allows patients in restrictive jurisdictions to complete cycles without prolonged absence.
- Embryo Culture:In vitro fertilization and blastocyst development in controlled laboratory environments. Vitrification competency requires supervised case volumes that exceed training pipeline capacity.
Cryopreservation absorbs the bulk of installed capacity; genetic screening is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barcelona anchors cross-border patient flows through its concentration of fertility clinics serving Northern European demand. The city's banking infrastructure processes retrieval cycles for patients from France, the United Kingdom, and Germany seeking donor anonymity provisions unavailable domestically.
United States
Employer-sponsored fertility benefits at technology and professional services firms normalize elective preservation for women in their early thirties. FDA 21 CFR Part 1271 harmonization reduces cross-clinic compliance friction, enabling referral networks to route patients toward specialized banking facilities. Boston's academic medical centers compress decision timelines through same-day stimulation-and-retrieval oncofertility protocols.
Spain
Barcelona and Madrid sustain donor recruitment networks that attract international patients from anonymity-restrictive jurisdictions. EMA's EU Tissues and Cells Directive mandates electronic traceability systems that Spanish facilities with existing digital infrastructure absorb more readily than smaller operators. The Mediterranean corridor maintains compensation frameworks that preserve donor pool depth despite identity-release sunset clauses.
Denmark
Copenhagen's cryologistics infrastructure enables pan-European distribution of donor gametes through closed-system carrier devices. The country's national pharmaceutical regulator enforces storage duration limits that redirect some patient flows toward more permissive jurisdictions. Aarhus university hospitals integrate fertility preservation into standard oncology care pathways.
United Kingdom
Liquid nitrogen supply concentration disrupts storage continuity at satellite clinic locations outside London. The Human Fertilisation and Embryology Authority mandates identity-release provisions that reduce donor recruitment pools relative to historical levels. Harley Street specialist practices maintain premium positioning through concierge banking services for career-focused professionals.
India
FSSAI draft guidelines for assisted reproductive technology create regulatory pathways for domestic egg banking outside the current medical tourism corridor. Mumbai and Delhi fertility networks expand capacity to serve returning diaspora patients seeking cost advantages. Telangana's medical device manufacturing clusters supply cryogenic equipment to domestic banking facilities.
Ovum Egg Banking Market Competitive Landscape
Capital-heavy cryogenic infrastructure operators compete with asset-light clinic networks that outsource storage to specialized third-party facilities. The market structure concentrates around vertically integrated fertility networks, standalone egg banking specialists, and equipment manufacturers supplying laboratory infrastructure. Three archetypes dominate: pan-European cryologistics platforms, employer-contracted fertility benefits managers, and academic medical center-based oncofertility programs. Competitive moves center on M&A consolidation of regional clinic networks and technology licensing agreements for closed-system vitrification devices.
Within the integrated network tier, Cryos International leverages its Danish origin to anchor pan-European donor access across multiple jurisdictions, while RMA Network exemplifies the standardized laboratory protocol approach that reduces cycle-to-cycle variability. Kindbody occupies a position within the employer-sponsored benefits vector, representing the asset-light model that contracts with rather than owns cryogenic infrastructure. These three entities collectively illustrate how geographic scope, capital intensity, and customer acquisition strategy separate viable competitors from marginal operators.
| Leading Market Players |
|---|
| CCRM Fertility |
| Cryos International |
| ReproTech LLC |
| Shady Grove Fertility |
| RMA Network |
| Carrot Fertility |
| CooperSurgical |
| Vitrolife AB |
| Kindbody |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration into pan-European cryologistics networks anchors both supply security and pricing power for dominant operators. Cryos International's cross-border infrastructure enables standardized donor access while compressing logistics costs that would otherwise fragment smaller competitors.
Pricing Analysis
Yield-linked pricing anchors fee structures to post-thaw survival rates rather than retrieval volume alone. Three-tier pricing structure across premium concierge, standard clinical, and economy bulk-banking levels separates patients by service intensity and laboratory accreditation tier. Pricing pressure stems from employer-sponsored benefit normalization driving volume discounts at contracted fertility networks. Price-sensitive segments cluster among self-pay elective preservation patients in their late twenties, while oncology patients and cross-border donor-egg recipients exhibit lower elasticity.
Supply Chain Analysis
EMA domestic-content traceability mandates are reshaping sourcing toward EU-certified liquid nitrogen suppliers and closed-system carrier device manufacturers. Supply concentration centers on Denmark for cryologistics infrastructure, Spain for donor recruitment networks, and the United States for hormonal stimulation pharmaceuticals. Raw material dependencies include liquid nitrogen industrial gas supply, vitrification media formulations, and gonadotropin API production. Single-source vulnerability runs through regional liquid nitrogen supplier consolidation, particularly acute in the United Kingdom and Germany. Distribution runs through specialized cold-chain logistics partnerships rather than general medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a vitrification-transition phase where flash-freeze protocols displace legacy slow-freeze inventory and associated thaw expertise. Closed-system automation is compressing the viability gap between fresh and frozen oocytes.
For Market Incumbents: Lock in embryologist certification pipelines through accredited fellowship partnerships before competency bottlenecks constrain expansion. Consolidate regional clinic networks to capture employer-sponsored benefit contracts that demand standardized outcomes across dispersed footprints. Vertical integration into captive cryostorage infrastructure defends against liquid nitrogen supply disruption.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in cross-border donor egg services enables mid-market positioning for telemedicine-enabled banking in Cyprus and Spain. Target returning diaspora patients in India before FSSAI guidelines fully domesticize supply chains. White-space concentration appears in AI-assisted oocyte grading tools for high-throughput laboratories lacking in-house machine vision development.
For Investors and Strategic Acquirers: Exit pathways concentrate in employer-contracted fertility benefits managers with demonstrated enrollment growth and technology licensing agreements for closed-system vitrification devices. Long-term viability favors operators with demonstrated compliance cost absorption under tightening EMA traceability mandates. Watch for inflection in donor anonymity regulation sunset clauses that could redirect patient flows and valuation multiples toward more permissive jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Vitrification Licensing | FDA 21 CFR Part 1271 compliance enables cross-clinic referral network expansion without redundant donor screening. |
| Employer Benefits Contracting | Kindbody's asset-light model demonstrates scalable patient acquisition through technology and professional services firm partnerships. |
| Pan-European Cryologistics Buildout | Cryos International's Danish-origin infrastructure sustains donor access across EMA-aligned jurisdictions with divergent anonymity rules. |
| AI-Assisted Oocyte Grading Development | Machine vision convergence with time-lapse imaging reduces embryologist labor intensity at high-throughput RMA Network facilities. |
| Oncofertility Protocol Standardization | Same-day stimulation-and-retrieval services at Boston academic medical centers compress decision timelines for chemotherapy patients. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with reproductive endocrinologists, embryology laboratory directors, fertility clinic operations managers, and employer benefits administrators combined with secondary validation from FDA 21 CFR Part 1271 guidance documents, EMA EU Tissues and Cells Directive submissions, and hospital procurement databases. Bottom-up patient volume modeling and top-down market sizing triangulated across cryostorage capacity estimates and cycle reporting.
Granularity-level modeling operated at the country-regulatory-cluster intersection, with separate projections for United States employer-sponsored benefit penetration, Spain cross-border donor anonymity flows, and India domestic market formation. Segmentation dimensions included preservation format, application workflow, end-user facility type, and technology protocol. CAGRs derived from installed base growth, cycle volume trajectories, and pricing normalization trends across the projection horizon. Industry-specific forecast inputs incorporated liquid nitrogen supply continuity indices and embryologist training pipeline capacity.
Inputs from fertility clinic networks and cryostorage facility operators were available through the study window; gaps in long-term storage cost accumulation data and donor recruitment pool depth introduce uncertainty bands around out-year projections. Forecasts reflect assumptions regarding EMA traceability mandate enforcement timelines and FSSAI guideline finalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Contraceptives Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Fertility Treatments Market