
 Anesthesia Vaporizers Market | 2026-2036
Anesthesia Vaporizers Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Vaporizers Market Analysis
EU MDR compliance is hardening requirements for clinical evidence and post-market surveillance of anesthesia vaporizers sold in European markets. GE Healthcare leverages its installed base of anesthesia workstations to sustain recurring revenue from vaporizer accessories and service contracts. Dragerwerk anchors its competitive position through integrated breathing system design that pairs vaporizer modules with ventilator platforms. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes on cost-engineered vaporizer assemblies targeting price-sensitive hospital procurement in Asia-Pacific and Latin American markets.
An anesthesia vaporizer is a precision flow-control device that thermodynamically converts liquid inhalation anesthetic agents into calibrated vapor concentrations, typically maintaining output accuracy within plus or minus 20% of dial setting across a 20-35 degrees Celsius operating range, for delivery via the fresh gas stream of an anesthesia breathing circuit. Variable bypass technology dominates the product type landscape due to its mechanical reliability and independence from electrical power, while computerized systems represent the fastest-growing segment as hospitals adopt automated end-tidal anesthetic concentration targeting. Ambulatory surgical centers constitute the most rapidly expanding end user category, though hospitals retain the largest share of absolute vaporizer procurement volume given their broader surgical service mix.
FDA 510(k) clearance pathways and ISO 80601-2-13 standards govern electromagnetic compatibility and essential performance of anesthesia vaporizers in the United States, while CE marking under EU MDR regulates market access for European distribution. China's NMPA implements GB standards for medical electrical equipment that constrain design parameters for vaporizers manufactured by domestic producers such as Beijing Aeonmed and Beijing Anton Medical Co., Ltd. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reframe regulatory obligations for vaporizers incorporating closed-loop anesthetic delivery algorithms.
Market Dynamics
The anesthesia vaporizers market is experiencing structural pressure from the EU Medical Device Regulation's tightened conformity requirements, which are forcing manufacturers to rebuild clinical evidence portfolios and post-market surveillance systems for European market access.
Growth Catalysts
- EU MDR compliance mandates:The EU Medical Device Regulation is compelling healthcare systems across Germany, France, and Italy to replace legacy vaporizer units with certified systems, creating replacement demand.
- Ambulatory surgical center expansion:Freestanding outpatient facilities in the United States are installing precision vaporization equipment to support rising volumes of same-day procedures.
- Variable bypass reliability:Mechanical vaporizer technology continues to dominate procurement decisions due to its electrical independence and operational stability in resource-constrained settings.
Market Restraints
- Specialized manufacturing concentration:Precision vaporizer production clusters among a limited set of European and North American component suppliers, creating supply vulnerability.
- Input cost volatility:Nickel-brass alloys and specialized polymers used in vaporizer wick assemblies face price instability from mining supply constraints.
- Regulatory friction:China's NMPA GB standards impose design constraints that limit interoperability of imported vaporizer modules with domestic anesthesia workstations.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil's ANVISA regulatory pathway improvements are enabling faster market entry for cost-engineered vaporizer assemblies targeting mid-tier hospital procurement.
- Closed-loop algorithm convergence:Integration of end-tidal gas monitoring with automated vaporizer control is opening software-as-a-medical-device revenue streams.
- Service contract unbundling:Independent service organizations are capturing vaporizer calibration and preventive maintenance work previously captive to original equipment manufacturers.
Industry Challenges
- Biomedical engineering talent scarcity:Hospitals face recruitment gaps for technicians trained in thermodynamic flow-control calibration and vaporizer preventive maintenance protocols.
- Legacy system integration complexity:Computerized vaporizer modules require substantial interface engineering to function with decades-old anesthesia breathing circuits still deployed in many facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Vaporizers Market |
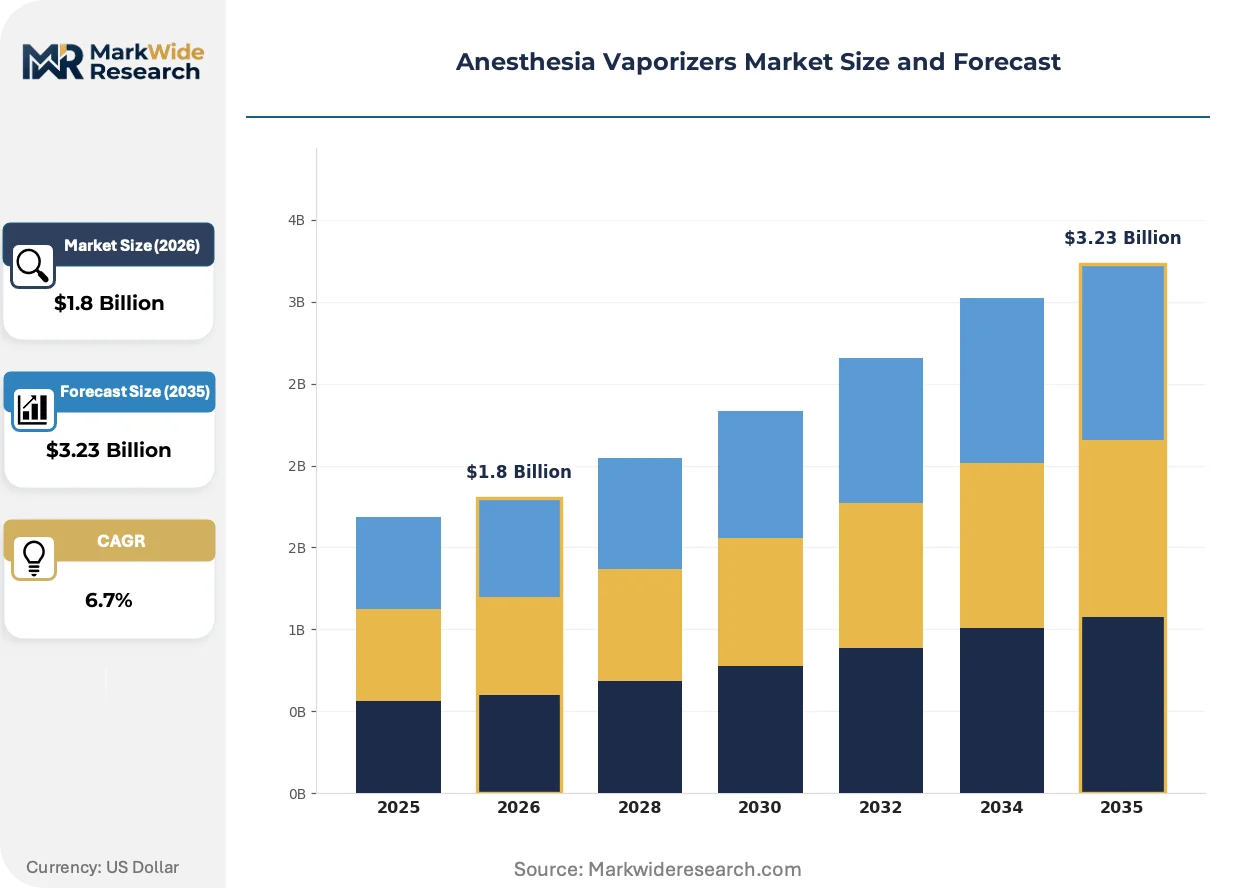
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volatile Agents, Inhalation Anesthetics, Anesthesia Machines, Accessories End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Continuous Flow, Variable Bypass, Anesthetic Vaporization, Computerized Systems Application: General Anesthesia, Sedation, Pain Management, Emergency Procedures |
| Companies Covered | Penlon, Spacelabs Healthcare, Dragerwerk, Beijing Aeonmed, Beijing Anton Medical Co., Ltd., GE Healthcare, Heinen & Lowenstein, Beijing Readeagle, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Vaporizers Market Emerging Trajectories
Digital control architectures are absorbing market share from mechanical systems while regulatory software classifications reshape competitive boundaries. Three developments are restructuring how vaporizer technology is developed, sold, and maintained.
Computerized vaporizer systems with automated end-tidal anesthetic concentration targeting are absorbing adoption momentum from variable bypass units in tertiary hospital settings. Academic medical centers in the United States and Western Europe are deploying these systems to reduce anesthetic gas waste and improve emergence profile consistency. The technology is absorbing capital allocation that previously flowed to conventional mechanical vaporizer refreshes, compressing replacement cycles for legacy installed bases.
The EU Medical Device Regulation's software classification guidance is forcing manufacturers to reframe algorithmic vaporizer control as potentially standalone medical device software. This policy shift is extending conformity assessment timelines and expanding clinical evidence requirements for systems with closed-loop delivery features. Vaporizer platforms incorporating automated concentration targeting face the most significant regulatory burden, with some manufacturers decoupling software modules to preserve mechanical core certifications.
Integrated delivery networks in the United States are consolidating vaporizer procurement through centralized biomedical engineering committees, displacing individual hospital purchasing autonomy. These committees standardize across dozens of facilities, favoring vendors with multi-site service infrastructure and compatible anesthesia workstation ecosystems. The concentration of buying authority is most visible in states with extensive health system consolidation such as California, Texas, and Ohio, where three to five IDNs control the majority of acute care beds.
Anesthesia Vaporizers Market Segmentation
Vaporizer procurement patterns diverge sharply across clinical settings and technological architectures. Equipment replacement cycles and regulatory recertification timelines create distinct demand profiles that shape how manufacturers configure their product portfolios and service infrastructure.
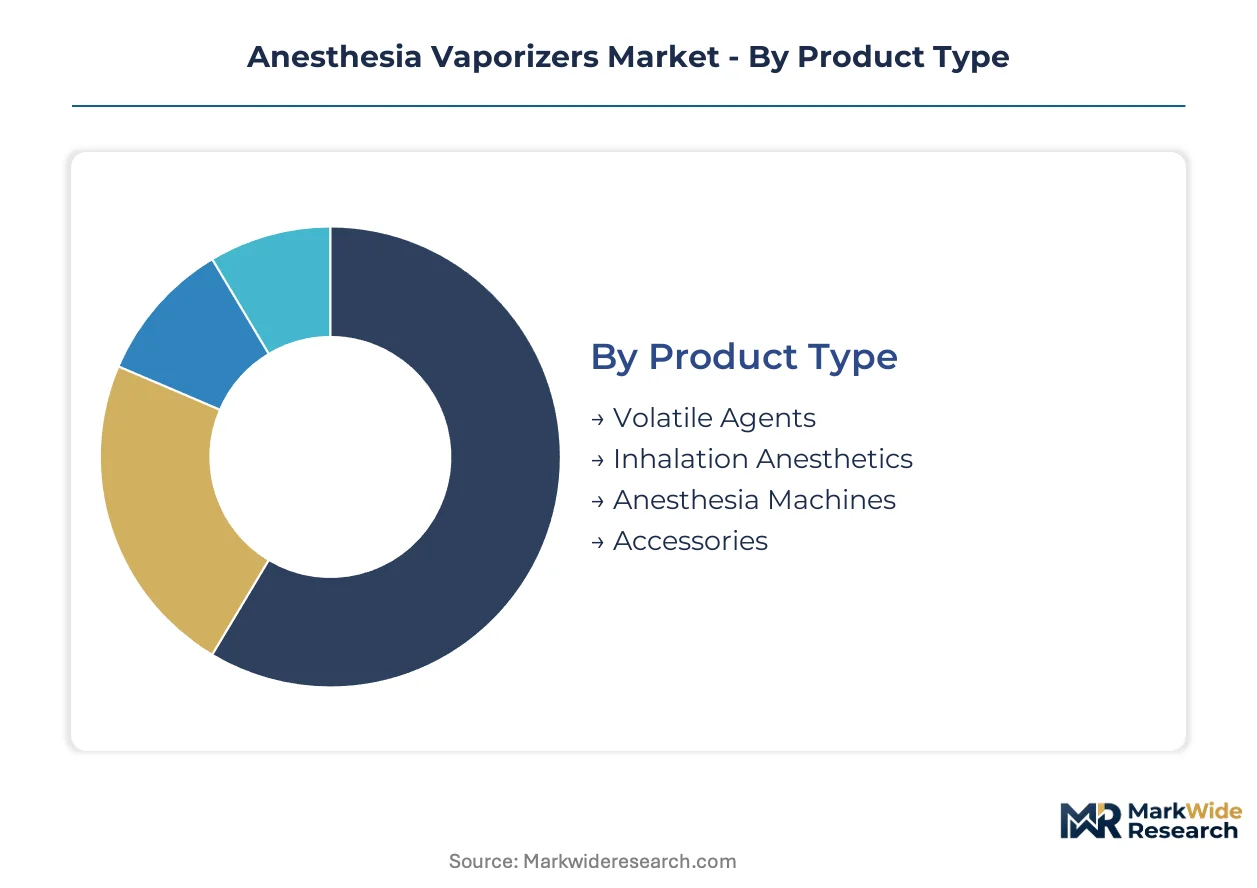
Product Type:
Upgrade cycles for precision vaporization hardware are accelerating as healthcare systems retire mechanical units in favor of digitally integrated platforms capable of automated concentration control.
- Volatile Agents:Halogenated ether compounds including sevoflurane and desflurane dominate liquid anesthetic consumption in tertiary care settings. Hospital pharmacies in the United States and Germany are consolidating procurement through centralized formularies that favor agents with favorable emergence profiles and lower greenhouse gas coefficients.
- Inhalation Anesthetics:Nitrous oxide and xenon gas delivery systems require specialized vaporizer interfaces with pressure-compensated flow control. Demand concentrates in obstetric suites and dental anesthesia suites across Japan and Australia where nitrous oxide analgesia retains established clinical protocols.
- Anesthesia Machines:Integrated workstation platforms combine vaporizer modules with ventilator and monitoring subsystems. European IDNs are standardizing on single-vendor ecosystems to simplify biomedical engineering training and spare parts logistics.
- Accessories:Vaporizer mounting brackets, filler caps, and wick replacement kits generate recurring aftermarket revenue. Independent service organizations in Brazil and Mexico are capturing calibration and preventive maintenance contracts previously held by original equipment manufacturers.
Volatile agents sit at the top of the volume ranking, with computerized vaporizer systems climbing the fastest.
End User:
Procurement authority is migrating from individual facility purchasing departments toward centralized supply chain committees that negotiate multi-year vaporizer fleet agreements.
- Hospitals:Academic medical centers and community hospitals maintain the largest installed bases of anesthesia workstations with embedded vaporizer modules. Replacement demand is hardening in Germany, France, and Italy as EU MDR compliance deadlines force retirement of legacy units lacking updated technical documentation.
- Ambulatory Surgical Centers:Freestanding outpatient facilities are installing compact vaporizer configurations optimized for rapid turnover of same-day procedures. United States ASCs in Texas, Florida, and California are driving demand for portable units with simplified calibration protocols.
- Clinics:Office-based surgical suites require miniaturized vaporizer systems with reduced agent consumption rates. Cost-engineered assemblies from Shenzhen Mindray Bio-Medical Electronics Co., Ltd. are penetrating price-sensitive procurement channels in Southeast Asia and Latin America.
- Research Institutions:Preclinical and veterinary research facilities utilize specialized vaporizer configurations for species-specific anesthetic delivery. Protocol standardization at NIH-funded centers in Maryland and Massachusetts is favoring vendors with documented reproducibility across small and large animal models.
Hospitals retain the dominant share of absolute procurement volume, though ambulatory surgical centers are expanding most quickly.
Technology:
Capital allocation is bifurcating between proven mechanical architectures and emerging digital platforms with closed-loop control capabilities.
- Variable Bypass:Mechanical flow-splitting technology maintains output accuracy through temperature-compensated metal bellows and wick assemblies. The design's electrical independence secures preference in resource-constrained settings across India and sub-Saharan Africa where power reliability is inconsistent.
- Computerized Systems:Microprocessor-controlled vaporizers with end-tidal gas feedback loops enable automated anesthetic concentration targeting. Tertiary hospitals in Switzerland, Sweden, and the Netherlands are deploying these systems to reduce agent waste and standardize emergence times.
- Continuous Flow:Conventional plenum vaporizer designs with fresh gas stream diversion remain prevalent in legacy anesthesia workstations. Biomedical engineering departments in Italy and Spain are extending service life of these units through component-level refurbishment rather than full replacement.
- Anesthetic Vaporization:Direct injection systems that vaporize liquid agent through heated nebulization chambers. Niche deployment in hyperbaric medicine suites and military field anesthesia units where conventional bypass designs face pressure-compensation challenges.
Variable bypass technology commands the largest installed base, while computerized systems are gaining share fastest.
Application:
Clinical workflow requirements dictate vaporizer specification priorities across surgical service lines with distinct agent selection and delivery precision demands.
- General Anesthesia:Inhaled agent maintenance for major surgical procedures requires vaporizers with precise output stability across varying fresh gas flows. Cardiac surgery suites in Cleveland Clinic and Mayo Clinic facilities are specifying dual-vaporizer configurations to enable rapid agent switching.
- Sedation:Conscious sedation protocols for endoscopic and interventional radiology procedures utilize low-flow vaporizer settings with scavenging systems. Ambulatory centers in Germany are adopting dedicated sedation vaporizer modules separate from main operating theater equipment pools.
- Pain Management:Chronic pain interventions including spinal cord stimulator trials employ nitrous oxide and low-dose volatile agent delivery. Pain clinics in United Kingdom NHS trusts are procuring compact vaporizer units for office-based procedural suites.
- Emergency Procedures:Field anesthesia and trauma bay applications demand vaporizers with rapid startup and minimal calibration requirements. Military medical services and civilian air ambulance operators in Australia and Canada are specifying ruggedized portable units.
General anesthesia applications generate the highest equipment utilization hours, with sedation services expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent pools in Germany, the United States, and Switzerland anchor the highest concentrations of vaporizer design expertise and precision manufacturing capability.
United States
Hospital consolidation across California, Texas, and Ohio is concentrating procurement authority within integrated delivery networks. FDA 510(k) clearance pathways govern electromagnetic compatibility standards for anesthesia workstations. Cleveland Clinic and Mayo Clinic cardiac surgery suites in Ohio and Minnesota specify dual-vaporizer configurations for rapid agent switching.
Germany
EU MDR compliance deadlines are forcing retirement of legacy vaporizer units lacking updated technical documentation. The country's national medical device regulator enforces stricter clinical evidence requirements for European market access. Baden-Württemberg and Bavaria host precision component suppliers serving Dragerwerk and other workstation manufacturers.
China
Domestic producers Beijing Aeonmed and Beijing Anton Medical Co., Ltd. compete on cost-engineered vaporizer assemblies for price-sensitive hospital procurement. NMPA GB standards constrain design parameters for medical electrical equipment. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. targets Asia-Pacific and Latin American markets from its Pearl River Delta manufacturing base.
Brazil
ANVISA regulatory pathway improvements are enabling faster market entry for cost-engineered vaporizer assemblies. The country's national health surveillance agency streamlines certification for mid-tier hospital procurement. São Paulo state hospitals represent the primary demand concentration for imported and domestic anesthesia equipment.
Switzerland
Tertiary hospitals in Zurich and Geneva deploy computerized vaporizer systems with automated end-tidal concentration targeting. Swissmedic maintains rigorous conformity assessment timelines for software-classified medical devices. The Basel-Land industrial corridor supports precision flow-control component manufacturing for European anesthesia workstation supply chains.
Anesthesia Vaporizers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the vaporizer value chain. The market structure consolidates around workstation-integrated platforms rather than standalone vaporizer modules. Three archetypes dominate: diversified medical technology conglomerates with anesthesia ecosystem control, mid-sized European specialists in precision flow-control engineering, and cost-optimized Asian fabricators serving emerging markets. Competitive moves center on service contract bundling and software module decoupling to preserve mechanical core certifications.
Among diversified medical technology conglomerates, GE Healthcare and Dragerwerk occupy positions anchored by installed bases of anesthesia workstations. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the cost-engineered Asian fabricator archetype targeting price-sensitive procurement channels. Beijing Aeonmed and Beijing Anton Medical Co., Ltd. represent domestic Chinese competitors operating within NMPA regulatory constraints.
| Leading Market Players |
|---|
| Penlon |
| Spacelabs Healthcare |
| Dragerwerk |
| Beijing Aeonmed |
| Beijing Anton Medical Co., Ltd. |
| GE Healthcare |
| Heinen & Lowenstein |
| Beijing Readeagle |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in the United States concentrate procurement authority across dozens of facilities, forcing vendors toward bundled service contracts that embed vaporizer hardware within multi-year anesthesia workstation agreements. This buyer concentration shifts pricing power toward volume-scale negotiations and away from standalone module transactions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vaporizer procurement, with differentiation driven by FDA 510(k) certification tier and after-sales service bundling. Pricing pressure stems from cost-engineered Asian competitors penetrating Latin American markets with stripped-down mechanical units. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize emergence profile consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European workstation OEMs mandate qualified suppliers in Germany, Switzerland, and the United States for precision flow-control components. Nickel-brass alloys and specialized polymer wick assemblies draw from mining operations in Canada and Australia. Single-source vulnerability concentrates in temperature-compensated metal bellows manufacturing. Distribution runs through authorized service organizations and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Europe create margin expansion opportunities for manufacturers with certified production in lower-regulatory jurisdictions.
For Market Incumbents: Deepen backward integration into nickel-brass alloy supply to offset input cost volatility from mining constraints. Lock in multi-year service contracts with expanding integrated delivery networks in Texas and California to defend against independent service organizations capturing calibration revenue. Prioritize CE marking pathway investments for computerized vaporizer systems before EU MDR software classification guidance hardens.
For New Entrants and Emerging Players: Independent service organizations represent the most penetrable channel partner type for aftermarket calibration and preventive maintenance contracts previously captive to original equipment manufacturers. Target Brazil's ANVISA-streamlined regulatory pathway for mid-tier hospital procurement. Penetrate through cost-engineered variable bypass assemblies optimized for power-unreliable settings in India and sub-Saharan Africa.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with anesthesia ecosystem control are the most active acquirer in this space, seeking vaporizer module capabilities to complete workstation portfolios. Five-to-ten year viability hinges on software-as-a-medical-device revenue streams from closed-loop algorithm convergence. Monitor EU MDR software classification enforcement timelines as inflection indicator for regulatory burden shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | CE marking under tightened software classifications extends conformity timelines for Dragerwerk and GE Healthcare platforms. |
| Hospital System Partnership | Multi-site service infrastructure agreements with Cleveland Clinic and Mayo Clinic standardize vaporizer fleets across cardiac surgery suites. |
| Software Companion Development | Closed-loop anesthetic delivery algorithms reframe regulatory obligations under FDA 510(k) and Swissmedic software guidance. |
| Backward Integration | Captive supply of nickel-brass alloys insulates Penlon and Heinen & Lowenstein from mining price volatility. |
| Geographic Manufacturing Footprint | Pearl River Delta production bases enable Shenzhen Mindray to serve price-sensitive Asia-Pacific and Latin American procurement. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineering directors and anesthesia department heads, GPO contracts databases, and FDA 510(k) clearance records — were reconciled against secondary validation from customs trade data and ISO 80601-2-13 technical documentation. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation anchored volume estimates. Conversations with hospital purchasing committees, independent service organization operators, and precision component suppliers in Baden-Württemberg informed replacement cycle assumptions.
Data-stream reconciliation across product type, technology architecture, end-user setting, and geographic regulatory cluster produced segmented demand profiles. CAGRs were derived from fitted growth curves applied to historical procurement patterns and projected EU MDR compliance-driven replacement waves. Industry-specific forecast inputs included ambulatory surgical center expansion rates in Texas and Florida, and NMPA GB standards evolution affecting domestic Chinese manufacturers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR software classification enforcement, nickel-brass alloy supply disruptions, and integrated delivery network consolidation pace. Deviation in EU MDR implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Anesthesia Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Ventilators Market
Medical Devices
Water Flosser Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Germany Aesthetic Devices Market