
 Global Vaginal Speculum Market | 2026-2036
Global Vaginal Speculum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaginal Speculum Market Foresight
A capital-intensity divergence between automated polymer molding and hand-finished stainless steel forging is bifurcating competitive returns across the supply base. Integra LifeSciences leverages its orthopedic-grade metalworking infrastructure to sustain premium positioning in reusable surgical-grade speculums. CooperSurgical Inc. anchors North American hospital contracts through integrated gynecology suites that bundle disposable plastic instruments with procedure trays.
A vaginal speculum is a hinged or fixed-blade instrument, typically manufactured from medical-grade stainless steel or autoclavable polymers such as polystyrene or polypropylene, designed to dilate the vaginal canal for visual examination of the cervix and vaginal walls during diagnostic or therapeutic procedures. Blade angle, width, and locking mechanism vary by procedural indication, with Graves and Pederson profiles representing the dominant geometric standards. The disposable plastic segment captures volume leadership in high-throughput screening programs where cross-contamination protocols prioritize single-use workflows. Reusable metal instruments retain margin concentration in tertiary hospitals with central sterile processing departments capable of validating autoclave cycles. Gynecological exams as an application category dominate procedure counts, though colposcopy-directed biopsies generate higher per-procedure instrument specificity.
FDA 510(k) clearance pathways and EU MDR Class I classification govern market access, with the latter imposing enhanced clinical evaluation and post-market surveillance obligations that extend certification timelines. India's CDSCO and BIS standards for medical devices are converging toward ISO 13485 quality management benchmarks, reshaping import requirements for multinational suppliers. Stakeholders must monitor how sterilization validation costs and extended MDR technical documentation timelines redistribute profitability between disposable and reusable product architectures.
Market Dynamics
The EU MDR's sterilization validation mandates are compressing margins for reusable metal speculum manufacturers while accelerating capital redeployment toward single-use polymer architectures.
Growth Catalysts
- India's Ayushman Bharat expansion:Government-funded cervical screening camps in tier-2 cities are generating instrument procurement contracts at volumes exceeding private hospital channels.
- ISO 13485 convergence:CDSCO and BIS alignment with international quality benchmarks is streamlining import pathways for multinational suppliers entering Indian distribution networks.
- Polymer molding automation:High-speed injection systems for medical-grade polystyrene are collapsing per-unit production costs for disposable speculum lines.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings are destabilizing margin forecasts for forged reusable instrument portfolios.
- EU MDR technical documentation:Extended clinical evaluation timelines for Class I reusable devices are freezing product line extensions and freezing R&D budgets.
- Central sterile processing concentration:Tertiary hospital consolidation of autoclave validation capabilities is limiting addressable market depth for premium reusable speculums.
Strategic Opportunities
- Brazil's SUS screening scale-up:ANVISA fast-track pathways for disposable gynecology kits are opening procurement windows for integrated procedure tray bundling.
- LED-integrated disposable speculums:Convergence of illumination electronics with polymer molding is creating premium single-use SKUs with 40-60% price elevation potential.
- Direct hospital contracting:Bypassing distributor markups through GPO-negotiated multi-year supply agreements is capturing margin compression from procurement centralization.
Industry Challenges
- Sterilization validation engineering:EU MDR's biocompatibility testing requirements for reusable metal instruments are creating talent scarcity in materials science and regulatory affairs functions.
- Legacy ERP integration:Hospital procurement platforms' rigid SKU hierarchies are forcing speculum suppliers to maintain parallel product master databases for contract compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaginal Speculum Market |
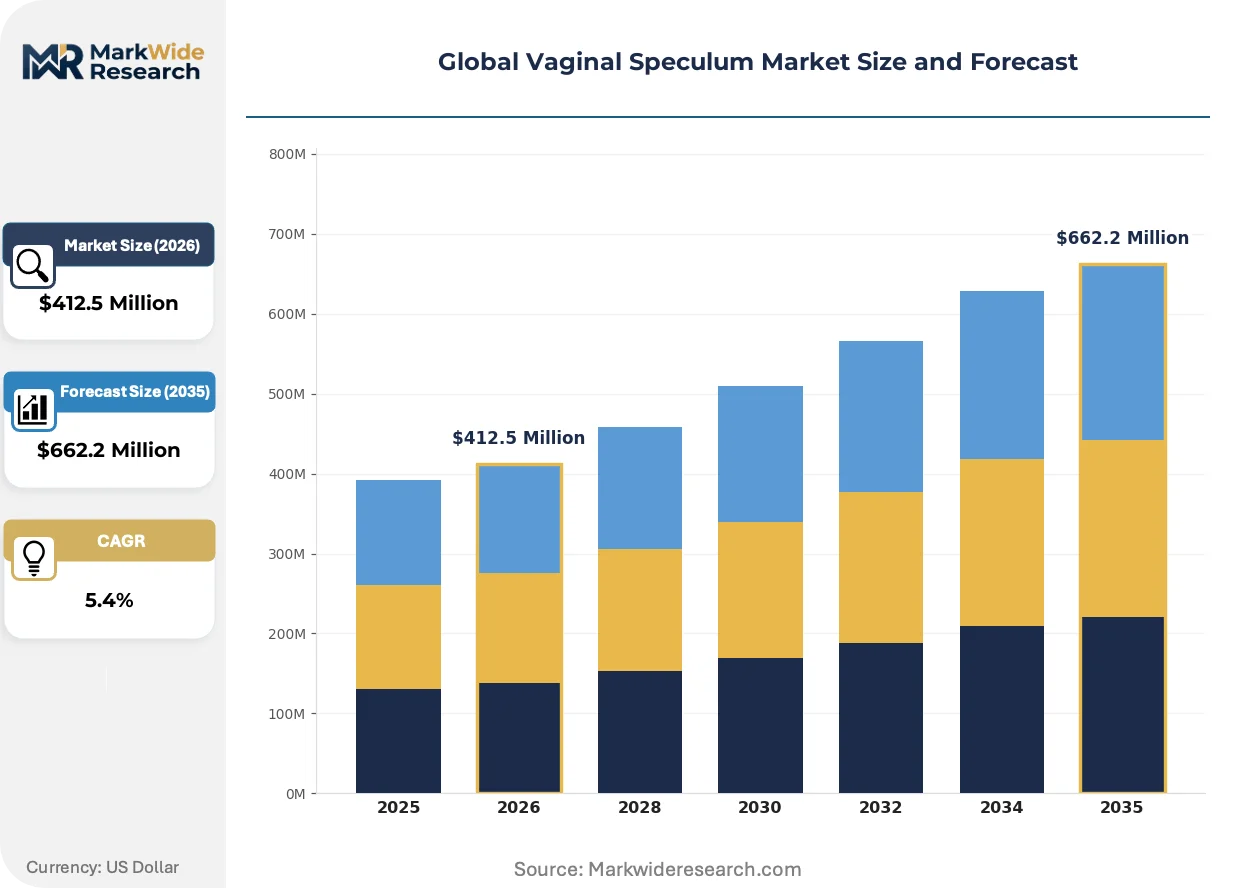
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Disposable, Reusable Application: Gynecological Exams, Obstetric Procedures, Colposcopy, Hysteroscopy End User: Hospitals, Diagnostic Centers, Maternity Clinics, Ambulatory Surgical Centers Distribution Channel: Direct Sales, Medical Distributors, Online Retail, Specialty Stores |
| Companies Covered | Integra LifeSciences, B. Braun Melsungen AG, CooperSurgical Inc., AdvaCare Pharma, MedGyn Products Inc., Becton Dickinson and Company, Teleflex Incorporated, Dynarex Corporation, Medline Industries LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaginal Speculum Market Shifts & Advancements
Material science advances and regulatory stringency are fragmenting competitive positioning between capital-intensive polymer automation and precision metalworking heritage.
Self-illuminated disposable speculums embedding LED arrays within molded polymer blades are eliminating external light source dependency during cervical visualization. Community health centers in India's Maharashtra and Tamil Nadu are piloting these instruments at 3x standard disposable pricing. This illumination integration is bifurcating procurement committees between cost-driven screening programs and premium-equipped tertiary facilities.
EU MDR's post-market surveillance obligations for Class I reusable devices are mandating electronic unique device identification and traceability systems. Manufacturers of stainless steel speculums must now maintain decade-long clinical follow-up databases previously exempt under MDD frameworks. German and French hospital systems are responding by accelerating disposable adoption to circumvent legacy instrument re-registration costs.
Hospital procurement departments are consolidating gynecology instrument purchasing through integrated procedure tray contracts that bundle speculums with drapes, swabs, and biopsy tools. Distributor networks in the United States are losing shelf-space influence as materials management departments negotiate directly with tray assemblers. This channel compression is most visible in IDN-affiliated hospitals where standardization committees override individual physician instrument preferences.
Global Vaginal Speculum Market Segmentation
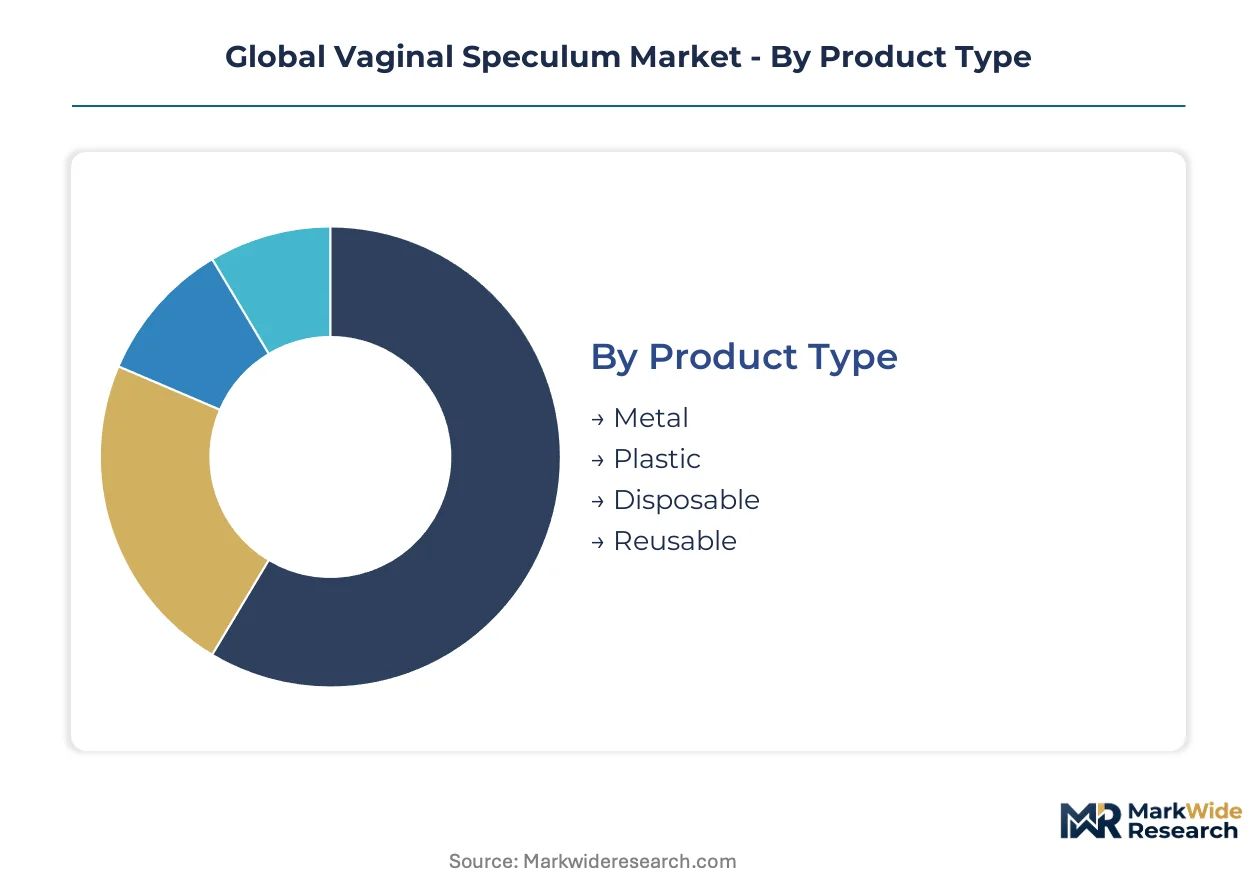
Product architecture and sterilization protocols fragment procurement patterns across institutional settings. Material selection and application specificity determine margin structures and regulatory compliance burdens for manufacturers.
Product Type:
FDA 510(k) clearance and EU MDR Class I classification impose divergent validation costs across material categories, reshaping competitive economics.
- Metal:Medical-grade stainless steel construction supports autoclave sterilization cycles exceeding 500 uses. Tertiary hospitals in Germany and the United States retain metal speculums where central sterile processing departments validate thermal disinfection protocols.
- Plastic:Injection-molded polystyrene or polypropylene variants eliminate cross-contamination risk in high-throughput screening programs. India's Ayushman Bharat cervical screening camps in tier-2 cities source plastic instruments at volumes exceeding private hospital procurement.
- Disposable:Single-use workflows dominate community health centers where sterilization infrastructure is absent.
- Reusable:Extended MDR technical documentation timelines and biocompatibility testing requirements compress margins for forged instrument portfolios.
Plastic handles the majority of throughput; Disposable is gaining share fastest in government-funded screening programs.
Application:
Procedure complexity and instrument specificity determine per-case revenue capture across diagnostic and therapeutic settings.
- Gynecological Exams:Routine cervical visualization drives procedure volume leadership, with standard Graves and Pederson blade profiles serving as geometric defaults. Mass screening initiatives in Brazil's SUS network and India's national health missions concentrate demand for basic examination instruments.
- Colposcopy:Directed biopsy procedures require speculums with integrated suction channels and enhanced cervical access angles. Tertiary oncology centers in France and Japan specify premium instruments for histological sampling accuracy.
- Obstetric Procedures:Amniocentesis and cerclage placement demand wider blade apertures and locking mechanisms engineered for maternal tissue sensitivity.
- Hysteroscopy:Distension medium compatibility and optical instrument passage requirements elevate specification thresholds for operative hysteroscopy suites.
Gynecological Exams generates the highest absolute procedure counts; Colposcopy commands the steepest expansion trajectory as cervical cancer screening protocols intensify.
End User:
Capital intensity and sterilization capability stratify addressable market depth across institutional tiers.
- Hospitals:Integrated procedure tray contracts and materials management centralization dominate procurement in IDN-affiliated facilities across the United States.
- Diagnostic Centers:High-throughput screening volumes in India's urban clusters and Brazil's metropolitan regions drive disposable instrument turnover.
- Maternity Clinics:Obstetric-focused settings in sub-Saharan Africa and Southeast Asia prioritize cost-minimized plastic speculums for antenatal examinations.
- Ambulatory Surgical Centers:Same-day discharge protocols in Germany and Switzerland favor pre-sterilized disposable kits to eliminate reprocessing bottlenecks.
Hospitals anchor procurement value; Diagnostic Centers are climbing fastest on volume contribution.
Distribution Channel:
Channel structure determines margin capture and customer relationship intensity across geographic markets.
- Direct Sales:GPO-negotiated multi-year agreements with hospital systems in the United States and national tender contracts in India's government health schemes bypass distributor markups.
- Medical Distributors:Regional networks in Latin America and Eastern Europe maintain inventory proximity for smaller clinics lacking centralized procurement.
- Online Retail:E-procurement platforms serving independent practitioners in Australia and Canada enable specification comparison and consolidated shipping.
- Specialty Stores:Medical supply retailers in Japan and South Korea serve outpatient gynecology practices with instrument customization services.
Direct Sales commands the largest revenue share; Online Retail is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for vaginal speculums diverges sharply across procurement contexts. Government-funded screening programs in India and Brazil prioritize unit cost minimization above all else. German and Japanese tertiary hospitals absorb premium pricing for reusable metal instruments where sterilization infrastructure validates extended-use economics.
United States
Hospital procurement centralization through integrated delivery networks concentrates contract awards for bundled procedure trays. FDA 510(k) clearance pathways govern market access for both polymer and stainless steel variants. The Southeast hospital corridor from Atlanta to Houston anchors domestic consumption volumes for disposable gynecology kits.
Germany
Central sterile processing departments in university hospitals sustain demand for autoclavable metal speculums despite EU MDR compliance burdens. The EU MDR's enhanced clinical evaluation timelines for Class I reusable devices compress margin forecasts for forged instrument portfolios. The Rhine-Ruhr industrial cluster hosts precision metalworking suppliers serving surgical instrument OEMs.
India
Ayushman Bharat cervical screening camps in tier-2 cities generate instrument procurement contracts at volumes exceeding private hospital channels. CDSCO convergence with ISO 13485 quality benchmarks streamlines import pathways for multinational suppliers. Maharashtra's Pune-Nashik manufacturing belt hosts domestic polymer molding operations serving government tender programs.
Brazil
ANVISA fast-track pathways for disposable gynecology kits accelerate procurement cycles within the SUS universal health network. Nickel and chromium price volatility destabilizes margin forecasts for imported stainless steel instruments. São Paulo's metropolitan diagnostic center density concentrates demand for high-throughput disposable workflows.
Japan
PMDA regulatory frameworks maintain stringent biocompatibility validation for reusable surgical instruments. METI industrial policy supports precision manufacturing heritage in medical device metalworking. The Osaka-Kobe corridor retains specialized forging capacity for premium surgical-grade speculums.
Global Vaginal Speculum Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vaginal speculum supply base. The market structure bifurcates between capital-intensive polymer automation specialists and heritage metalworking operations with orthopedic-grade forging capabilities. Three archetypes dominate: integrated gynecology suite bundlers, disposable volume manufacturers, and premium reusable instrument forgers. Competitive moves concentrate on direct hospital contracting to bypass distributor markups and LED-integrated product line extensions to capture premium pricing.
Among North American medical device conglomerates, CooperSurgical Inc. and Integra LifeSciences exemplify divergent strategic positions. CooperSurgical anchors integrated gynecology suite contracts that bundle disposable instruments with procedure trays. Integra LifeSciences occupies the premium reusable tier, leveraging orthopedic-grade metalworking infrastructure. B. Braun Melsungen AG represents European-scale manufacturing depth with diversified surgical instrument portfolios spanning both material categories.
| Leading Market Players |
|---|
| Integra LifeSciences |
| B. Braun Melsungen AG |
| CooperSurgical Inc. |
| AdvaCare Pharma |
| MedGyn Products Inc. |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| Dynarex Corporation |
| Medline Industries LP |
| Others |
Supply & Pricing Matrix
Multi-year GPO-negotiated contracts with United States hospital systems lock in polymer speculum supply access while compressing price visibility for reusable metal alternatives facing EU MDR compliance cost inflation. India's Ayushman Bharat tender structures amplify this divergence, bundling disposable instruments at government-negotiated rates that exclude premium stainless steel variants.
Pricing Analysis
After-sales revenue from sterilization validation services and extended maintenance contracts drives lifetime value capture for reusable metal speculum portfolios. Three-tier pricing structure across premium surgical-grade, standard clinical-grade, and economy screening-grade levels stratifies procurement committees. Cost compression in economy tiers intensifies because India's government health schemes prioritize unit cost minimization over instrument longevity. Diagnostic centers in Brazil's SUS network exhibit highest price sensitivity; German university hospitals with central sterile processing departments show least sensitivity.
Supply Chain Analysis
Just-in-time inventory preferences dominate disposable polymer speculum procurement, while strategic stockpiling of medical-grade stainless steel persists among heritage metalworking suppliers hedging nickel and chromium price volatility. Manufacturing concentrates in China for polymer injection molding, Germany for precision forging, and India for domestic tender fulfillment. Raw material dependencies include medical-grade polystyrene, 316L stainless steel, and nickel-chromium alloys. Single-source vulnerability in specialty polymer resin supply creates structural risk. Distribution runs through integrated procedure tray assemblers bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in government-funded screening program procurement, where Ayushman Bharat and Brazil's SUS expansion create volume niches inaccessible to premium reusable instrument specialists.
For Market Incumbents: Fortify hospital system partnerships through integrated gynecology suite bundling that locks out disposable-only competitors. Deepen backward integration into medical-grade polymer resin supply to offset commodity price volatility threatening margin stability. Prioritize LED-integrated product line extensions capturing premium pricing in tertiary facilities. For New Entrants and Emerging Players: Anchor in India's tier-2 city diagnostic center networks, the most penetrable geography where government tender volumes exceed private hospital procurement. Target maternity clinic segments in sub-Saharan Africa with cost-minimized plastic speculum lines. Deploy direct-to-hospital digital procurement platforms eliminating distributor markup capture. For Investors and Strategic Acquirers: Polymer molding automation specialists with ISO 13485 certification and established government tender relationships represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch EU MDR technical documentation timeline extensions as inflection indicator for disposable adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class I reusable device re-registration validates decade-long traceability infrastructure investment. |
| Hospital System Partnership | Integrated procedure tray contracts with United States IDNs bypass distributor shelf-space competition. |
| Backward Integration | In-house medical-grade polymer resin production hedges commodity cost volatility in high-throughput lines. |
| Software Companion Development | Electronic unique device identification systems satisfy EU MDR post-market surveillance mandates for reusable instruments. |
| Reimbursement Strategy | Government health scheme alignment in India and Brazil secures volume procurement at contracted price floors. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and regulatory affairs leads at polymer molding operations. Secondary validation drew from customs trade data, ISO 13485 certification registries, and government tender announcement archives. Bottom-up instrument shipment modeling triangulated against top-down healthcare expenditure allocation estimates.
Variance-decomposition across material type, application specificity, end-user capital intensity, and distribution channel structure anchored the analytical framework. Segmentation dimensions modeled include product architecture, sterilization protocol, procedure complexity tier, and institutional procurement centralization level. CAGRs derived from shipment volume trajectories adjusted for regulatory timeline impacts and raw material cost cycle positioning. Forecast inputs incorporated EU MDR compliance cost inflation and government screening program expansion schedules.
Material uncertainties — sterilization validation cost escalation, nickel price volatility, and government tender award timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline stability and polymer resin supply continuity. Revision becomes warranted when EU MDR technical documentation backlogs exceed hospital system patience thresholds for reusable instrument re-registration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cough Assist Devices Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Band Ligators Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Power Smart Bed Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Medical Electrodes Market
Medical Devices
US Medical Display Monitors Market