
 Global Holter ECG Market | 2026-2036
Global Holter ECG Market Size, Share, and Industry Trends Forecast 2026-2036
Global Holter ECG Market Foresight
Buyer concentration among large hospital networks and integrated delivery systems is hardening procurement standards for Holter ECG vendors. GE Healthcare leverages its installed base of cardiac imaging systems to cross-sell monitoring solutions. Philips sustains technology leadership through its digital health platform integration. Nihon Kohden anchors its position in Asia-Pacific markets with localized manufacturing and regulatory expertise.
A Holter ECG is a portable ambulatory electrocardiography device that continuously records cardiac electrical activity over 24 to 48 hours via multiple skin electrodes, storing data in digital memory for later analysis of transient arrhythmias and ischemic episodes. Wireless Holter systems are capturing the fastest growth trajectory as real-time monitoring and cloud-enabled data transmission replace traditional memory-card retrieval workflows. Cardiology clinics represent the most concentrated end-user margin pool due to recurring device utilization and interpretation service revenue.
FDA premarket notification requirements, CE marking under the EU MDR, and Japan PMDA quality management standards collectively elevate barriers for new entrants lacking clinical validation infrastructure. These frameworks compel manufacturers to invest in software lifecycle documentation and cybersecurity assurance before commercial release. Stakeholders must monitor evolving reimbursement codes for remote cardiac monitoring as payers recalibrate coverage for continuous versus episodic diagnostic modalities.
Market Dynamics
Wireless telemetry and cloud-based data transmission are compressing the traditional Holter ECG workflow from memory-card retrieval to real-time physician notification, forcing incumbent vendors to rearchitect software stacks around cybersecurity validation and interoperability standards.
Growth Catalysts
- EU MDR software lifecycle requirements:Stricter CE marking documentation for cloud-enabled cardiac monitors is filtering out low-validation competitors and consolidating procurement toward established vendors with clinical evidence infrastructure.
- Cardiology clinic consolidation:Large integrated delivery networks in the United States are standardizing on single-vendor ambulatory monitoring platforms to streamline interpretation workflows and capture recurring service revenue.
- Patch-based electrode arrays:Extended-wear adhesive sensors eliminating lead-wire artifacts are expanding patient compliance and diagnostic yield in 14-day monitoring protocols.
Market Restraints
- Semiconductor component concentration:Discrete analog-to-digital converters and low-power Bluetooth modules face supply allocation pressure from consumer electronics demand, stretching lead times for Holter device manufacturers.
- FDA 510(k) cybersecurity documentation:Pre-submission requirements for software bill of materials and threat modeling have extended regulatory timelines by four to six months for cloud-connected submissions.
- Consumer-grade wearable substitution:Apple Watch and similar photoplethysmography devices are capturing low-acuity arrhythmia screening, compressing addressable volume for entry-level Holter systems in wellness applications.
Strategic Opportunities
- Japan's PMDA fast-track pathway:Breakthrough designation for AI-augmented arrhythmia detection is accelerating market access for algorithm-enabled Holter platforms in the world's most aged population.
- Remote patient monitoring reimbursement codes:CMS physician fee schedule expansions for continuous cardiac monitoring are creating service revenue pools beyond device sale margins in United States outpatient settings.
- Machine learning and EHR integration:Automated report generation directly into Epic and Cerner workflows is converging diagnostic devices with health system IT infrastructure, embedding vendor stickiness.
Industry Challenges
- Electrophysiologist interpretation capacity:Rising ambulatory monitoring volumes are outstripping trained clinician availability, forcing vendors to develop FDA-cleared autonomous analysis algorithms or risk report backlogs.
- Legacy HL7 v2 interface maintenance:Health system EHR fragmentation requires ongoing engineering investment to support multiple connectivity standards, diverting R&D from next-generation sensor development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Holter ECG Market |
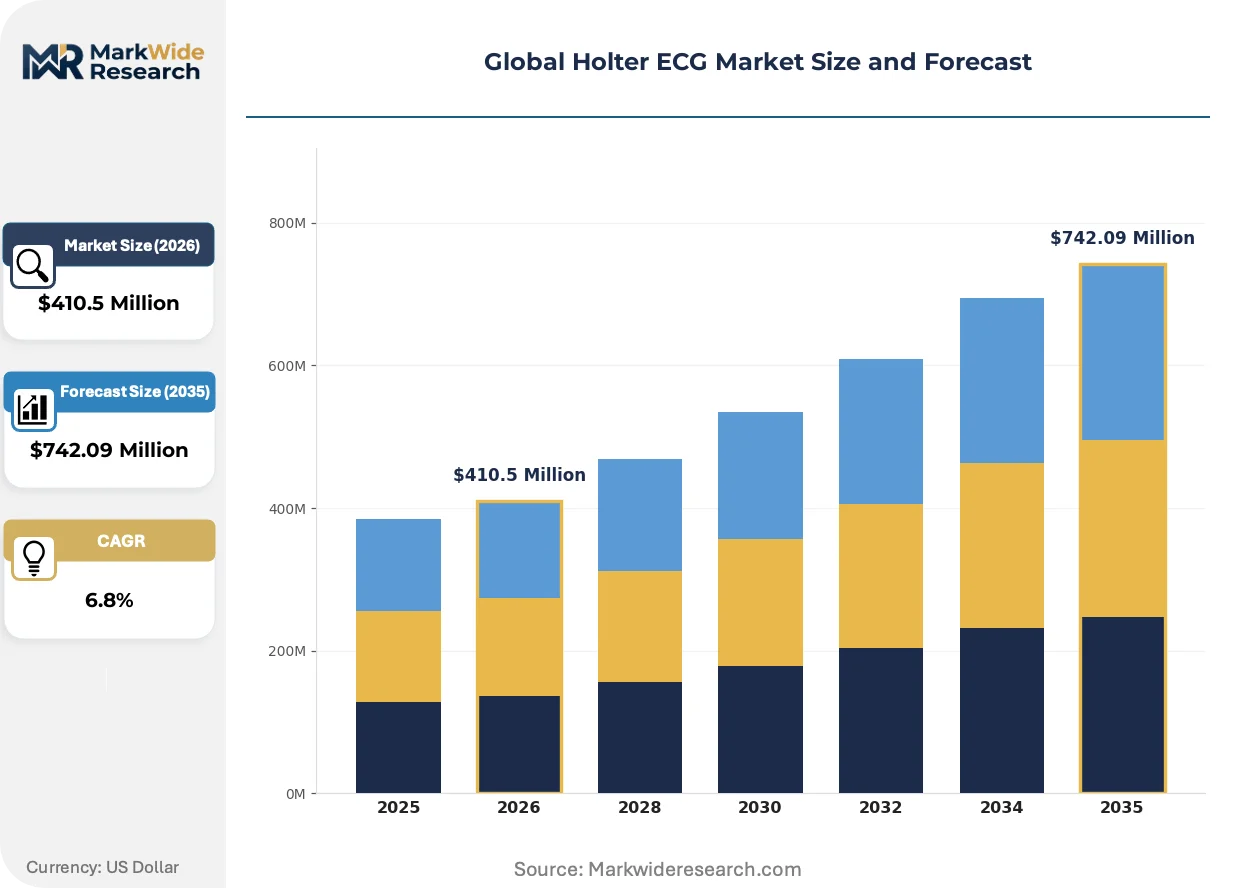
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $742.09 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Dual-Channel, Multi-Channel, Wireless Holter Technology: Digital Recording, Memory Storage, Real-Time Monitoring, Cloud-Enabled Application: Arrhythmia Detection, Ischemic Heart Disease, Palpitations, Syncope Monitoring End User: Cardiology Clinics, Diagnostic Centers, Ambulatory Care, Research Laboratories |
| Companies Covered | Fukuda Denshi Co., Ltd., OSI Systems, Inc., Koninklijke Philips N.V., Biotricity Inc., Hill-Rom (Baxter), GE Healthcare, Schiller AG, Bittium Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Holter ECG Market Shifts & Advancements
Artificial intelligence inference at the edge is transforming Holter ECG devices from passive data loggers into real-time clinical decision support tools, compressing the diagnostic cycle from days to minutes and redefining competitive differentiation around algorithmic accuracy rather than hardware specifications alone.
Deep learning arrhythmia classifiers running on low-power neural processing units are converging with traditional Holter hardware architectures. Cardiology clinics in Germany and the United States are piloting these systems for same-day critical event notification. This convergence is compressing the value chain by eliminating third-party interpretation services and capturing margin within device vendors.
Japan's PMDA revised software as a medical device guidance now mandates post-market surveillance for AI-enabled diagnostic algorithms, requiring manufacturers to maintain real-world performance registries. The regulation is forcing Holter vendors to architect cloud infrastructure for continuous model monitoring rather than static premarket validation. Systems with adaptive learning capabilities face the steepest compliance burden under this framework.
Hospital procurement committees are unbundling device acquisition from interpretation service contracts, creating direct purchasing relationships with Holter manufacturers previously mediated by cardiology service companies. This disintermediation is most visible in United States integrated delivery networks consolidating vendor lists under value-based care contracts. Manufacturers must now build direct clinical support capabilities or cede margin to retained service intermediaries.
Global Holter ECG Market Segmentation
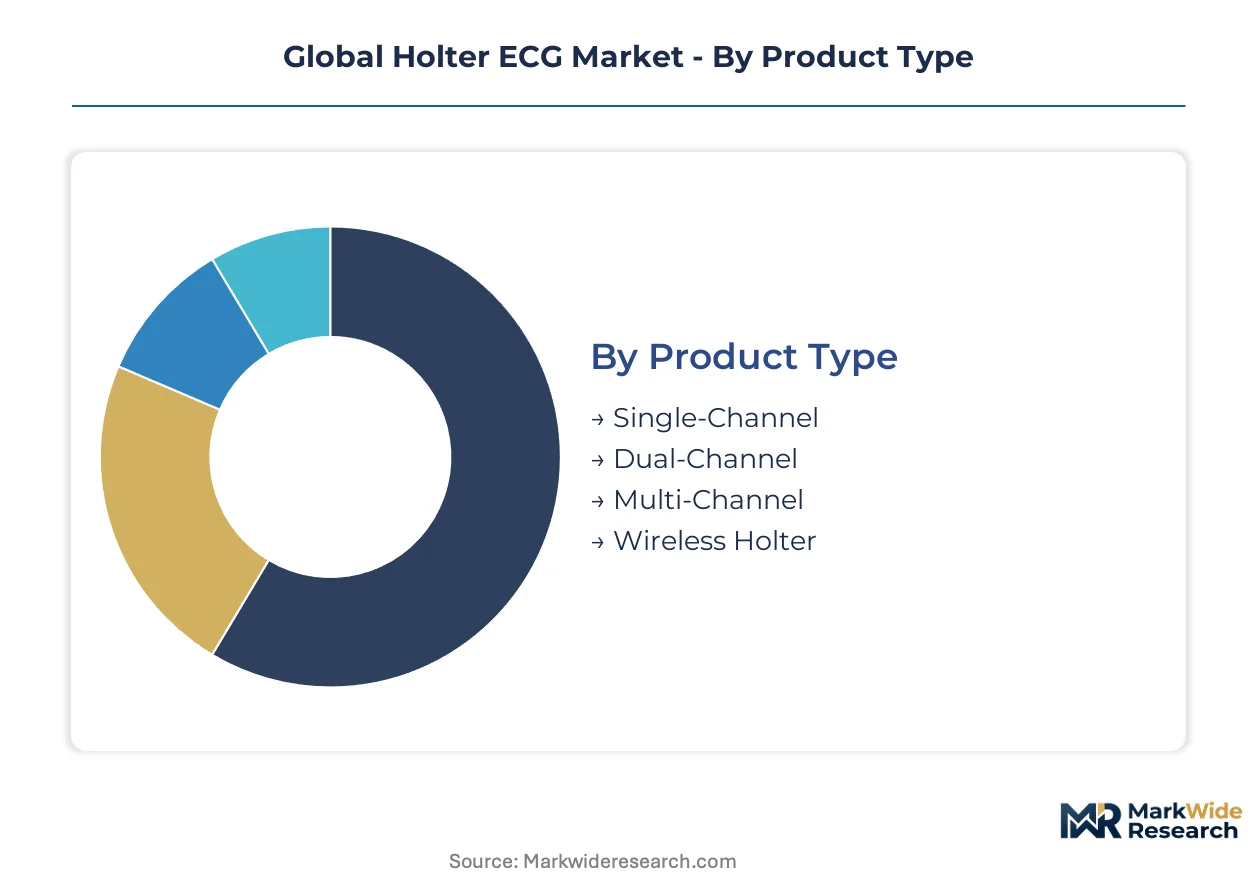
Holter ECG segmentation reveals distinct margin structures across hardware configurations and service delivery models. Product architecture determines whether vendors capture one-time device revenue or recurring monitoring service fees. Technology integration depth separates standalone diagnostic tools from embedded health system infrastructure.
Product Type:
Single-channel systems serve basic screening in resource-constrained settings while multi-channel and wireless architectures embed into integrated cardiac monitoring platforms with real-time telemetry capabilities.
- Single-Channel:Compact two-electrode configuration recording one vector of cardiac electrical activity. Demand concentrates in primary care clinics across India and Brazil where cost sensitivity dominates procurement decisions and reimbursement for extended monitoring remains limited.
- Dual-Channel:Simultaneous bipolar recording from two independent leads improves arrhythmia localization accuracy. Cardiology clinics in Germany and Japan deploy these systems for intermediate-risk patients requiring more spatial resolution than single-channel devices without full 12-lead complexity.
- Multi-Channel:Three to twelve lead configurations capturing comprehensive electrocardiographic data for complex arrhythmia characterization.
- Wireless Holter:Bluetooth-enabled devices transmitting continuous ECG streams to cloud platforms for immediate clinician review.
Volume placements concentrate in dual-channel systems; the faster expansion belongs to wireless Holter platforms.
Technology:
Recording and transmission architectures determine regulatory pathway complexity and software validation burden under FDA and EU MDR frameworks.
- Digital Recording:Analog-to-digital conversion with local flash memory storage remains the baseline technology for cost-sensitive procurement.
- Memory Storage:Removable SD card or internal solid-state retention requiring physical device retrieval for data analysis.
- Real-Time Monitoring:Continuous cellular or WiFi transmission enabling immediate event notification to clinical teams. United States integrated delivery networks prioritize these systems for post-discharge monitoring programs under remote patient monitoring reimbursement codes.
- Cloud-Enabled:Full software-as-a-service architecture with automated analysis, multi-site data sharing, and predictive algorithm deployment. Japan's PMDA fast-track pathway accelerates approval for AI-augmented cloud platforms serving its aged population.
Memory storage dominates current installed base; cloud-enabled configurations are climbing the fastest.
Application:
Clinical indication shapes monitoring duration requirements and algorithm training priorities for automated interpretation systems.
- Arrhythmia Detection:Algorithm-optimized systems identifying atrial fibrillation, ventricular tachycardia, and conduction abnormalities. Demand concentrates in United States cardiology clinics where stroke prevention protocols drive extended monitoring for cryptogenic stroke patients.
- Ischemic Heart Disease:ST-segment analysis for silent ischemia detection during daily activities. German rehabilitation centers deploy these systems for post-MI exercise tolerance assessment under statutory health insurance coverage.
- Palpitations:Symptom-correlation monitoring linking patient-triggered events to electrocardiographic findings.
- Syncope Monitoring:Extended 14 to 30-day recording protocols capturing infrequent events suggesting bradyarrhythmias or conduction system disease.
Arrhythmia detection generates highest procedure volume; syncope monitoring shows steepest expansion trajectory.
End User:
Procurement authority and service revenue capture potential vary sharply across institutional settings.
- Cardiology Clinics:Physician-owned practices and hospital outpatient departments capturing interpretation fees alongside device utilization. United States integrated delivery networks consolidate vendor relationships here to streamline workflow and retain margin.
- Diagnostic Centers:Independent testing facilities performing device application and preliminary analysis for referring physicians. India's diagnostic chains expand Holter services in tier-2 cities under cash-pay models.
- Ambulatory Care:Hospital-based same-day surgery and emergency observation units requiring rapid-turnaround pre-discharge screening.
- Research Laboratories:Academic medical centers and contract research organizations deploying Holter systems for clinical trial endpoints.
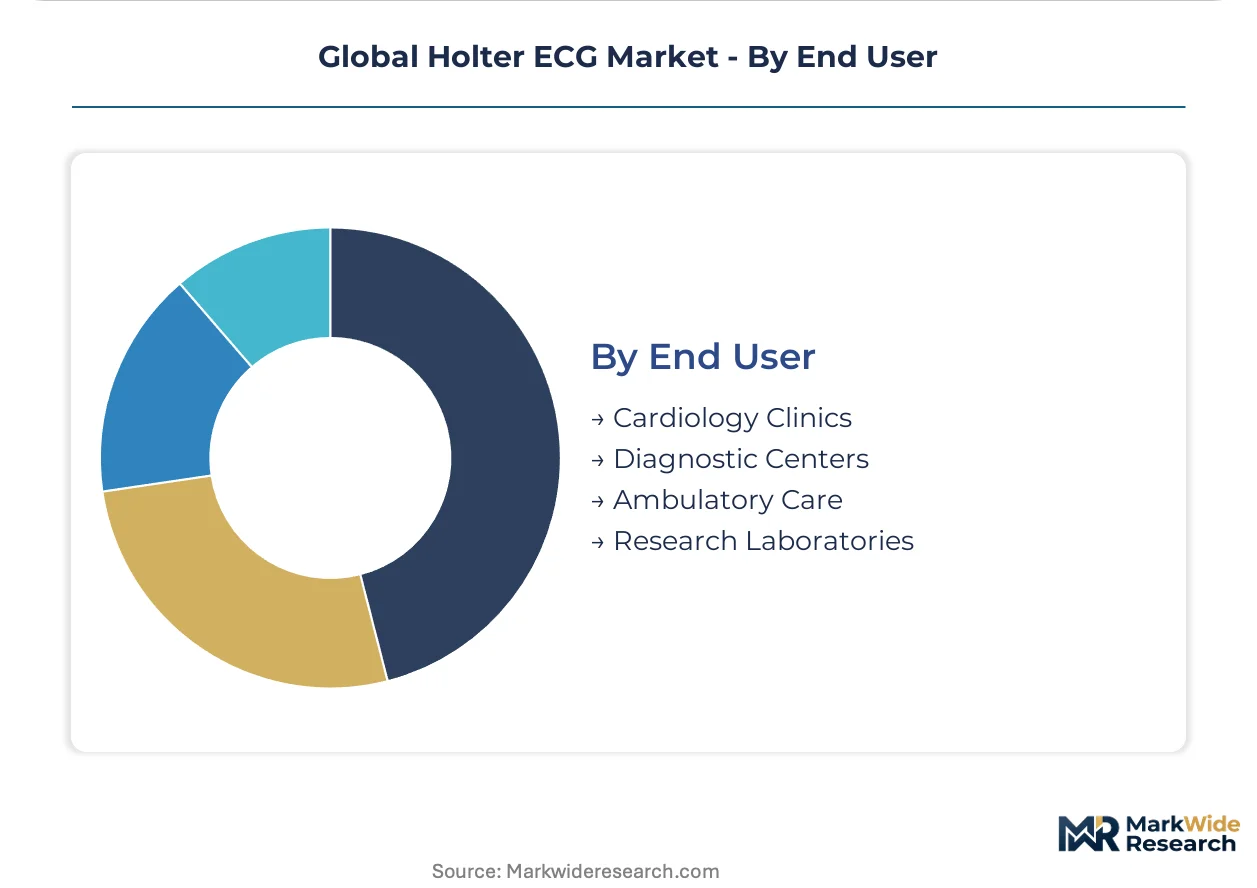
Cardiology clinics anchor current revenue concentration; diagnostic centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic demand concentrates in aging populations with established reimbursement frameworks for ambulatory cardiac monitoring. Regulatory pathways diverge sharply across jurisdictions, fragmenting vendor compliance strategies. Industrial clusters align with specialized cardiology infrastructure and health system consolidation patterns.
United States
Integrated delivery networks in Texas and California drive standardization of single-vendor ambulatory monitoring platforms. FDA 510(k) cybersecurity documentation requirements extend regulatory timelines for cloud-connected submissions. The Minneapolis medical device corridor hosts established cardiac monitoring specialists with clinical validation infrastructure.
Germany
Statutory health insurance coverage for post-MI rehabilitation monitoring sustains demand across dual-channel and multi-channel configurations. EU MDR software lifecycle requirements filter procurement toward vendors with comprehensive clinical evidence packages. The Baden-Württemberg medical technology cluster concentrates electrophysiology interpretation expertise.
Japan
The world's most aged population generates diagnostic volume for extended monitoring protocols addressing cryptogenic stroke and syncope. PMDA fast-track designation for AI-augmented arrhythmia detection accelerates market access for algorithm-enabled platforms. Tokyo and Osaka metropolitan areas anchor cardiology clinic consolidation and digital health platform adoption.
India
Diagnostic chains expand Holter services in tier-2 cities under cash-pay models, concentrating demand in single-channel cost-sensitive configurations. CDSCO medical device regulations tighten quality management standards for imported monitoring equipment. Maharashtra and Gujarat host manufacturing facilities serving domestic price-sensitive procurement.
Brazil
Private health insurance expansion in São Paulo and Rio de Janeiro drives adoption of wireless telemetry systems for post-discharge monitoring. ANVISA medical device registration requirements elevate documentation burdens for cloud-enabled platforms. The Southeast region concentrates cardiology clinic infrastructure and interpretation service capacity.
Global Holter ECG Market Competitive Landscape
United States and European producers anchor the premium technology tier; Japanese specialists hold position in Asia-Pacific regulatory expertise. Vendor concentration is moderate, with established cardiac monitoring divisions of diversified health technology conglomerates competing against focused ambulatory monitoring specialists. Three archetypes dominate: imaging-system incumbents cross-selling monitoring solutions, pure-play telemetry specialists, and diversified electronics manufacturers leveraging component scale. Competitive moves center on health system IT integration partnerships and AI algorithm regulatory clearances.
Within the diversified health technology tier, GE Healthcare and Koninklijke Philips N.V. represent cross-selling archetypes leveraging installed imaging bases. Nihon Kohden Corporation anchors Asia-Pacific positioning through localized manufacturing and PMDA regulatory expertise. Fukuda Denshi Co., Ltd. exemplifies the specialized cardiac monitoring fabricator with concentrated regional presence. OSI Systems, Inc. and Hill-Rom (Baxter) occupy positions spanning hospital infrastructure and patient monitoring equipment. Biotricity Inc. and Bittium Corporation represent emerging telemetry-focused specialists, while Schiller AG maintains European positioning in diagnostic cardiology systems.
| Leading Market Players |
|---|
| Fukuda Denshi Co., Ltd. |
| OSI Systems, Inc. |
| Koninklijke Philips N.V. |
| Biotricity Inc. |
| Hill-Rom (Baxter) |
| GE Healthcare |
| Schiller AG |
| Bittium Corporation |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Electrophysiologist interpretation capacity in the Minneapolis medical device corridor creates labor-cost differentials that widen pricing-tier spreads between premium AI-augmented platforms and economy-grade single-channel devices. Cardiology clinics in Germany and Japan absorb higher service fees for algorithm-enabled systems while Indian diagnostic chains drive procurement toward cost-minimized configurations.
Pricing Analysis
Volume placements concentrate in dual-channel systems capturing standard-tier margins while wireless Holter platforms command premium positioning through real-time telemetry capabilities. Pricing stratifies across premium, standard, and economy tiers based on FDA cybersecurity documentation tier and after-sales interpretation service bundling. Pricing pressure stems from consumer-grade wearable substitution compressing entry-level addressable volume. Diagnostic centers in India and Brazil exhibit highest price sensitivity; United States integrated delivery networks prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Regional distribution centers in Minnesota, Baden-Württemberg, and Tokyo prefecture anchor hub-and-spoke patterns serving cardiology clinic networks with rapid device replenishment. Component manufacturing concentrates in Taiwan, South Korea, and Japan for discrete analog-to-digital converters and low-power Bluetooth modules. Raw material dependencies span semiconductor wafers, medical-grade adhesives for patch-based electrodes, and lithium-ion cells for extended-wear configurations. Single-source vulnerability in neural processing units for AI inference creates procurement risk. Distribution runs through direct hospital system contracts and specialized cardiology distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR software lifecycle requirements are filtering out low-validation competitors and consolidating procurement toward established vendors with clinical evidence infrastructure, forcing weaker players toward exit or acquisition.
For Market Incumbents: Extend algorithmic differentiation through PMDA fast-track pathway submissions in Japan while embedding cloud platforms directly into Epic and Cerner EHR workflows. Consumer-grade wearable substitution threatens entry-tier revenue; defend through backward integration into proprietary sensor manufacturing and exclusive interpretation service contracts with United States integrated delivery networks. For New Entrants and Emerging Players: Tier-2 city diagnostic chains in India represent an underserved buyer archetype with cash-pay models and limited incumbent penetration. Target cloud-enabled platforms with simplified AI analysis bypassing electrophysiologist bottlenecks. Pursue white-label manufacturing partnerships with Maharashtra-based facilities to achieve cost parity with single-channel imports. For Investors and Strategic Acquirers: Re-rating potential sits with telemetry-focused specialists possessing FDA-cleared autonomous analysis algorithms given CMS reimbursement code expansion for remote patient monitoring. Long-term viability favors vendors with health system IT integration depth over hardware-only fabricators. Watch Japan PMDA post-market surveillance compliance costs as inflection indicator for AI-enabled platform margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Cybersecurity documentation requirements extend timelines for cloud-connected 510(k) pathways. |
| CE Marking Pathway | EU MDR software lifecycle mandates filter procurement toward validated clinical evidence packages. |
| Hospital System Partnership | Integrated delivery network consolidation creates single-vendor platform standardization opportunities. |
| Software Companion Development | AI-augmented arrhythmia detection embedded in Epic workflows captures interpretation service margin. |
| Reimbursement Strategy | CMS physician fee schedule expansion for continuous monitoring creates service revenue pools beyond device sales. |
Research Methodology
Document review covered FDA 510(k) filings, CE marking documentation under EU MDR, PMDA approval records, and CMS reimbursement code updates, complemented by interviews with electrophysiologists, hospital biomedical engineers, GPO contracts managers, and cardiology clinic administrators. Secondary sources included hospital procurement databases, GPO contract repositories, and medical device trade data. Bottom-up shipment estimates triangulated against top-down diagnostic procedure volume projections.
Cross-referencing historical adoption curves with panel input from regulatory affairs specialists and health system IT directors anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, recording technology, clinical application, and end-user institution type. CAGRs derived from regression analysis of procedure volume growth, reimbursement rate trajectories, and technology substitution elasticities. Forecast inputs incorporated semiconductor supply allocation pressures and AI algorithm regulatory clearance timelines.
Revisions become necessary when FDA cybersecurity guidance tightens, EU MDR enforcement intensifies, or consumer-grade wearable diagnostic accuracy improves materially. Forecasts reflect documented assumptions regarding reimbursement stability and electrophysiologist workforce expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Retinal Implant Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Diabetes Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Liquid Oxygen Devices Market