
 Global Extremities Market | 2026-2036
Global Extremities Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extremities Market Analysis
Maintenance and implant tracking subscription services is expanding how orthopedic manufacturers monetize patient outcomes over device lifecycles. Stryker leverages connected implant platforms to sustain recurring revenue streams. Zimmer Biomet anchors its portfolio with remote monitoring capabilities for joint replacement patients.
Extremities encompass the bones, joints, and soft tissues of the shoulder, arm, hand, hip, leg, and foot, typically reconstructed using titanium alloy implants, carbon-fiber composites, or resorbable polymers through additive manufacturing or precision forging processes. Orthopedic implants command the largest revenue pool due to high procedure volumes and premium pricing for shoulder and ankle arthroplasty systems. Fixation devices represent the fastest-expanding category, driven by minimally invasive trauma procedures and biodegradable material adoption that reduces secondary removal surgeries.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and commercial access for extremity device manufacturers. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains. Stakeholders must weigh regulatory compliance investments against the margin compression from value-based care contracting models.
Market Dynamics
Patient-specific implant manufacturing through additive production is compressing development cycles and enabling mass customization at unit economics previously reserved for standard catalogs. This shift forces manufacturers to reconfigure quality systems around lot sizes of one rather than batch validation.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS reimbursement parity for outpatient joint procedures in the United States accelerates site-of-service migration for shoulder and ankle arthroplasty. Fixation device volumes concentrate in these lower-cost settings.
- EU MDR Technical Documentation Requirements:Stricter clinical evidence standards for Class III implants are elevating barriers for marginal competitors. Incumbent manufacturers with established PMCF data capture disproportionate share gains.
- Titanium Lattice Structures:Additive-manufactured porous architectures improve osseointegration rates in revision cases. Orthopedic surgeons in Germany and Japan demonstrate preference for these constructs in complex reconstructions.
Market Restraints
- Titanium Sponge Price Volatility:Aerospace and energy sector competition for sponge feedstock creates input cost instability. Implant manufacturers lack long-term offtake agreements with Russian or Chinese sponge producers.
- Single-Source Ceramic Bearing Supply:Femoral head ceramic production concentrates among three European suppliers. Any disruption to German or French sintering capacity halts premium arthroplasty assembly lines.
- Bioresorbable Polymer Degradation Uncertainty:Variable in-vivo resorption rates for PLLA and PGA fixation devices complicate clinical predictability. Surgeons in conservative markets default to metallic alternatives.
Strategic Opportunities
- India Reconstruction Penetration:Trauma fixation procedure rates remain below one-fifth of OECD benchmarks. CDSCO streamlined 510(k)-equivalent pathways for predicate devices reduce registration timelines for multinational entrants.
- Remote Patient Monitoring Integration:Connected implant platforms enable post-operative kinematic tracking. Recurring software subscriptions supplement one-time hardware margins in United States value-based care contracts.
- PEEK-OPTIMA Polymer Adoption in Foot/Ankle:Radiolucent properties improve post-operative imaging assessment. Ankle fusion and osteotomy applications represent underpenetrated expansion vectors.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Qualified operators for electron beam melting and laser powder bed fusion command premium wages. Orthopedic OEMs compete with aerospace and dental for limited talent pools.
- EU MDR Notified Body Capacity Bottlenecks:Extended conformity assessment queues delay product launches. Manufacturers face 18-24 month certification cycles versus 6-9 months under previous directives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extremities Market |
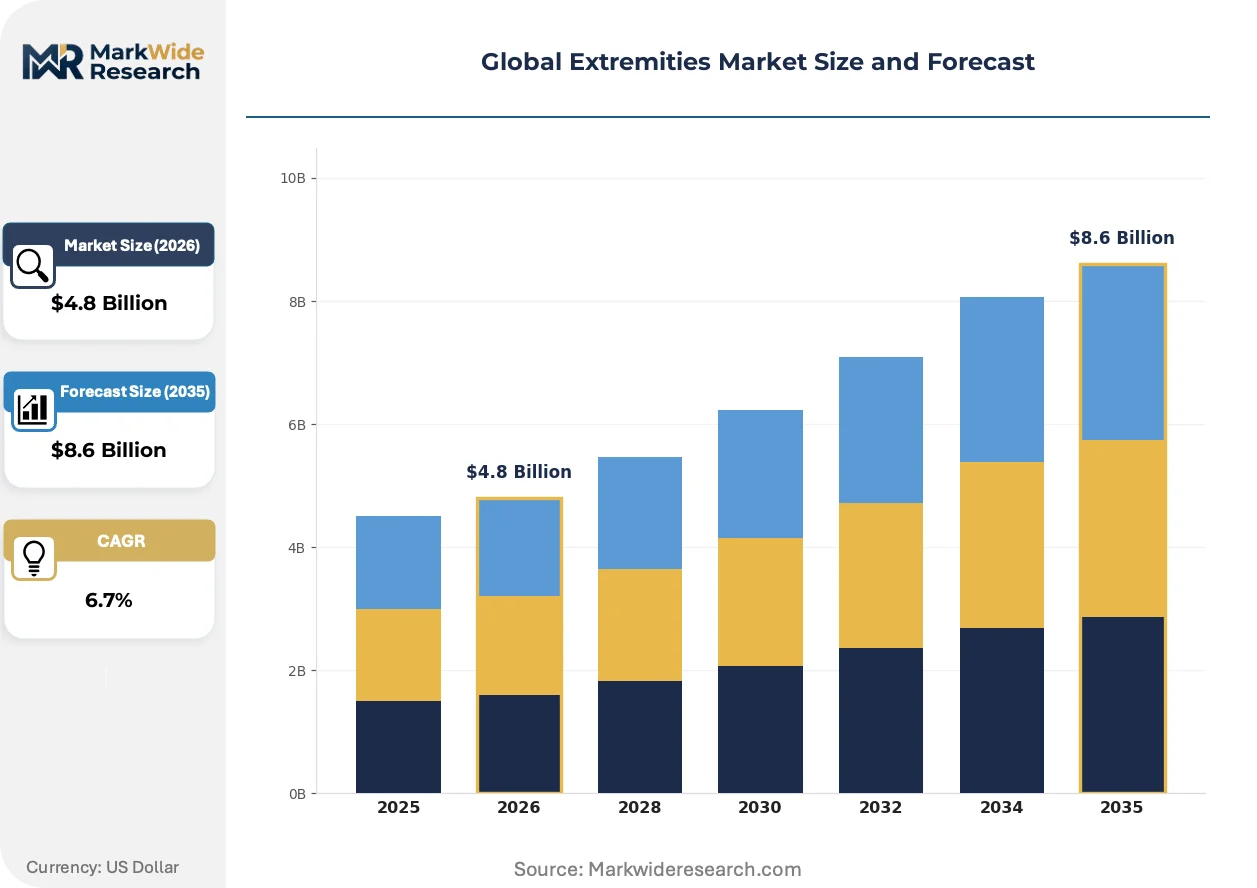
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Prosthetic Limbs, Orthopedic Implants, Fixation Devices, Bone Plates Application: Trauma & Fracture, Sports Injuries, Reconstruction, Arthritis End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Home Care Material: Metal, Polymer, Composites, Biodegradable Materials |
| Companies Covered | Johnson & Johnson, Orthofix, Stryker, Arthrex, Globus Medical, Zimmer Biomet, Enovis, MicroPort, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extremities Market Emerging Trajectories
Additive manufacturing is collapsing the traditional trade-off between customization and scale in extremity implant production. Three developments are restructuring competitive advantage.
Patient-matched cutting guides and instrumentation are consolidating pre-operative planning into integrated digital workflows. Ambulatory surgical centers in the United States adopt these systems to reduce operative time and sterilization burden. The technology is consolidating instrument tray complexity from 12-15 cases to 3-4 universal configurations.
EU MDR Article 10 post-market clinical follow-up mandates are extending evidence generation obligations across implant lifecycles. Manufacturers must now collect real-world performance data for 10-15 year horizons. Shoulder arthroplasty systems face the steepest compliance curves given higher revision rates and longer follow-up requirements.
Surgeon ownership of outpatient surgery facilities is altering capital equipment procurement authority. Independent physicians in Florida and Texas now control implant selection previously managed by hospital value analysis committees. Distributor relationships pivot toward direct surgeon engagement and inventory consignment models.
Global Extremities Market Segmentation
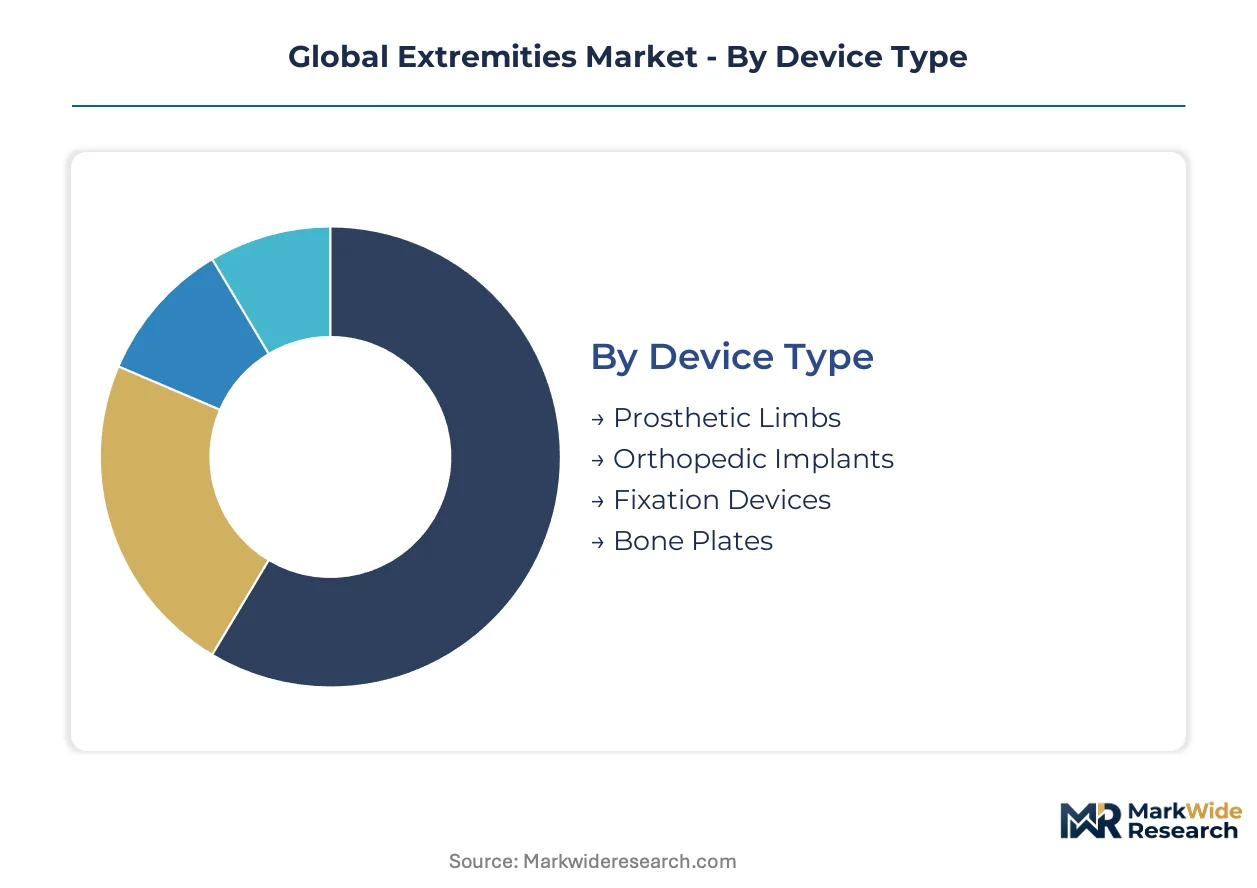
Segmentation in the Global Extremities Market reveals how procurement authority, clinical setting economics, and material science trajectories create divergent margin pools. Manufacturers configure product portfolios around these fractures to capture premium positioning in high-acuity reconstructions while defending volume in trauma fixation.
Device Type:
Cost tier separates acute intervention devices from elective reconstruction systems, with reimbursement intensity tracking invasiveness and implant permanence.
- Orthopedic Implants:Titanium alloy and cobalt-chrome constructs for shoulder and ankle arthroplasty command premium pricing through additive-manufactured porous surfaces. Demand concentrates in the United States and Germany where aging demographics drive revision procedures and CMS reimbursement parity enables outpatient migration.
- Fixation Devices:Minimally invasive plates, screws, and intramedullary nails fabricated from stainless steel or resorbable polymers serve trauma and sports medicine applications. Ambulatory surgical centers in Florida and Texas absorb expanding volumes as surgeon-owned facilities capture site-of-service economics.
- Prosthetic Limbs:Microprocessor-controlled knee and myoelectric upper extremity systems integrate sensor arrays for gait optimization. Veterans Affairs procurement in the United States and national health service tenders in Germany sustain premium segment development.
- Bone Plates:Anatomic locking plates for distal radius and calcaneal fractures employ variable angle screw technology. Trauma centers in Japan demonstrate preference for low-profile titanium designs that preserve soft tissue envelope.
Volume sits with Fixation Devices; growth tilts toward Orthopedic Implants.
Application:
Procedure acuity determines capital equipment requirements and implant permanence, with reconstruction demanding longer evidence horizons than trauma intervention.
- Trauma & Fracture:Acute fracture management employs provisional and definitive fixation across proximal humerus, distal femur, and ankle pilon patterns. Level I trauma centers in the United States generate concentrated demand for polyaxial locking systems that accommodate comminuted metaphyseal bone.
- Reconstruction:Post-traumatic and degenerative joint salvage procedures require anatomic implant systems with modular augments. German orthopedic surgeons demonstrate preference for patient-specific instrumentation that reduces operative time and blood loss in complex revision settings.
- Sports Injuries:Ligament reconstruction and osteochondral repair address ACL, rotator cuff, and ankle instability patterns. Professional sports medicine clinics in Japan drive adoption of biocomposite interference screws that accelerate return-to-play timelines.
- Arthritis:End-stage degenerative joint disease management spans fusion, resurfacing, and total joint replacement alternatives. Medicare Advantage penetration in the United States shapes site-of-service selection for elective arthroplasty procedures.
Procedure counts peak in Trauma & Fracture; margin expansion concentrates in Reconstruction.
End User:
Customer type dictates inventory models, with capital ownership shifting from consolidated purchasing to physician-directed procurement.
- Hospitals:Integrated delivery networks maintain value analysis committees that standardize implant selection across service lines. Academic medical centers in the United States generate disproportionate influence through fellowship training and technique dissemination.
- Ambulatory Surgical Centers:Surgeon-owned facilities in Texas and Florida control implant selection through direct distributor relationships. These settings favor streamlined instrument trays and consignment inventory that minimize sterilization burden and capital deployment.
- Rehabilitation Clinics:Post-acute facilities manage prosthetic fitting and orthotic adjustment for amputation and bracing patients. German statutory health insurance reimbursement frameworks determine regional service density for prosthetic provision.
- Home Care:Remote patient monitoring platforms track post-operative kinematics and wound healing for joint replacement recipients. United States value-based care contracts incentivize connected implant adoption that enables early complication detection.
Revenue concentration remains with Hospitals; patient volume migrates fastest toward Ambulatory Surgical Centers.
Material:
Supply concentration and processing complexity separate commodity metal feedstock from engineered polymer and composite systems.
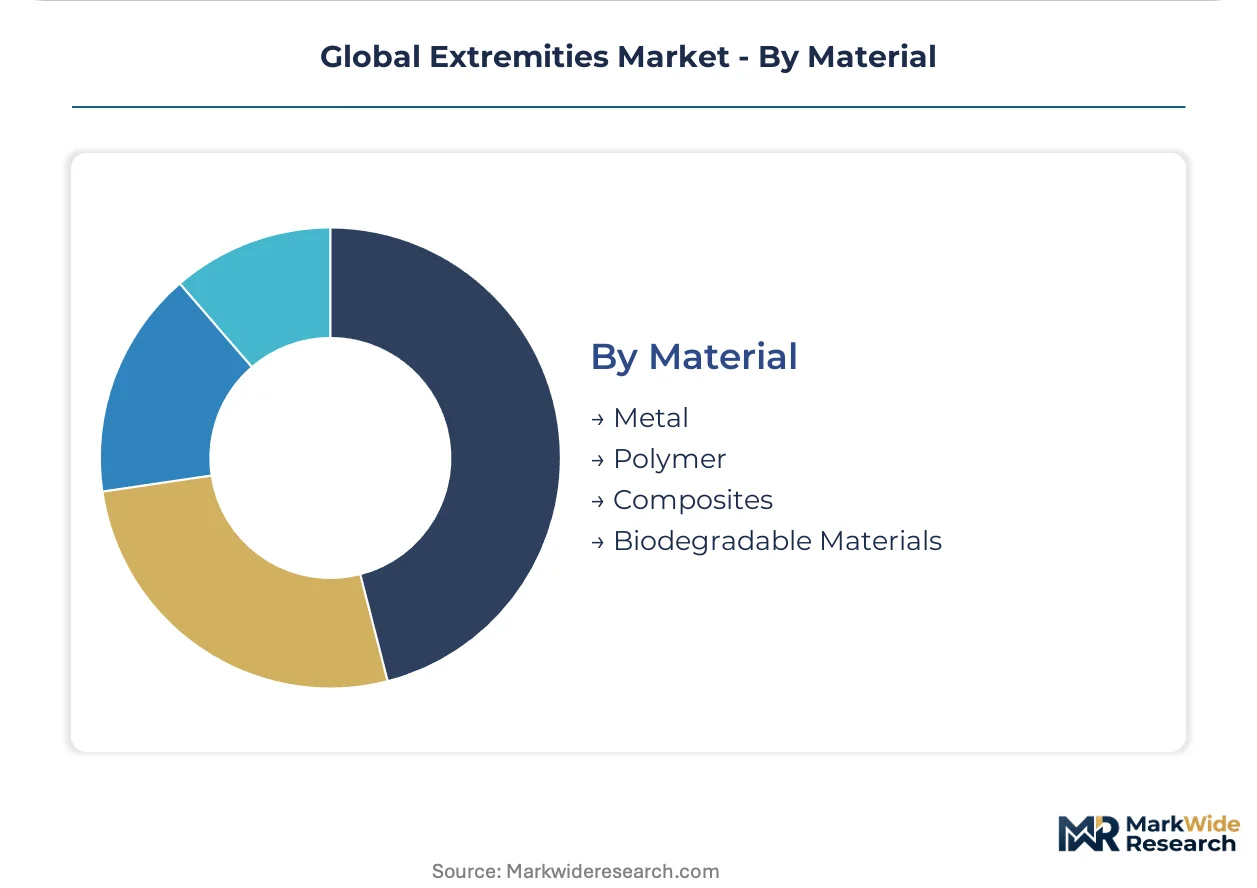
- Metal:Titanium alloys, cobalt-chrome, and stainless steel dominate load-bearing applications through fatigue resistance and osseointegration capacity. Aerospace competition for titanium sponge feedstock creates input cost volatility that compresses implant margins.
- Biodegradable Materials:PLLA and PGA polymers eliminate secondary removal surgeries in pediatric and trauma applications. Variable in-vivo resorption rates constrain adoption in conservative surgical markets that default to metallic alternatives.
- Polymer:PEEK-OPTIMA and ultra-high molecular weight polyethylene serve radiolucent fixation and bearing surface applications. Foot and ankle fusion procedures in the United States demonstrate expanding adoption of polymer-based osteotomy plates.
- Composites:Carbon-fiber reinforced polymers deliver strength-to-weight advantages in prosthetic limb sockets and orthotic bracing. Japanese manufacturers lead processing expertise for continuous fiber architectures in sports medicine applications.
Metal commands current volume; Biodegradable Materials climb the fastest as resorption predictability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of titanium alloy implants concentrates in Germany and the United States, while procedural demand expands fastest in Japan and India where aging demographics and trauma incidence reshape clinical volumes.
United States
Medicare Advantage penetration and CMS reimbursement parity for outpatient joint procedures accelerate site-of-service migration toward ambulatory surgical centers. FDA 510(k) clearance pathways maintain streamlined market access for predicate-based extremity devices. Surgeon-owned facilities in Florida and Texas now control implant selection through direct distributor relationships, bypassing traditional hospital value analysis committees.
Germany
Statutory health insurance frameworks sustain premium pricing for revision arthroplasty systems while academic medical centers in Bavaria and North Rhine-Westphalia drive adoption of patient-specific instrumentation. EU MDR technical documentation requirements and notified body capacity constraints extend certification cycles to 18-24 months. Stuttgart and Tuttlingen clusters anchor precision forging and additive manufacturing capabilities for porous titanium constructs.
Japan
PMDA regulatory harmonization with FDA standards reduces duplicate clinical evidence requirements for multinational manufacturers. The Ministry of Economy, Trade and Industry promotes domestic production of advanced biomaterials through R&D consortia. Osaka and Tokyo metropolitan areas concentrate Level I trauma centers that generate concentrated demand for low-profile titanium fixation systems.
India
Trauma fixation procedure rates remain below one-fifth of OECD benchmarks despite rising road traffic injury incidence. CDSCO streamlined 510(k)-equivalent pathways for predicate devices compress registration timelines for multinational entrants. Manufacturing clusters in Maharashtra and Gujarat assemble imported components for cost-optimized plating systems serving domestic and export markets.
Switzerland
Swissmedic maintains stringent clinical evidence standards that favor established manufacturers with robust PMCF data capture. Precision machining expertise in the Jura Arc and Zurich regions supports high-value orthopedic component production. Proximity to German and French surgical markets enables rapid feedback loops between implant designers and academic orthopedic centers.
Global Extremities Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the extremities market, with integrated manufacturers maintaining titanium forging and additive manufacturing capabilities while specialized firms outsource production to certified foundries. The vendor base separates into three tiers: diversified orthopedic conglomerates with full extremity portfolios, mid-cap trauma specialists focused on plating and nailing systems, and emerging players in bioresorbable materials. Consolidation activity concentrates in additive manufacturing technology acquisitions and digital surgery platform integrations.
Among diversified orthopedic manufacturers, Johnson & Johnson, Stryker, and Zimmer Biomet occupy positions that span implant design through post-operative monitoring services. These entities exemplify the integrated archetype that combines manufacturing scale with recurring revenue from maintenance and tracking subscriptions. Mid-cap specialists including Orthofix and Globus Medical represent focused competitors that concentrate resources on specific anatomical segments or material technologies. The competitive dynamic forces portfolio breadth against surgical specialization, with reimbursement economics in the United States and EU MDR compliance costs determining sustainable positioning.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Orthofix |
| Stryker |
| Arthrex |
| Globus Medical |
| Zimmer Biomet |
| Enovis |
| MicroPort |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 10 post-market clinical follow-up mandates gate qualified supply access and premium-tier pricing power, as manufacturers with robust PMCF data capture disproportionate share gains while marginal competitors face margin compression from extended certification cycles.
Pricing Analysis
Margin tightening in standard-tier fixation devices reflects CMS reimbursement parity pressures and ambulatory surgical center procurement consolidation. Three-tier pricing structure across premium, standard, and economy levels separates additive-manufactured porous implants from conventional forged constructs and commodity trauma plating. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification grade. Cost-down pressure on economy-tier resorbable polymers accelerates because of variable in-vivo degradation rates that complicate clinical predictability. Surgeon-owned facilities in Florida and Texas demonstrate highest price sensitivity; academic medical centers in Germany and Japan exhibit lowest sensitivity for revision arthroplasty systems.
Supply Chain Analysis
Instrument refurbishment and implant remanufacturing flows remain underdeveloped in extremities, creating stranded asset risk for distributor-held consignment inventory. Titanium sponge feedstock concentrates in Russia and China; precision forging capabilities cluster in Germany and the United States; additive manufacturing equipment sources from Germany and Japan. Raw material dependencies include titanium sponge, cobalt-chrome bar stock, and ceramic bearing blanks. Single-source ceramic bearing supply from German and French sintering facilities creates vulnerability to regional production halts. Distribution runs through distributor consignment models in surgeon-owned ambulatory centers and direct hospital contracts in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The extremities market functions as a vertical-integration race where control over additive manufacturing talent pools and EU MDR notified body relationships determines sustainable positioning.
For Market Incumbents: To counter additive manufacturing technician scarcity, secure captive electron beam melting and laser powder bed fusion capacity through apprenticeship pipelines in Stuttgart and Tuttlingen clusters. Deepen backward integration into titanium sponge offtake agreements to insulate margins from aerospace sector competition. For New Entrants and Emerging Players: Launch via CDSCO streamlined predicate pathways targeting trauma fixation penetration in Maharashtra and Gujarat manufacturing corridors. Concentrate on bioresorbable polymer applications in pediatric extremity trauma where metallic alternative removal surgeries create reimbursement arbitrage. For Investors and Strategic Acquirers: EU MDR notified body capacity bottlenecks extending to 18-24 month cycles is the leading indicator that mid-cap trauma specialists with existing PMCF databases represent prime acquisition targets. Monitor CDSCO registration acceleration rates for early signals of multinational manufacturing commitment to Indian assembly operations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Clinical Follow-up Investment | Establishes 10-15 year evidence generation infrastructure that marginal competitors cannot replicate. |
| Additive Manufacturing Talent Pipeline Development | Captures scarce electron beam melting operators before aerospace and dental sectors exhaust supply. |
| Connected Implant Platform Integration | Enables recurring software subscriptions that supplement one-time hardware margins in US value-based contracts. |
| CDSCO Registration Acceleration | Compresses market entry timelines for predicate devices in trauma fixation penetration below OECD benchmarks. |
| Patient-Specific Instrumentation Digital Workflow | Consolidates pre-operative planning into integrated systems that reduce operative time in German academic centers. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance volumes, EU MDR notified body queue lengths, and CMS site-of-service reimbursement shifts anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and additive manufacturing technicians. Secondary validation drew from FDA 510(k) databases, EUDAMED registration records, CMS Medicare cost reports, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Input-output matrices mapped titanium sponge feedstock flows through forging and additive production stages to finished implant and fixation device outputs over the projection horizon. Segmentation dimensions modeled include device type, application acuity, end-user facility category, and material technology trajectory. CAGRs derived from procedure volume elasticities against demographic aging curves and reimbursement intensity shifts. Industry-specific forecast inputs incorporated EU MDR certification cycle durations and ambulatory surgical center migration rates.
The model assumes a particular technology adoption path; alternative pathways for bioresorbable polymer degradation predictability would alter the outlook for metallic fixation displacement. Forecasts reflect assumptions regarding CMS reimbursement parity maintenance and EU MDR notified body capacity expansion. Practitioners should monitor titanium sponge price volatility and ceramic bearing supply continuity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Liposuction Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Medical Coatings Market
Medical Devices
Facial Implant Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Knee Braces Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Global Vein Finders Market
Medical Devices
Global Trauma Devices Market
Medical Devices
C-Arms Devices Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Hearing Devices 3D Printing Market