
 Surgical Gowns Market | 2026-2036
Surgical Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Gowns Market Analysis
The EU Green Deal is repositioning material sourcing across European surgical textile supply chains. Cardinal Health leverages vertical integration to secure spunbond polypropylene feedstock. Mölnlycke Health Care anchors its competitive stance through R&D intensity in breathable viral barrier technologies. Owens & Minor dominates North American distribution channels through direct sales contracts with integrated delivery networks.
Surgical gowns are personal protective garments engineered from spunbond-meltblown-spunbond laminates or reinforced cotton-polyester blends, designed to achieve AAMI Level 1 through Level 4 liquid barrier protection for operating room personnel. Disposable gowns now capture the majority of unit volume in acute care settings due to infection control protocols, while reusable gowns sustain niche demand among sustainability-focused European hospital systems. SMS material constructions lead value generation given their superior strike-through resistance compared to basic spunbond alternatives.
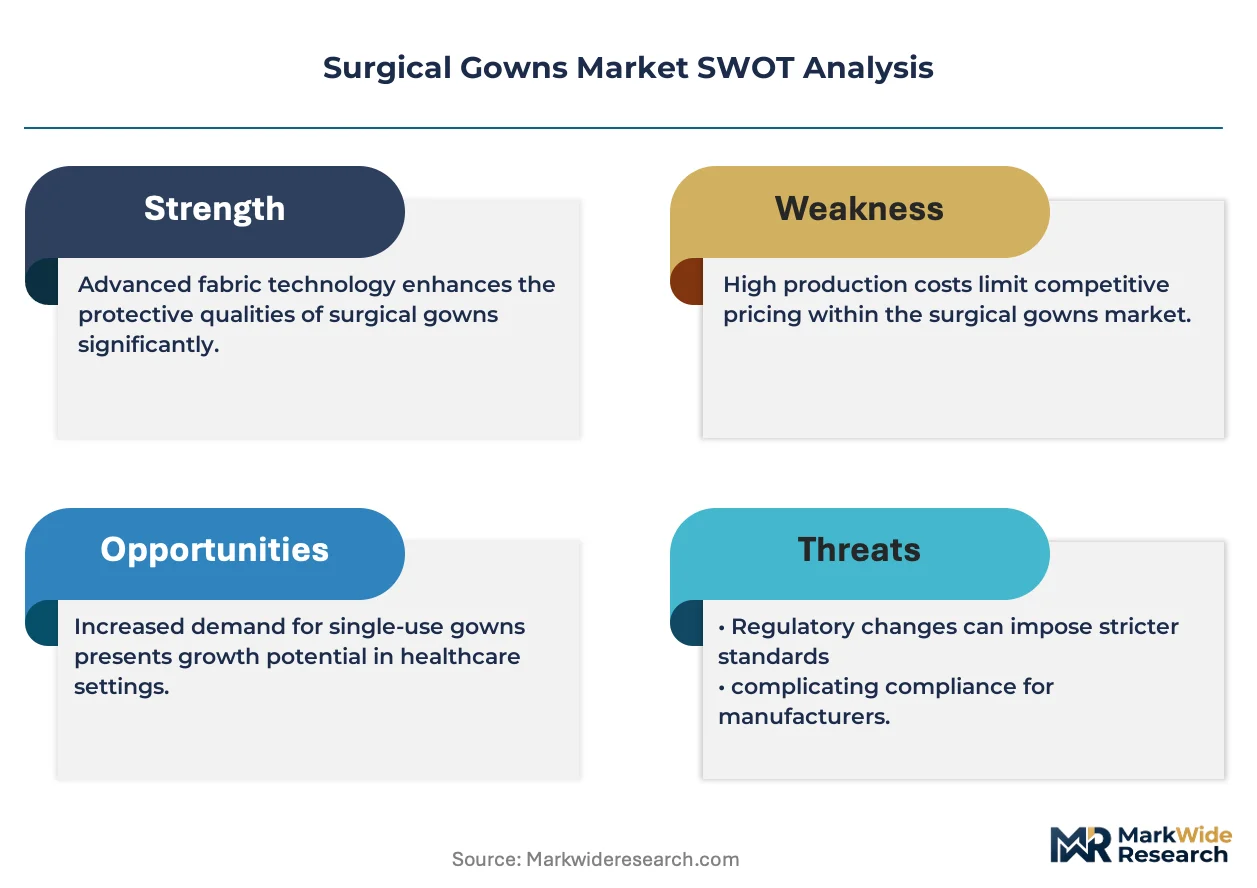
FDA liquid barrier classification rules, AAMI PB70 testing standards, and EU MDR device registration requirements collectively determine market access and pricing power for gown manufacturers. The EPA regulates antimicrobial additive claims in treated fabrics, creating additional compliance layers for product differentiation. Stakeholders must monitor evolving state-level hospital procurement mandates around domestic manufacturing content.
Market Dynamics
The FDA's updated liquid barrier performance guidance is compressing domestic manufacturer compliance timelines while EU MDR registration requirements extend market access cycles for European suppliers. This regulatory divergence is fragmenting procurement strategies across hospital systems and ambulatory surgical centers.
Growth Catalysts
- AAMI PB70 Level 4 certification:Acute care facilities in the United States are mandating maximum barrier protection for orthopedic and cardiovascular procedures, pulling demand toward reinforced SMS laminates.
- Spunbond-meltblown-spunbond technology:Material science advances in breathable viral barrier fabrics are enabling longer procedure durations without moisture buildup.
- Ambulatory surgical center expansion:Outpatient procedure volume concentration in the United States is generating dedicated gown procurement contracts separate from hospital system tenders.
Market Restraints
- Spunbond polypropylene feedstock volatility:Petrochemical input costs fluctuate with crude oil indices, compressing margin visibility for disposable gown producers.
- Single-use plastic restriction frameworks:The EU Green Deal's circular economy action plan is creating compliance friction for standard SMS disposal pathways in European markets.
- Reusable gown durability thresholds:Cotton-polyester blend performance degradation after industrial laundering limits lifecycle economics against disposable alternatives.
Strategic Opportunities
- Biodegradable barrier materials:PLA and PHA-based nonwoven research is opening sustainability-positioned product lines for EU hospital systems facing waste reduction mandates.
- Direct-to-ASC distribution channels:Bypassing integrated delivery network procurement layers allows margin capture from high-volume outpatient surgery chains.
- EPA-registered antimicrobial additives:Silver-ion and copper-infused fabric treatments create differentiation in infection-sensitive procedure segments.
Industry Challenges
- AAMI PB70 testing laboratory capacity:Certification backlog at accredited facilities extends product launch timelines for new barrier level submissions.
- Sterile packaging validation:ISO 11607 compliance for gown sterilization maintenance through distribution requires capital-intensive barrier testing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Gowns Market |
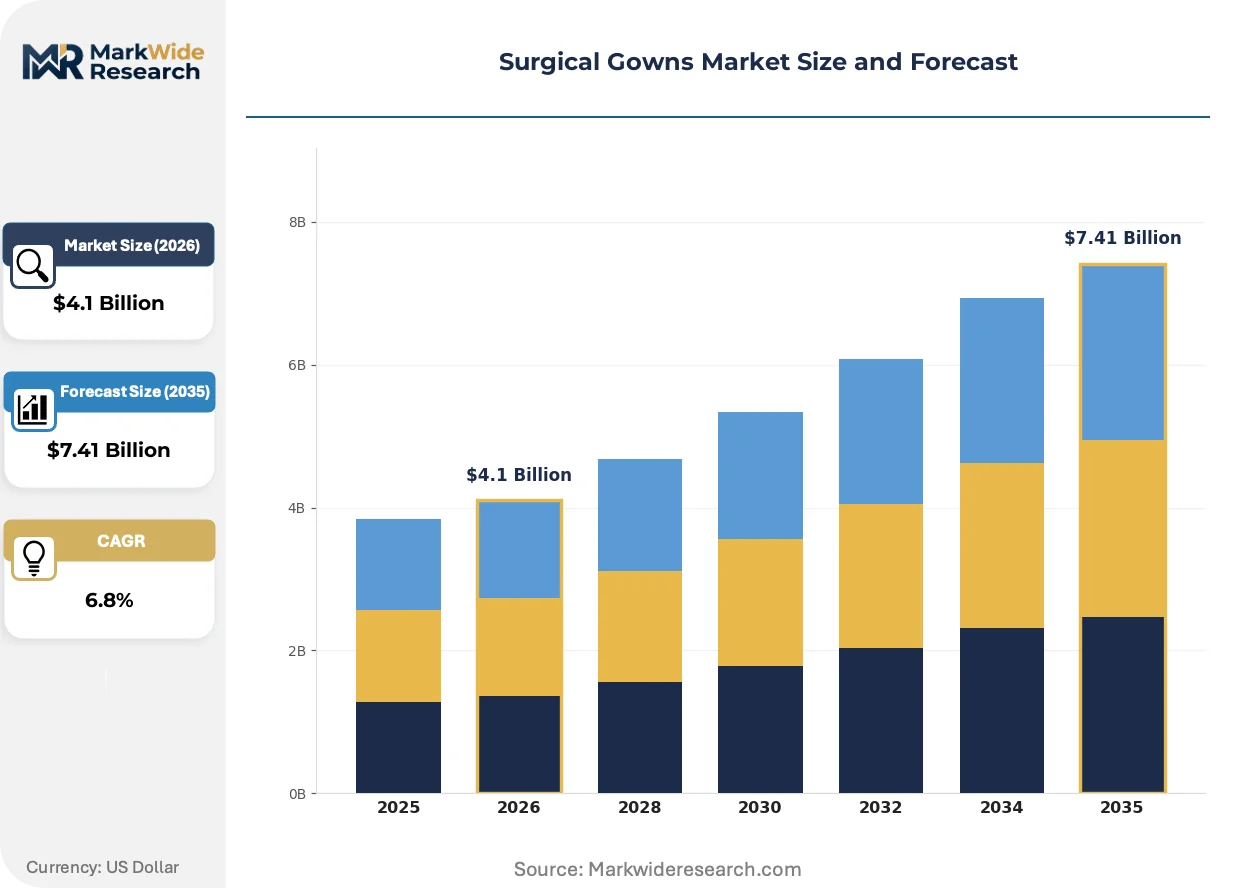
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Gowns, Disposable Gowns, Sterile Gowns, Non-Sterile Gowns Material: Cotton, Polyester, Spunbond, SMS End User: Hospitals, Clinics, Surgical Centers, Laboratories Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | 3M, Ahlstrom-Munksjö, Cardinal Health, priMED Medical Products, TIDI Products, Medline Industries, Mölnlycke Health Care, Paul Hartmann, Owens & Minor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Gowns Market Emerging Trajectories
Material science convergence with regulatory pressure is compressing product development cycles while reshaping competitive differentiation. Manufacturers now face simultaneous demands for elevated barrier performance and reduced environmental footprint.
Breathable viral barrier (BVB) technology is electrifying surgical gown engineering by integrating hydrophobic nanofiber layers with spunbond substrates. Level 4-rated BVB gowns are displacing traditional reinforced designs in United States academic medical centers. This electrifying shift is compressing pricing premiums for legacy SMS constructions while enabling procedure-specific customization.
EU MDR device classification rules are extending registration timelines for surgical textiles marketed as infection control devices. The European Medicines Agency's expanded clinical evidence requirements are forcing manufacturers to conduct biocompatibility testing beyond prior textile standards. German and French hospital procurement consortia are now requiring MDR compliance documentation in tender specifications.
Consolidated supplier contracting is compressing vendor counts within United States integrated delivery networks. Single-source gown agreements are displacing multi-vendor catalogs that previously accommodated regional preferences. This concentration is most visible in Texas and Florida health systems where procurement standardization spans 50+ facility networks.
Surgical Gowns Market Segmentation
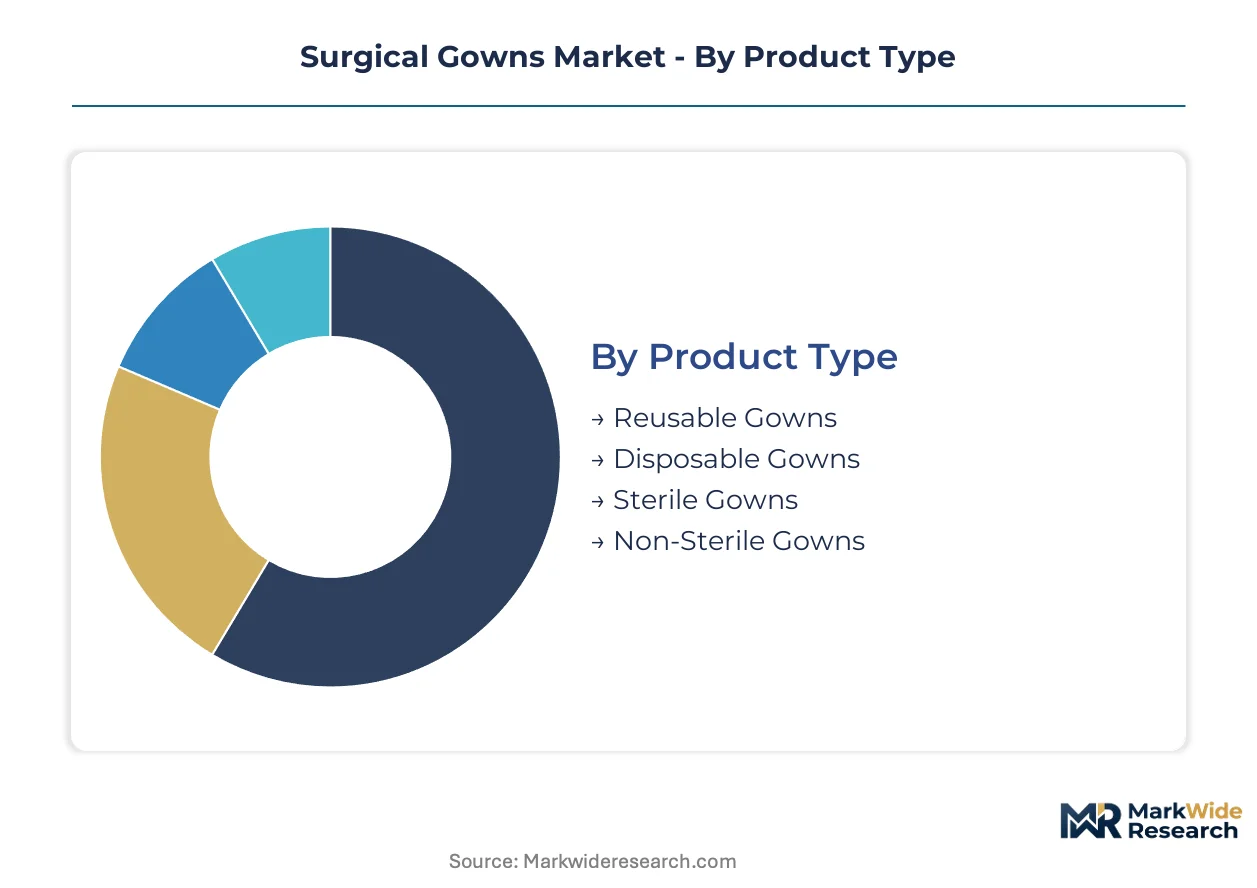
Surgical gown procurement patterns diverge sharply across use environments, with infection control protocols and sterilization requirements driving distinct material and product specifications. Understanding these segment boundaries reveals where manufacturers can capture premium positioning versus commodity volume.
Product Type:
Upgrade cycles in acute care facilities are compressing as AAMI barrier level requirements tighten, forcing hospitals to retire legacy gown inventories faster than historical replacement timelines.
- Disposable Gowns:Single-use SMS or spunbond-meltblown-spunbond laminates dominate United States hospital procurement through infection control mandates. Spunbond polypropylene feedstock volatility compresses margin visibility for producers serving high-volume integrated delivery networks.
- Reusable Gowns:Cotton-polyester blends sustain demand among sustainability-focused European hospital systems facing EU Green Deal waste reduction targets. Industrial laundering durability thresholds limit lifecycle economics against disposables in high-throughput surgical environments.
- Sterile Gowns:Pre-sterilized packaging meeting ISO 11607 standards commands premium positioning in cardiovascular and orthopedic procedure suites.
- Non-Sterile Gowns:Basic barrier protection for low-risk procedures and patient isolation protocols in secondary care settings.
Disposable gowns sit at the top of the volume ranking, with sterile gowns climbing the fastest as procedure-specific certification requirements expand.
Material:
Cost tier differentiation in raw material sourcing separates premium barrier performance from economy positioning across gown procurement contracts.
- SMS:Spunbond-meltblown-spunbond laminates achieve AAMI Level 3 and Level 4 liquid barrier ratings through hydrophobic meltblown cores. United States academic medical centers mandate SMS construction for orthopedic and cardiovascular procedures.
- Spunbond:Basic polypropylene nonwovens serve AAMI Level 1 and Level 2 applications in outpatient and minor procedure settings. Petrochemical input cost exposure compresses pricing power for standard-grade gown producers.
- Polyester:Synthetic fiber reinforcement in reusable gown blends enhances tear resistance through industrial laundering cycles.
- Cotton:Natural fiber base for traditional reusable gowns in European sustainability-mandated procurement frameworks.
SMS commands the highest value concentration per unit, with biodegradable PLA and PHA research opening sustainability-positioned alternatives.
End User:
Customer type fragmentation across care delivery settings is reshaping distribution channel requirements and contract structuring.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate supplier contracts across 50+ facility networks, compressing vendor counts. AAMI PB70 Level 4 certification mandates pull demand toward reinforced barrier technologies in academic medical centers.
- Surgical Centers:Ambulatory surgical center expansion in the United States generates dedicated procurement contracts separate from hospital system tenders. Direct-to-ASC distribution channels bypass integrated delivery network procurement layers.
- Clinics:Outpatient procedure volume concentrates in lower barrier level requirements for minor surgical interventions.
- Laboratories:Research and pathology settings drive non-sterile gown demand for chemical and biological hazard protection.
Hospitals retain the largest procurement scale, with surgical centers expanding most quickly as outpatient procedure migration accelerates.
Distribution Channel:
Supply concentration in North American distribution channels determines market access efficiency for gown manufacturers competing for integrated delivery network contracts.
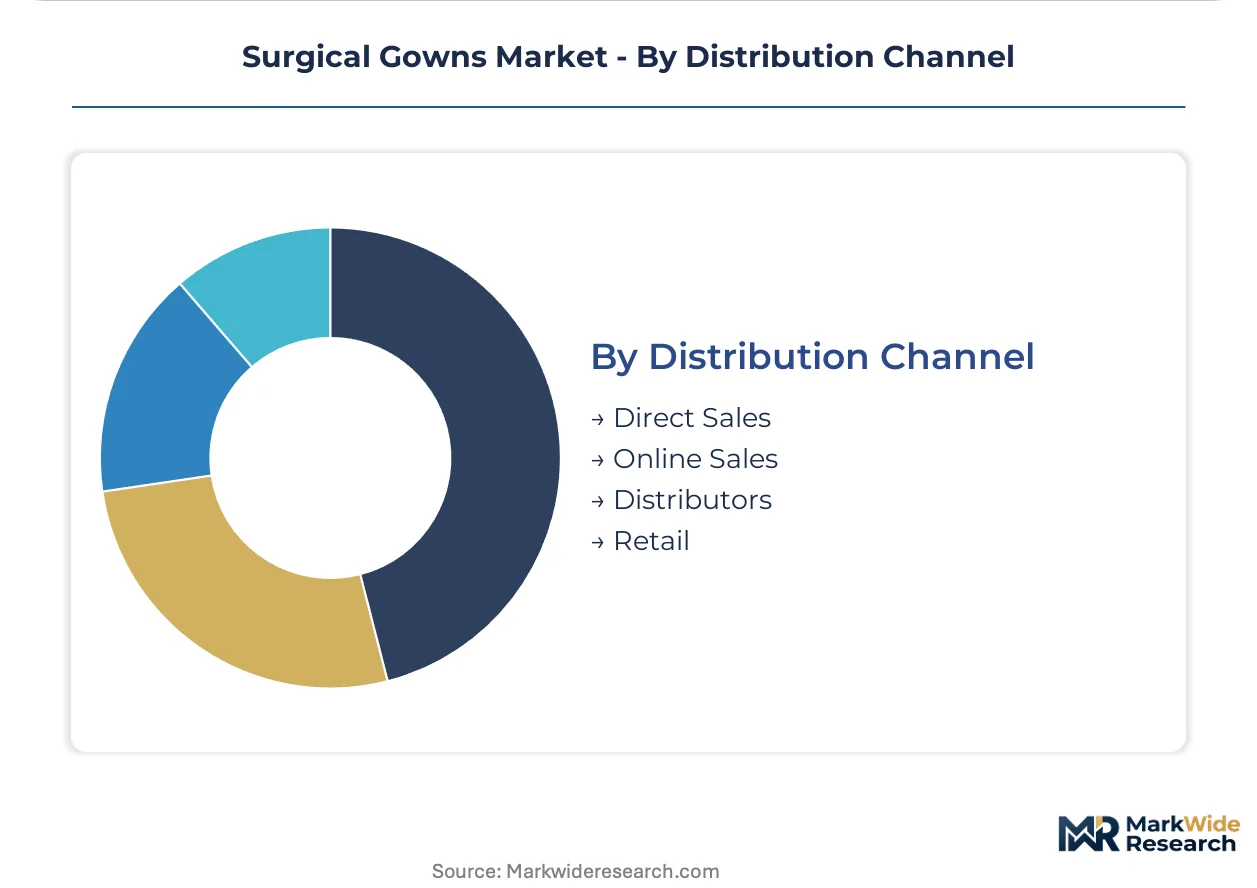
- Direct Sales:Manufacturer contracts with integrated delivery networks and large hospital systems eliminate distributor margins. Owens & Minor dominates United States direct sales channels through exclusive agreements with multi-facility health systems.
- Distributors:Third-party logistics networks serve mid-size hospital systems and independent surgical centers with regional inventory positioning. Cardinal Health leverages vertical integration to secure spunbond polypropylene feedstock for captive gown production.
- Online Sales:E-procurement platforms gain traction in ambulatory surgical center and clinic segments with standardized product specifications.
- Retail:Limited presence for consumer-grade protective gowns in veterinary and home care applications.
Direct sales capture the highest value concentration, with distributor relationships climbing fastest as mid-tier health systems seek procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical gown manufacturing originated in the United States during the mid-20th century as aseptic surgical techniques standardized. Domestic production scaled through hospital system consolidation and infection control mandates. Today procurement patterns diverge across regulatory environments and care delivery models.
United States
Integrated delivery networks in Texas and Florida consolidate supplier contracts across 50-plus facility networks. FDA liquid barrier performance guidance compresses compliance timelines for domestic manufacturers. Owens & Minor anchors North American distribution through direct sales agreements with multi-hospital systems.
Germany
Hospital procurement consortia mandate EU MDR compliance documentation in tender specifications. The European Medicines Agency extends registration timelines for surgical textiles classified as infection control devices. Bavaria-based manufacturers face biocompatibility testing requirements beyond prior textile standards.
China
Spunbond polypropylene feedstock availability supports export-oriented gown production for North American and European markets. NMPA device registration rules create parallel compliance tracks for domestic versus export production. Yangtze River Delta manufacturing clusters supply global distributors with SMS laminate constructions.
India
Domestic hospital procurement is shifting toward AAMI-equivalent barrier standards as surgical volume expands in metropolitan centers. CDSCO medical device rules create registration pathways for imported versus locally manufactured gowns. Maharashtra and Gujarat textile hubs develop spunbond nonwoven capacity for regional supply.
United Kingdom
Post-Brexit procurement frameworks diverge from EU MDR harmonization while maintaining CE marking recognition for existing suppliers. NHS England consolidation of personal protective equipment contracts compresses vendor counts across regional trusts. London and Southeast England health systems drive demand for Level 4 barrier protection in specialized surgical units.
Surgical Gowns Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier certification tiers and distribution channel control. The market structures around three concentration nodes: integrated health system direct contracts, distributor-captive production, and specialized ASC channels. Strategic archetypes include vertically integrated material suppliers, distributor-owned manufacturers, and R&D-intensive barrier technology specialists. Capacity expansion and direct-to-provider distribution partnerships constitute the dominant competitive moves.
Among North American distributors, Cardinal Health exemplifies backward integration into spunbond polypropylene feedstock. Mölnlycke Health Care occupies a position within the breathable viral barrier technology tier. Owens & Minor anchors the direct sales channel archetype through exclusive multi-facility agreements. These three represent distinct strategic postures without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| 3M |
| Ahlstrom-Munksjö |
| Cardinal Health |
| priMED Medical Products |
| TIDI Products |
| Medline Industries |
| Mölnlycke Health Care |
| Paul Hartmann |
| Owens & Minor |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's circular economy mandates gate qualified supply access and premium-tier pricing power for surgical gown manufacturers seeking European hospital procurement contracts. Compliance with waste reduction targets and MDR registration requirements separates certified suppliers from commodity competitors, compressing margin visibility for non-compliant producers while enabling sustainability-positioned pricing premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates surgical gown procurement, with AAMI PB70 certification tier and volume scale driving price differentiation. Pricing pressure stems from spunbond polypropylene feedstock volatility tied to crude oil indices, compressing margins for disposable gown producers serving high-volume integrated delivery networks. Academic medical centers demonstrate lowest price sensitivity due to mandatory Level 4 barrier requirements, while ambulatory surgical centers exhibit highest sensitivity as outpatient procedure margins tighten.
Supply Chain Analysis
Direct-to-hospital contracts and distributor-captive channels handle hyperscale demand from integrated delivery networks in Texas and Florida. Manufacturing concentrates in China, the United States, and Germany, with Yangtze River Delta clusters supplying SMS laminate exports and Bavaria-based producers serving EU MDR-compliant domestic demand. Raw material sourcing draws from petrochemical feedstocks for spunbond polypropylene, meltblown cores for barrier layers, and cotton-polyester blends for reusable alternatives. Single-source vulnerability in accredited AAMI PB70 testing laboratories extends certification backlogs, while tariff exposure on Chinese nonwoven imports threatens cost structures for North American distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical gown manufacturers can expand margins through biodegradable barrier material R&D that captures EU Green Deal procurement premiums and offsets petrochemical input volatility.
For Market Incumbents: Acquire biodegradable material R&D capabilities and AAMI PB70 testing laboratory capacity to defend against emerging PLA-based competitors and certification bottlenecks. Backward integration into spunbond polypropylene feedstock secures margin visibility against crude oil index fluctuations. Direct sales channel control through exclusive integrated delivery network agreements in Texas and Florida health systems compresses distributor dependence. For New Entrants and Emerging Players: Enter via ambulatory surgical center direct distribution channels, bypassing consolidated hospital procurement layers that favor incumbent relationships. Target outpatient surgery chains in the United States with standardized Level 2 and Level 3 gown specifications where barrier requirements are less stringent than academic medical centers. Position biodegradable SMS alternatives for EU hospital systems facing mandatory waste reduction targets. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor-owned manufacturers because integrated delivery network consolidation is compressing vendor counts and creating captive demand for scaled suppliers. Five-to-ten year viability hinges on MDR compliance infrastructure and biodegradable material pipelines. Monitor EU hospital procurement consortia tender specifications for biocompatibility testing requirements as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material R&D Investment | PLA and PHA-based nonwoven development captures EU Green Deal procurement premiums in German and French hospital systems. |
| AAMI PB70 Testing Laboratory Acquisition | Accredited certification capacity eliminates product launch delays from third-party testing backlogs. |
| Direct-to-ASC Distribution Buildout | Bypassing integrated delivery network layers captures margin from high-volume outpatient surgery chains in Texas and Florida. |
| Backward Integration into Spunbond Feedstock | Captive polypropylene supply insulates margin visibility from crude oil index volatility. |
| EU MDR Registration Infrastructure | Clinical evidence and biocompatibility documentation unlocks tender access in European hospital procurement consortia. |
Methodological Framework
Multiple input streams — hospital procurement committee interviews, GPO contracts managers, biomedical engineers, and regulatory affairs leads — were reconciled with secondary validation from FDA 510(k) filings, EU MDR registration databases, hospital procurement records, and spunbond polypropylene trade flow data. Bottom-up demand modeling across acute care facilities, ambulatory surgical centers, and clinics was cross-checked against top-down healthcare expenditure allocation estimates. Triangulation between primary stakeholder perspectives and secondary regulatory documentation ensures segmentation accuracy across barrier certification tiers.
Historical shipment volumes were cross-referenced against panel input from distribution channel partners to construct demand trajectories across the projection horizon. Segmentation modeling incorporated product type, AAMI barrier level, material construction, end-user setting, and geographic regulatory cluster dimensions. CAGRs were derived from fitted growth curves adjusted for EU MDR compliance timeline extensions and ambulatory surgical center expansion rates. Forecast inputs included outpatient procedure migration patterns, petrochemical feedstock price indices, and hospital system consolidation velocity.
The model holds under stable regulatory harmonization and continued outpatient procedure volume concentration; deviation in EU Green Deal enforcement intensity or FDA barrier guidance revisions would shift demand trajectories. Forecasts reflect documented assumptions regarding AAMI PB70 certification adoption rates and biodegradable material cost parity timelines. Periodic stress-testing of base assumptions is recommended given feedstock volatility and procurement consolidation uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Safety Lancet Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Blood Bags Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Swab Cups Market
Medical Supplies
Blood Bag Tube Sealer Market