
 South Africa Blood Glucose Monitoring Market | 2026-2036
South Africa Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Blood Glucose Monitoring Market Insights
CE marking under the EU Medical Device Regulation is reorganizing supplier qualification benchmarks for South African importers, forcing distributors to validate technical documentation before SAHPRA submission. Roche sustains broad diagnostic portfolio depth across private hospital networks. Abbott competes through FreeStyle Libre flash glucose positioning in retail pharmacy channels. Ascensia Diabetes Care specializes in conventional meter-strip ecosystems that still dominate public sector procurement.
Blood glucose monitoring encompasses electrochemical biosensor systems that measure interstitial or capillary glucose concentration through enzyme-mediated reactions, typically employing glucose oxidase or dehydrogenase chemistry on disposable test strips or implanted sensors, with primary purpose of enabling real-time glycemic management to prevent diabetic complications. Continuous glucose monitors capture premium margins among Type 1 diabetes management cases requiring intensive insulin titration, while blood glucose meters retain volume dominance across Type 2 diabetes monitoring in public health facilities where strip reimbursement governs access. Home care distribution through retail pharmacies represents the fastest-expanding channel as patients self-fund devices outside constrained hospital formularies.
SAHPRA medical device registration, ISO 15197 accuracy standards, and National Health Insurance procurement frameworks collectively determine which products reach South African patients, with SAHPRA's reliance on prior FDA or CE approvals creating dual-certification cost barriers for entrants. The South African Bureau of Standards enforces local labeling and electrical safety requirements that add compliance layers beyond international certifications. Stakeholders must track NHI benefit package negotiations, as inclusion or exclusion of continuous monitoring technologies will reshape reimbursement-driven demand across public and private care segments.
Market Dynamics
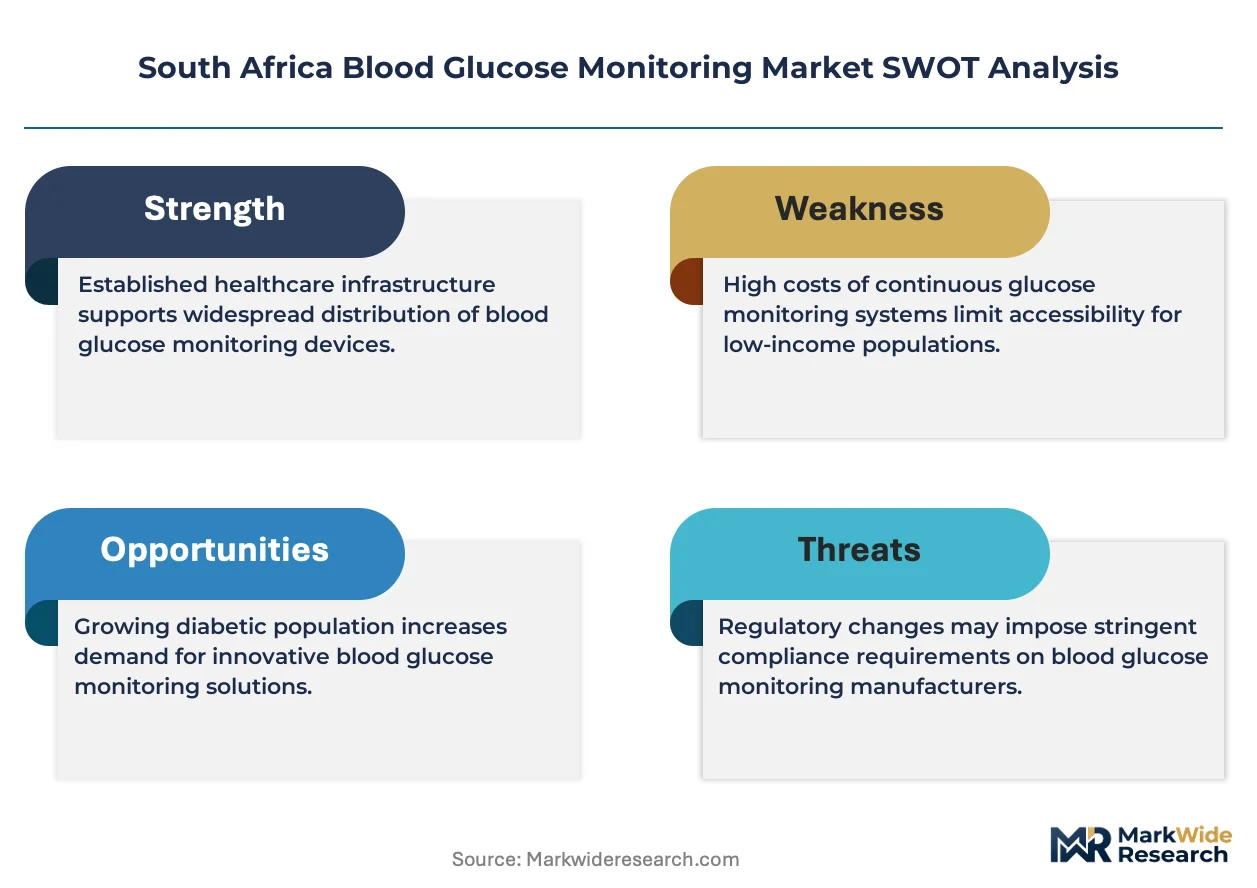
SAHPRA's reliance on prior FDA or CE approvals creates dual-certification cost barriers that filter which glucose monitoring technologies reach South African patients, concentrating supply among established multinationals with regulatory bandwidth.
Growth Catalysts
- Type 1 diabetes case expansion:Intensive insulin titration protocols in Gauteng and Western Cape tertiary hospitals drive continuous glucose monitor adoption among pediatric and young adult populations.
- Retail pharmacy channel maturation:Dis-Chem and Clicks pharmacy chains expand dedicated diabetes care sections, enabling patient self-funding outside constrained hospital formularies.
- NHI benefit package negotiations:Inclusion of blood glucose monitoring in draft National Health Insurance reimbursement schedules would unlock public sector procurement volumes.
Market Restraints
- Dual-certification cost structure:SAHPRA's requirement for prior FDA or CE marking forces manufacturers to sustain parallel regulatory filings, elevating entry costs for mid-tier suppliers.
- Test strip reimbursement volatility:Public sector strip procurement depends on provincial health department budgets, creating demand uncertainty in Eastern Cape and Limpopo.
- Continuous glucose monitor substitution ceiling:Fingerstick meters retain cost advantage for Type 2 diabetes management in resource-constrained settings.
Strategic Opportunities
- KwaZulu-Natal underpenetration:Private hospital network expansion in Durban and Pietermaritzburg creates whitespace for diabetes clinic density comparable to Gauteng.
- Telemedicine convergence:Integration of glucose data with remote consultation platforms enables rural patient monitoring beyond clinic infrastructure.
- Community health worker deployment:National Department of Health training programs position ward-based outreach teams to distribute basic meters in informal settlements.
Industry Challenges
- Biomedical engineering skill scarcity:SAHPRA-authorized local representatives with ISO 15197 technical competency remain concentrated in Johannesburg and Cape Town.
- Legacy meter data integration:Public sector facilities operate incompatible glucose data management systems across provincial health information exchanges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Blood Glucose Monitoring Market |
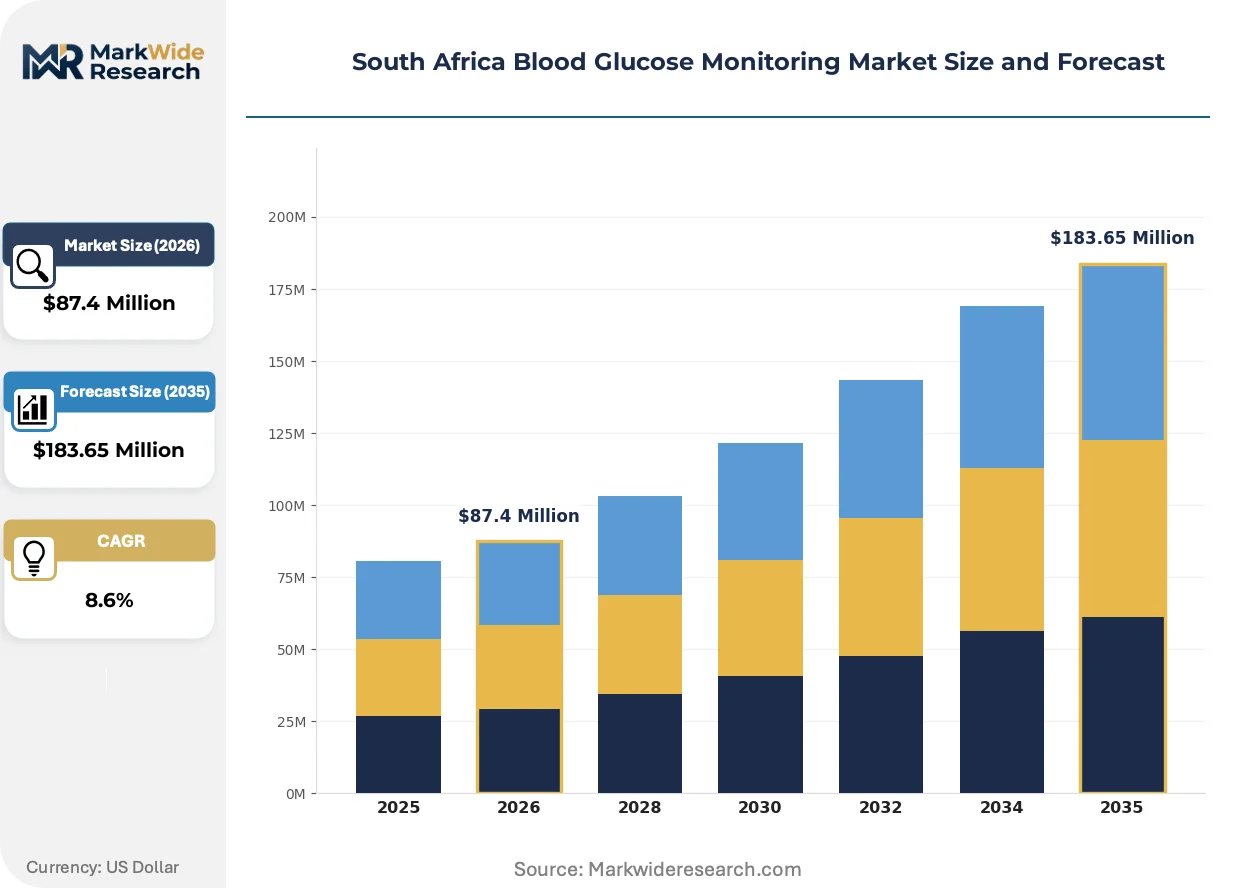
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Blood Glucose Meters, Sensor-Augmented Pumps, Flash Glucose Monitors End User: Diabetes Clinics, Research Centers, Home Care, Diagnostic Laboratories Application: Type 1 Diabetes Management, Type 2 Diabetes Monitoring, Gestational Diabetes Control, Prediabetes Assessment Distribution Channel: Pharmacies, Hospitals, Online Retailers, Medical Device Distributors |
| Companies Covered | Roche, Abbott, Ascensia Diabetes Care, Medtronic, Dexcom, LifeScan, Arkray, Senseonics, Bionime Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Blood Glucose Monitoring Market Trends and Innovations
Flash glucose sensing and connected care platforms are restructuring how South African diabetes patients and clinicians interact with glycemic data, compressing traditional monitoring workflows.
Factory-calibrated flash glucose sensors are decomposing the test strip supply chain by eliminating fingerstick confirmation requirements for treatment decisions. Private endocrinology practices in Sandton and Claremont adopt these systems for insulin-intensive patients. The technology is decomposing distributor margins on consumable strips while capturing premium device placement.
EU Medical Device Regulation CE marking reorganization is elevating technical documentation standards for South African importers. Distributors must now validate quality management systems before SAHPRA submission. Continuous glucose monitor categories face extended review timelines as SAHPRA assesses MDR-compliant clinical evidence packages.
Self-funded device procurement through retail pharmacies is displacing hospital-based dispensing for stable Type 2 diabetes patients. Medical aid scheme gap cover products increasingly exclude chronic device benefits, pushing patients toward pharmacy direct purchase. This pattern concentrates in Western Cape and Gauteng urban centers with highest medical scheme penetration.
South Africa Blood Glucose Monitoring Market Segmentation
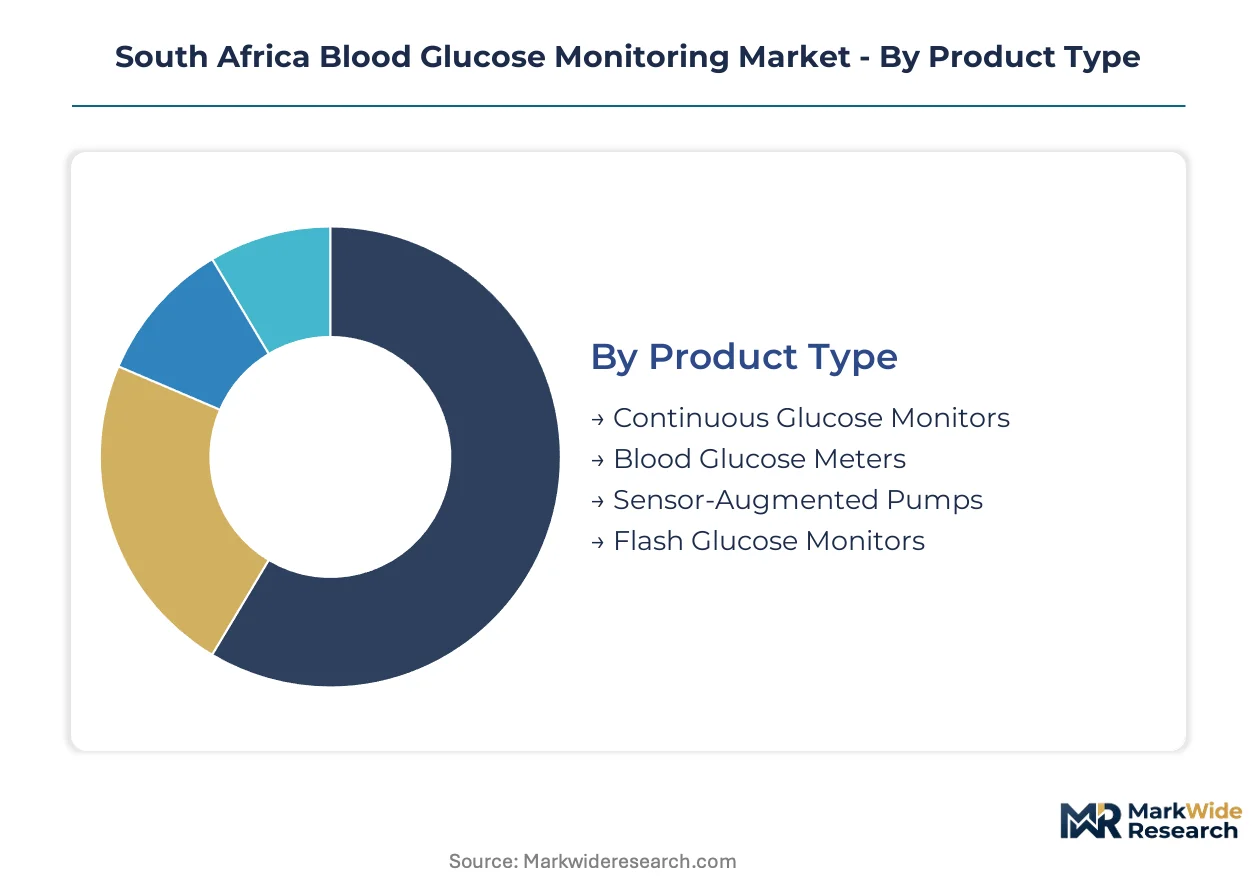
Segmentation in South Africa's blood glucose monitoring landscape reveals how regulatory pathways, reimbursement tiers, and care delivery models fragment demand across product categories and access channels. Understanding these divisions exposes where SAHPRA certification burdens, provincial procurement budgets, and patient self-funding patterns create divergent commercial opportunities.
Product Type:
SAHPRA's reliance on prior FDA or CE marking creates tiered entry barriers that concentrate supply among multinationals with regulatory bandwidth for continuous monitoring technologies, while conventional meters face lighter documentation requirements.
- Continuous Glucose Monitors:Implantable sensors with factory-calibrated algorithms transmit interstitial glucose readings every 1-5 minutes to receivers or smartphones. Demand concentrates in Gauteng private endocrinology practices where medical scheme coverage supports intensive insulin titration for Type 1 pediatric cases, though SAHPRA's extended review timelines for software-as-medical-device components constrain new entrant pipeline.
- Blood Glucose Meters:Electrochemical biosensor handheld devices utilizing glucose oxidase chemistry on disposable strips remain the procurement backbone of Eastern Cape and Limpopo public health facilities. Provincial health department tender volatility and strip reimbursement caps limit manufacturer margin stability despite volume dominance.
- Sensor-Augmented Pumps:Integrated insulin delivery systems combining continuous sensing with automated basal adjustment. KwaZulu-Natal private hospital networks in Durban represent emerging placement sites as diabetes clinic density expands.
- Flash Glucose Monitors:Factory-calibrated sensors eliminating fingerstick confirmation for treatment decisions. Western Cape retail pharmacy channels through Dis-Chem and Clicks drive patient self-funded adoption outside constrained hospital formularies.
Established volume favors blood glucose meters; emerging adoption favors flash glucose monitors.
End User:
Care setting determines device sophistication requirements and procurement authority, with hospital-based dispensing giving way to patient-directed pharmacy purchasing in stable chronic cases.
- Home Care:Self-monitoring patients utilizing retail pharmacy channels and direct online procurement. Western Cape and Gauteng urban centers with highest medical scheme penetration drive device self-funding as gap cover products increasingly exclude chronic benefits.
- Diabetes Clinics:Specialized outpatient facilities in Sandton, Claremont, and Durban providing integrated glycemic management. These sites generate concentrated continuous monitor prescriptions for insulin-intensive populations.
- Diagnostic Laboratories:Centralized testing facilities processing HbA1c and point-of-care glucose validation. Quality control protocols reference ISO 15197 accuracy standards for meter-strip system verification.
- Research Centers:Academic institutions conducting clinical validation studies for SAHPRA submission packages. Stellenbosch and Witwatersrand university hospitals generate localized demand for research-grade monitoring equipment.
Procurement authority concentrates in diabetes clinics; patient autonomy is expanding most quickly in home care.
Application:
Disease severity and insulin dependency dictate monitoring intensity, with reimbursement frameworks aligning technology access to clinical risk stratification.
- Type 1 Diabetes Management:Absolute insulin deficiency requiring intensive glucose monitoring for dosing safety. Tertiary hospitals in Gauteng and Western Cape drive continuous monitor adoption among pediatric and young adult populations.
- Type 2 Diabetes Monitoring:Progressive insulin resistance managed through lifestyle and pharmacological intervention. Public sector facilities across all nine provinces deploy conventional meter-strip systems where provincial budgets govern strip access.
- Gestational Diabetes Control:Glucose intolerance during pregnancy requiring temporary monitoring protocols. Maternity units in private hospital networks utilize flash systems for short-term glycemic surveillance.
- Prediabetes Assessment:Impaired glucose tolerance screening for progression prevention. Workplace wellness programs and primary care clinics generate intermittent testing demand.
Reimbursement depth favors Type 1 diabetes management; case volume expansion favors Type 2 diabetes monitoring.
Distribution Channel:
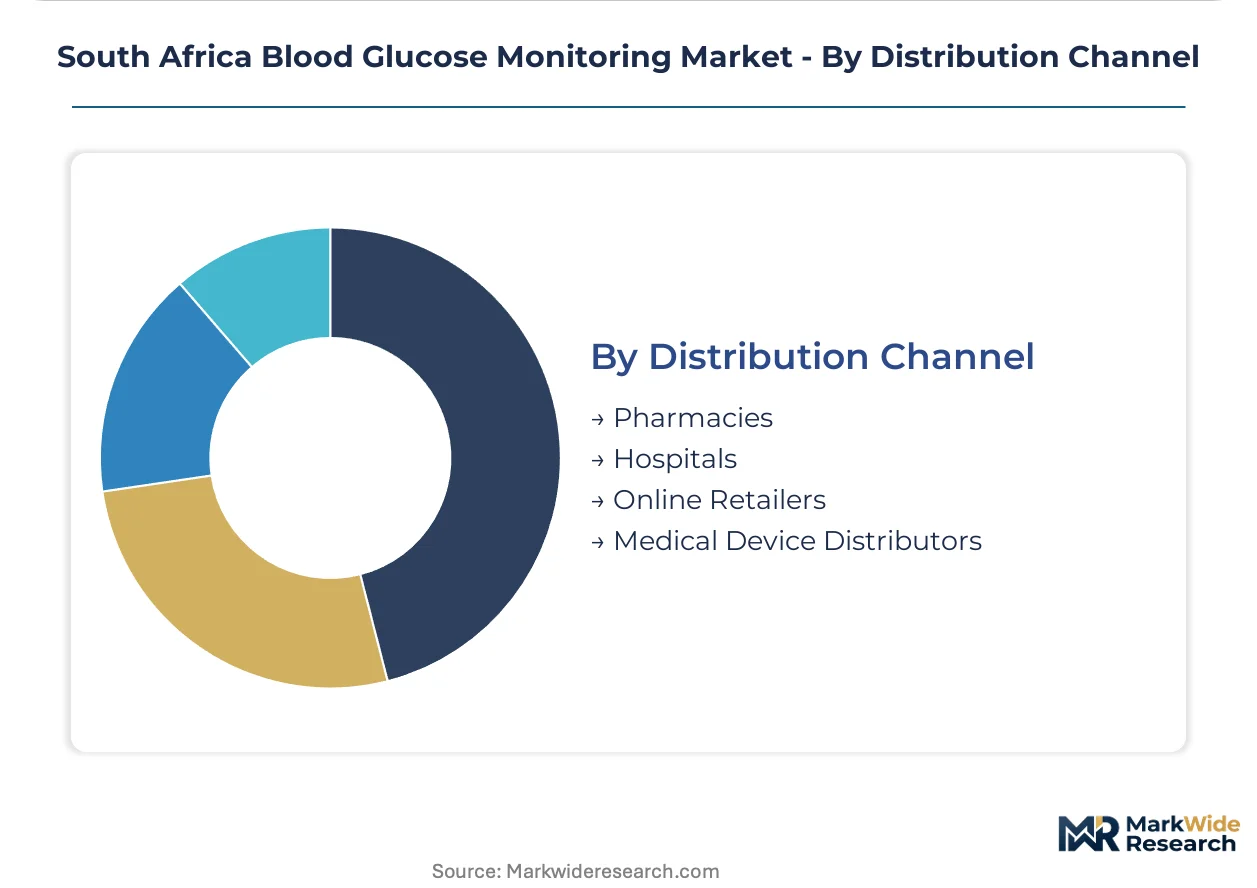
Channel selection reflects patient payment capability and device complexity, with retail displacement accelerating in medically insured urban populations.
- Pharmacies:Dis-Chem and Clicks chains expanding dedicated diabetes care sections enable direct patient purchase. This channel captures self-funded flash glucose monitor growth in Gauteng and Western Cape.
- Hospitals:Tertiary facility dispensing for acute decompensation and new diagnosis cases. Constrained formularies limit continuous monitor placement to insured inpatients.
- Medical Device Distributors:SAHPRA-authorized local representatives with ISO 15197 technical competency concentrated in Johannesburg and Cape Town. These intermediaries validate EU MDR documentation before regulatory submission.
- Online Retailers:Direct-to-consumer platforms serving remote and price-sensitive segments. KwaZulu-Natal and Eastern Cape rural access gaps drive e-commerce adoption for strip resupply.
Institutional procurement favors medical device distributors; patient convenience is climbing fastest through pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Durban-Gauteng freight corridor and Cape Town container terminal infrastructure underpin South Africa's medical device distribution networks, enabling glucose monitoring supply chains to reach provincial health facilities across all nine provinces.
Gauteng
Private hospital networks in Sandton and Pretoria drive continuous glucose monitor adoption among Type 1 pediatric populations. The National Health Insurance pilot programs in Johannesburg public clinics test meter-strip procurement frameworks. The Tshwane biomedical engineering cluster hosts SAHPRA-authorized technical representatives with ISO 15197 competency.
Western Cape
Medical scheme penetration in Cape Town and Claremont accelerates patient self-funding of flash glucose monitors through retail pharmacy channels. The provincial health department's chronic disease management protocols influence public sector strip reimbursement rates. The Stellenbosch university hospital research complex generates clinical validation studies for regulatory submission packages.
KwaZulu-Natal
Private hospital expansion in Durban and Pietermaritzburg creates whitespace for diabetes clinic density growth comparable to Gauteng. The provincial tender system for public sector glucose meters operates on constrained budgets with irregular procurement cycles. The Richards Bay logistics corridor facilitates medical device import distribution to underserved rural districts.
Eastern Cape
Resource-constrained public health facilities in Mthatha and Port Elizabeth rely on conventional meter-strip systems with volatile provincial procurement budgets. The Nelson Mandela Bay metropolitan health district experiments with community health worker meter distribution in informal settlements. The Coega industrial development zone attracts medical device assembly investment for regional supply.
Limpopo
Rural healthcare access gaps in Polokwane and surrounding districts drive demand for basic glucose meters through ward-based outreach teams. The provincial health department's chronic medication distribution program incorporates intermittent glucose testing protocols. The Musina border post corridor enables parallel import channels for strip resupply from neighboring markets.
South Africa Blood Glucose Monitoring Market Competitive Landscape
Listed diagnostic multinationals compete with private device specialists across regulatory bandwidth and channel access dimensions. Market structure concentrates supply among established players with dual FDA-CE certification capacity for SAHPRA submission. Three archetypes dominate: integrated diagnostic conglomerates with broad hospital network contracts; flash glucose specialists leveraging retail pharmacy penetration; and conventional meter-strip suppliers anchoring public sector tenders. Competitive moves center on distributor technical documentation validation and provincial tender pre-qualification.
Within the integrated diagnostic tier, Roche and Abbott exemplify multinational scale advantages in navigating SAHPRA's extended review timelines for software-as-medical-device components. Ascensia Diabetes Care occupies a position representing conventional meter-strip ecosystem specialists that retain volume dominance in Eastern Cape and Limpopo public procurement. These three anchors illustrate how regulatory bandwidth and channel specialization stratify competitive positioning across South Africa's bifurcated private-public healthcare landscape.
| Leading Market Players |
|---|
| Roche |
| Abbott |
| Ascensia Diabetes Care |
| Medtronic |
| Dexcom |
| LifeScan |
| Arkray |
| Senseonics |
| Bionime Corporation |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay provincial tender structures lock Eastern Cape and Limpopo health departments into multi-year strip supply contracts that anchor price visibility while constraining flexibility for flash glucose monitor adoption. SAHPRA dual-certification requirements compound supplier qualification costs, concentrating procurement leverage among Roche, Abbott, and Ascensia with established FDA-CE documentation bandwidth.
Pricing Analysis
Volume-discount tiering structures stratify South Africa's glucose monitoring landscape across three performance levels: premium continuous monitors for Type 1 intensive insulin cases, standard flash systems for self-funded urban patients, and economy meter-strip bundles for public sector tenders. Price differentiation hinges on SAHPRA software-as-medical-device review intensity and ISO 15197 accuracy certification tier. Cost compression in economy meter-strip tiers intensifies as provincial health departments consolidate tender volumes. Public sector procurement committees exhibit highest price sensitivity, while private endocrinology practices in Sandton and Claremont prioritize clinical performance over unit economics.
Supply Chain Analysis
Durban-Gauteng freight corridor chokepoints concentrate medical device import flows through Johannesburg and Cape Town distribution hubs, extending lead times to Eastern Cape and Limpopo rural facilities. Manufacturing draws from Ireland, Germany, and Malaysia for sensor substrates and enzyme chemistry components. Single-source vulnerability persists for factory-calibrated flash sensor membranes, with SAHPRA extended review timelines amplifying stockout risk for new entrant products. Distribution feeds from SAHPRA-authorized local representatives through Dis-Chem and Clicks pharmacy chains, with hospital formularies retaining direct procurement for acute cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's bifurcated private-public healthcare structure fragments glucose monitoring demand across incompatible procurement systems, creating niche entry points for specialists targeting reimbursement gaps and regulatory fast-tracks.
For Market Incumbents: Secure provincial tender pre-qualification status in KwaZulu-Natal before private hospital network expansion accelerates diabetes clinic density comparable to Gauteng. Anchor distributor technical documentation validation capacity in Tshwane to exploit SAHPRA's reliance on prior FDA or CE marking, while building backward integration into enzyme chemistry supply to offset flash sensor substitution pressure on strip volumes. For New Entrants and Emerging Players: CE marking fast-track pathways under EU MDR reorganization enable SAHPRA submission packages with compressed review timelines for software-as-medical-device components. Target KwaZulu-Natal private hospital whitespace in Durban and Pietermaritzburg where diabetes clinic density remains below Gauteng benchmarks. Deploy telemedicine-integrated glucose data platforms to bypass biomedical engineering skill scarcity concentrated in Johannesburg and Cape Town. For Investors and Strategic Acquirers: Capital is best deployed toward SAHPRA-authorized local representatives with ISO 15197 technical competency and established distributor relationships across Dis-Chem and Clicks pharmacy networks. Long-term viability hinges on positioning for National Health Insurance benefit package inclusion negotiations, where continuous monitoring technology coverage decisions will reshape reimbursement-driven demand. Watch NHI procurement framework finalization as the inflection signal for public sector volume unlock.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Software-as-Medical-Device Submission | Accelerates regulatory pathways for connected glucose platforms in Gauteng private networks. |
| CE Marking Pathway Under EU MDR | Validates technical documentation for South African importer qualification before SAHPRA review. |
| Hospital System Partnership | Secures formulary placement for continuous monitors in Western Cape tertiary facilities. |
| Software Companion Development | Enables telemedicine convergence for rural patient monitoring beyond clinic infrastructure. |
| Reimbursement Strategy | Positions products for NHI benefit package inclusion across provincial health departments. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committees, SAHPRA regulatory affairs specialists, and pharmacy chain category managers, and refined through secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, provincial health department tender records, and medical scheme benefit schedule disclosures. Bottom-up demand modeling across product type, end user, application, and distribution channel dimensions was triangulated with top-down market sizing.
Variance-decomposition framing isolated contribution effects from Type 1 case expansion, retail pharmacy channel maturation, and NHI benefit package negotiation scenarios across the analysis window. Segmentation dimensions modeled include product technology tier, care setting procurement authority, disease severity stratum, and patient payment capability. CAGRs were derived from installed base growth rates and replacement cycle dynamics, with flash glucose monitor substitution elasticity and strip reimbursement volatility as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable SAHPRA review timelines and provincial health budget allocations; material deviation in NHI implementation pace or medical scheme gap cover exclusions would warrant model refresh. Practitioners should keep alternative scenarios live as reimbursement framework negotiations and EU MDR documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market