
 Global Disposable Syringes Market | 2026-2036
Global Disposable Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Syringes Market Foresight
The capital-intensity gap between integrated polymer processors and assembly-only manufacturers is collapsing as automated molding and needle-attachment lines compress break-even thresholds. Becton Dickinson leverages captive resin compounding and in-house needle grinding to sustain margin structure across safety syringe portfolios. Terumo Corporation anchors its position through regional manufacturing hubs that navigate procurement localization mandates in Southeast Asia and Latin America.
Disposable syringes are single-use medical devices comprising a polypropylene barrel, elastomer plunger tip, and stainless steel cannula, manufactured through injection molding of medical-grade polymers followed by siliconization and sterile packaging; they deliver measured parenteral doses while eliminating cross-contamination risk. Safety syringes lead value generation as needlestick prevention laws harden across industrialized markets, while insulin syringes compete on unit cost in retail pharmacy channels. Blister pack formats dominate hospital procurement specifications, though pouch configurations gain traction in home healthcare logistics where space and disposal weight matter.
FDA quality system regulation and EU MDR conformity requirements shape product development cycles, with ISO 7864 dimensional standards governing Luer taper interoperability across jurisdictions. The WHO prequalification pathway governs access to multilateral vaccine procurement, creating tiered compliance burdens for manufacturers serving Gavi-funded programs. Stakeholders must monitor polymer supply chain concentration and evolving extended producer responsibility frameworks for plastic medical waste.
Market Dynamics
Automated needle-attachment lines and robotic siliconization systems are compressing capital barriers between integrated polymer processors and assembly-only manufacturers, collapsing historical margin structures that protected regional specialists.
Growth Catalysts
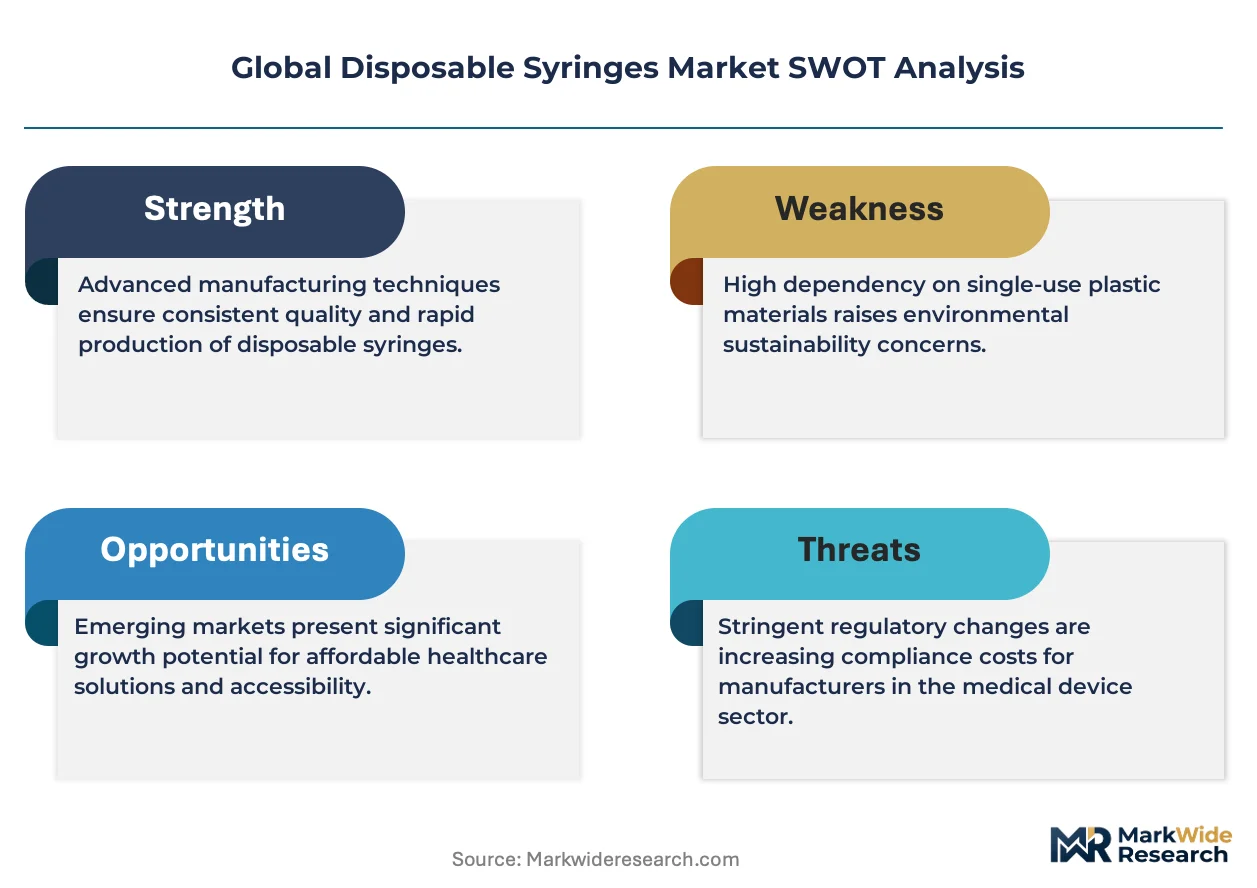
- EU MDR sterility mandates:The EU Medical Device Regulation tightens traceability requirements for Class IIa devices, forcing hospital procurement departments toward pre-qualified suppliers with validated sterilization cycles.
- Home healthcare expansion:Chronic disease management programs in India and China are scaling insulin self-administration, pulling safety-engineered syringes into retail pharmacy channels previously dominated by conventional units.
- Polymer compounding automation:In-house resin formulation capabilities now break even at lower volumes, allowing mid-scale manufacturers to match the material consistency of integrated giants.
Market Restraints
- Medical-grade polypropylene concentration:Three Southeast Asian resin compounders supply over sixty percent of specialized syringe-grade polymer, creating input vulnerability during petrochemical feedstock disruptions.
- Needlestick prevention law fragmentation:OSHA bloodborne pathogen standards in the United States lack harmonization with EU MDR safety-device definitions, forcing dual certification runs for cross-Atlantic suppliers.
- Glass prefillable substitution:Biologic drug manufacturers are migrating sensitive formulations to glass syringe systems, eroding polymer barrel demand in high-value therapeutic categories.
Strategic Opportunities
- Brazilian immunization localization:ANVISA procurement rules now mandate domestic final assembly for government vaccine programs, creating greenfield manufacturing incentives for safety syringe producers.
- WHO prequalification acceleration:Gavi-funded vaccine campaigns are fast-tracking PQ pathway approvals, opening multilateral procurement access for manufacturers with documented cold-chain stability data.
- Connected injection convergence:Bluetooth-enabled dose-capture modules are integrating with disposable safety syringes, enabling adherence monitoring for diabetes management payers.
Industry Challenges
- Siliconization technician scarcity:Uniform lubricant deposition requires specialized coating engineers, yet vocational programs in polymer surface treatment remain underdeveloped across manufacturing hubs.
- ISO 7864 dimensional recertification:Luer taper interoperability testing demands six-month validation cycles, compressing product refresh timelines against faster-moving regional competitors.
- Legacy ERP integration friction:UDI serialization mandates require real-time production data capture, forcing mid-tier manufacturers to replace analog track-and-trace systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Syringes Market |
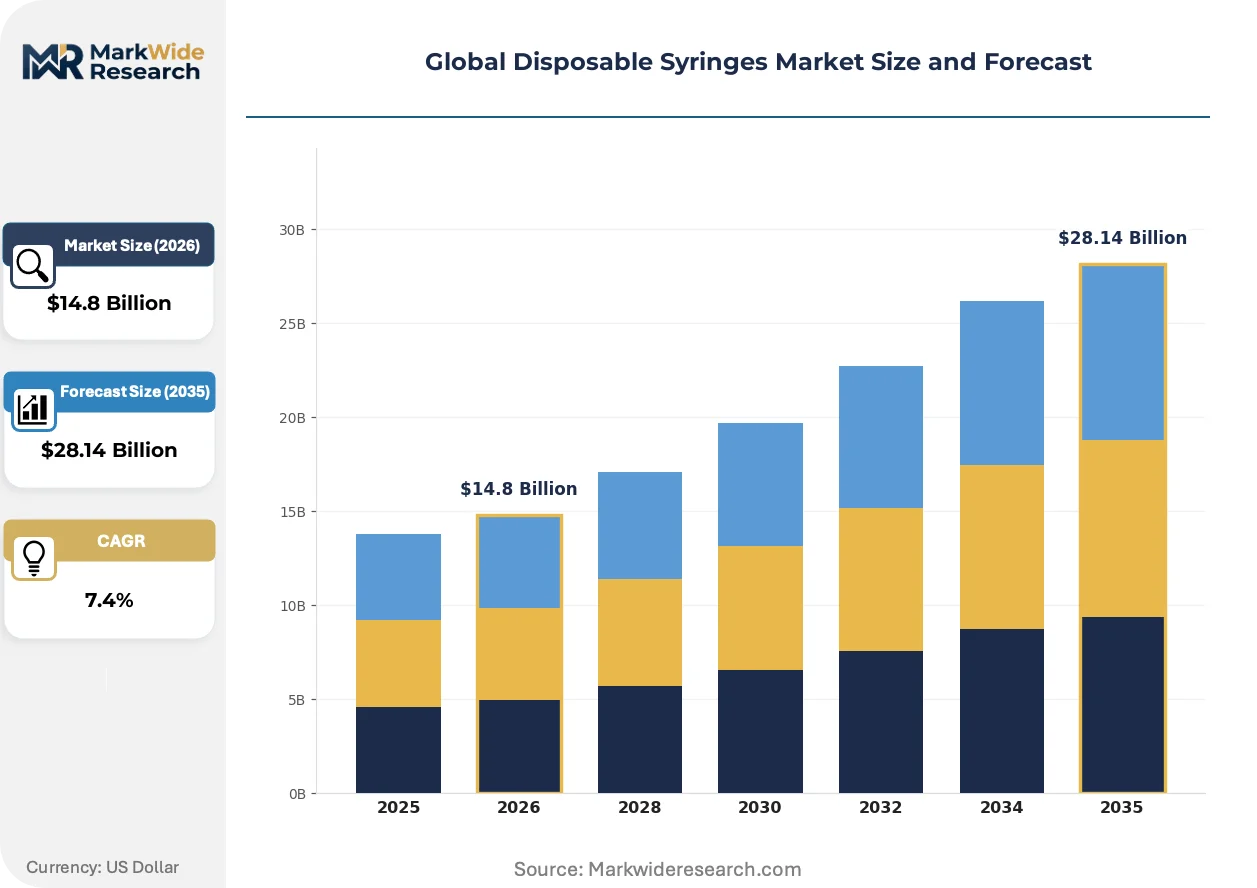
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.14 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Insulin Syringes, Tuberculin Syringes, Safety Syringes, Needle Tip Syringes Application: Vaccination, Blood Sampling, Drug Delivery, Insulin Administration, Intravenous Therapy End User: Hospitals, Clinics, Diagnostic Laboratories, Home Healthcare Providers, Research Institutes Packaging Type: Blister Packs, Pouches, Bulk Packaging, Sterile Packs, Boxed Sets |
| Companies Covered | Becton Dickinson, Terumo Corporation, Nipro Corporation, Cardinal Health, Hindustan Syringes & Medical Devices Ltd, B. Braun SE, Medtronic, Retractable Technologies, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Syringes Market Shifts & Advancements
Device miniaturization, regulatory serialization mandates, and channel disintermediation are converging to reshape how disposable syringes are specified, procured, and delivered across care settings.
Micro-dose safety syringes is miniaturizing barrel volumes to 0.3mL and 0.5mL specifications for precision biologic delivery. Pediatric endocrinology departments and fertility clinics are standardizing these formats for hormone therapies requiring tight titration. The technology is miniaturizing residual volume losses, enabling cost recovery on high-value drug formulations that previously tolerated significant dead-space waste.
REACH SVHC disclosure requirements now mandate full material composition transparency for polymer additives and lubricants entering EU member states. Compounders must document phthalate-free plunger formulations and alternative plasticizer chemistries through extended safety data sheets. Safety syringe portfolios with pre-validated SVHC compliance are capturing preference share among German and French hospital purchasing consortia.
Direct-to-clinic distribution platforms are bypassing traditional medical-surgical distributors for high-volume safety syringe contracts. Large integrated delivery networks in Texas and California are consolidating needlestick-prevention purchasing through dedicated supply chain subsidiaries. This channel compression is most visible in United States acute care settings where GPO affiliation is weakening against self-distribution models.
Global Disposable Syringes Market Segmentation
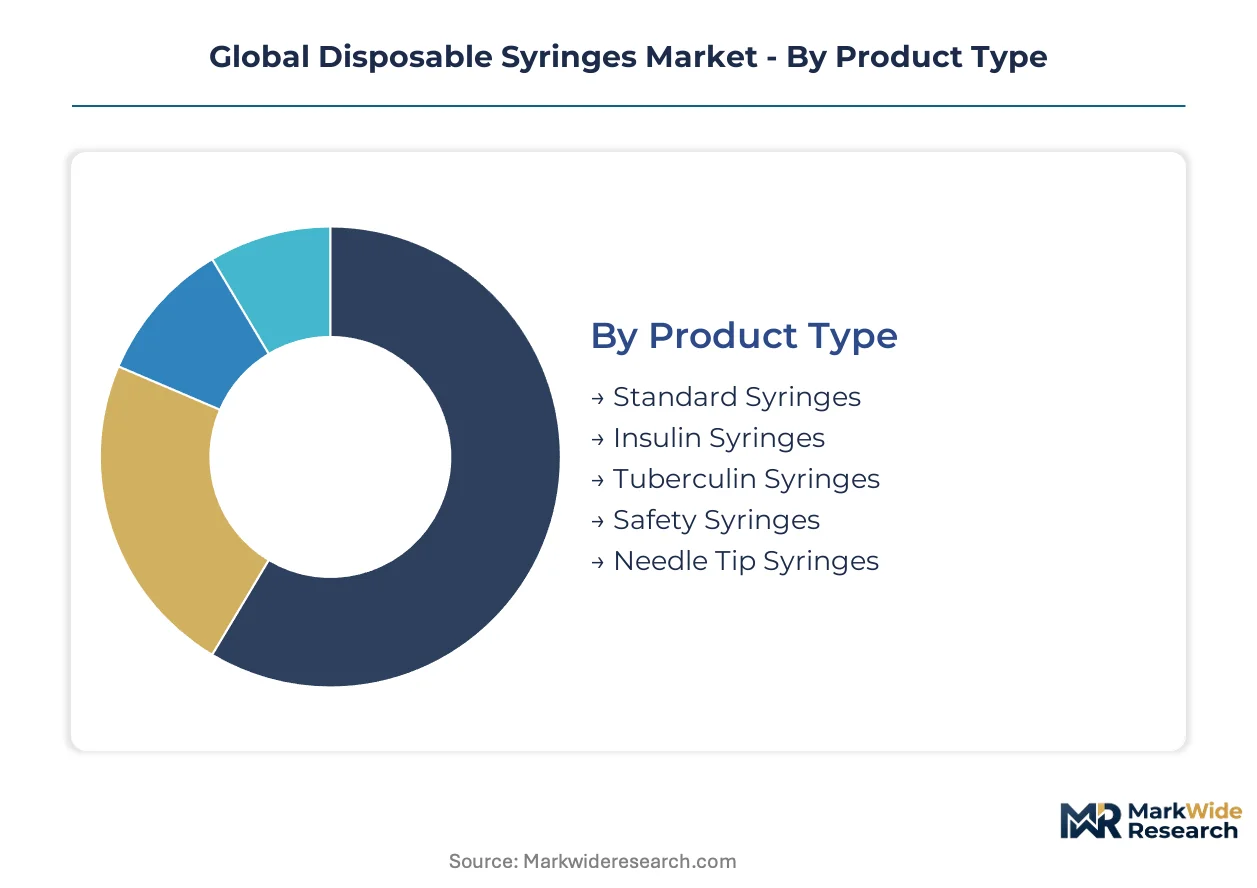
Disposable syringe manufacturers configure product portfolios across four intersecting dimensions to capture divergent margin pools. Safety-engineered devices command premium pricing in regulated markets while standard units compete on unit economics in high-volume procurement channels.
Product Type:
Safety syringes generate the highest per-unit margins, driven by needlestick prevention mandates in the United States and EU member states.
- Safety Syringes:These devices incorporate retractable needles or protective shields that activate after injection. Hospital procurement departments in Germany and France now require documented OSHA-equivalent compliance for all sharps purchases, consolidating demand toward pre-validated suppliers.
- Insulin Syringes:Ultra-fine 31-gauge needles and unit-specific barrel markings characterize these devices. Retail pharmacy chains in India and China are expanding self-administration programs for Type 2 diabetes management, pulling volume from institutional channels into consumer-direct distribution.
- Standard Syringes:Conventional Luer-lock designs dominate emerging market immunization campaigns where cost minimization overrides safety features.
- Tuberculin Syringes:1mL graduated barrels with fine needles serve Mantoux testing and allergy immunotherapy protocols.
- Needle Tip Syringes:Pre-attached needle configurations reduce assembly steps in high-throughput vaccination settings.
The dominant share belongs to standard syringes, while safety syringes are closing the gap fastest.
Application:
Volume concentration varies sharply by therapeutic category, with vaccination programs representing the largest unit demand while drug delivery captures value through specialized configurations.
- Vaccination:Mass immunization campaigns require high-output disposable units with minimal dead space. Gavi-funded programs in Nigeria and Indonesia specify WHO-prequalified suppliers with documented cold-chain stability.
- Drug Delivery:Biologic formulations demand siliconized barrels and elastomer plungers compatible with sensitive protein structures. Oncology infusion centers in the United States are standardizing safety-engineered systems for chemotherapy administration.
- Insulin Administration:Home-based diabetes management drives demand for compact, discreet disposal systems.
- Blood Sampling:Diagnostic laboratories specify low-residual-volume designs for accurate hematology panels.
- Intravenous Therapy:Hospital emergency departments require rapid-flush capabilities and Luer compatibility across fluid administration sets.
Vaccination maintains volume leadership, though drug delivery applications are expanding most quickly through biologic therapy adoption.
End User:
Procurement sophistication diverges sharply between institutional buyers with validated supplier lists and retail channels competing on shelf price.
- Hospitals:Integrated delivery networks in Texas and California consolidate purchasing through dedicated supply chain subsidiaries, bypassing traditional medical-surgical distributors for safety syringe contracts.
- Home Healthcare Providers:Space-constrained logistics favor pouch packaging configurations and compact disposal systems. Medicare reimbursement patterns in the United States influence device selection for chronic disease management.
- Clinics:Federally qualified health centers balance cost constraints against OSHA bloodborne pathogen compliance requirements.
- Diagnostic Laboratories:High-throughput processing demands standardized Luer taper interoperability across instrument platforms.
- Research Institutes:Preclinical studies require documented lot traceability and material composition transparency under REACH SVHC disclosure rules.
Hospitals retain the largest procurement scale, while home healthcare providers are gaining share fastest through chronic disease program expansion.
Packaging Type:
Packaging configuration directly determines distribution economics and sterility assurance levels across care settings.
- Blister Packs:Individual unit presentation with Tyvek-lidded thermoformed trays dominates hospital sterile processing departments. German and French purchasing consortia specify peel-force testing protocols for aseptic presentation.
- Pouches:Flexible film packaging reduces shipping cube and disposal weight for home healthcare logistics. Last-mile distributors in Brazil and Mexico favor this format for remote clinic replenishment.
- Sterile Packs:Pre-sterilized procedure kits combine syringes with ancillary items for emergency department efficiency.
- Boxed Sets:Multi-unit cartons serve high-volume vaccination sites with centralized inventory management.
- Bulk Packaging:Unsterilized component shipments support in-house assembly operations for regional manufacturers.
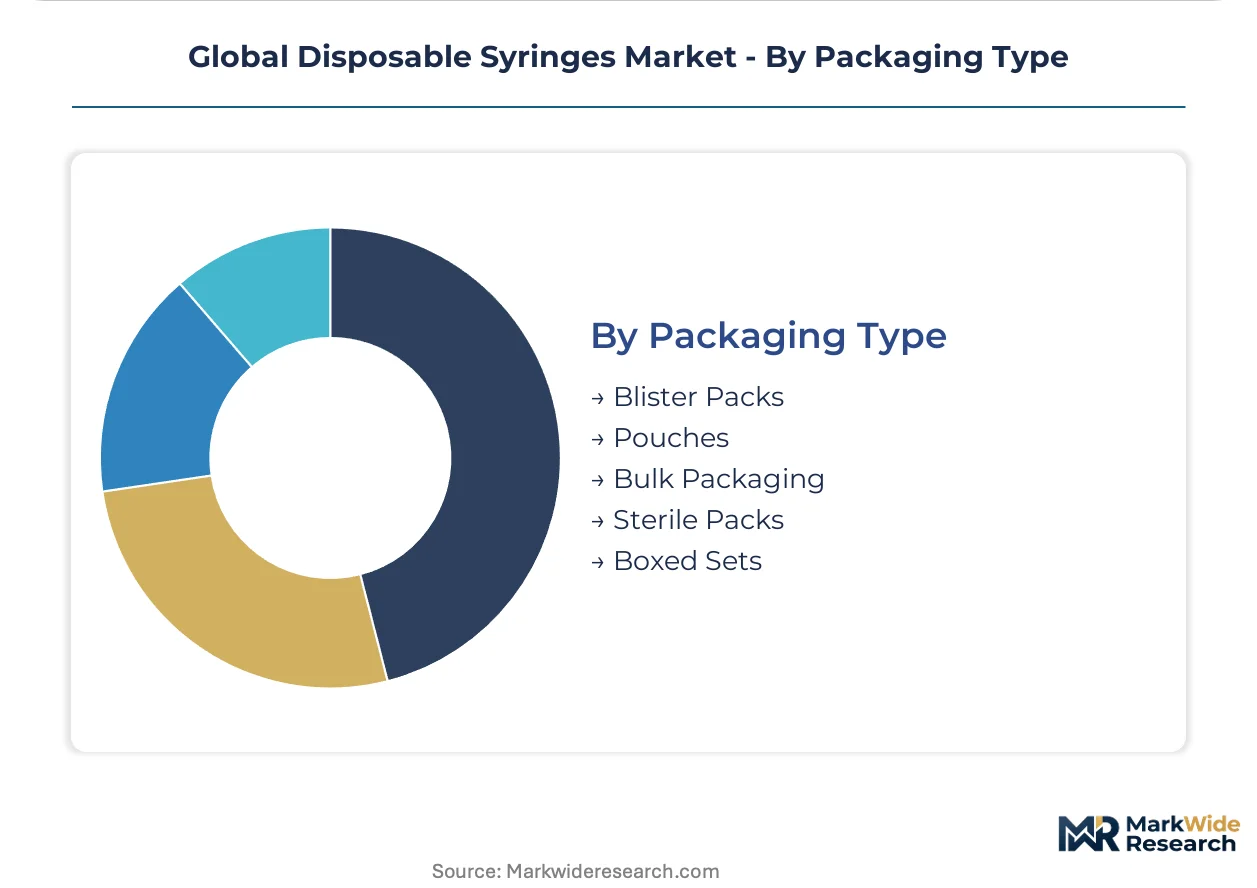
Blister packs hold the leading position, though pouches are climbing the fastest through home healthcare channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and France sits at a 40-60% premium over procurement benchmarks in India and Indonesia, reflecting divergent regulatory compliance burdens and safety-device mandates. This asymmetry fragments manufacturing investment across three distinct cost-quality tiers. Procurement localization rules in Brazil and Southeast Asia are redrawing supply chain geography.
United States
Hospital procurement consolidation through integrated delivery networks in Texas and California is compressing distributor margins. OSHA bloodborne pathogen standards mandate safety-engineered devices in acute care settings. The Boston-Cambridge medical device cluster anchors R&D for connected injection technologies.
Germany
Hospital purchasing consortia in North Rhine-Westphalia and Bavaria specify REACH SVHC-compliant formulations for all polymer components. EU MDR Class IIa traceability requirements extend sterilization validation cycles. The Freiburg medical technology corridor hosts specialized siliconization service providers.
China
Chronic disease management programs in Shanghai and Guangzhou are scaling insulin self-administration through retail pharmacy channels. NMPA quality system regulations align with ISO 13485 for export-oriented manufacturers. The Yangtze River Delta concentrates automated needle-attachment line production.
Brazil
ANVISA procurement mandates now require domestic final assembly for government immunization campaigns. Federal vaccine distribution programs in São Paulo and Minas Gerais create demand for high-volume safety syringe contracts. The Campinas medical device cluster attracts greenfield manufacturing investment.
India
Universal immunization expansion in Maharashtra and Gujarat drives unit demand for conventional Luer-lock designs. CDSCO medical device rules are harmonizing with WHO prequalification standards for Gavi-funded access. The Faridabad-Ballabgarh corridor hosts polymer compounding operations serving regional assemblers.
Global Disposable Syringes Market Competitive Landscape
Concentration sits with integrated polymer processors that command sterilization validation capabilities and captive resin supply. The vendor base stratifies across three tiers: multinational device conglomerates with full vertical control, regional specialists leveraging procurement localization, and contract manufacturers serving private-label programs. Two competitive moves dominate: backward integration into medical-grade polymer compounding, and geographic expansion through regional hub architectures that satisfy domestic content rules.
Within the integrated multinational tier, Becton Dickinson and Terumo Corporation exemplify archetypes of resin-captive processing and regional hub deployment respectively. Hindustan Syringes & Medical Devices Ltd. occupies a position among emerging market volume leaders. Retractable Technologies represents the safety-device specialization vector. These anchors illustrate how competitive positioning fragments across compliance depth, cost scale, and feature differentiation rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Becton Dickinson |
| Terumo Corporation |
| Nipro Corporation |
| Cardinal Health |
| Hindustan Syringes & Medical Devices Ltd |
| B. Braun SE |
| Medtronic |
| Retractable Technologies |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Glass prefillable syringe substitution for biologic formulations is simultaneously redrawing raw material sourcing maps and compressing polymer barrel pricing power in high-value therapeutic categories. This input displacement forces polypropylene compounders to defend position through REACH SVHC-compliant formulation investments while safety-engineered devices capture residual margin in regulated channels.
Pricing Analysis
The customization-premium spread between configured-to-order safety syringes and standard Luer-lock units spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EU MDR traceability certification and OSHA-equivalent needlestick compliance as dual validation tiers. Cost compression in standard immunization syringes is intensifying because Brazilian and Indian procurement localization mandates force margin absorption at the assembly tier. Retail pharmacy channels in emerging markets exhibit highest price sensitivity, while German hospital purchasing consortia prioritize pre-validated SVHC compliance over unit cost.
Supply Chain Analysis
Thailand, Malaysia, and South Korea anchor medical-grade polypropylene compounding for specialized syringe-grade resin. The supply chain draws from petrochemical feedstock streams, stainless steel cannula wire drawing operations, and elastomer plunger formulation specialists. Single-source vulnerability concentrates in Southeast Asian resin compounders supplying the majority of syringe-grade polymer. Distribution runs through regional medical-surgical distributors, direct-to-clinic platforms, and GPO-affiliated procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable syringes market is recovering from pandemic-era demand volatility as routine immunization schedules normalize and chronic disease management programs expand. Inventory destocking cycles in hospital procurement are reversing, pulling safety-engineered devices back into forward-buying patterns.
For Market Incumbents: Consolidate sterilization validation capabilities and captive resin compounding to defend margin structure against mid-scale automated manufacturers. Backward integration into medical-grade polypropylene formulation protects input cost stability when petrochemical feedstock prices fluctuate. Priority investments should target WHO prequalification documentation for Gavi-funded program access.
For New Entrants and Emerging Players: Lead with connected injection convergence opportunities in diabetes management, where Bluetooth-enabled dose-capture modules command adherence-monitoring premiums. Brazilian ANVISA localization mandates create the most penetrable greenfield manufacturing entry point for safety syringe assembly. Go-to-market positioning should emphasize documented cold-chain stability data for multilateral procurement qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists possessing validated EU MDR Class IIa compliance but lacking global distribution reach. Long-term viability hinges on extended producer responsibility frameworks for plastic medical waste creating regulatory moats. The signal to watch is polymer supply chain concentration disruption triggering procurement preference shifts toward vertically integrated manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Traceability validation opens German and French hospital procurement consortia to pre-qualified suppliers. |
| Backward Integration into Polymer Compounding | In-house resin formulation breaks even at lower volumes, matching integrated giant material consistency. |
| WHO Prequalification Pathway Completion | PQ documentation enables Gavi-funded vaccine campaign access for manufacturers with cold-chain data. |
| Connected Injection Technology Partnership | Bluetooth dose-capture module integration enables adherence monitoring for diabetes management payers. |
| Brazilian Greenfield Manufacturing Deployment | ANVISA domestic final assembly mandates create captive supply positioning for federal immunization programs. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and polymer compounding specialists anchors the qualitative findings. Secondary validation draws from FDA quality system regulation filings, EU MDR conformity documentation, WHO prequalification databases, and hospital procurement contract disclosures. Bottom-up demand modeling across vaccination, drug delivery, and insulin administration applications triangulates with top-down polymer consumption estimates.
Sensitivity analysis on petrochemical feedstock price volatility, regulatory compliance timeline extensions, and procurement localization mandate adoption shapes the analytical framework. Segmentation dimensions span product type, application, end user, and packaging format across the projection horizon. CAGRs derive from installed base attrition rates, immunization program expansion schedules, and chronic disease prevalence trajectories. Industry-specific inputs include siliconization capacity utilization and Luer taper interoperability recertification cycle durations.
Forecasts assume regulatory continuity in FDA quality system regulation and EU MDR enforcement regimes; material policy shifts would require re-modeling sterilization validation burden and traceability cost structures. Specific risks include REACH SVHC disclosure requirement expansion, glass prefillable substitution acceleration in biologics, and needlestick prevention law harmonization failure between OSHA and EU MDR definitions. Recalibration cycles align with material shifts in polymer supply concentration and extended producer responsibility framework implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Breast Shells Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
UAE Hospital Supplies Market