
 Disposable Bed Sheets Market | 2026-2036
Disposable Bed Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Bed Sheets Market Analysis
Medical-grade SMS fabric specifications are redrawing competitive boundaries in disposable bed sheets. Cardinal Health leverages captive nonwoven manufacturing to sustain cost advantages across hospital group purchasing contracts. Medline Industries anchors North American distribution through direct-to-facility logistics networks that bypass traditional medical supply wholesalers. Paul Hartmann AG competes on European regulatory compliance depth, with CE-marked product lines that navigate EUDAMED registration requirements for Class I medical devices.
Disposable bed sheets are single-use textile barriers engineered from spunbond polypropylene, meltblown filtration layers, or polyethylene laminates, manufactured through thermal bonding or ultrasonic sealing to achieve fluid resistance and bacterial filtration efficiency. Their primary commercial purpose is to eliminate cross-contamination vectors in patient care environments where laundry sterilization costs exceed per-unit disposable economics. Flat sheets dominate hospital procurement volumes due to standardized sizing and minimal fitting labor, while fitted sheets command premium positioning in ambulatory surgical centers where stretcher turnover speed determines throughput. Pillow cases and mattress protectors represent faster-growing margin pools as infection control protocols extend beyond primary contact surfaces to secondary vectors.
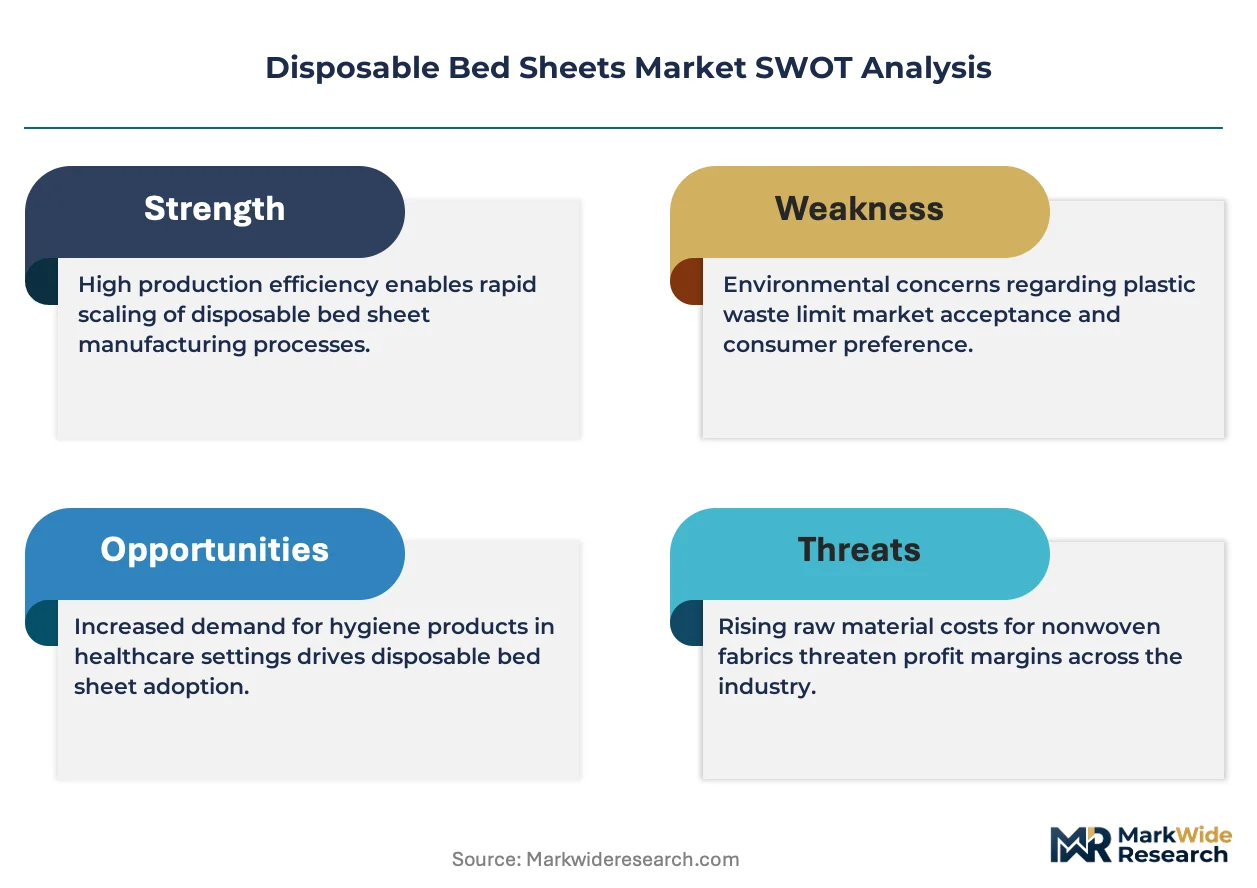
FDA 510(k) clearance pathways and EPA antimicrobial claims frameworks shape product development cycles and market access timelines for U.S. manufacturers. The EU Medical Device Regulation (MDR) reclassification of certain barrier textiles intensifies conformity assessment burdens for European market entrants. ISO 10993 biocompatibility testing and AAMI PB70 liquid barrier standards function as de facto global benchmarks that purchasers reference in tender specifications regardless of geography. Stakeholders must monitor how CMS inpatient prospective payment system adjustments and EU Green Deal circular economy mandates create conflicting incentives between disposable hygiene and reusable textile sustainability targets.
Market Dynamics
SMS fabric technology is consolidating manufacturing economics around thermal-bonded nonwovens, compressing woven cotton's addressable market as hospital infection protocols harden against reusable textile vectors.
Growth Catalysts
- CMS Reimbursement Rules:United States ambulatory surgical centers now receive favorable inpatient prospective payment system adjustments for single-use linens, accelerating procurement velocity over reusable alternatives.
- EUDAMED Registration Requirements:The EU Medical Device Regulation's Class I reclassification of barrier textiles creates compliance-driven replacement cycles as facilities retire non-conforming inventory.
- Spunbond Polypropylene:Thermal bonding advances in meltblown filtration layers are reducing per-unit fluid resistance costs below steam-sterilization breakeven thresholds.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene resin prices fluctuate with crude oil indices, compressing margin stability for manufacturers lacking backward integration into polymer production.
- EU Green Deal Circular Economy Mandates:The European Commission's single-use plastic reduction targets impose conflicting compliance burdens against infection control protocols favoring disposability.
- Reusable Textile Service Contracts:Industrial laundry operators in Germany and France are bundling linen management with equipment leasing, creating switching-cost barriers for disposable conversion.
Strategic Opportunities
- India's PLI Scheme for Technical Textiles:Production-linked incentives for nonwoven manufacturing are attracting capacity investments serving domestic hospital infrastructure expansion.
- Home Healthcare Settings:Post-acute care migration from institutional to residential environments creates demand for retail-packaged disposable bedding kits.
- Ultrasonic Sealing Convergence with Antimicrobial Additives:EPA-registered silver-ion integration during thermal bonding opens premium positioning against standard SMS without separate finishing steps.
Industry Challenges
- FDA 510(k) Clearance Timelines:Fluid barrier claims requiring predicate device substantiation extend product launch windows by 12-18 months for novel fabric constructions.
- ISO 10993 Biocompatibility Testing Backlogs:Contract laboratory capacity constraints in cytotoxicity and sensitization assays delay certification for skin-contact pillow case innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Bed Sheets Market |
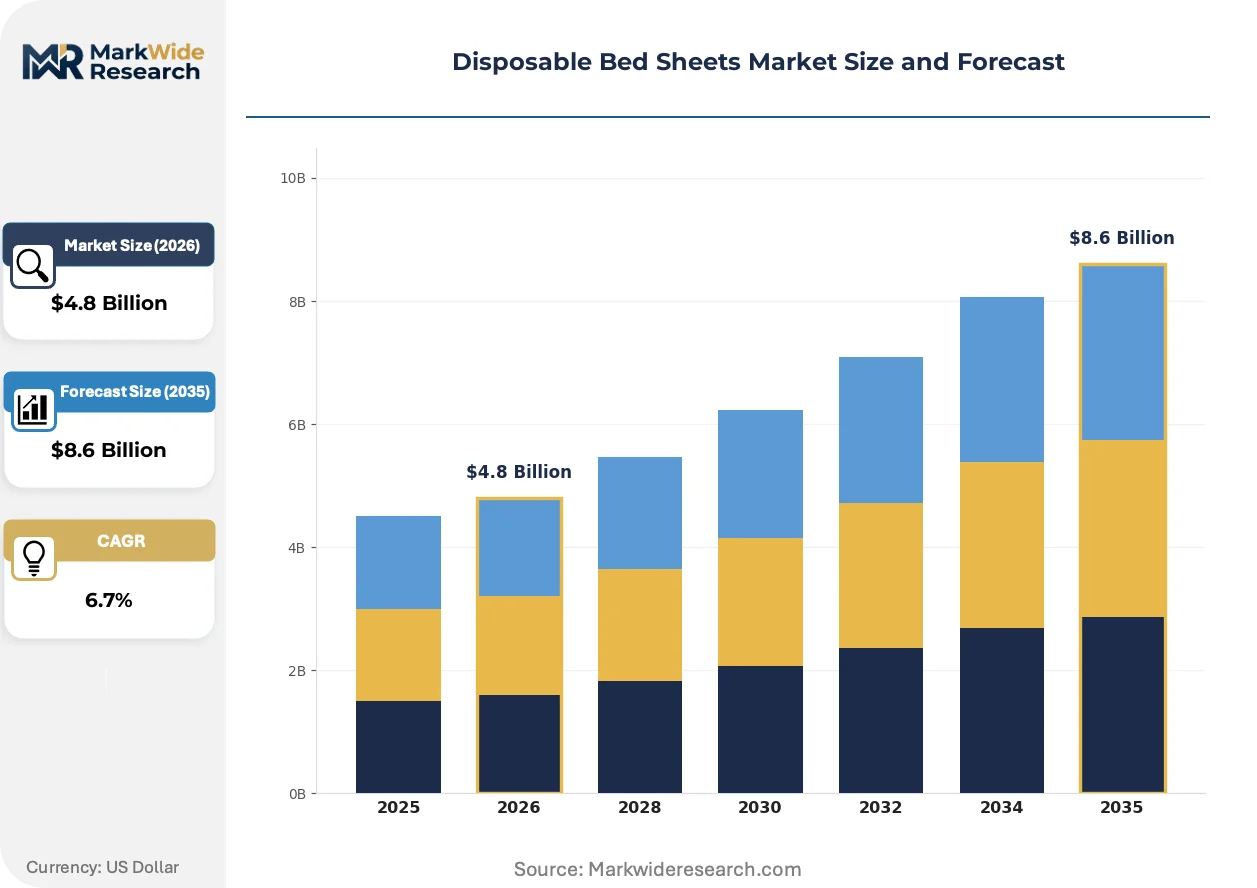
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sheets, Fitted Sheets, Pillow Cases, Mattress Protectors Material: Polypropylene, Polyethylene, Non-Woven Fabric, Cotton Blend End User: Hotels, Hospitals, Spas, Home Care Distribution Channel: Online Retail, Supermarkets, Medical Supply Stores, Wholesale |
| Companies Covered | Cardinal Health, 3M Healthcare, Medline Industries, Paul Hartmann AG, Winner Medical, TIDI Products, Berry Global, Kimberly-Clark, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Bed Sheets Market Emerging Trajectories
Active innovation clusters are compressing product development cycles around bonded nonwoven architectures while regulatory frameworks fragment compliance requirements across major healthcare procurement jurisdictions.
Thermal-bonded SMS laminates with integrated meltblown bacterial filtration layers are supplanting woven cotton-polyester blends in United States acute care isolation protocols. Hospital materials management departments are specifying AAMI PB70 Level 2-3 barriers for standard medical-surgical units, eliminating separate laundry service contracts. This substitution is compressing capital deployment timelines from multi-year textile service agreements to spot purchasing through group purchasing organizations.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of durable water-repellent finishes previously standard on polyethylene-laminated bed sheets. European manufacturers are migrating to silicone-based alternatives or eliminating repellency claims entirely, narrowing product differentiation vectors. German hospital procurement tenders now require full substance disclosure under SCIP database obligations, favoring suppliers with established chemical transparency protocols.
Direct-to-facility logistics models are eroding traditional medical supply wholesaler margins in North American distribution. Ambulatory surgical centers with high stretcher turnover rates are contracting manufacturers for floor-stock programs bypassing distributor warehousing. This channel compression is most advanced in Texas and Florida metropolitan markets where ASC density supports dedicated delivery route economics.
Disposable Bed Sheets Market Segmentation
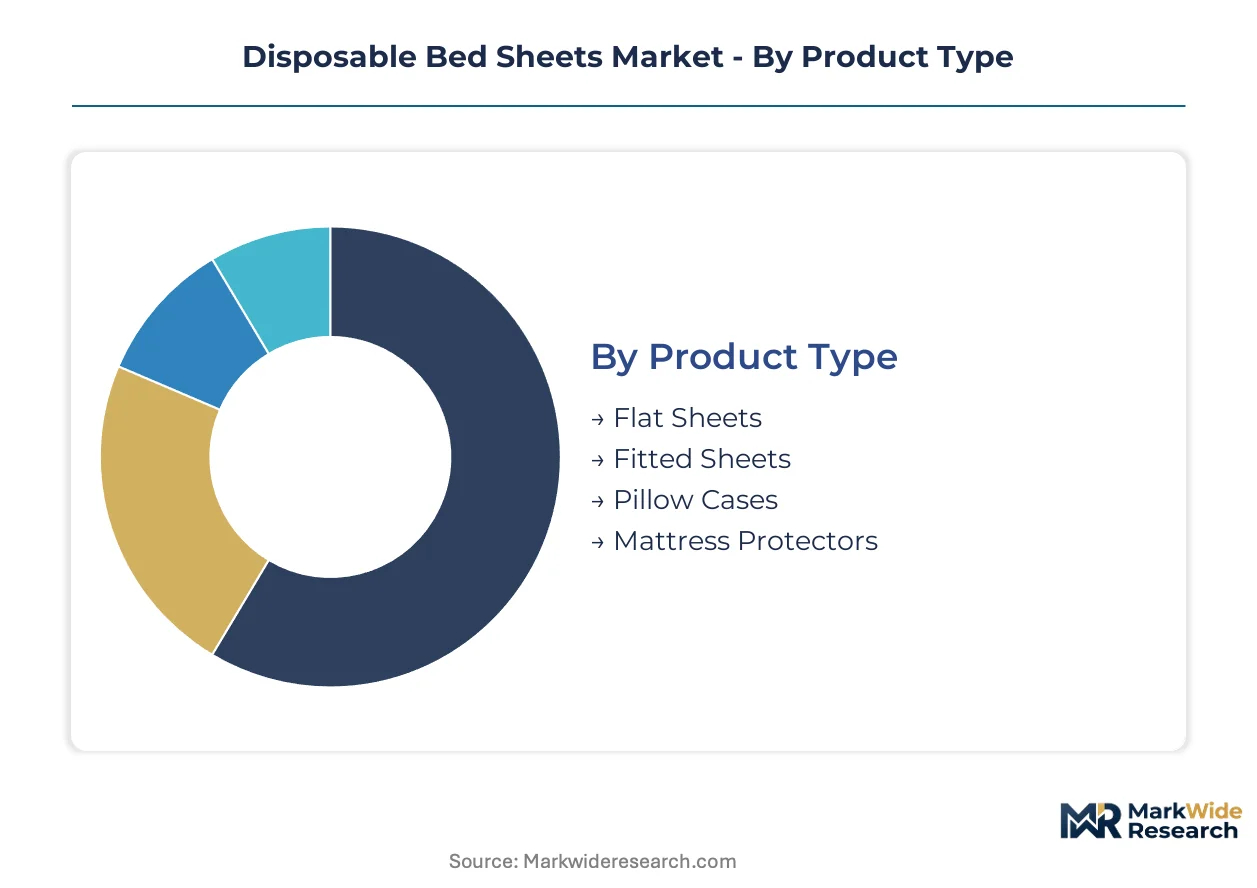
Segmentation in disposable bed sheets reveals divergent substitution economics across use cases. Hospital procurement departments weight infection control against linen service contracts, while hospitality buyers prioritize cost-per-change metrics against guest experience thresholds.
Product Type:
Flat sheets face the most intense substitution pressure from reusable cotton alternatives in budget hospitality settings, whereas fitted sheets defend their position through stretcher-specific dimensional requirements that resist laundering standardization.
- Flat Sheets:Single-layer spunbond polypropylene barriers in standardized dimensions dominate acute care isolation units. Demand concentrates in United States hospital systems where CMS reimbursement adjustments favor single-use procurement over textile service contracts.
- Fitted Sheets:Elasticized ultrasonic-sealed edges accommodate surgical stretchers and bariatric beds. Ambulatory surgical centers in Texas and Florida metropolitan markets specify fitted configurations to accelerate turnover between procedures.
- Pillow Cases:SMS fabric envelopes with bacterial filtration efficiency specifications for head-contact surfaces.
- Mattress Protectors:Polyethylene-laminated barriers with fluid-resistant seams for secondary contamination control.
Flat sheets anchor the volume base while fitted sheets gain share at the steepest rate.
Material:
Cost tier stratification separates commodity polypropylene from premium meltblown laminates, with polyethylene occupying mid-market hospitality applications where fluid resistance requirements moderate.
- Polypropylene:Thermal-bonded spunbond structures manufactured through continuous filament extrusion. Hospital procurement in Germany and France specifies polypropylene for standard medical-surgical units under EU Medical Device Regulation compliance frameworks.
- Non-Woven Fabric:SMS laminates integrating meltblown bacterial filtration layers between spunbond outer plies. United States surgical centers specify AAMI PB70 Level 2-3 barriers for isolation protocols, displacing woven cotton-polyester blends.
- Polyethylene:Extruded film barriers with silicone-based water repellency following REACH restrictions on per- and polyfluoroalkyl substances.
- Cotton Blend:Limited disposable applications in premium hospitality segments where biodegradability claims offset higher per-unit costs.
Polypropylene dominates procurement volumes while non-woven fabric expands most quickly through surgical specification upgrades.
End User:
Application maturity varies sharply: hospitals operate under regulated infection control mandates, while home care remains underpenetrated due to retail distribution gaps.
- Hospitals:Acute care facilities with standardized barrier textile specifications under FDA 510(k) or CE marking requirements. Demand clusters in United States health systems consolidating procurement through group purchasing organizations.
- Hotels:Budget and mid-scale properties calculating cost-per-change against laundry service economics. Properties in India leverage domestic technical textile capacity under PLI scheme incentives to reduce import dependency.
- Spas:Wellness facilities with intermittent high-volume turnover during peak treatment periods.
- Home Care:Post-acute patients and caregivers sourcing retail-packaged bedding kits through online channels.
Hospitals anchor the volume base while home care gains share at the steepest rate.
Distribution Channel:
Customer type fragmentation drives channel bifurcation: institutional buyers demand direct-to-facility logistics, while residential purchasers default to e-commerce convenience.
- Medical Supply Stores:Specialized distributors stocking AAMI PB70 certified inventory for hospital materials management departments. United States ambulatory surgical centers in high-density metropolitan markets contract floor-stock programs bypassing traditional wholesaler warehousing.
- Online Retail:E-commerce platforms serving home care and small hospitality operators with pallet-scale procurement. India's hospital infrastructure expansion drives platform investments in technical textile categories.
- Supermarkets:Mass retail channels for hospitality bulk purchasing and emergency institutional restocking.
- Wholesale:Traditional medical supply intermediaries facing margin compression from manufacturer direct contracts.
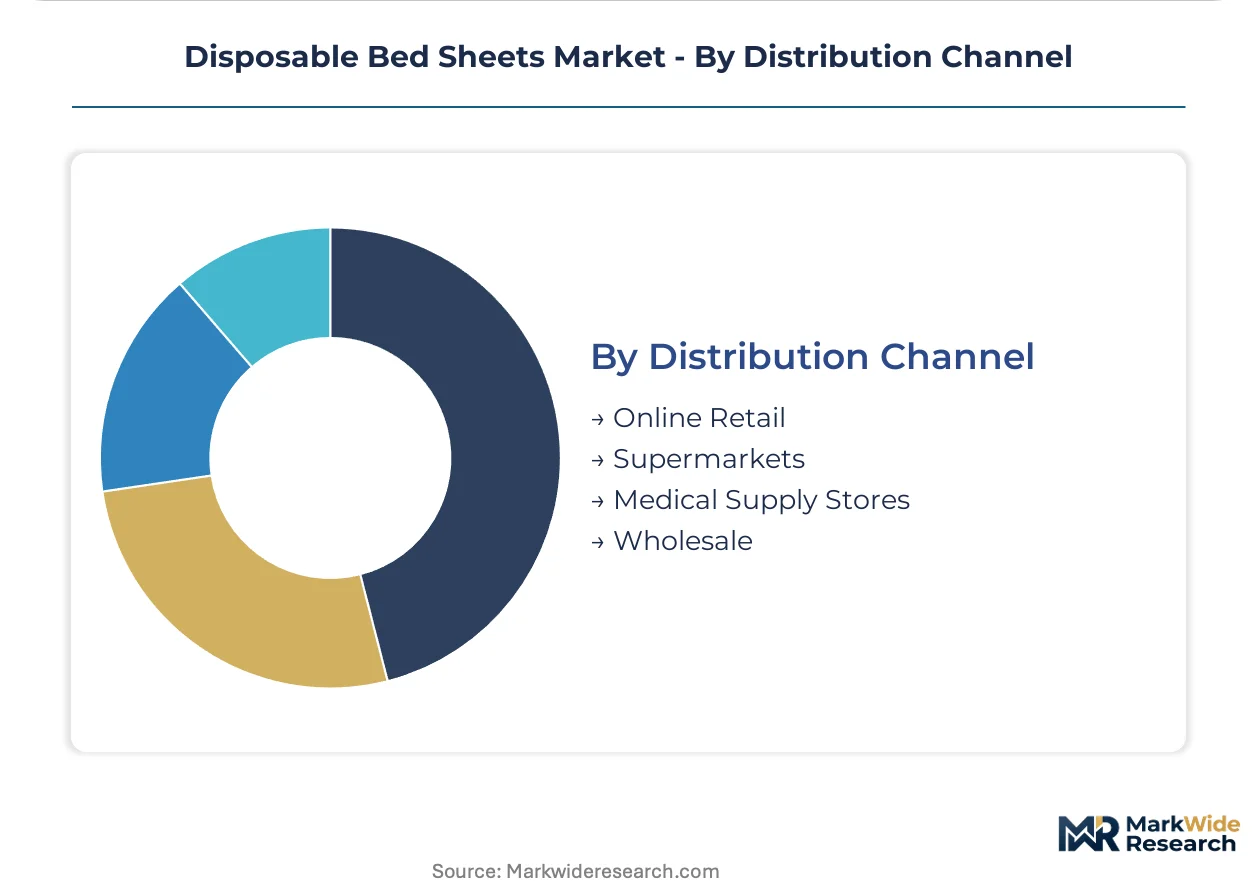
Medical supply stores anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor net-producing regions with polymer feedstock access and technical textile infrastructure. The United States runs a structural surplus in SMS fabric conversion while importing spunbond base materials from Asian suppliers. European markets exhibit balanced trade in finished barriers but rising polymer import dependency.
United States
Ambulatory surgical center expansion in Texas and Florida drives fitted sheet procurement velocity. CMS inpatient prospective payment system adjustments favor single-use linens over reusable textile contracts. Dallas-Fort Worth ASC clusters negotiate direct-to-facility floor-stock programs bypassing traditional medical supply wholesalers.
Germany
Industrial laundry operators in North Rhine-Westphalia bundle linen management with equipment leasing, creating switching-cost barriers for disposable conversion. EU Medical Device Regulation Class I reclassification forces compliance-driven inventory replacement cycles. Bavarian hospital procurement tenders now mandate SCIP database substance disclosure for barrier textiles.
China
Spunbond polypropylene capacity expansion in Zhejiang and Jiangsu provinces reduces import dependency for base nonwoven materials. NMPA medical device registration requirements tighten quality thresholds for export-oriented manufacturers. Yangtze River Delta technical textile clusters supply SMS laminates to Southeast Asian hospital infrastructure projects.
India
Production-linked incentive schemes for technical textiles attract nonwoven manufacturing investments serving domestic hospital expansion. CDSCO medical device rules create registration bottlenecks for imported barrier products. Gujarat pharmaceutical manufacturing corridors generate adjacent demand for cleanroom-grade disposable bedding.
United Kingdom
Post-acute care migration from NHS hospitals to residential settings expands home healthcare kit demand through online retail channels. MHRA regulatory alignment with EU MDR maintains conformity assessment burdens for barrier textile importers. London metropolitan health systems consolidate procurement through group purchasing organizations favoring standardized flat sheet specifications.
Disposable Bed Sheets Market Vendor Landscape
Concentration sits with diversified health conglomerates possessing captive nonwoven manufacturing and direct-to-facility distribution infrastructure. The vendor base stratifies across three tiers: integrated polymer-to-product manufacturers, specialized medical textile converters, and regional distributors with limited backward integration. Dominant competitive moves include capacity expansion in spunbond-meltblown-spunbond laminates and strategic partnerships with ambulatory surgical center networks for floor-stock logistics contracts.
Within the integrated health systems tier, Cardinal Health and Medline Industries exemplify archetypes combining polymer conversion with distribution control. Paul Hartmann AG anchors European positioning through CE-marked product lines navigating EUDAMED registration requirements. These three entities represent distinct geographic footprints: United States-based conglomerates with domestic ASC network penetration, and German compliance-depth specialists serving regulated European procurement frameworks.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M Healthcare |
| Medline Industries |
| Paul Hartmann AG |
| Winner Medical |
| TIDI Products |
| Berry Global |
| Kimberly-Clark |
| Mölnlycke Health Care |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles at United States ambulatory surgical centers concentrate purchasing power among group purchasing organizations, compressing manufacturer margins while rewarding backward-integrated suppliers with captive polypropylene conversion. This lead-time band ties pricing power directly to feedstock access and thermal-bonding capacity location.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hospital procurement. Three-tier pricing structure across premium, standard, and economy levels separates AAMI PB70 Level 3 SMS laminates from Level 2 barriers and commodity spunbond polypropylene. Cost compression in standard tiers is intensifying because REACH-compliant silicone-based repellency reformulations add finishing steps without reimbursement recognition. Budget hospitality operators exhibit highest price sensitivity, while United States ASC networks with floor-stock programs prioritize stretcher turnover speed over per-unit cost.
Supply Chain Analysis
Inventory positioning at 45-60 days for meltblown filtration layers reflects just-in-time sourcing from Zhejiang and Jiangsu province manufacturers. Raw material flows draw from Saudi Arabian and Qatari polypropylene resin, Jiangsu spunbond base materials, and German ultrasonic sealing equipment. Single-source vulnerability concentrates in meltblown capacity following pandemic-era capacity retirements. Distribution runs through direct-to-facility logistics networks that bypass traditional medical supply wholesalers in Texas and Florida metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable bed sheets markets are recovering from post-pandemic inventory destocking as hospital capital expenditure cycles normalize and ASC construction permits accelerate across Sun Belt states.
For Market Incumbents: Fortify thermal-bonding capacity in polypropylene-conversion corridors to defend against Asian import price pressure. Invest in EUDAMED registration depth ahead of EU Medical Device Regulation Class I reclassification deadlines. Deepen floor-stock logistics contracts with high-turnover ASC clusters to create switching-cost barriers for disposable conversion.
For New Entrants and Emerging Players: Lead with retail-packaged home healthcare bedding kits targeting post-acute care migration from institutional to residential settings. India's PLI scheme for technical textiles offers the most penetrable geography for greenfield nonwoven manufacturing. Pursue CDSCO medical device registration to access domestic hospital infrastructure expansion bypassing import bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across commodity spunbond tiers as Chinese capacity expansion saturates base material supply. Long-term viability favors integrated polymer-to-product manufacturers with direct-to-facility distribution control. Acquisition target archetype: regional medical textile converters with established GPO contracts and underutilized SMS laminate capacity. Watch CMS inpatient prospective payment system adjustments as inflection signal for single-use procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Conversion | Captive resin supply insulates margins from petrochemical volatility affecting commodity competitors. |
| EUDAMED Registration Pathway Investment | CE-marked product lines secure procurement eligibility under EU Medical Device Regulation Class I reclassification. |
| Floor-Stock Logistics Partnership | Dedicated delivery routes to Texas and Florida ASC clusters bypass distributor warehousing compression. |
| Antimicrobial Additive Integration | EPA-registered silver-ion bonding during thermal sealing opens premium positioning against standard SMS. |
| Home Healthcare Retail Packaging | Post-acute care migration creates channel expansion beyond institutional procurement concentration. |
Methodological Framework
A spread of perspectives from hospital materials management directors, ambulatory surgical center operations managers, nonwoven manufacturing plant engineers, and group purchasing organization contract specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EPA antimicrobial claim registrations, CMS reimbursement rulemaking dockets, and EU EUDAMED device registration databases. Bottom-up procurement volume estimates triangulated against top-down polymer feedstock consumption figures across the analysis window.
Segmentation dimensions modeled span product type, material composition, end-user facility category, and distribution channel structure throughout the forecast period. CAGRs derive from elasticity-adjusted demand projections tied to hospital bed capacity expansion, ASC construction permits, and infection control protocol adoption curves. Industry-specific inputs include AAMI PB70 barrier level specifications, REACH substance restriction timelines, and PLI scheme incentive disbursement patterns.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement favorability or abrupt EU Green Deal circular economy mandate acceleration would require recalibration. Forecasts reflect documented assumptions regarding polymer resin price stability and contract laboratory testing capacity availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Hemodialysis Consumables Market