
 Specimen Containers Market | 2026-2036
Specimen Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Specimen Containers Market Intelligence
Modular container systems with integrated temperature indicators and leak-proof seals is repositioning procurement criteria across European and North American healthcare networks. Cardinal Health leverages its distribution scale to bundle specimen containers with complementary consumables, while SARSTEDT AG & Co. KG anchors its position through specialized vacutainer engineering for blood collection workflows. Thermo Fisher Scientific competes by extending its R&D intensity into cryopreservation-compatible materials for biobanking clients.
Specimen containers are sterile receptacles manufactured from medical-grade polypropylene, polyethylene, or borosilicate glass, engineered to maintain sample integrity across temperature ranges from ambient storage to cryogenic conditions. Their primary purpose spans clinical diagnostics, pathological analysis, and long-term biological specimen preservation in regulated healthcare and research environments. Plastic containers dominate volume due to disposability economics and shatter resistance, while glass variants retain share in chromatography and volatile compound applications where chemical inertness commands premium positioning. Diagnostic labs represent the fastest-growing end-user channel as decentralized testing networks expand specimen throughput requirements.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product entry timelines and material validation standards for manufacturers targeting regulated markets. ISO 13485 quality management systems and CLSI specimen handling guidelines further constrain design freedom while elevating compliance costs for new entrants. Stakeholders must monitor evolving biobanking accreditation requirements and sustainability mandates affecting single-use plastic specifications across procurement frameworks.
Market Dynamics
EU MDR conformity assessments and FDA 510(k) clearance pathways are compressing product entry timelines while elevating material validation standards for sterile specimen container manufacturers targeting regulated healthcare networks.
Growth Catalysts
- Decentralized diagnostic networks:Point-of-care testing expansion in Germany and the United States is driving specimen throughput requirements for sterile, single-use containers with integrated leak-proof seals.
- REACH-compliant material innovation:Cryogenic-grade polypropylene formulations meeting EU chemical safety standards are unlocking biobanking applications requiring long-term preservation below minus 150 degrees Celsius.
- ISO 13485 certification mandates:Quality management system requirements across European and North American procurement frameworks are filtering out uncertified suppliers and consolidating demand toward validated manufacturers.
Market Restraints
- Medical-grade resin price volatility:Polypropylene and polyethylene input costs fluctuate with petrochemical feedstock markets, compressing margin stability for container producers.
- Borosilicate glass supply concentration:Chromatography-grade glass manufacturing clusters in Germany and China create geographic concentration risk for specialty container variants.
- Single-use plastic substitution pressure:Reusable sterilizable container systems threaten disposability economics in sustainability-focused European hospital networks.
Strategic Opportunities
- Indian diagnostic lab expansion:CDSCO regulatory alignment with international standards is opening procurement channels for sterile specimen handling products in underpenetrated South Asian markets.
- Integrated temperature-indicator systems:Smart packaging convergence with RFID tracking creates premium positioning for cold-chain specimen integrity monitoring.
- EU Green Deal procurement mandates:Circular economy specifications in public healthcare tenders favor recyclable polypropylene formulations and bio-based material alternatives.
Industry Challenges
- CLSI guideline implementation:Specimen handling protocol updates require continuous staff retraining and workflow reconfiguration across hospital laboratory networks.
- Cryogenic material validation timelines:Extended stability testing for minus 196 degrees Celsius compatibility delays product commercialization and ties up R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specimen Containers Market |
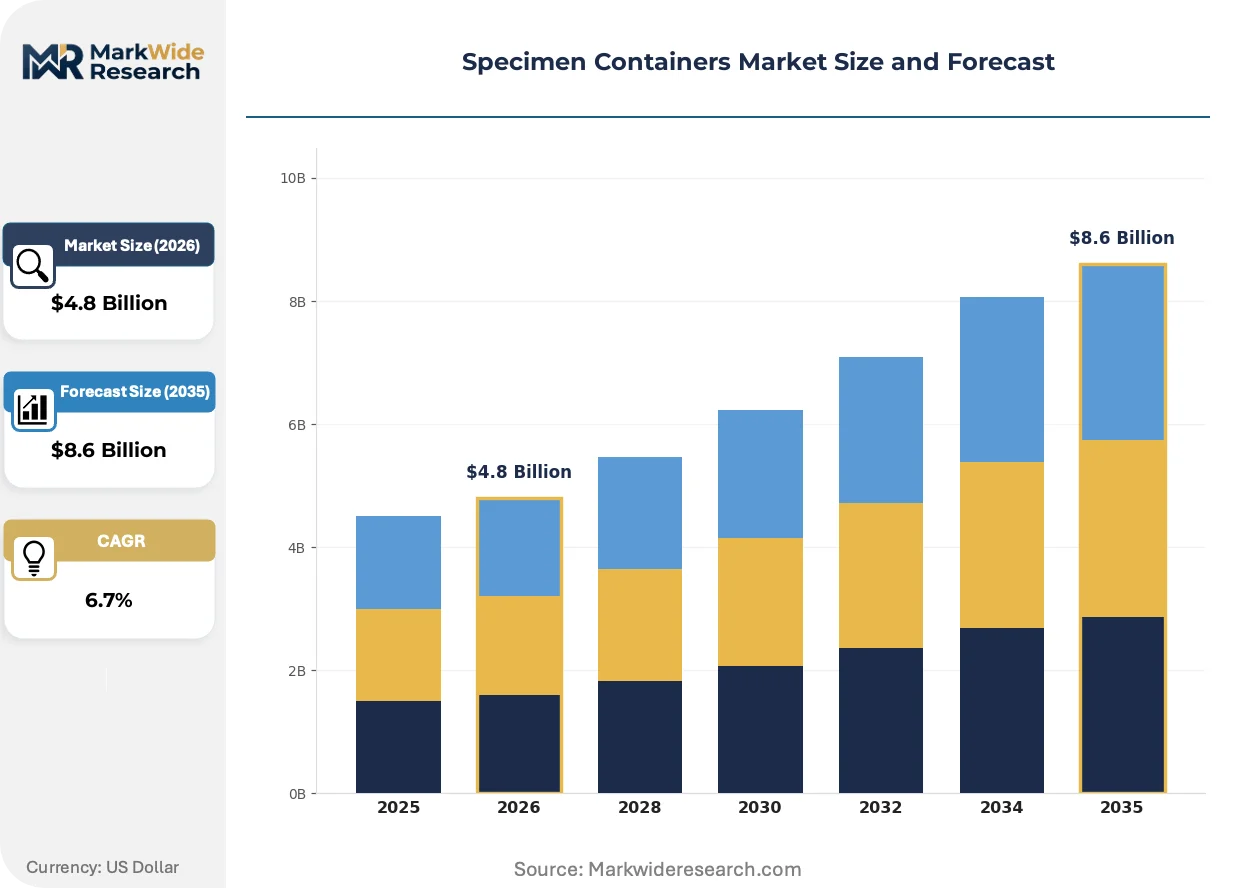
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Vacutainers, Jars, Tubes, Bottles Material: Plastic, Glass, Polypropylene, Polyethylene End User: Hospitals, Diagnostic Labs, Research Centers, Blood Banks Application: Clinical Studies, Biobanking, Pathological Testing, Microbiology |
| Companies Covered | Kartell Labware, FL MEDICAL s.r.l., Cardinal Health, VITLAB GmbH, Vernacare, Sterimed Group, SARSTEDT AG & Co. KG, BD, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specimen Containers Market Strategic Shifts & Innovations
Modular container architectures with embedded sensor capabilities are redefining procurement criteria, while regulatory convergence between FDA and EU MDR frameworks is standardizing validation protocols across Atlantic markets.
Smart specimen containers with NFC-enabled temperature logging and chain-of-custody tracking are decentralizing sample integrity monitoring from centralized laboratory equipment to point-of-collection devices. Diagnostic networks in the United States and Germany are deploying these systems to reduce pre-analytical error rates. The technology is decentralizing quality control accountability from lab technicians to frontline collection staff.
EU MDR Article 10 technical documentation requirements are mandating extended clinical evidence for sterile container systems previously cleared under withdrawn directives. Manufacturers must now submit biological safety data and post-market surveillance plans for continued market access. German notified bodies are experiencing backlog delays, compressing launch timelines for medium-sized suppliers.
Hospital procurement consortia are consolidating vendor relationships and unbundling after-sales technical support from product pricing. Large integrated delivery networks in the United States now negotiate multi-year sole-source agreements for specimen container categories. This concentration is most visible in academic medical center supply chains, where standardization committees mandate single-platform deployments across affiliated outpatient clinics.
Specimen Containers Market Segmentation
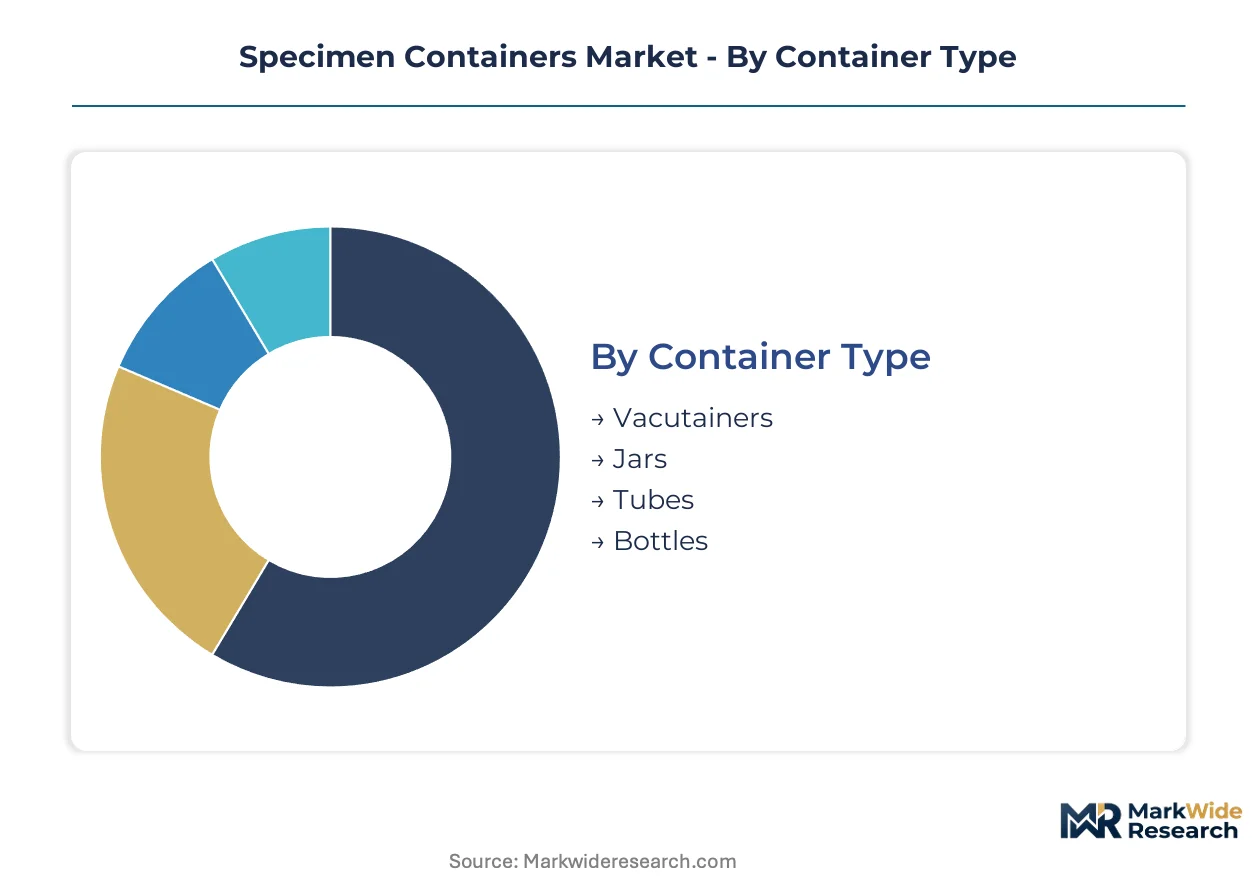
Specimen container procurement varies sharply across use cases, with material specifications and sterility grades determining supplier eligibility. Segmentation reveals where margin pools concentrate and which technical barriers protect incumbent positions.
Container Type:
Production tooling investments cluster around blood collection formats, with specialized mold engineering creating durable supply advantages for established manufacturers.
- Vacutainers:Evacuated blood collection tubes with precise vacuum calibration for standardized draw volumes. Diagnostic labs in Germany and the United States drive procurement volume as decentralized testing networks expand phlebotomy throughput requirements.
- Jars:Wide-mouth cylindrical containers for tissue specimens and histology samples, typically manufactured from polypropylene or borosilicate glass. Biobanking facilities in the United States concentrate demand for large-format sterile storage with cryogenic compatibility.
- Tubes:Cylindrical formats for liquid specimens including serum, plasma, and urine, available in conical or round-bottom configurations. Clinical laboratories specify additive-coated interiors for coagulation and chemistry panels.
- Bottles:Larger-volume receptacles for bulk specimen transport and culture media storage. Research centers favor screw-cap designs with tamper-evident seals for multi-site study protocols.
Vacutainers absorb the bulk of installed capacity; jars are expanding most quickly as biobanking infrastructure scales.
Material:
Raw material sourcing strategies diverge between commodity resin buyers and specialty polymer compounders, with certification requirements filtering supplier tiers.
- Plastic:Polyethylene and polypropylene formulations dominate disposable volume, with injection molding economics favoring high-throughput producers. REACH-compliant resin grades are becoming mandatory for EU MDR conformity, elevating compounder qualification barriers.
- Glass:Borosilicate variants retain premium positioning in chromatography and volatile compound applications where chemical inertness prevents sample degradation. Manufacturing clusters in Germany and China create geographic supply concentration for specialty grades.
- Polypropylene:Cryogenic-grade homopolymers engineered for minus 196 degrees Celsius stability in biobanking applications. Extended validation timelines for ultra-low temperature compatibility delay new entrant commercialization.
- Polyethylene:Low-density and high-density grades for general-purpose specimen handling, with linear low-density variants offering improved impact resistance for transport containers.
Plastic commands the greatest production volume; polypropylene climbs the fastest as long-term preservation protocols proliferate.
End User:
Procurement authority structures vary dramatically across customer types, with consolidated buying power reshaping vendor relationships.
- Diagnostic Labs:High-throughput facilities processing thousands of specimens daily, driving demand for sterile single-use containers with integrated leak-proof seals. Point-of-care testing expansion in decentralized networks is accelerating volume requirements.
- Hospitals:Integrated delivery networks with standardization committees mandating sole-source agreements across affiliated outpatient clinics. Sustainability mandates in European hospital procurement are pressuring single-use plastic specifications.
- Research Centers:Academic and contract research organizations with specialized protocols for multi-site clinical studies. Temperature-indicator integration and chain-of-custody tracking command premium pricing in this segment.
- Blood Banks:Collection and processing facilities with stringent sterility and traceability requirements for transfusion safety. ISO 13485 certification filters supplier eligibility for this regulated channel.
Diagnostic labs represent the steepest expansion trajectory; hospitals retain the largest aggregate procurement spend.
Application:
Regulatory validation requirements intensify with specimen preservation duration, creating tiered margin structures across use cases.
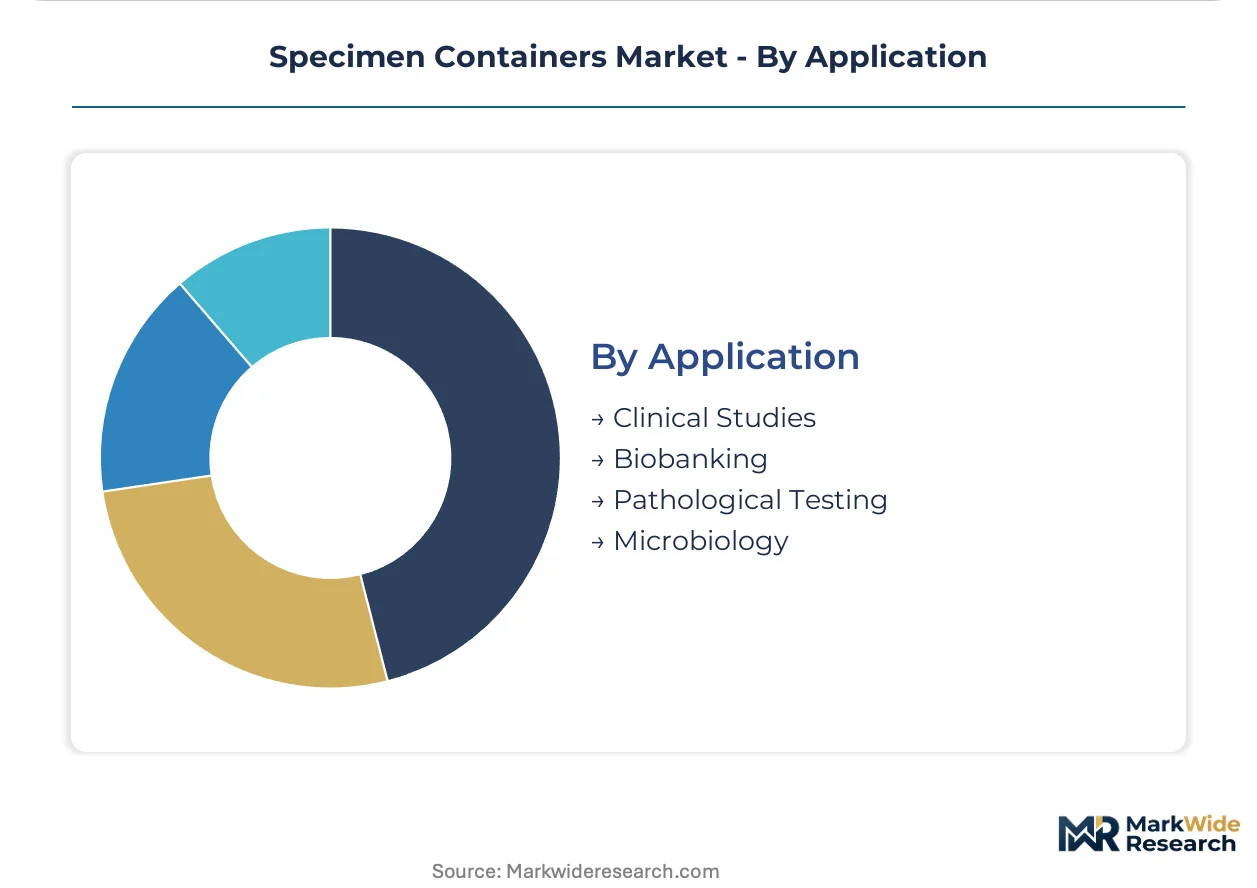
- Biobanking:Long-term biological specimen preservation requiring cryogenic-grade materials and extended stability documentation. EU MDR Article 10 technical documentation mandates are elevating compliance costs for container suppliers serving this segment.
- Pathological Testing:Tissue processing and histology workflows utilizing formalin-fixed specimens in leak-resistant containers. Clinical laboratories in Germany are expanding sterile handling protocols under updated EU MDR frameworks.
- Clinical Studies:Multi-site trials with standardized collection protocols and centralized laboratory analysis. RFID-enabled tracking and temperature logging are becoming procurement requirements for phase III studies.
- Microbiology:Culture media transport and anaerobic specimen handling with specialized barrier properties. Hospital laboratories specify containers maintaining specimen viability during extended transport intervals.
Biobanking captures premium pricing tiers; clinical studies are gaining share fastest as trial complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States, while consumption spreads across diagnostic networks in Europe, North America, and emerging Asian markets. Regulatory divergence between FDA and EU MDR frameworks shapes material validation requirements and commercial entry timelines.
United States
Decentralized diagnostic networks and biobanking infrastructure expansion drive container procurement volume. FDA 510(k) clearance pathways compress product entry timelines while elevating sterility documentation standards. The Boston-Cambridge biotech corridor concentrates demand for cryogenic-grade polypropylene containers from long-term preservation facilities.
Germany
Diagnostic lab expansion under EU MDR sterile handling protocols accelerates vacutainer and specimen jar procurement. Notified body backlog delays are compressing launch timelines for medium-sized suppliers seeking conformity assessments. The Rhine-Ruhr industrial basin hosts specialized mold engineering clusters serving blood collection workflow manufacturers.
China
Hospital laboratory standardization and domestic diagnostic equipment manufacturing scale container demand. NMPA regulatory alignment with international standards opens procurement channels for sterile handling products. The Yangtze River Delta concentrates injection molding capacity for medical-grade polypropylene formulations.
India
Diagnostic lab network expansion in tier-2 and tier-3 cities drives specimen container volume requirements. CDSCO regulatory harmonization with ISO 13485 standards filters supplier eligibility for institutional procurement. Maharashtra's Mumbai-Pune pharmaceutical corridor anchors sterile consumables distribution infrastructure.
Japan
Aging demographics and hospital consolidation reshape specimen handling procurement toward standardized, high-reliability container systems. PMDA quality management requirements elevate documentation burdens for foreign manufacturers. The Kansai region's Osaka-Kobe industrial zone maintains specialty polymer compounding capacity for medical-grade applications.
Specimen Containers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material tiers and application segments. The vendor base organizes into three strategic archetypes: diversified healthcare distributors leveraging procurement scale, specialized laboratory consumables engineers with vacutainer expertise, and diversified life sciences conglomerates extending cryopreservation R&D. Competitive moves concentrate on multi-year sole-source agreements with integrated delivery networks and backward integration into medical-grade resin compounding.
Among diversified healthcare distributors, Cardinal Health exemplifies procurement bundling strategies that combine specimen containers with complementary consumables. SARSTEDT AG & Co. KG occupies a position within the specialized engineering tier, representing concentrated expertise in evacuated blood collection systems. Thermo Fisher Scientific anchors the life sciences conglomerate archetype, extending materials science capabilities into cryogenic-compatible container formulations for biobanking clients.
| Leading Market Players |
|---|
| Kartell Labware |
| FL MEDICAL s.r.l. |
| Cardinal Health |
| VITLAB GmbH |
| Vernacare |
| Sterimed Group |
| SARSTEDT AG & Co. KG |
| BD |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Polypropylene resin price indices cascade through specimen container manufacturing tiers, compressing margin structures for commodity-grade producers while cryogenic-grade compounders retain pricing power through ISO 13485 certification barriers and extended validation timelines.
Pricing Analysis
Margin tightening in standard-grade polyethylene containers reflects petrochemical feedstock volatility and Asian import competition. Three-tier pricing structure across cryogenic-certified, clinical-grade, and general-purpose levels separates biobanking clients from diagnostic labs from cost-conscious research buyers. Cost-down pressure on economy-tier suppliers accelerates as Indian and Chinese manufacturers expand injection molding capacity. Hospital procurement consortia exhibit highest price sensitivity through multi-year sole-source negotiations, while biobanking facilities prioritize temperature stability over unit economics.
Supply Chain Analysis
ISO 13485 certification gating concentrates qualified supply among German, United States, and Chinese mold engineering clusters with documented biological safety data. Medical-grade polypropylene and borosilicate glass feedstock draws from petrochemical complexes in the US Gulf Coast and specialty glassworks in Germany and China. Single-source vulnerability persists for chromatography-grade borosilicate given manufacturing concentration in the Rhine-Ruhr basin. Distribution runs through diversified healthcare distributors and direct hospital procurement consortia with unbundled technical support contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 technical documentation mandates erect a cost-of-compliance moat that filters uncertified suppliers and consolidates procurement toward validated manufacturers with post-market surveillance infrastructure.
For Market Incumbents: Cement market position through backward integration into REACH-compliant resin compounding and captive supply of cryogenic-grade polypropylene. Expand mold engineering capacity in the Rhine-Ruhr cluster to exploit notified body proximity. Defend against emerging Asian price competitors by embedding RFID temperature indicators as standard features, not premium add-ons.
For New Entrants and Emerging Players: Launch via CDSCO-aligned regulatory pathways into Indian tier-2 and tier-3 diagnostic lab networks where ISO 13485 certification scarcity limits incumbent penetration. Target biobanking adjacent segments—clinical studies with decentralized collection protocols—where chain-of-custody tracking commands premium positioning without minus 196 degrees Celsius validation burdens.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German manufacturers with EU MDR technical documentation already filed and notified body relationships intact. Long-term viability hinges on sustainability credentialing as EU Green Deal procurement mandates expand. Watch for CDSCO regulatory harmonization completion as inflection signal for South Asian market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Biological safety data packages accelerate notified body assessments and compress rival launch timelines. |
| Cryogenic Material Validation Programs | Minus 196 degrees Celsius stability documentation unlocks biobanking premium tiers and long-term sole-source agreements. |
| RFID Temperature Indicator Integration | Smart packaging convergence reduces pre-analytical error rates and shifts quality accountability to collection staff. |
| REACH-Compliant Resin Compounding | In-house polymer formulation controls input cost volatility and filters uncertified commodity competitors. |
| Indian Diagnostic Lab Distribution Partnerships | CDSCO-aligned channel access captures volume expansion in underpenetrated tier-2 and tier-3 cities. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and ISO 13485 certification registries, complemented by interviews with laboratory procurement managers, biomedical engineers at academic medical centers, GPO contracts specialists, and diagnostic equipment manufacturing executives. Secondary validation drew from hospital procurement databases, customs trade data for medical-grade resin imports, and CLSI guideline documentation. Bottom-up demand modeling triangulated against top-down healthcare expenditure projections.
Cross-referencing historical volume trajectories with expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include container type, material grade tier, end-user procurement authority structure, and regional regulatory cluster. CAGRs derived from weighted average of historical trend extrapolation and scenario-adjusted growth assumptions. Cryogenic-grade polypropylene adoption curves and decentralized diagnostic network expansion rates served as industry-specific forecast inputs.
Petrochemical feedstock volatility, notified body assessment backlogs, and biobanking accreditation requirement shifts are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU MDR enforcement intensity or CDSCO regulatory harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Skin Tac Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Compression Socks Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Dental Emergency Kit Market