
 North America Intravenous Solutions Market | 2026-2036
North America Intravenous Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Intravenous Solutions Market Insights
Aftermarket service revenue from infusion pump maintenance and fluid bag compatibility testing is rewriting margin distribution across the value chain. Baxter International leverages its integrated manufacturing footprint to sustain pricing power in large-volume parenterals. Fresenius Kabi anchors its position through specialized compounding capabilities for oncology and critical care applications. ICU Medical competes aggressively on needle-free connector technology that reduces bloodstream infection risk.
Intravenous solutions are sterile, pyrogen-free aqueous preparations containing electrolytes, dextrose, amino acids, or medications, manufactured via aseptic processing in cleanroom environments and terminally sterilized to meet USP <797> and <800> standards for immediate vascular administration. Electrolyte solutions and nutritional solutions dominate volume throughput in hospital settings where fluid resuscitation and parenteral nutrition protocols drive recurring consumption. Oncology applications within the application segment command premium positioning due to complex compounding requirements and narrow therapeutic windows that limit supplier substitution.
FDA enforces current Good Manufacturing Practice regulations for finished pharmaceuticals while USP Chapter <797> governs sterile compounding operations, collectively elevating compliance costs and consolidating production among qualified manufacturers. Health Canada and the US EPA jointly influence environmental discharge standards for pharmaceutical manufacturing wastewater, adding location constraints to facility siting decisions. Stakeholders must monitor evolving USP compounding standards and cross-border regulatory harmonization initiatives that could reshape competitive access across the US-Canada trade corridor.
Market Dynamics
Home healthcare adoption across the United States and Canada is restructuring demand patterns, pulling infusion therapy from acute care settings into residential environments and forcing manufacturers to redesign packaging, stability profiles, and distribution logistics for non-hospital endpoints.
Growth Catalysts
- USP Compounding Standards:FDA enforcement of USP Chapter <797> and <800> for sterile compounding is consolidating qualified supplier pools and elevating pricing power among compliant manufacturers.
- Oncology Protocol Expansion:Complex parenteral nutrition and chemotherapy compounding requirements in US hospital systems are driving recurring volume through specialized high-margin product lines.
- Midwest and Southeast Hospital Corridors:Concentrated health system purchasing power across these US regions is generating predictable bulk demand for large-volume parenterals.
Market Restraints
- API and Excipient Concentration:Limited domestic sources for pharmaceutical-grade salts and dextrose monohydrate create input vulnerability for North American formulators.
- Environmental Discharge Compliance:US EPA and Health Canada wastewater standards for pharmaceutical manufacturing constrain greenfield facility siting and expansion timelines.
- Glass and Polymer Supply Rigidity:Specialized blow-fill-seal equipment and pharmaceutical-grade resin supply chains exhibit limited elasticity against demand spikes.
Strategic Opportunities
- Canadian Home Infusion Expansion:Underpenetrated ambulatory infusion services in Ontario and British Columbia offer whitespace for direct-to-patient distribution models.
- Needle-Free Connector Adoption:Infection control mandates in US acute care settings are accelerating conversion from traditional spike systems to closed transfer devices.
- IRA Hospital Supply Resilience Provisions:Federal incentives for domestic pharmaceutical manufacturing are improving project economics for US-based sterile fill-finish capacity.
Industry Challenges
- Compounding Pharmacy Technician Shortage:USP <797>-certified personnel scarcity in the US is extending batch release timelines and constraining output scaling.
- Legacy Pump Interoperability:Fluid bag barcode and connector standardization gaps across installed hospital device bases complicate product line harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Intravenous Solutions Market |
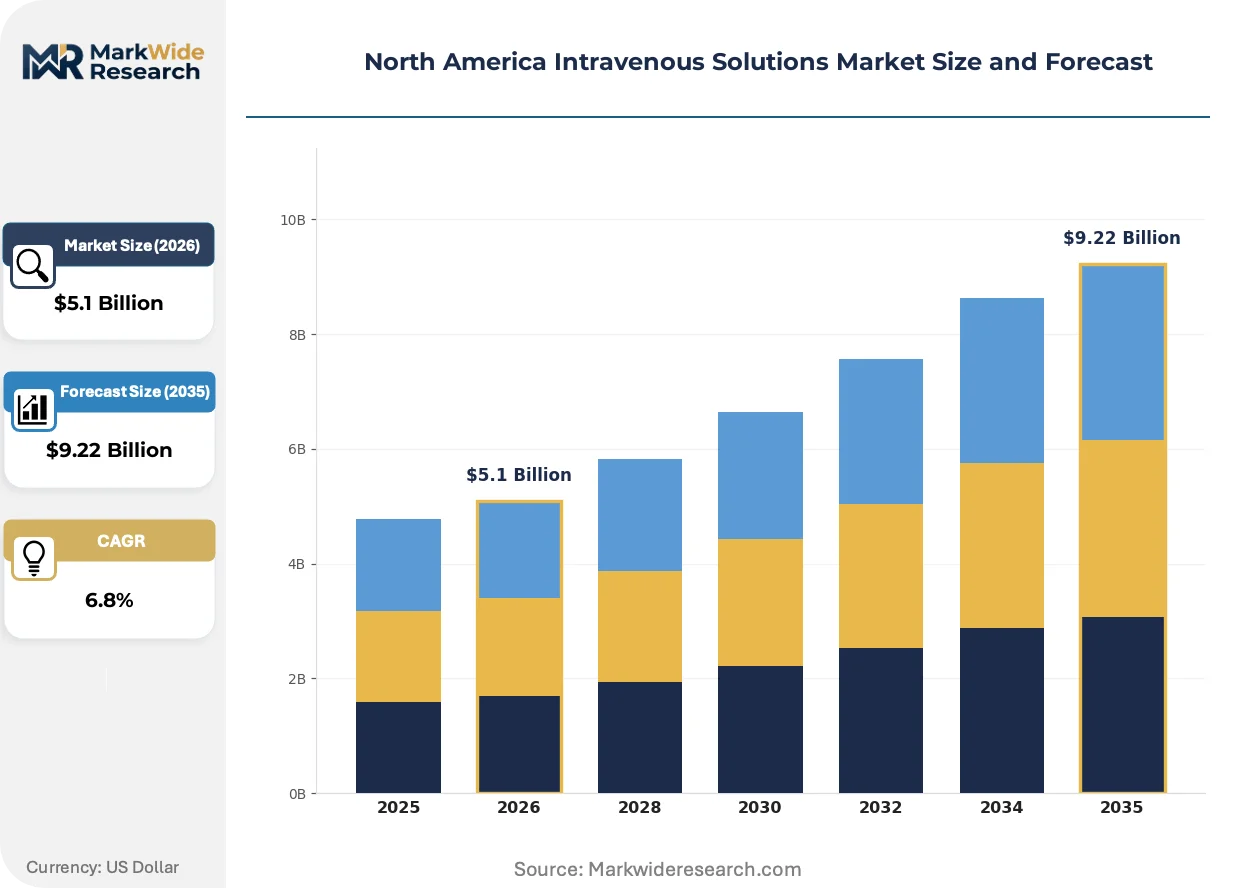
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Dextrose Solutions, Nutritional Solutions, Antibiotic Solutions Application: Oncology, Critical Care, Hypovolemia, Surgery End User: Hospitals, Dialysis Centers, Home Healthcare, Outpatient Clinics Delivery Mode: IV Drip, Infusion Pump, Gravity Feed, Syringe Pump |
| Companies Covered | Baxter International, Fresenius Kabi, ICU Medical, B. Braun Medical, Pfizer, Option Care Health, Grifols, Otsuka Pharmaceutical, CSL, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Intravenous Solutions Market Trends and Innovations
Digital integration of compounding workflows and closed-system drug transfer devices are compressing contamination risk profiles while regulatory pressure on environmental compliance is reshaping manufacturing footprints across the continent.
Closed-system transfer devices (CSTDs) for hazardous drug handling are digitizing manual compounding verification steps through integrated barcode scanning and gravimetric confirmation. US oncology units and hospital pharmacies are adopting these systems at accelerated replacement cycles for legacy open-vial techniques. This convergence of mechanical containment with electronic record-keeping is digitizing compliance documentation and compressing pharmacist oversight burdens per preparation.
FDA's intensified current Good Manufacturing Practice enforcement for sterile injectables is elevating facility inspection frequency and data integrity requirements. Manufacturers are responding with redundant environmental monitoring systems and real-time particle counting infrastructure. Large-volume parenteral facilities in the US Midwest face the steepest compliance investment curves given their aging physical plants and high-volume throughput exposure.
Hospital purchasing consortia in the US Southeast are consolidating supplier rosters and unbundling after-sales service from product procurement. Integrated delivery networks are replacing transactional distributor relationships with direct manufacturer contracts carrying multi-year volume commitments. This concentration of buying power is most visible in Florida and Texas health systems where IDN mergers have compressed vendor panels to three or fewer qualified suppliers per therapeutic category.
North America Intravenous Solutions Market Segmentation
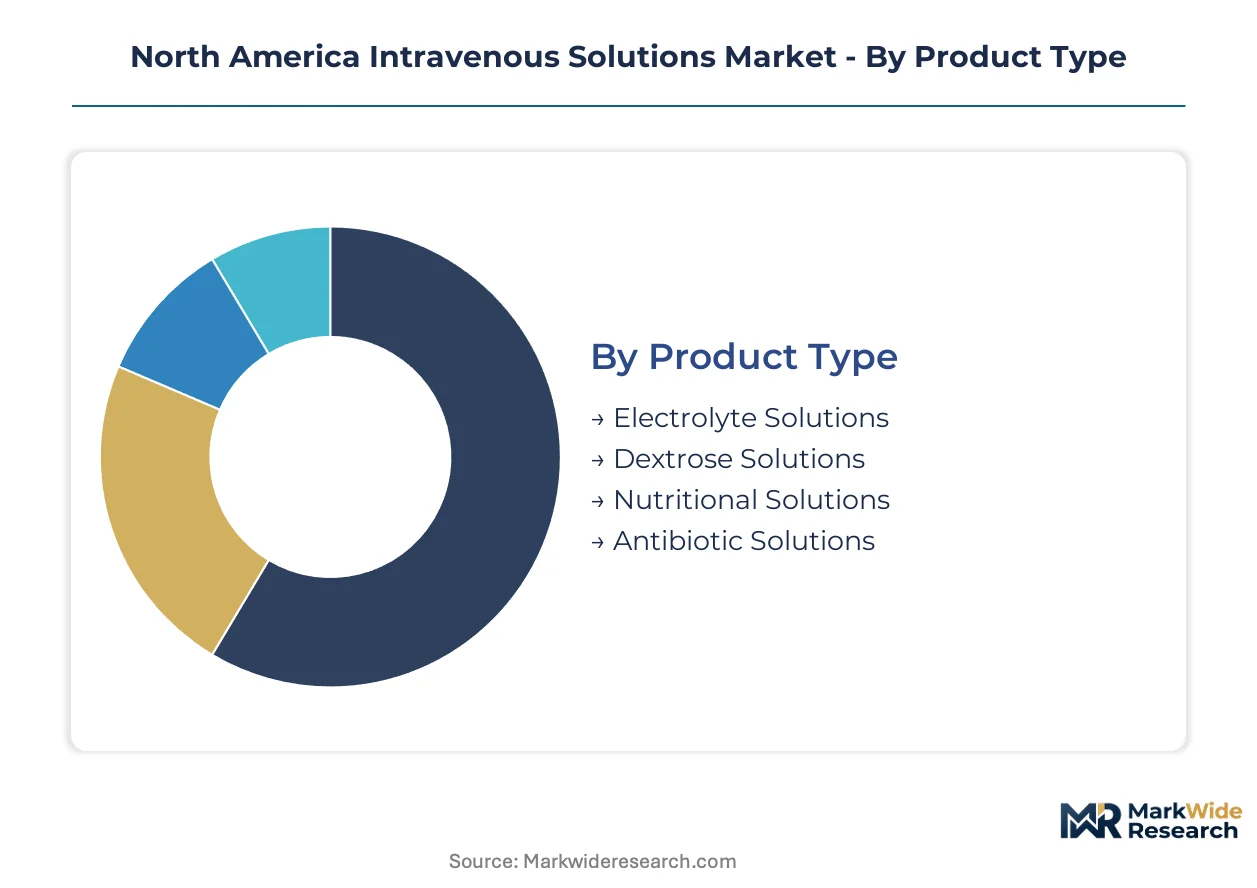
Segmentation in the North America intravenous solutions market exposes divergent margin structures and regulatory exposure across product categories. Each dimension reveals distinct competitive dynamics that reshape procurement patterns and manufacturing investment priorities.
Product Type:
Cycle times vary sharply across this category, with electrolyte solutions turning over in days while nutritional solutions require weeks of stability validation and custom compounding.
- Electrolyte Solutions:Sterile aqueous preparations containing sodium chloride, potassium, or balanced crystalloid mixtures for fluid resuscitation. Hospital systems across the US Midwest and Southeast corridors consume these at the highest velocity, driven by emergency department throughput and surgical scheduling density.
- Nutritional Solutions:Parenteral formulations combining amino acids, lipids, dextrose, and micronutrients for patients unable to tolerate enteral feeding. Home healthcare adoption in Ontario and British Columbia is pulling demand toward ambulatory infusion models with extended stability requirements.
- Dextrose Solutions:Hypertonic glucose preparations for caloric support and hypoglycemia correction. FDA USP <797> compliance costs concentrate production among qualified sterile compounders.
- Antibiotic Solutions:Pre-mixed antibacterial infusions requiring narrow therapeutic window management. Hospital pharmacy oversight burdens limit supplier flexibility.
Electrolyte solutions anchor the volume base while nutritional solutions gain share at the steepest rate.
Application:
Cost tier stratification separates commodity fluid replacement from premium-priced oncology compounding where specialized handling commands pricing power.
- Oncology:Chemotherapy and supportive care infusions requiring USP <800> hazardous drug containment protocols. Complex compounding workflows in US hospital systems limit supplier substitution and sustain margin premiums.
- Critical Care:Vasopressor and sedative continuous infusions for ICU hemodynamic management. Needle-free connector mandates in US acute care settings are accelerating closed-system transfer device adoption.
- Hypovolemia:Rapid volume replacement protocols for hemorrhage and septic shock. Trauma centers in Texas and Florida generate concentrated demand spikes.
- Surgery:Perioperative fluid management and balanced crystalloid administration. Ambulatory surgical centers are shortening length-of-stay and compressing infusion duration requirements.
Oncology commands the highest cost tier while critical care delivers the most predictable recurring volume.
End User:
Customer type determines packaging specifications, distribution logistics, and regulatory documentation intensity across the value chain.
- Hospitals:Integrated delivery networks with consolidated purchasing power and multi-year direct manufacturer contracts. IDN mergers in Florida and Texas have compressed vendor panels to three or fewer qualified suppliers per therapeutic category.
- Home Healthcare:Residential infusion therapy requiring redesigned stability profiles and patient-administered delivery systems. Underpenetrated services in Ontario and British Columbia offer whitespace for direct-to-patient distribution models.
- Dialysis Centers:High-volume electrolyte consumption for hemodialysis and peritoneal dialysis protocols. Freestanding centers operate on tighter inventory cycles than hospital-based units.
- Outpatient Clinics:Same-day infusion services for antibiotics, hydration, and biologics. These facilities prioritize pre-mixed bag availability over compounding flexibility.
Hospitals dominate procurement volume while home healthcare is expanding most quickly.
Delivery Mode:
Technology maturity separates legacy gravity systems from digitally integrated smart pumps with barcode verification and dose error reduction software.
- Infusion Pump:Electronically controlled volumetric or syringe devices with programmable flow rates and alarm systems. Legacy pump interoperability gaps across installed hospital device bases complicate fluid bag standardization.
- IV Drip:Basic gravity-fed administration with macrodrip or microdrip tubing sets. Cost-sensitive settings retain this modality for low-risk hydration protocols.
- Syringe Pump:Precision devices for small-volume medication delivery in neonatal and pediatric applications. Narrow therapeutic windows demand exact flow control.
- Gravity Feed:Passive flow systems without electronic monitoring. Resource-constrained environments and backup scenarios sustain residual demand.
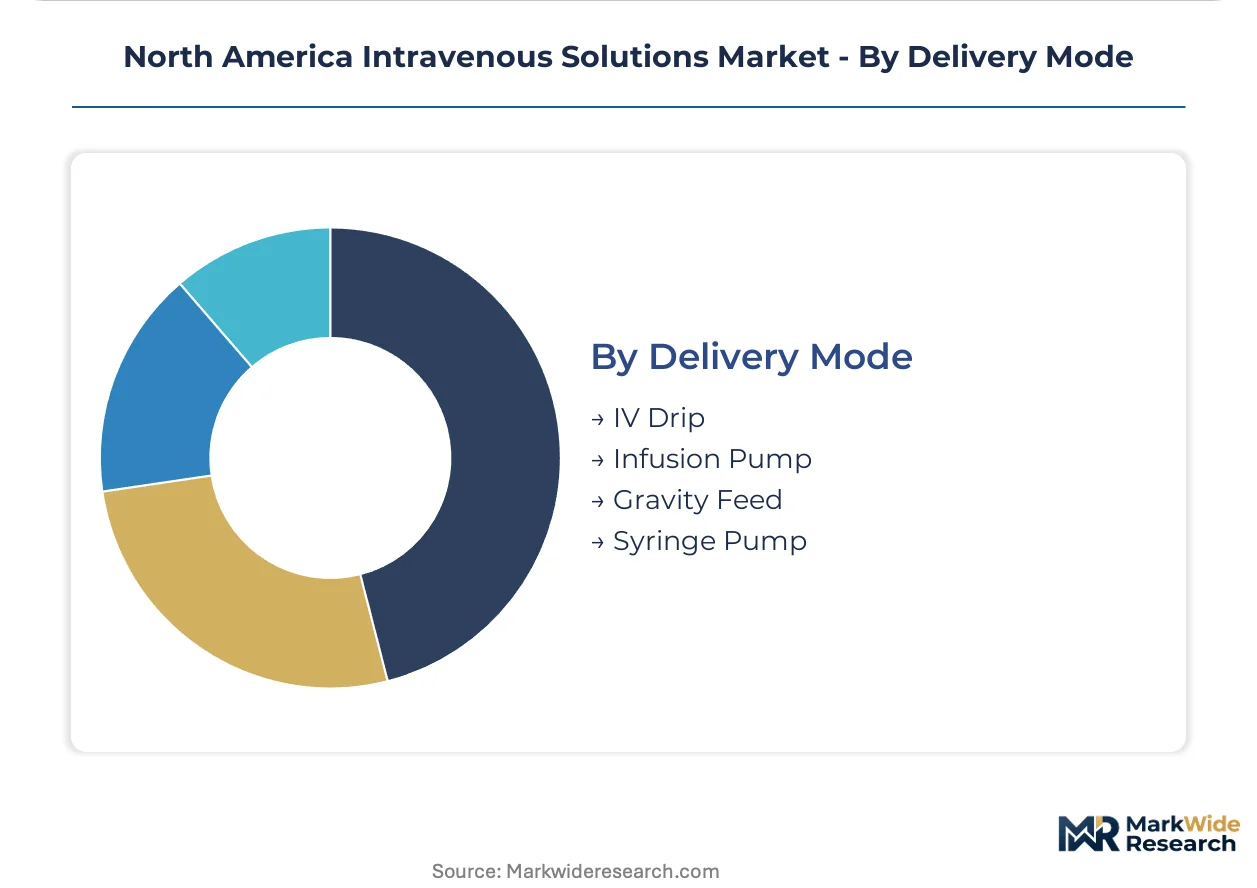
Infusion pumps anchor technology investment while syringe pumps show the steepest expansion trajectory in specialized care units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing consortia in the US Southeast negotiate with the sharpest price sensitivity, while oncology compounding specialists in the US Midwest command premium positioning. Canadian home infusion services exhibit the most elastic demand growth trajectory across the analysis window.
United States
Integrated delivery networks in Florida and Texas have compressed vendor panels to three or fewer qualified suppliers per therapeutic category. FDA enforcement of USP Chapter <797> and <800> elevates compliance costs and consolidates production among qualified manufacturers. Large-volume parenteral facilities in the US Midwest face the steepest compliance investment curves given aging physical plants.
Canada
Underpenetrated ambulatory infusion services in Ontario and British Columbia offer whitespace for direct-to-patient distribution models. Health Canada and the US EPA jointly influence environmental discharge standards for pharmaceutical manufacturing wastewater. Ontario's hospital procurement alliances are consolidating purchasing power and unbundling after-sales service from product procurement.
Mexico
Cross-border regulatory harmonization initiatives could reshape competitive access across the US-Canada trade corridor and extend into Mexican manufacturing zones. The country's national pharmaceutical regulator maintains alignment with FDA current Good Manufacturing Practice frameworks. Northern border states concentrate maquiladora operations serving US hospital supply chains.
North America Intravenous Solutions Market Competitive Landscape
Capability concentration sits with specialized compounders; scale advantage sits with integrated large-volume parenteral manufacturers. The market structure reflects a tiered competitive field where sterile fill-finish expertise and regulatory compliance credentials determine supplier access. Three strategic archetypes dominate: integrated manufacturing conglomerates with backward control over resin and API supply, specialized oncology compounders with USP <800> hazardous drug handling certifications, and technology-focused device innovators with needle-free connector portfolios. Dominant competitive moves include capacity expansion in US-based sterile fill-finish facilities and strategic partnerships between solution formulators and home infusion service providers.
Within the integrated manufacturing tier, Baxter International and Fresenius Kabi exemplify scale-driven positioning through captive production networks. ICU Medical occupies a specialized position anchored in infection control technology. These three entities represent the competitive spectrum from commodity large-volume parenterals through premium compounding services to device-integrated delivery systems.
| Leading Market Players |
|---|
| Baxter International |
| Fresenius Kabi |
| ICU Medical |
| B. Braun Medical |
| Pfizer |
| Option Care Health |
| Grifols |
| Otsuka Pharmaceutical |
| CSL |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade dextrose monohydrate and sodium chloride API sourcing from India and China concentrates upstream margin capture among specialized chemical manufacturers, while downstream pricing power accrues to sterile compounders with USP <797> certification credentials. Baxter International and Fresenius Kabi leverage captive resin production and backward integration into blow-fill-seal equipment to defend margin pools against commodity erosion.
Pricing Analysis
Aftermarket service revenue from infusion pump maintenance contracts and fluid bag compatibility testing drives lifetime value realization across installed hospital device bases. Three-tier pricing structure across premium, standard, and economy levels separates USP <800>-certified oncology compounders from large-volume parenteral manufacturers and basic electrolyte suppliers. Pricing pressure stems from IDN purchasing consortia in Florida and Texas unbundling service from product procurement. Dialysis centers and outpatient clinics exhibit the sharpest price sensitivity, while oncology units show the least.
Supply Chain Analysis
Upstream feedstock concentration for pharmaceutical-grade salts and dextrose monohydrate centers on India, China, and limited domestic North American sources. Blow-fill-seal equipment, pharmaceutical-grade resins, and specialized glass vials constitute critical component dependencies. Single-source vulnerability for FDA-compliant sterile fill-finish capacity creates structural risk during demand spikes. Distribution runs through integrated delivery networks with direct manufacturer contracts replacing transactional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home healthcare adoption and USP compounding digitization are disrupting traditional acute-care supply chains, with FDA enforcement of sterile processing standards creating a regulatory inflection that separates qualified manufacturers from marginal competitors.
For Market Incumbents: Harden USP <797> and <800> certification credentials through redundant environmental monitoring infrastructure and real-time particle counting systems. Deepen backward integration into pharmaceutical-grade resin production to offset API concentration risk from Asian suppliers. Consolidate vendor relationships with IDN purchasing consortia in the US Southeast through multi-year direct contracts carrying volume commitments. For New Entrants and Emerging Players: Pursue underpenetrated ambulatory infusion services in Ontario and British Columbia where direct-to-patient distribution models remain nascent. Target home healthcare packaging redesign and extended stability profile development as the most penetrable segment. Establish strategic partnerships with established sterile compounders for regulatory navigation rather than greenfield facility construction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed home infusion service providers lacking captive manufacturing capabilities. Five-to-ten year viability hinges on regulatory compliance durability rather than volume scale alone. Acquisition targets should demonstrate USP <800> hazardous drug handling certifications and closed-system transfer device integration. Monitor Health Canada-US EPA environmental discharge standard harmonization as the signal for cross-border manufacturing footprint expansion.| Strategic Initiative | Industry Significance |
|---|---|
| USP <800> Certification Investment | FDA enforcement elevates barrier to entry for hazardous drug compounders. |
| Home Infusion Service Partnership | Ontario and British Columbia whitespace enables direct-to-patient distribution capture. |
| Closed-System Transfer Device Integration | Needle-free connector mandates in US acute care accelerate infection control adoption. |
| Domestic Sterile Fill-Finish Capacity Expansion | IRA hospital supply resilience provisions improve project economics for US-based facilities. |
| Digital Compounding Workflow Integration | Barcode scanning and gravimetric confirmation compress pharmacist oversight burdens per preparation. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, GPO contracts managers, biomedical engineers, and sterile compounding technicians anchored the qualitative base. Primary interviews combined with secondary validation from FDA 483 inspection records, USP chapter revision dockets, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates across the analysis window.
Scenario-bracketing framed analytical projections across product type, application, end user, and delivery mode dimensions. CAGRs derived from historical volume trajectories, regulatory compliance cost curves, and IDN purchasing pattern shifts. Oncology protocol expansion rates and home healthcare adoption velocity served as industry-specific forecast inputs throughout the modeling period.
Sensitivities concentrate around USP compounding standard revisions, Health Canada environmental discharge enforcement, and cross-border regulatory harmonization timing. Forecasts reflect documented assumptions on sterile processing capacity expansion and IDN vendor panel consolidation. Material shifts in FDA inspection intensity or IRA domestic manufacturing incentive allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bags Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Pressure Redistribution Pads Market