
 Global Lancet and Pen Needles Market | 2026-2036
Global Lancet and Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lancet and Pen Needles Market Foresight
The split between premium safety-engineered devices and commodity disposable lancets is repositioning procurement criteria across healthcare systems. Novo Nordisk A/S dominates insulin pen needle supply through backward integration into diabetes care ecosystems. Ypsomed Holding AG differentiates via self-injection technology leadership and automated manufacturing scale. BD sustains broad hospital channel control across both lancet and pen needle portfolios.
Lancets and pen needles are sterile, single-use piercing instruments manufactured from surgical-grade stainless steel or siliconized cannula, typically 28G to 32G in diameter, designed to extract capillary blood or deliver subcutaneous medication with minimal tissue trauma. Safety pen needles now lead value generation as needlestick prevention mandates expand across acute and ambulatory settings. Gauge size stratification concentrates margin pools at 31G and 32G where thinner-wall technology reduces patient pain perception and drives brand loyalty in homecare settings. Diagnostic laboratories anchor volume demand for disposable lancets while specialty clinics shift toward integrated glucose monitoring systems.
FDA quality system regulations and EU MDR conformity requirements shape product design, sterilization validation, and market access timelines for manufacturers. ISO 11608 needle-based injection systems standards further define performance benchmarks that HTL-STREFA S.A. and Terumo Corporation navigate in their European and Asian regulatory filings. Stakeholders must monitor how reimbursement compression in public health systems alters the premium-commodity tier balance and whether emerging markets adopt safety-engineered mandates that mirror OECD precedents.
Market Dynamics
EU MDR sterility mandates and FDA quality system updates are compressing product development timelines while accelerating consolidation among manufacturers unable to absorb validation costs.
Growth Catalysts
- Homecare channel expansion:Diabetes management migration from clinics to patient residences drives recurring demand for 31G and 32G pen needles designed for self-administration.
- Needlestick prevention mandates:OSHA bloodborne pathogen standards and EU MDR safety requirements force acute care facilities toward safety-engineered pen needle adoption.
- Siliconization advances:Thin-wall cannula technology reduces insertion force and patient pain perception, strengthening brand loyalty in German and Japanese reimbursement markets.
Market Restraints
- Surgical-grade stainless steel price volatility:Raw material cost swings compress margins for commodity lancet producers lacking backward integration into metal sourcing.
- Single-use sterility validation:ISO 11608 compliance and gamma sterilization requirements extend time-to-market for new product introductions.
- Integrated glucose monitoring substitution:Continuous glucose monitoring systems reduce fingerstick frequency, eroding volume demand for disposable lancets in diagnostic laboratories.
Strategic Opportunities
- Brazil safety-engineered mandate gap:ANVISA has not yet replicated OECD needlestick prevention standards, creating first-mover positioning for safety pen needle suppliers.
- Retail pharmacy channel bypass:Direct-to-patient subscription models for pen needle resupply circumvent traditional hospital procurement and distributor markups.
- Dual carbon goals alignment:China's MEE packaging reduction targets favor manufacturers with bio-based needle shield materials and minimized sterile barrier mass.
Industry Challenges
- Gamma sterilization capacity scarcity:Contract sterilization bottlenecks delay batch release for manufacturers without captive irradiation facilities.
- Legacy ERP integration:UDI compliance and EU MDR traceability requirements force mid-tier producers to replace manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lancet and Pen Needles Market |
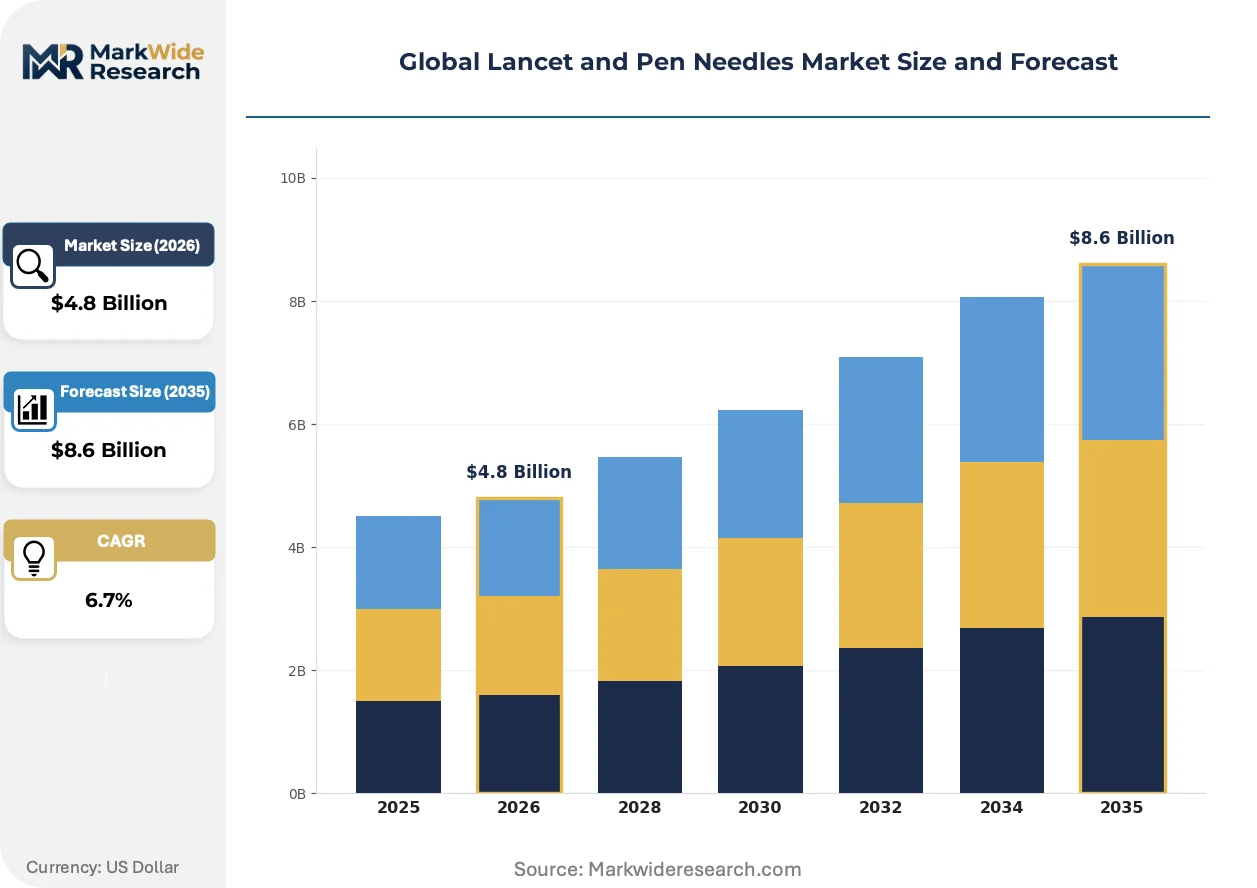
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Lancets, Safety Lancets, Reusable Lancets, Pen Needles, Safety Pen Needles Gauge Size: 28G, 29G, 30G, 31G, 32G Application: Insulin Delivery, Blood Glucose Monitoring, Clinical Diagnostics, Home Care, Veterinary End User: Hospitals, Diagnostic Laboratories, Homecare Settings, Specialty Clinics |
| Companies Covered | Novo Nordisk A/S, Ypsomed Holding AG, B. Braun Melsungen AG, HTL-STREFA S.A., Terumo Corporation, Embecta Corp., Owen Mumford Ltd., BD, ARKRAY, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lancet and Pen Needles Market Shifts & Advancements
Thin-wall cannula engineering and automated assembly lines are compressing unit economics while regulatory traceability requirements reshape quality management infrastructure across manufacturing footprints.
Siliconized 32G pen needles is overtaking standard 31G configurations in Japanese and German homecare markets where pain minimization determines brand selection. Endocrinology clinics in Osaka and Munich now specify ultra-thin wall specifications for insulin-dependent patients. This gauge compression is overtaking legacy 29G hospital contracts and forcing manufacturers to retool extrusion and grinding equipment.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for pen needle biocompatibility beyond prior self-certification protocols. Sterile device manufacturers face extended notified body review timelines and heightened post-market surveillance obligations. Safety pen needle portfolios face the steepest compliance burden as reclassification under Rule 6 triggers additional clinical evaluation requirements.
Hospital group purchasing organizations now consolidate lancet and pen needle procurement across integrated delivery networks, displacing individual facility purchasing autonomy. Banner Health and Kaiser Permanente in the United States negotiate multi-year sole-source agreements that lock out secondary suppliers. This concentration is most visible in United States acute care settings where reimbursement compression rewards volume aggregation over product differentiation.
Global Lancet and Pen Needles Market Segmentation
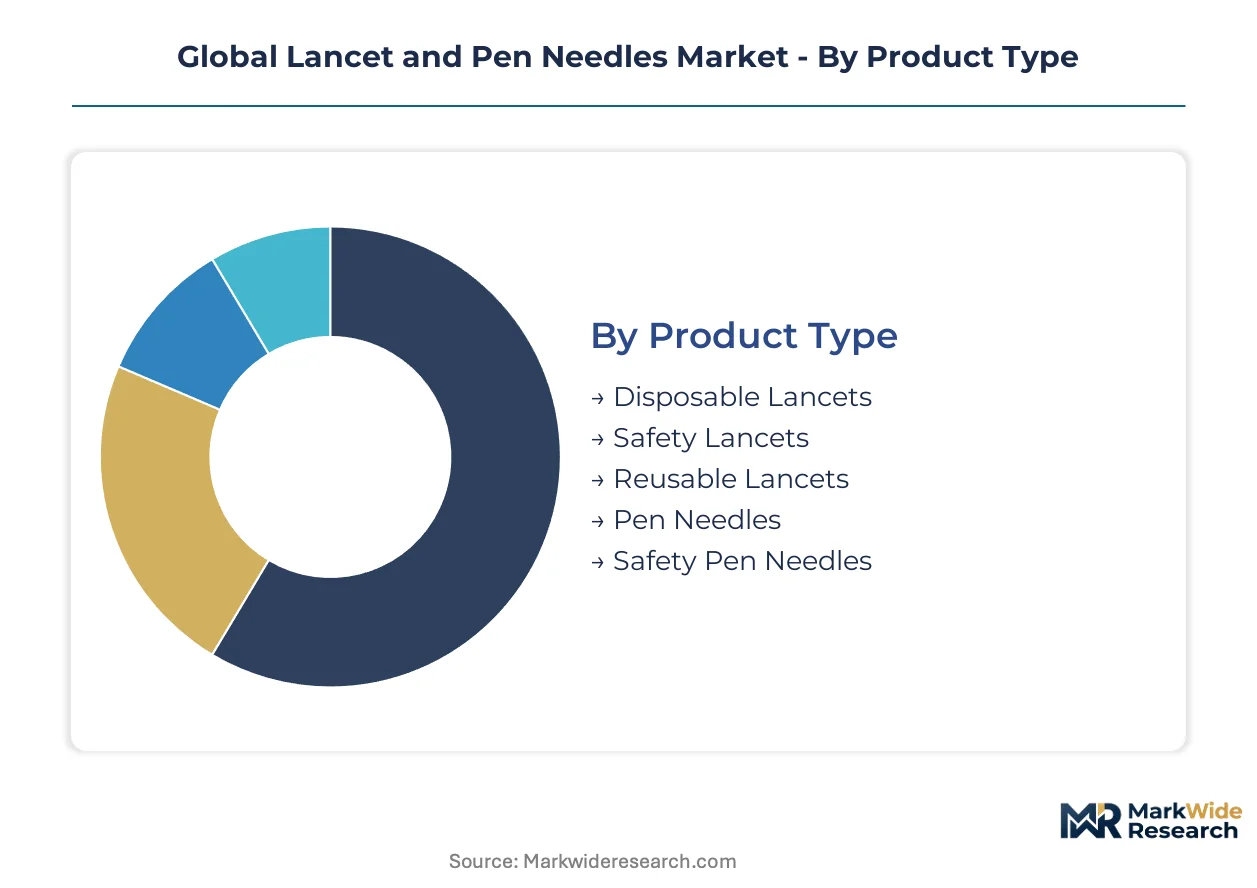
Segmentation in the lancet and pen needles market reveals how procurement criteria diverge across acute care, ambulatory, and self-administration environments. Product architecture, gauge engineering, and end-user workflow requirements create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Customization intensity spans from commodity disposables to precision-engineered safety systems with integrated needlestick protection mechanisms.
- Disposable Lancets:Single-use piercing instruments manufactured from surgical-grade stainless steel with fixed-depth penetration profiles. Diagnostic laboratories in Germany and Japan anchor volume procurement through high-throughput glucose screening contracts. Raw material price volatility compresses margins for producers lacking backward integration into metal sourcing.
- Safety Pen Needles:Siliconized cannula devices with integrated shield mechanisms that activate post-injection to prevent needlestick injuries. OSHA bloodborne pathogen standards and EU MDR Rule 6 reclassification mandate adoption across United States and European acute care facilities. This segment commands premium pricing through clinical evidence requirements and sterilization validation burdens.
- Safety Lancets:Spring-loaded devices with automatic blade retraction for capillary blood collection. Point-of-care testing expansion in United States integrated delivery networks drives replacement of conventional lancets.
- Reusable Lancets:Metal-bodied devices with replaceable lancet blades for multi-use scenarios. Veterinary applications and cost-sensitive homecare markets in emerging economies sustain residual demand.
- Pen Needles:Standard non-safety insulin delivery cannulas, predominantly 31G and 32G configurations. Japanese and German reimbursement systems favor thin-wall technology that reduces patient pain perception.
Leading the category by volume: Disposable Lancets. Growing fastest: Safety Pen Needles.
Gauge Size:
Cost tier stratification concentrates manufacturing investment at the fine-gauge end where wall thickness engineering commands price premiums.
- 32G:Ultra-thin wall cannula with minimal tissue trauma profiles, manufactured through precision grinding and siliconization processes. Endocrinology clinics in Osaka and Munich now specify this gauge for insulin-dependent patients with needle anxiety. Japanese homecare markets reward brand loyalty through pain minimization performance.
- 31G:Thin-wall standard for insulin pen systems, balancing penetration force reduction with structural integrity during injection. German statutory health insurance reimbursement tiers favor this specification for type 2 diabetes management.
- 30G:Mid-range gauge retaining hospital formulary presence for patients with thicker subcutaneous tissue profiles. United States long-term care facilities specify this configuration for elderly populations with skin elasticity variations.
- 29G:Legacy hospital contracts in acute care settings where procurement prioritizes unit cost over patient experience metrics. Volume erosion accelerates as integrated delivery networks consolidate around finer gauges.
- 28G:Coarsest specification confined to veterinary applications and specialized clinical diagnostics requiring larger blood volumes. Niche demand from blood bank screening protocols sustains minimal production runs.
Dominating procurement volumes: 31G. Expanding most quickly: 32G.
Application:
Customer workflow requirements separate high-frequency self-administration from institutional batch processing environments.
- Insulin Delivery:Subcutaneous medication administration via pen injector systems, requiring siliconized cannula with consistent extrusion geometry. Homecare migration from clinic-based administration drives recurring resupply demand in United States and German markets. Patient adherence programs now incorporate gauge preference into personalized diabetes management protocols.
- Blood Glucose Monitoring:Capillary blood extraction for point-of-care testing and self-monitoring of blood glucose. Continuous glucose monitoring substitution erodes fingerstick frequency in diagnostic laboratories, though homecare testing sustains residual lancet consumption.
- Clinical Diagnostics:High-volume screening applications including hemoglobin A1c and lipid panel testing. Hospital group purchasing organizations consolidate procurement across integrated delivery networks.
- Home Care:Patient-directed administration and monitoring outside institutional settings. Direct-to-patient subscription models circumvent traditional distributor markups.
- Veterinary:Companion animal glucose monitoring and medication delivery. Reusable lancet systems retain preference due to cost sensitivity in veterinary practice economics.
Capturing largest volume share: Insulin Delivery. Gaining share fastest: Home Care.
End User:
Supply concentration patterns align with reimbursement infrastructure density and regulatory enforcement stringency.
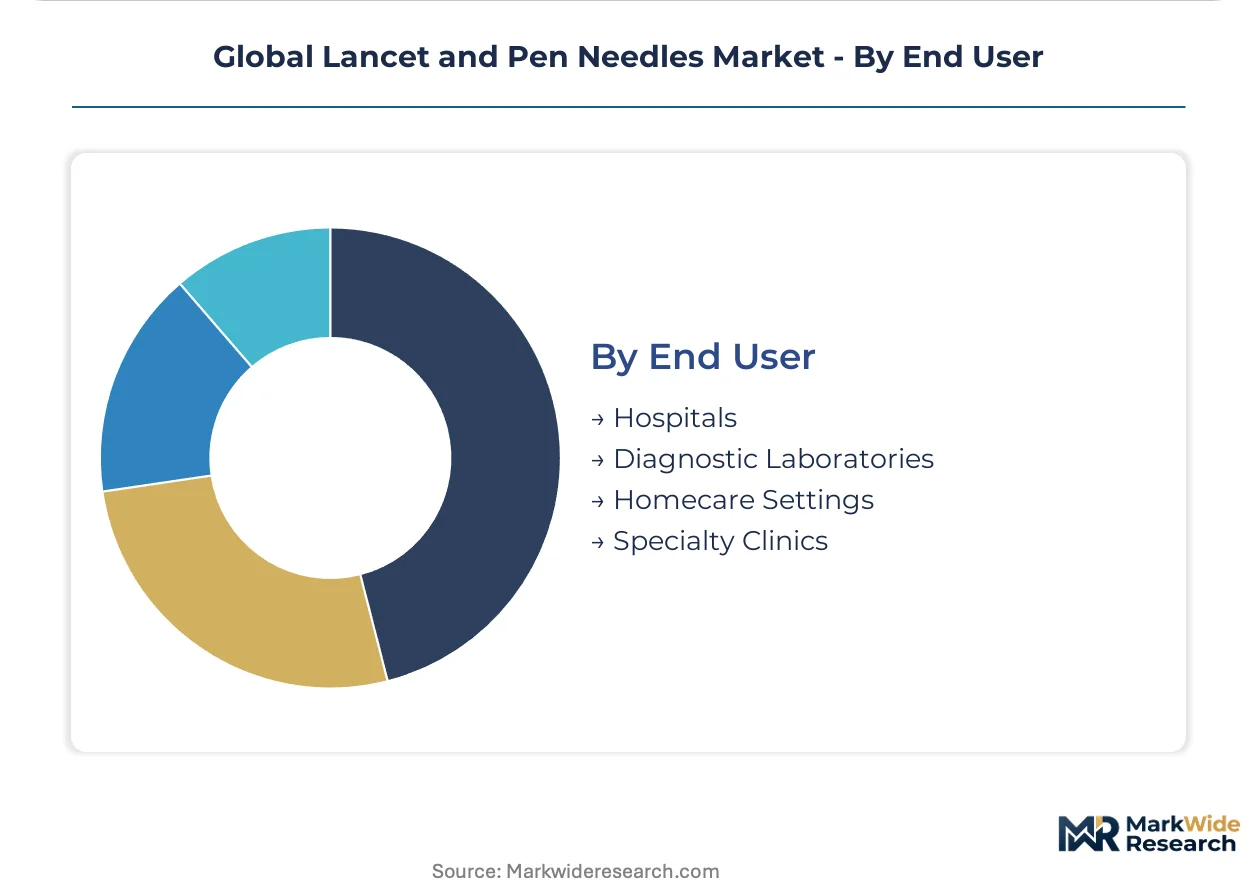
- Homecare Settings:Patient residences where self-administration of insulin and glucose monitoring occurs without clinical supervision. German and Japanese reimbursement systems support premium gauge adoption through pain-minimization incentives.
- Hospitals:Acute care facilities subject to OSHA bloodborne pathogen standards and EU MDR safety mandates. Banner Health and Kaiser Permanente negotiate multi-year sole-source agreements that displace secondary suppliers.
- Diagnostic Laboratories:High-throughput centralized testing facilities processing population-scale screening programs. Continuous glucose monitoring adoption reduces fingerstick dependency.
- Specialty Clinics:Endocrinology and diabetes care centers emphasizing patient experience metrics. Osaka and Munich clinic networks specify ultra-thin wall pen needle configurations.
Generating highest unit volumes: Homecare Settings. Climbing the fastest: Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka anchors Japanese demand for ultra-thin 32G pen needles, with endocrinology clinics specifying siliconized cannula for insulin-dependent patients. German statutory health insurance and Japanese reimbursement tiers reward pain-minimization engineering. United States hospital procurement concentrates through integrated delivery networks. Brazilian regulatory gaps and Chinese packaging mandates reshape competitive entry strategies.
United States
Banner Health and Kaiser Permanente negotiate multi-year sole-source agreements for lancet and pen needle procurement across integrated delivery networks. OSHA bloodborne pathogen standards mandate safety-engineered pen needle adoption in acute care facilities. The Greater Boston cluster hosts specialty diabetes care centers driving 31G specification for type 2 management protocols.
Germany
Munich endocrinology clinics specify 32G ultra-thin wall configurations for insulin-dependent patients with needle anxiety. EU MDR Article 10 technical documentation requirements extend notified body review timelines for sterile device manufacturers. The Baden-Württemberg medical technology corridor concentrates automated assembly capacity for siliconized cannula production.
Japan
Osaka clinic networks drive 32G gauge compression overtaking legacy 29G hospital contracts through patient experience metrics. METI reimbursement tiers favor thin-wall technology reducing insertion force for elderly diabetes populations. The Kansai region anchors domestic manufacturing scale for precision-ground pen needle extrusion.
Brazil
ANVISA has not yet replicated OECD needlestick prevention standards, creating first-mover positioning for safety pen needle suppliers entering Latin America's largest diabetes market. The country's national pharmaceutical regulator maintains less stringent sterility validation requirements than EU MDR protocols. São Paulo state concentrates private hospital procurement for insulin delivery systems.
China
MEE packaging reduction targets favor manufacturers with bio-based needle shield materials and minimized sterile barrier mass. NMPA quality system regulations align with ISO 11608 needle-based injection systems standards for market access. The Yangtze River Delta cluster hosts contract sterilization facilities serving domestic pen needle producers.
Global Lancet and Pen Needles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across gauge engineering and safety mechanism integration. The market structure consolidates around three tiers: backward-integrated diabetes care ecosystems, automated manufacturing specialists, and broad hospital channel controllers. Strategic archetypes include siliconization technology leaders, sterile barrier innovators, and integrated delivery network contract holders. Dominant competitive moves encompass multi-year sole-source procurement agreements and captive gamma sterilization facility investments.
Among European fabricators, Novo Nordisk A/S and Ypsomed Holding AG occupy positions representing ecosystem integration and self-injection technology leadership respectively. HTL-STREFA S.A. exemplifies the mid-tier specialist archetype navigating EU MDR conformity requirements. These three entities anchor the competitive structure across reimbursement-intensive markets in Germany and Japan.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Ypsomed Holding AG |
| B. Braun Melsungen AG |
| HTL-STREFA S.A. |
| Terumo Corporation |
| Embecta Corp. |
| Owen Mumford Ltd. |
| BD |
| ARKRAY, Inc. |
| Others |
Supply & Pricing Matrix
Surgical-grade stainless steel price volatility propagates through commodity lancet manufacturing into three-tier pricing stratification across premium safety-engineered, standard thin-wall, and economy fixed-depth configurations. Gamma sterilization capacity scarcity in contract facilities concentrates pricing power among manufacturers with captive irradiation infrastructure, widening margin spreads between integrated and non-integrated producers.
Pricing Analysis
Outcome-based pricing anchored to needlestick injury reduction metrics commands premium positioning for safety pen needles in OSHA-regulated United States acute care facilities. Pricing stratifies across premium, standard, and economy tiers driven by gauge thickness engineering and EU MDR certification burden, with 32G siliconized configurations extracting brand loyalty premiums in German and Japanese homecare markets. Cost compression in commodity disposable lancets intensifies because raw material swings erode producer margins lacking backward integration into metal sourcing. Diagnostic laboratories exhibit highest price sensitivity through high-volume screening contracts, while endocrinology clinics in Osaka and Munich demonstrate lowest sensitivity for pain-minimization specifications.
Supply Chain Analysis
Single-source vulnerability sits with gamma sterilization contract facilities concentrated in Germany, China, and the United States, where batch release bottlenecks delay market entry for mid-tier manufacturers. Stainless steel feedstock draws from specialized metallurgical suppliers in Japan and Germany, while precision grinding equipment sources from Swiss and Italian machine tool builders. Tariff exposure on Chinese-manufactured needle shields threatens cost structures for producers lacking alternative sterile barrier suppliers. Distribution runs through hospital group purchasing organizations and retail pharmacy chains, with direct-to-patient subscription models emerging as channel-bypass alternatives in United States and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lancet and Pen Needles Market sits in a technology-transition phase where continuous glucose monitoring substitution is displacing fingerstick-dependent lancet volume in diagnostic settings. Thin-wall 32G cannula engineering is overtaking legacy 29G hospital contracts as the dominant performance standard.
For Market Incumbents: Extend backward integration into surgical-grade stainless steel sourcing to defend against raw material volatility compressing commodity lancet margins. Expand captive gamma sterilization footprint in the Yangtze River Delta and Baden-Württemberg corridors to circumvent contract facility bottlenecks delaying batch release. Lock multi-year sole-source agreements with Banner Health-scale integrated delivery networks before reimbursement compression accelerates procurement consolidation.
For New Entrants and Emerging Players: ANVISA's absence of OECD needlestick prevention standards in Brazil opens a window for safety pen needle first-mover positioning in Latin America's largest diabetes market. Target direct-to-patient subscription channels in German and Japanese homecare settings where reimbursement tiers support premium gauge adoption and brand loyalty formation. Pursue white-label manufacturing partnerships with mid-tier European fabricators lacking EU MDR Article 10 clinical evidence capabilities.
For Investors and Strategic Acquirers: EU MDR Rule 6 reclassification triggering additional clinical evaluation requirements for safety pen needles is the leading indicator that regulatory compliance burden will consolidate mid-tier manufacturers into acquisition targets. Five-to-ten year viability favors automated manufacturing specialists with siliconization technology leadership and sterile barrier innovation capabilities. Monitor gamma sterilization facility construction announcements as the signal for supply chain bottleneck resolution enabling volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Article 10 compliance compresses timelines for safety pen needle market access. |
| Hospital System Partnership | Sole-source agreements with Kaiser Permanente-scale IDNs displace secondary supplier competition. |
| Backward Integration into Metal Sourcing | Captive stainless steel supply hedges against commodity volatility eroding lancet margins. |
| Software Companion Development | Digital adherence platforms for pen needle resupply lock recurring revenue in homecare channels. |
| Reimbursement Strategy Alignment | German statutory health insurance tiers reward 31G and 32G pain-minimization specifications. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings on pricing tier stratification. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and endocrinology clinic administrators combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and ISO 11608 standards publications. Bottom-up demand modeling across gauge size, application, and end-user segments triangulates against top-down market sizing from trade flow analysis.
Rate-of-change decomposition across the analysis window separates volume growth from value migration between commodity and premium tiers. Segmentation dimensions modeled include product architecture, gauge engineering, application workflow, and end-user procurement concentration, with regional regulatory cluster effects incorporated as overlay variables. CAGRs derive from installed base expansion in diabetes populations, substitution rates from continuous glucose monitoring, and safety-engineered mandate adoption curves. Sterilization validation timelines and reimbursement tier adjustments feed as scenario inputs.
The model assumes a particular technology adoption path; alternative pathways for non-invasive glucose monitoring would alter the outlook for lancet volume demand. Forecasts reflect assumptions on EU MDR enforcement stringency, OSHA needlestick prevention standard expansion, and Japanese METI reimbursement tier stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Syringe Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Micro Vials Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Medical Liners Market