
 Drosophila Bottles Market | 2026-2036
Drosophila Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Drosophila Bottles Market Foresight
Polycarbonate is recalibrating cost-performance trade-offs across the Drosophila bottles landscape as laboratories seek autoclavable clarity at lower weight than glass. Thermo Fisher Scientific leverages its global distribution network to sustain institutional purchasing contracts across North American research universities. Genesee Scientific anchors West Coast supply through specialized Drosophila husbandry catalogs with same-day fulfillment capabilities. Avantor Science competes on cGMP-aligned documentation packages that streamline pharmaceutical client qualification audits.
Drosophila bottles are purpose-built cylindrical vessels, typically 6-8 ounces in nominal capacity, designed for rearing Drosophila melanogaster under controlled temperature and humidity conditions with specialized venting to prevent media desiccation while excluding contaminating mites. Standard bottles retain dominant unit volume across academic teaching labs where cost minimization overrides specialized features, while vented bottles capture expanding share among pharmaceutical firms running multi-generational toxicity assays requiring precise gas exchange. Polypropylene commands the material tier for high-temperature sterilization cycles, whereas polycarbonate differentiates in optical clarity applications demanding continuous behavioral observation without transfer.
The U.S. FDA and EPA jointly shape demand through Good Laboratory Practice enforcement and chemical toxicity testing mandates that elevate documentation and traceability requirements for consumables in regulatory-submission studies. REACH compliance in Europe restricts certain plasticizers and additives, pushing manufacturers toward certified polypropylene grades with full material safety data lineage. ISO 10993 biocompatibility standards increasingly penetrate procurement specifications as pharmaceutical firms integrate Drosophila models earlier in preclinical pipelines. Stakeholders must monitor how tightening chemical disclosure rules across multiple jurisdictions reshape raw material qualification timelines and supplier switching costs.
Market Dynamics
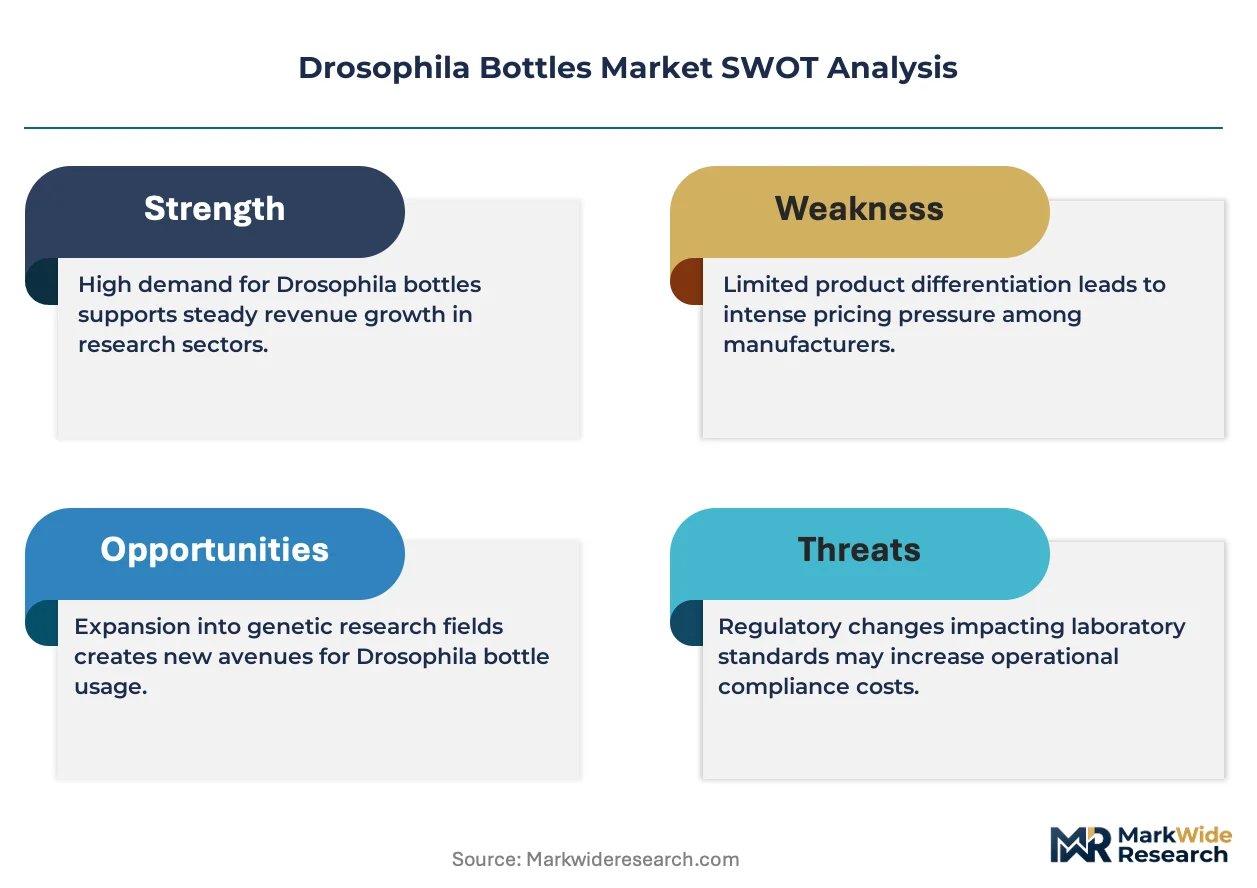
Pharmaceutical firms are compressing preclinical timelines by integrating Drosophila models earlier in toxicity screening pipelines, forcing consumables suppliers to align documentation and sterility protocols with FDA Good Laboratory Practice standards. This regulatory pull is restructuring procurement relationships and elevating cGMP-aligned product tiers above standard academic-grade formats.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA restrictions on plasticizers and additives are accelerating demand for certified polypropylene grades with full material safety data lineage, benefiting suppliers with pre-qualified raw material streams.
- High-throughput screening infrastructure:Pharmaceutical firms running multi-generational toxicity assays are expanding vented bottle adoption to maintain precise gas exchange across automated handling systems.
- Max Planck Institute research clusters:Germany's centralized biotechnology procurement systems sustain above-average per-laboratory consumption, creating concentrated demand pockets for specialized husbandry formats.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polycarbonate resin prices fluctuate with crude oil benchmarks, compressing margin stability for manufacturers without long-term supply contracts.
- Autoclave capacity constraints:Glass-to-plastic conversion is limited by institutional sterilization infrastructure that cannot reliably process polycarbonate above 121°C without warping.
- Single-use plastic directives:EU packaging waste regulations are creating compliance friction for disposable bottle formats in publicly funded research institutions.
Strategic Opportunities
- ISO 10993 biocompatibility certification:Early-stage pharmaceutical pipelines are adopting Drosophila for human-relevant pathway modeling, creating demand for consumables meeting medical-device material standards.
- Behavioral neuroscience applications:Continuous optical observation protocols in sleep and circadian rhythm studies are opening premium tiers for polycarbonate clarity without transfer interruption.
- Same-day fulfillment channels:Regional distribution hubs with specialized Drosophila husbandry catalogs can capture emergency replenishment cycles that centralized procurement systems cannot address.
Industry Challenges
- Multi-jurisdiction material qualification:Suppliers must maintain parallel documentation streams for FDA, EMA, and emerging Asian pharmaceutical regulators, extending product launch timelines.
- Legacy venting standard fragmentation:Incompatible closure systems across bottle manufacturers force laboratories to maintain redundant inventory, complicating automated handling integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drosophila Bottles Market |
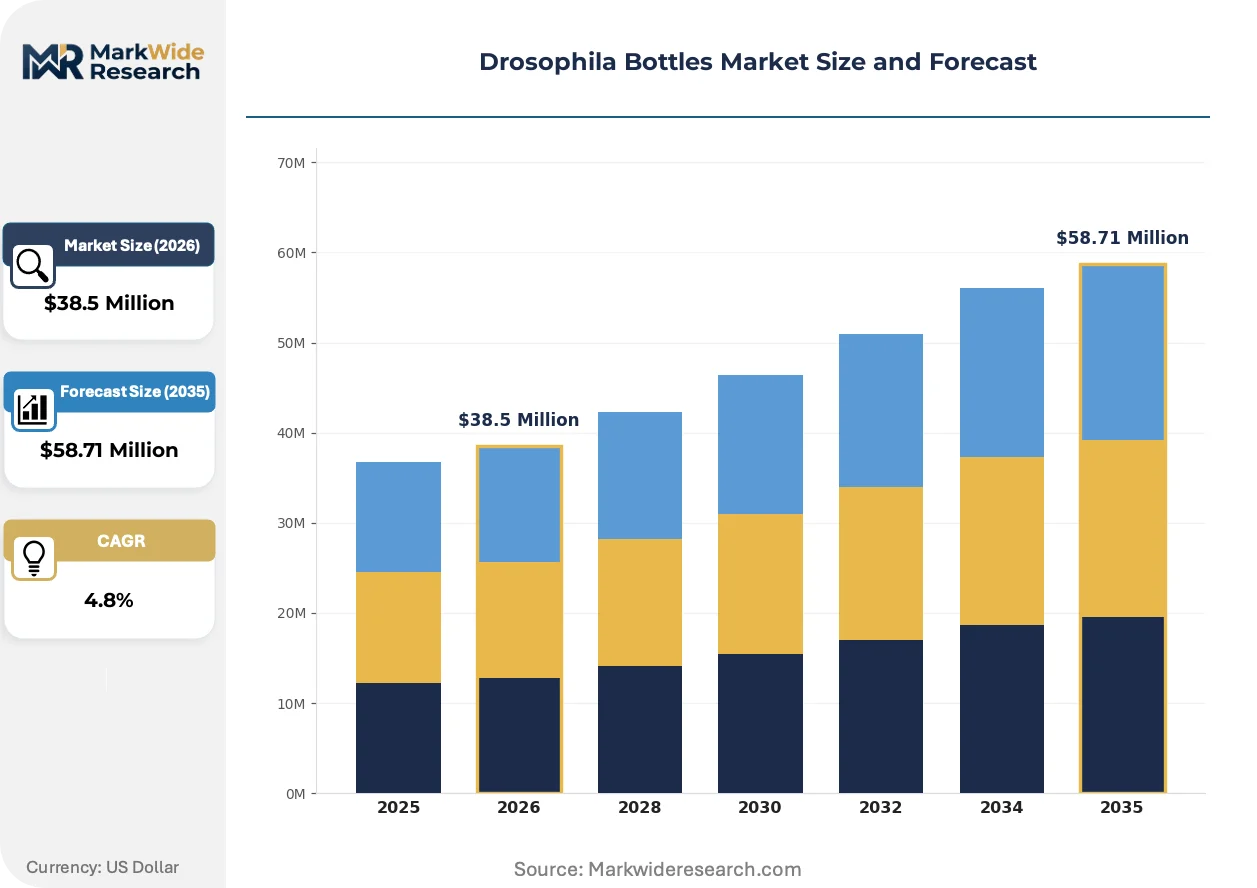
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $58.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bottles, Vented Bottles, Disposable Bottles, Reusable Bottles Material: Plastic, Glass, Polypropylene, Polycarbonate Closure Type: Screw Caps, Plug Caps, Snap Caps, Corks End User: Research Laboratories, Educational Institutions, Biotechnology Companies, Pharmaceutical Firms |
| Companies Covered | Thermo Fisher Scientific, Avantor Science, Genesee Scientific, Tritech Research, Biologix, Andaaf Scientific, Azer Scientific, Parter Medical Products, ELSE-nnovation Life Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drosophila Bottles Market Shifts & Advancements
Automation-compatible bottle formats are displacing legacy designs as pharmaceutical screening density increases, while regulatory documentation requirements are hardening material traceability standards. These shifts are compressing the supplier base toward entities with integrated quality management systems.
Polycarbonate is consolidating position in optical clarity applications where continuous behavioral observation without transfer is mandatory. Neuroscience laboratories studying sleep architecture and social aggregation patterns are adopting these formats at accelerating rates. The material's autoclavable durability is compressing total cost of ownership calculations against glass alternatives despite higher unit pricing.
REACH compliance in Europe is restricting certain plasticizers and additives, pushing manufacturers toward certified polypropylene grades with full material safety data lineage. ECHA enforcement is elevating raw material qualification timelines and supplier switching costs. Pharmaceutical firms with regulatory-submission studies are responding by consolidating vendor relationships with entities holding pre-validated documentation packages.
Buying patterns among research institutions are fragmenting between centralized procurement systems and emergency direct-channel replenishment. Germany's Max Planck-affiliated clusters exemplify the former, while West Coast biotechnology startups favor same-day fulfillment from specialized catalogs. Academic teaching labs remain most visible in the United States, where cost minimization overrides specialized features and sustains standard bottle dominance.
Drosophila Bottles Market Segmentation
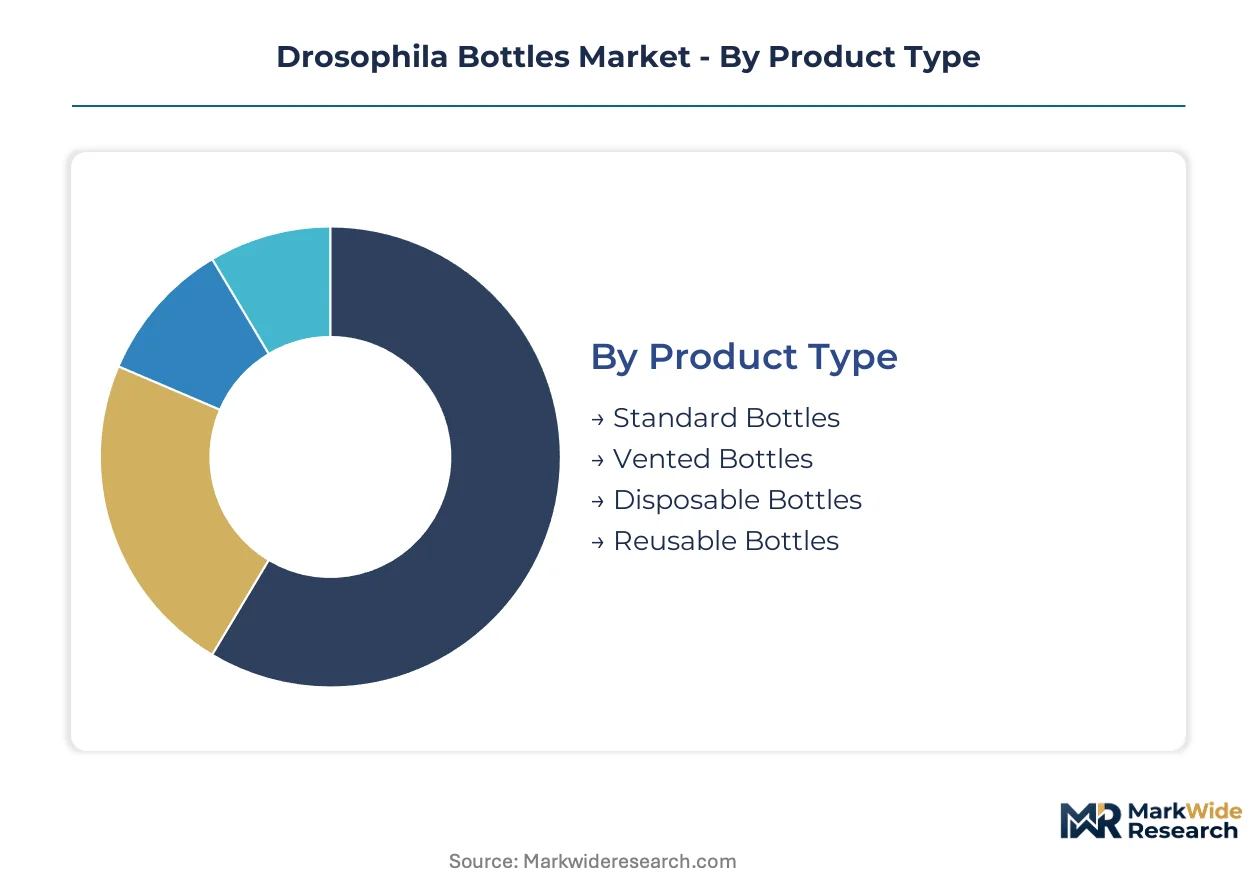
Drosophila bottle procurement fragments across four distinct axes: functional design, material composition, closure mechanics, and end-user sophistication. Each dimension carries divergent technical requirements and regulatory burdens that reshape supplier positioning.
Product Type:
Customization intensity varies sharply across this category, from commodity standard formats to engineered venting systems for automated pharmaceutical workflows.
- Standard Bottles:Basic cylindrical vessels with fixed ventilation apertures dominate academic teaching environments where unit cost minimization overrides specialized features. Procurement concentrates in United States public university systems running high-enrollment genetics courses, constrained by shrinking equipment budgets.
- Vented Bottles:Precision-engineered gas exchange membranes maintain media hydration across multi-generational toxicity assays. Pharmaceutical firms in Germany's Max Planck-affiliated clusters are expanding vented format adoption for automated screening infrastructure requiring consistent atmospheric control.
- Disposable Bottles:Single-use polypropylene formats eliminate cross-contamination risk in high-throughput screening pipelines. Demand faces friction from EU packaging waste regulations affecting publicly funded research institutions.
- Reusable Bottles:Autoclavable polycarbonate and glass variants serve behavioral neuroscience protocols requiring continuous observation without transfer interruption. Optical clarity specifications drive premium positioning in sleep and circadian rhythm research.
Leading the category by volume: Standard Bottles. Growing fastest: Vented Bottles.
Material:
Cost-performance trade-offs separate commodity thermoplastics from optical-grade engineered polymers in sterilization-critical applications.
- Plastic:Generic polymer blends serve cost-sensitive teaching laboratories with limited autoclave infrastructure. United States community college systems represent concentrated demand pockets for this tier.
- Glass:Borosilicate formats retain niche positioning where absolute chemical inertness and visual clarity are mandatory. Traditional Drosophila husbandry facilities in Heidelberg and Cambridge maintain glass inventories for legacy protocol compliance.
- Polypropylene:High-temperature sterilization cycles up to 134°C drive pharmaceutical adoption. ECHA REACH restrictions on plasticizers are accelerating demand for certified grades with full material safety data lineage.
- Polycarbonate:Optical clarity combined with autoclavable durability is compressing total cost of ownership against glass in continuous observation protocols. Neuroscience laboratories studying social aggregation patterns are adopting these formats at accelerating rates.
Polypropylene commands the volume lead. Polycarbonate exhibits the steepest expansion trajectory.
Closure Type:
Interchangeability constraints across manufacturer ecosystems create inventory redundancy that complicates automated handling integration.
- Screw Caps:Threaded polypropylene closures with integrated ventilation membranes dominate pharmaceutical cGMP environments. FDA Good Laboratory Practice documentation requirements favor standardized screw-cap formats with validated seal integrity.
- Plug Caps:Tapered friction-fit designs serve rapid-access protocols in behavioral observation studies. Academic laboratories in California's biotechnology corridor favor plug caps for manual handling efficiency.
- Snap Caps:Audible-click retention mechanisms prevent accidental dislodgement during incubator stacking. High-throughput screening facilities in Boston's pharmaceutical cluster specify snap-cap compatibility for robotic handling systems.
- Corks:Natural and synthetic stopper formats persist in legacy European research institutions with established husbandry protocols. Cork demand is contracting as laboratories modernize toward standardized plastic closure systems.
Screw Caps lead by institutional procurement volume. Snap Caps are gaining share fastest in automated environments.
End User:
Regulatory sophistication tiers separate academic cost minimization from pharmaceutical documentation intensity.
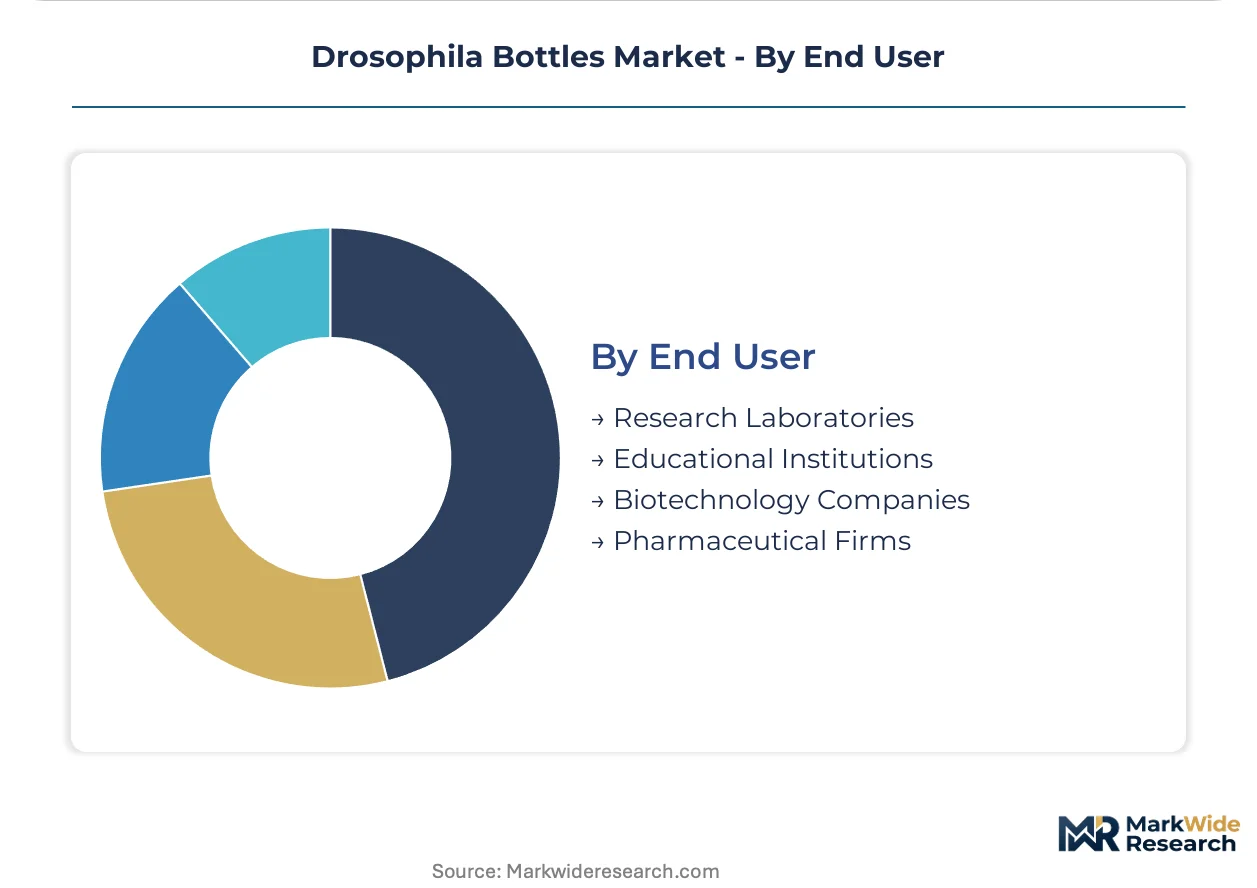
- Research Laboratories:Mixed-purpose facilities running both teaching and investigative protocols require flexible inventory spanning standard and vented formats. Germany's centralized biotechnology procurement systems sustain above-average per-laboratory consumption.
- Educational Institutions:High-volume, low-margin procurement prioritizes standard bottles with minimal specialized features. United States public university systems represent the largest geographic concentration.
- Biotechnology Companies:Venture-funded startups favor same-day fulfillment channels for emergency replenishment cycles. West Coast clusters in San Diego and South San Francisco drive regional distribution hub development.
- Pharmaceutical Firms:Regulatory-submission studies demand cGMP-aligned documentation packages and ISO 10993 biocompatibility certification. These entities are compressing preclinical timelines by integrating Drosophila models earlier in toxicity screening pipelines.
Educational Institutions anchor volume. Pharmaceutical Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's biotechnology special economic zone concentrates pharmaceutical-grade Drosophila bottle demand through Max Planck Institute-affiliated research clusters. Germany's centralized procurement systems sustain above-average per-laboratory consumption. FDA Good Laboratory Practice standards in the United States elevate documentation requirements for consumables in regulatory-submission studies.
United States
Public university systems in California and Massachusetts drive standard bottle volume for high-enrollment genetics courses. FDA refinement of Good Laboratory Practice standards for in vivo alternative models elevates product quality requirements. Greater Boston's pharmaceutical corridor specifies snap-cap compatibility for robotic handling systems in high-throughput screening facilities.
Germany
Max Planck Institute-affiliated research clusters sustain concentrated demand for vented and disposable bottle formats. ECHA REACH restrictions on plasticizers accelerate demand for certified polypropylene grades with full material safety data lineage. Heidelberg maintains glass inventories for legacy protocol compliance in traditional Drosophila husbandry facilities.
United Kingdom
Cambridge research institutions balance behavioral neuroscience protocols requiring continuous observation with teaching laboratory cost constraints. ISO 10993 biocompatibility standards increasingly penetrate procurement specifications as pharmaceutical firms integrate Drosophila models earlier in preclinical pipelines. London's biotechnology procurement systems favor cGMP-aligned documentation packages.
China
Domestic laboratory supply chains expand polycarbonate production for optical clarity applications in sleep and circadian rhythm studies. NMPA alignment with international pharmaceutical standards drives documentation intensity for export-oriented manufacturers. Shanghai's research universities adopt autoclavable formats to reduce glass dependency in high-humidity climates.
Japan
PMDA regulatory harmonization with FDA standards creates demand for traceable consumables in pharmaceutical toxicity screening. METI funding for alternative model validation accelerates vented bottle adoption in automated handling infrastructure. Osaka's life science clusters specify screw-cap formats with validated seal integrity for multi-generational assays.
Drosophila Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement systems favoring established documentation capabilities while emergency replenishment channels reward regional fulfillment speed. The supplier base compresses toward entities with integrated quality management systems as regulatory documentation requirements harden. Three archetypes dominate: diversified life science conglomerates with global distribution networks, regional specialists with same-day fulfillment capabilities, and cGMP-aligned documentation providers serving pharmaceutical audit requirements. Competitive moves concentrate on geographic expansion through specialized distribution hubs and portfolio diversification into automation-compatible formats.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying institutional purchasing contract sustainment across North American research universities. Genesee Scientific represents the regional specialist archetype, anchoring West Coast supply through specialized husbandry catalogs. Avantor Science sits within the cGMP-aligned tier, competing on documentation packages that streamline pharmaceutical client qualification audits.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Avantor Science |
| Genesee Scientific |
| Tritech Research |
| Biologix |
| Andaaf Scientific |
| Azer Scientific |
| Parter Medical Products |
| ELSE-nnovation Life Science |
| Others |
Supply & Pricing Matrix
Polypropylene resin futures volatility cascades through Drosophila bottle manufacturing into tiered pricing structures that separate pharmaceutical-grade documentation packages from academic commodity formats. ECHA REACH compliance costs concentrate in European supply chains, forcing certified material premiums that widen spreads between regulatory-submission and teaching-laboratory tiers.
Pricing Analysis
Expedited fulfillment windows command substantial premiums over standard procurement cycles, with same-day channels extracting margin from West Coast biotechnology clusters facing emergency replenishment pressure. Three-tier pricing structure across premium, standard, and economy levels stratifies by documentation intensity: cGMP-aligned ISO 10993-certified bottles anchor the top tier, vented formats with validated seal integrity occupy the middle, and basic polypropylene teaching-laboratory units dominate volume at compressed margins. Cost compression in commodity grades intensifies as United States public university systems consolidate purchasing through centralized procurement systems. Educational institutions exhibit highest price sensitivity, while pharmaceutical firms running FDA-submission studies absorb premium positioning without volume elasticity.
Supply Chain Analysis
Regional distribution centers in California, Massachusetts, and Bavaria anchor hub-and-spoke fulfillment patterns that position inventory within four-hour ground transit of major research clusters. Manufacturing concentration in China, Germany, and the United States draws from polycarbonate resin feedstocks, polypropylene polymer streams, and precision-molded closure components. Single-source vulnerability in medical-grade polycarbonate supply creates exposure to petrochemical feedstock disruptions. Distribution runs through institutional purchasing contracts for pharmaceutical clients and specialized husbandry catalogs for emergency academic replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Good Laboratory Practice standards erect documentation barriers that entrench pre-qualified suppliers against commodity competition.
For Market Incumbents: Deploy cGMP-aligned certification investment to deepen moats against emerging Asian contract manufacturers. Consolidate vendor relationships with Max Planck Institute-affiliated clusters through pre-validated documentation packages that accelerate pharmaceutical audit cycles. Counter polycarbonate resin volatility through long-term supply contracts with certified polypropylene grades holding full material safety data lineage. For New Entrants and Emerging Players: ECHA REACH restrictions in Europe open a window for certified polypropylene specialists with pre-qualified raw material streams. Target behavioral neuroscience laboratories in Cambridge and Heidelberg requiring continuous optical observation formats as the most penetrable premium segment. Enter through same-day fulfillment partnerships with West Coast biotechnology startups bypassing centralized procurement friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distribution specialists with specialized husbandry catalogs in San Diego and South San Francisco. Long-term viability hinges on regulatory documentation capabilities expanding from FDA toward NMPA and PMDA harmonization. Monitor ISO 10993 biocompatibility penetration into preclinical pharmaceutical pipelines as inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Certification | Pharmaceutical firms integrate Drosophila models earlier, demanding medical-device material standards. |
| Regional Distribution Hub Expansion | Same-day fulfillment capabilities capture emergency replenishment cycles from West Coast biotechnology clusters. |
| REACH-Compliant Material Qualification | Certified polypropylene grades with full safety data lineage secure European pharmaceutical procurement. |
| Automation-Compatible Format Development | Snap-cap and screw-cap standardization enables robotic handling integration in high-throughput screening. |
| Multi-Jurisdiction Documentation Investment | Parallel FDA, EMA, and PMDA qualification streams compress product launch timelines for global clients. |
Research Methodology
Multi-period observation of polycarbonate pricing spreads, autoclave infrastructure deployment, and regulatory submission volumes anchored the trend analysis, supplemented by interviews with laboratory supply procurement managers, pharmaceutical toxicology directors, Drosophila husbandry facility managers, and centralized biotechnology purchasing officers. Secondary validation drew from FDA GLP guidance documents, ECHA REACH restriction updates, ISO 10993 biocompatibility standards, and institutional procurement database extracts. Bottom-up segment sizing triangulated against top-down market reconstruction across material, closure, and end-user dimensions.
Segment-weighting approaches applied differential growth assumptions by product tier: standard bottles tracked academic enrollment and equipment budget trajectories; vented and disposable formats modeled pharmaceutical screening pipeline expansion; polycarbonate clarity segments captured behavioral neuroscience protocol adoption. CAGRs were derived from regression against raw material cost indices, regulatory enforcement intensity metrics, and research funding disbursement patterns. Forecast inputs incorporated Max Planck Institute cluster procurement velocity and West Coast biotechnology startup formation rates.
Caveats apply where petrochemical feedstock disruptions, autoclave infrastructure conversion delays, or single-use plastic directive enforcement could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Swab Cups Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Medical Instruments Disinfection Market