
 Anti Venom Market | 2026-2036
Anti Venom Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Venom Market Intelligence
Demand from government-led public health stockpiling programs is collapsing the traditional distinction between private hospital purchasing and direct-to-clinic distribution models. CSL Limited leverages its extensive portfolio of snake and spider antivenoms for developed markets like Australia. Bharat Serums and Vaccines Limited anchors its position through large-scale production for the Indian subcontinent. Instituto Bioclon S.A. de C.V. specializes in antivenoms for species native to the Americas.
Anti-venom consists of purified immunoglobulins derived from animal plasma hyperimmunized with specific snake, spider, or scorpion venoms. These antibodies function to neutralize the enzymatic and toxic components of venom following a bite or sting, preventing systemic damage and death. Polyvalent antivenoms, effective against multiple venom types, dominate sales due to their utility in emergency situations where the snake species is unknown. Hospitals remain the primary end-user channel, accounting for the majority of procurement and administration.
Product approval and quality are governed by national authorities like the US FDA and India's CDSCO, often guided by WHO prequalification standards. These regulations ensure the safety, potency, and efficacy of antivenoms, which are critical for market access. The key decision for manufacturers revolves around investing in next-generation recombinant antivenoms versus optimizing existing plasma-derived production methods to meet acute supply shortages.
Market Dynamics
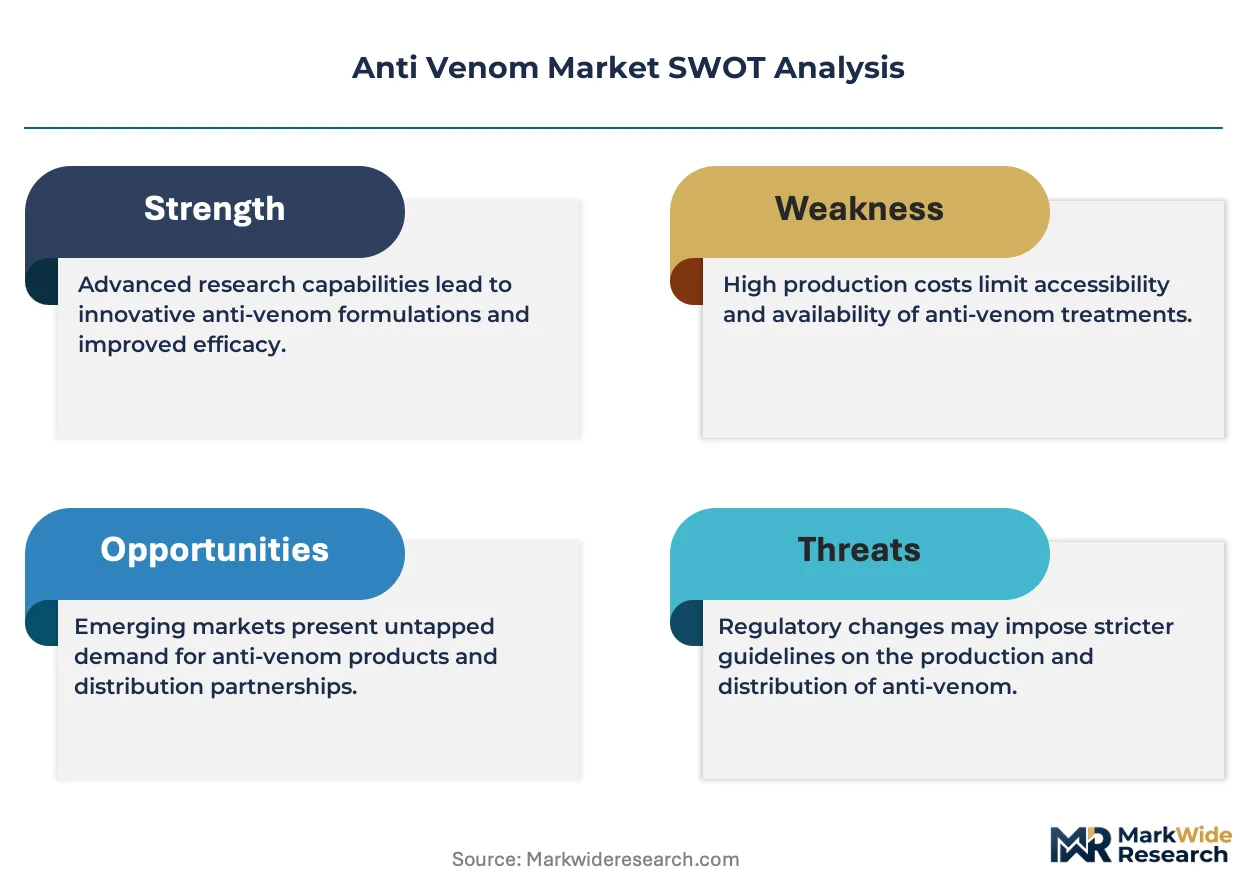
The central dynamic shaping the anti-venom market is the structural imbalance between unpredictable, acute demand concentrated in low-income tropical countries and the complex, capital-intensive biological manufacturing process required for production, a gap the WHO's global strategy aims to close.
Growth Catalysts
- WHO Strategic Roadmap:The World Health Organization's initiative to halve snakebite envenoming deaths and disabilities provides a coordinated global framework, stimulating government investment in public health programs and stockpiling efforts across affected nations.
- High-Burden Geographies:Persistent high incidence of snakebites in agricultural and rural populations across India, Nigeria, and Brazil creates a constant, non-discretionary demand from public and private healthcare systems for effective antivenoms.
- Clinical Utility of Polyvalent Formulations:Emergency care protocols increasingly favor polyvalent antivenoms, which neutralize venom from multiple species, due to the frequent inability to identify the snake, thereby expanding their applicability and market volume.
Market Restraints
- Animal-Based Supply Dependency:The entire production chain depends on hyperimmunized animal plasma, a process with inherent biological variability, ethical considerations, and supply limitations tied to the health and availability of donor animals.
- Cold Chain Distribution Complexity:Maintaining the cold chain for antivenom stability from manufacturing sites to remote, often off-grid clinics in tropical climates presents a significant logistical and cost barrier, limiting last-mile availability.
- Regional Venom Specificity:Antivenoms are highly specific to the venoms of species from a particular geographic region, preventing products developed for Australian snakes, for example, from being effective against African or Asian species and limiting global fungibility.
Strategic Opportunities
- Next-Generation Recombinant Platforms:Investing in the development of recombinant or fully synthetic antivenoms offers a path to bypass animal-derived plasma, enabling more consistent, scalable production and improved product safety profiles.
- Sub-Saharan Africa Market Development:Establishing local or regional manufacturing and distribution hubs in Sub-Saharan Africa can address severe supply gaps, reduce reliance on imports, and create antivenoms tailored to the region's specific snake species.
- Thermostable Formulation Innovation:Developing heat-stable antivenom formulations that do not require a stringent cold chain would revolutionize distribution, enabling effective stockpiling in rural health posts and improving access in resource-limited settings.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of herpetologists for venom collection and technicians skilled in animal immunization and plasma purification protocols creates a significant bottleneck in scaling up raw material production for antivenom manufacturing.
- Fragmented Regulatory Pathways:Manufacturers face long and costly approval timelines navigating disparate regulatory requirements from national bodies like India's CDSCO, Brazil's ANVISA, and the US FDA, which delays product entry into new markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Venom Market |
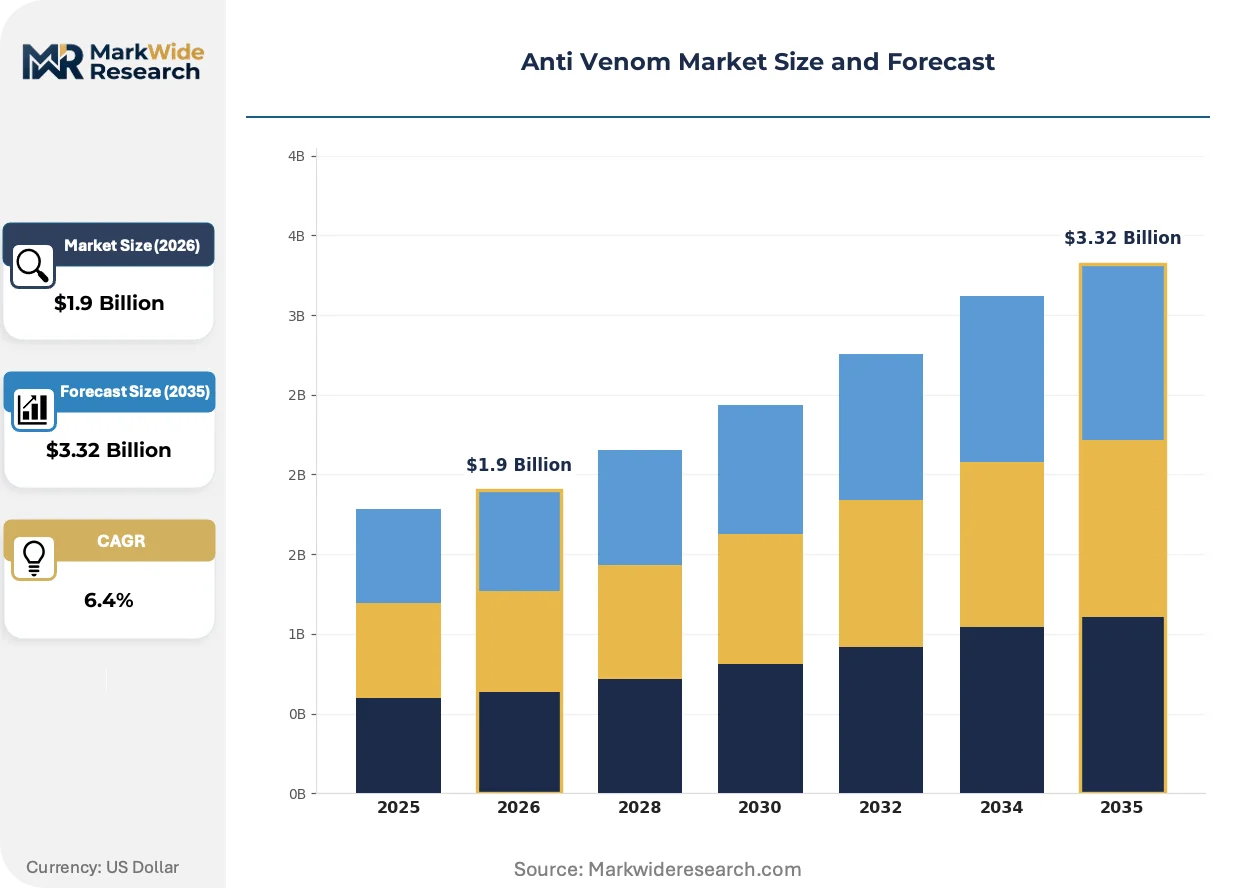
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monovalent Antivenoms, Polyvalent Antivenoms, Nucleotides, Enzymatic Products Application: Emergency Care, Hospital Treatment, Research, Clinical Trials End User: Hospitals, Pharmacies, Research Institutions, Veterinary Clinics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Medical Distributors |
| Companies Covered | Bharat Serums and Vaccines Limited, CSL Limited, Pfizer Inc., Boehringer Ingelheim International GmbH, MicroPharm Limited, Rare Disease Therapeutics Inc., Haffkine Bio-Pharmaceutical Corporation Limited, Incepta Pharmaceuticals Limited, Instituto Bioclon S.A. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Venom Market Strategic Shifts & Innovations
A fundamental transition from traditional serotherapy toward biotechnological solutions is underway, driven by the inherent limitations of animal-derived plasma and new regulatory incentives. This shift promises to improve the safety, scalability, and accessibility of antivenom treatments.
Recombinant antibody fragments are engineered proteins designed to neutralize specific venom toxins without using whole immunoglobulins derived from animal plasma. Research institutions and specialized biotechnology firms are pioneering these platforms, attracting funding from public health bodies. This approach is miniaturizing the active neutralizing component, paving the way for more stable, potent, and precisely targeted therapies that can be more easily produced at scale.
The World Health Organization's Prequalification program for antivenoms establishes a global benchmark for product safety, quality, and efficacy. This initiative provides a transparent pathway for manufacturers to gain approval for large-volume procurement by UN agencies and national health ministries. Producers targeting public tenders in high-burden regions like Southeast Asia and Africa are most affected, aligning their quality management systems and clinical data with WHO standards.
A significant demand-side change involves national health systems moving from fragmented, clinic-level purchasing to consolidated, centralized stockpiling programs. This model consolidates purchasing power within a single government entity, often displacing direct-to-hospital distribution channels in favor of large-scale tenders. This procurement behavior is most pronounced in countries like India and Brazil, where it is used to manage supply security and promote equitable access across regions.
Anti Venom Market Segmentation
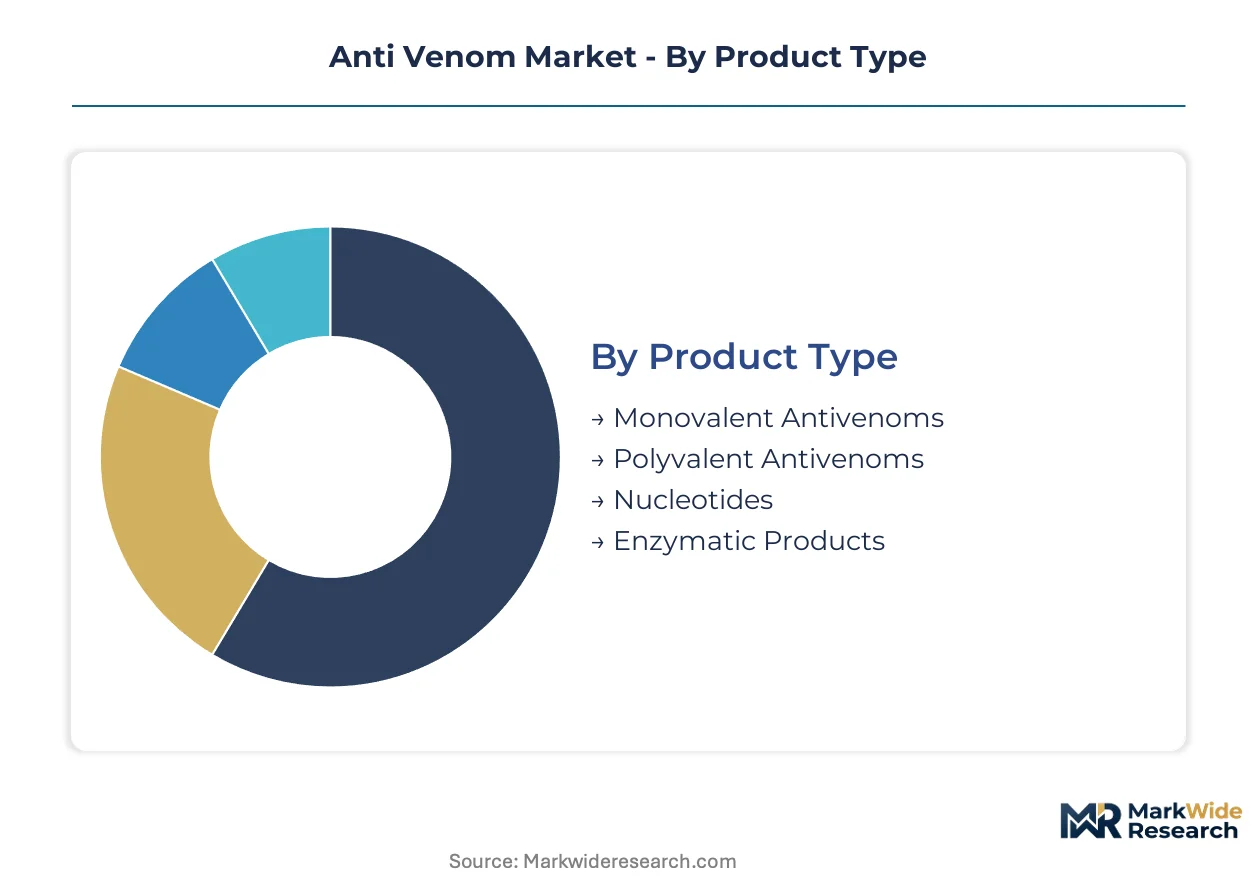
Market segmentation for anti-venom products reflects the diverse biological threats and varied healthcare infrastructures across different regions. Understanding these segments is critical for manufacturers to tailor product development, optimize distribution networks, and align with public health priorities.
Product Type:
Product categorization often reflects the geographic spread of venomous species, dictating whether a product serves a localized population or a broader international emergency response.
- Polyvalent Antivenoms:These formulations contain antibodies effective against venoms from multiple snake species, making them essential for emergency situations where the biting species is unknown. Demand concentrates heavily in high-burden countries like India and Brazil due to the wide variety of venomous snakes encountered.
- Monovalent Antivenoms:Designed to neutralize the venom of a single specific species, these antivenoms are used when the identity of the biting snake is confirmed. Australia relies on monovalent products tailored to its unique snake populations.
- Nucleotides:This advanced product class represents next-generation therapies, exploring synthetic alternatives to traditional animal-derived immunoglobulins.
- Enzymatic Products:These products target specific venom components, offering potential for adjunctive therapy or novel antivenom development.
Polyvalent Antivenoms holds the largest share; momentum sits with Nucleotides.
Application:
Application segments are differentiated by the investment required for their implementation, ranging from immediate life-saving interventions to long-term research endeavors.
- Emergency Care:This segment encompasses the immediate administration of antivenom following a snakebite or envenoming incident, often in pre-hospital or remote clinic settings. High incidence rates in regions like Sub-Saharan Africa drive consistent demand for rapid-response solutions.
- Hospital Treatment:This application involves the comprehensive management of envenoming cases within a hospital environment, including antivenom administration, supportive care, and monitoring. Hospitals remain the primary point of care for severe envenoming cases globally.
- Research:This segment involves the study of venoms, antivenoms, and envenoming mechanisms, driving innovation in product development.
- Clinical Trials:This application focuses on testing new antivenom formulations or treatment protocols in human subjects to establish safety and efficacy.
Emergency Care applications maintain the largest market volume; Clinical Trials are expanding most quickly.
End User:
End-user segments drive distinct procurement volumes, influencing the scale and frequency of antivenom orders from manufacturers.
- Hospitals:These institutions serve as the primary point of administration for antivenoms, requiring consistent supply for emergency and routine treatment of envenoming. Public hospitals in countries like Nigeria are major purchasers due to the high patient load.
- Research Institutions:Academic and private research bodies utilize antivenoms and venom components for scientific study, contributing to future therapeutic advancements. Institutes like those supported by the WHO's strategy are key users.
- Pharmacies:Retail and hospital pharmacies distribute antivenoms, particularly in regions with established healthcare infrastructure.
- Veterinary Clinics:These facilities use antivenoms to treat envenoming in animals, especially in rural or agricultural areas.
Hospitals constitute the primary end-user base; Research Institutions are gaining share fastest as innovation accelerates.
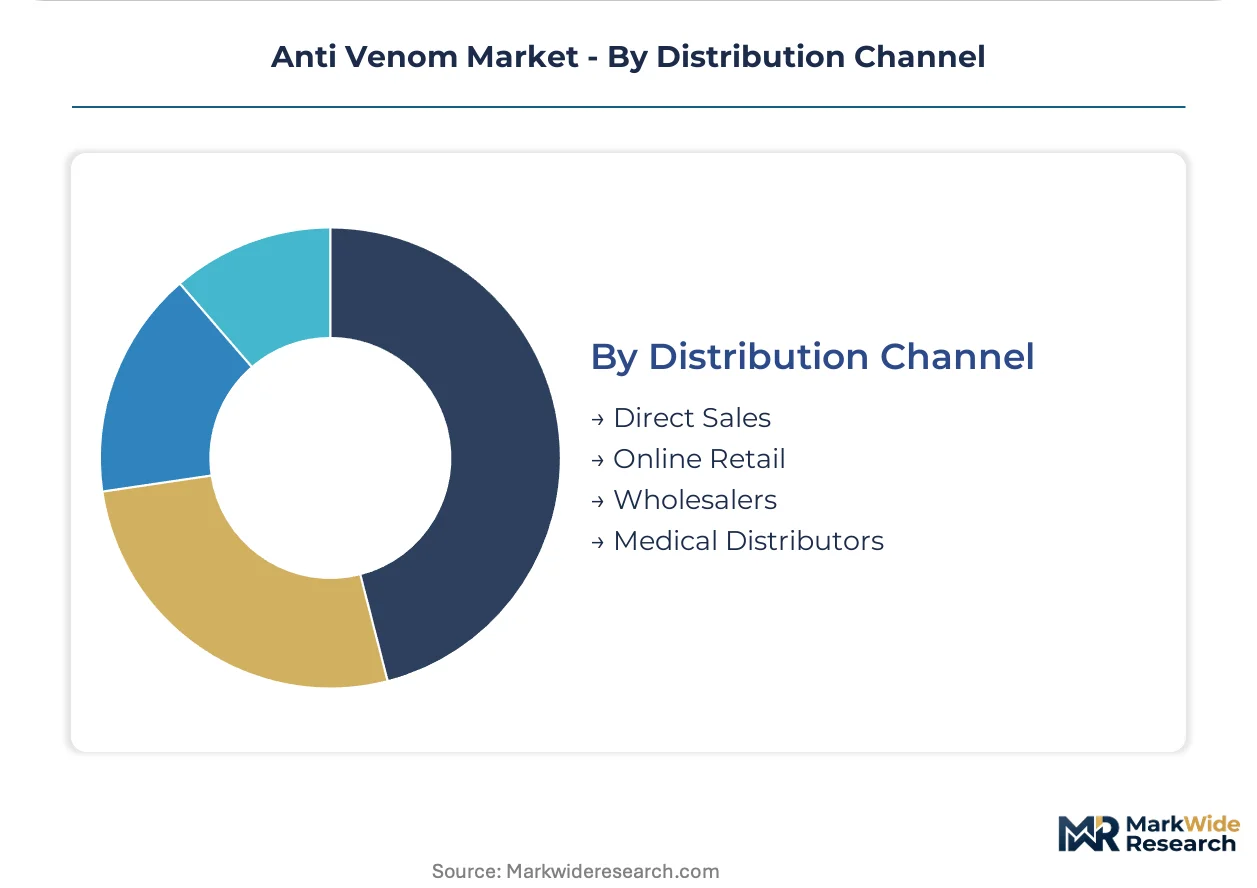
Distribution Channel:
Distribution channels are largely shaped by the concentration of antivenom supply, influencing how products reach diverse end-users.
- Medical Distributors:These entities manage the logistics and supply chain for antivenoms, ensuring products reach hospitals and clinics across broad geographic areas. They are crucial for maintaining cold chain integrity in tropical climates.
- Direct Sales:Manufacturers engage in direct sales, particularly to government agencies for national stockpiling programs or to large hospital networks. This model is seen in countries like Brazil for centralized procurement.
- Wholesalers:These intermediaries purchase antivenoms in bulk from manufacturers and supply them to smaller distributors or pharmacies.
- Online Retail:This channel facilitates procurement for specialized clinics or individual medical practitioners, offering convenience for smaller orders.
Medical Distributors facilitate the bulk of antivenom delivery; Direct Sales channels are seeing the steepest expansion trajectory due to government initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences the anti-venom market's regional dynamics. Government-led public health stockpiling programs in high-burden nations are transforming procurement patterns. This shift prioritizes large-scale tenders over fragmented clinic-level purchasing across several key geographies.
India
India's market demand stems from persistent high incidence of snakebites in agricultural populations. The country's Central Drugs Standard Control Organization (CDSCO) regulates antivenom quality and market access. Mumbai and Pune serve as significant pharmaceutical manufacturing and R&D hubs for antivenom production.
Nigeria
Nigeria experiences consistent demand due to frequent snakebite envenoming in rural areas. The National Agency for Food and Drug Administration and Control (NAFDAC) oversees product approval. Lagos acts as a critical distribution and logistics hub for antivenom supply across West Africa.
Brazil
Brazil's antivenom demand is driven by a high incidence of snakebites and government-led centralized procurement. ANVISA, the national health surveillance agency, sets product standards. São Paulo is a key center for biopharmaceutical research and production, including antivenoms.
Australia
Australia's demand is for monovalent products tailored to its unique snake populations and developed market needs. The Therapeutic Goods Administration (TGA) ensures product safety and efficacy. Melbourne hosts significant research and manufacturing capabilities, notably for CSL Limited.
United States
The United States market focuses on advanced emergency care and research into next-generation treatments. The US FDA regulates all antivenom products for safety and effectiveness. Biotech clusters in Boston and the San Francisco Bay Area drive innovation in recombinant antivenoms.
Anti Venom Market Key Industry Players
Player mix skews toward specialized biopharmaceutical companies with distinct regional or product focuses. The market exhibits a tiered structure, with established players alongside emerging innovators and research-driven entities. Strategic archetypes include large-scale regional volume producers, global portfolio holders with diverse offerings, and specialized biotech firms pioneering advanced solutions. Companies frequently engage in portfolio diversification, investment in next-generation recombinant platforms, and strategic partnerships to address supply chain complexities.
Within the global specialist tier, CSL Limited exemplifies a company with an extensive antivenom portfolio, particularly for developed markets like Australia. This Australia-based entity maintains a broad product range for various envenoming incidents. Bharat Serums and Vaccines Limited, an India-based firm, anchors its position through large-scale production tailored for the Indian subcontinent, addressing significant public health needs with high-volume output. Instituto Bioclon S.A. de C.V., a Mexico-based company, occupies a specialized position in developing antivenoms for species native to the Americas, demonstrating a focused regional expertise and production capability. These companies collectively represent the varied strategic approaches in antivenom manufacturing and distribution.
| Leading Market Players |
|---|
| Bharat Serums and Vaccines Limited |
| CSL Limited |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| MicroPharm Limited |
| Rare Disease Therapeutics Inc. |
| Haffkine Bio-Pharmaceutical Corporation Limited |
| Incepta Pharmaceuticals Limited |
| Instituto Bioclon S.A. de C.V. |
| Others |
Cost & Logistics Intelligence
Six-month production lead times for plasma-derived antivenoms directly influence market pricing, especially for polyvalent formulations. This extended manufacturing cycle creates pricing power for established producers and shapes procurement strategies in high-incidence regions.
Pricing Analysis
The pricing gap between existing plasma-derived antivenoms and next-generation recombinant therapies is significant. The market primarily uses a contract-based long-term offtake model for government procurement, alongside per-unit transactional sales for private hospitals. Price differentiation stems from WHO prequalification status, cold chain delivery costs, and volume scale for national stockpiling. Pricing pressure intensifies from public health programs demanding affordability, making government entities the most price-sensitive buyers compared to private hospital systems.
Supply Chain Analysis
Strategic stockpiling preferences dominate the anti-venom market, driven by unpredictable demand and long production cycles, rather than just-in-time inventory. Supply concentrates in India, Australia, and Mexico due to established manufacturing capabilities. The chain relies on hyperimmunized animal plasma and specific venoms for raw material, and cold chain complexity presents a significant structural risk. Distribution runs through medical distributors, with direct sales increasingly common for national government initiatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-venom market is in an early-cycle expansion phase, driven by the World Health Organization's strategic roadmap to reduce snakebite envenoming. This global initiative stimulates government investment and broadens market penetration in high-burden regions.
For Market Incumbents: Consolidate existing plasma-derived production methods to enhance efficiency and meet current demand spikes. Incumbents should also invest in next-generation recombinant antivenom R&D to counter the long-term threat from biotechnological solutions. Prioritize WHO prequalification and consider capacity additions in Sub-Saharan Africa to secure market share against emerging innovators.
For New Entrants and Emerging Players: Anchor in next-generation recombinant platforms to bypass the limitations of animal-based production. Target the severe supply gaps in Sub-Saharan Africa, which represents the most penetrable geography for innovative solutions. Pursue partnerships with national health ministries for public health stockpiling programs, focusing on thermostable formulations to improve last-mile availability.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger pharmaceutical conglomerates seeking to divest non-core biological assets. Long-term viability is strong due to the critical public health need and the WHO's sustained global strategy. Identify specialized biotech firms pioneering recombinant antivenoms or regional manufacturers with tailored product portfolios as prime acquisition candidates. The signal to watch is successful Phase 2 or 3 clinical trial data for novel antivenom formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the market entry of safer, more effective next-generation recombinant antivenoms. |
| Manufacturing Scale-Up | Addresses acute supply shortages in high-burden regions through increased production capacity. |
| Regulatory Approval Pathway | Secures market access by aligning product quality and efficacy with national and WHO standards. |
| Distribution Channel Expansion | Improves last-mile availability of antivenoms, especially in remote, resource-limited settings. |
| Strategic Partnerships | Leverages specialized expertise for venom collection or regional distribution networks. |
Research Approach
Desk research of WHO reports, national health ministry publications, and CDSCO filings preceded structured interviews with antivenom manufacturers, public health officials, hospital procurement leads, and herpetologists. This approach combined primary insights with secondary validation, employing both bottom-up and top-down triangulation. This ensured a comprehensive understanding of market dynamics and stakeholder perspectives across the value chain.
Variance decomposition analysis underpins the market forecast, disaggregating growth drivers across the analysis window. Segmentation dimensions modeled include product type, application, end user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected demand, and the impact of public health policies. Key forecast inputs include snakebite incidence rates and government stockpiling budgets across high-burden nations.
Decision-makers should treat outputs as directional under current regulatory landscape and WHO strategy assumptions; material deviation would warrant model refresh. Forecasts acknowledge potential impacts from the emergence of novel antivenom technologies or significant shifts in public health funding. Revision becomes warranted when these conditions cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Europe Medical Clothing Market